
 Global Anti-Snoring Devices and Snoring Surgery Market | 2026-2036
Global Anti-Snoring Devices and Snoring Surgery Market Size, Share, and Industry Trends Forecast 2026-2036
Global Anti-Snoring Devices and Snoring Surgery Market Foresight
ISO 13485 certification cycles are reorganizing competitive entry in the anti-snoring device sector, forcing smaller manufacturers to invest in quality management infrastructure before commercialization. ResMed leverages its respiratory technology platform to dominate continuous positive airway pressure segments across multiple continents. SomnoMed anchors its position through specialized mandibular advancement expertise and direct dental channel relationships. Fisher & Paykel Healthcare competes on humidification-integrated systems that extend patient therapy adherence.
Anti-snoring devices and snoring surgery encompass mechanical, electromechanical, and thermal interventions designed to maintain upper airway patency during sleep, with mandibular advancement devices typically fabricated from biocompatible acrylic resins requiring precise dental impressions and adjustable protrusion mechanisms. The primary commercial purpose centers on reducing pharyngeal airway collapse to improve sleep architecture and reduce cardiovascular comorbidity risk. Mandibular advancement devices occupy the largest revenue pool due to dental office dispensing economics and patient preference for non-surgical alternatives. Radiofrequency and laser technologies within surgical interventions represent faster-growing margin segments as outpatient ENT procedures expand. CPAP machines retain structural importance in obstructive sleep apnea despite compliance challenges that drive complementary oral appliance demand.
FDA 510(k) premarket notification requirements and EU MDR technical documentation standards are elevating clinical evidence thresholds for novel anti-snoring devices, directly shaping R&D investment priorities and market access timelines. The country's national pharmaceutical regulator in Japan and Health Canada impose additional sleep therapy device classifications that fragment global registration strategies. Stakeholders must monitor evolving reimbursement parity between dental-administered oral appliances and physician-prescribed CPAP systems across national health technology assessment frameworks.
Market Dynamics
ISO 13485 certification cycles are compressing competitive entry timelines, forcing mandibular advancement device manufacturers to front-load quality management investments before securing FDA 510(k) clearance or CE marking under EU MDR.
Growth Catalysts
- EU MDR Technical Documentation:Harmonized clinical evidence standards across European member states are streamlining cross-border dental appliance distribution for compliant manufacturers.
- Japan's Sleep Clinic Expansion:Metropolitan sleep centers in Tokyo and Osaka are scaling procurement of oral appliance therapies as first-line interventions.
- Biocompatible Acrylic Resins:Advanced dental polymers with adjustable protrusion mechanisms are improving patient tolerance and extending device replacement cycles.
Market Restraints
- CPAP Compliance Challenges:Continuous positive airway pressure systems face patient abandonment rates that limit total addressable market expansion despite clinical efficacy.
- ENT Specialist Concentration:Radiofrequency and laser surgical procedures depend on concentrated outpatient capacity in urban United States and German medical centers.
- Reimbursement Parity Gaps:Dental-administered oral appliances lack standardized physician-prescribed CPAP coding equivalence across national health technology assessment frameworks.
Strategic Opportunities
- India's Underserved Sleep Medicine Infrastructure:Diagnostic penetration in tier-two cities creates whitespace for mandibular advancement device partnerships with local dental chains.
- Humidification-Integrated Systems:Convergence of respiratory humidification with oral appliance platforms addresses adherence failures in dry-climate patient populations.
- Telehealth-Enabled Dental Impressions:Remote intraoral scanning protocols are opening direct-to-patient channels outside traditional dental office dispensing economics.
Industry Challenges
- ISO 13485 Implementation Timelines:Smaller manufacturers face 12-18 month quality management system certification cycles that delay commercialization.
- Dental-Sleep Medicine Integration:Cross-training requirements for dentists in polysomnography interpretation create workforce pipeline constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Anti-Snoring Devices and Snoring Surgery Market |
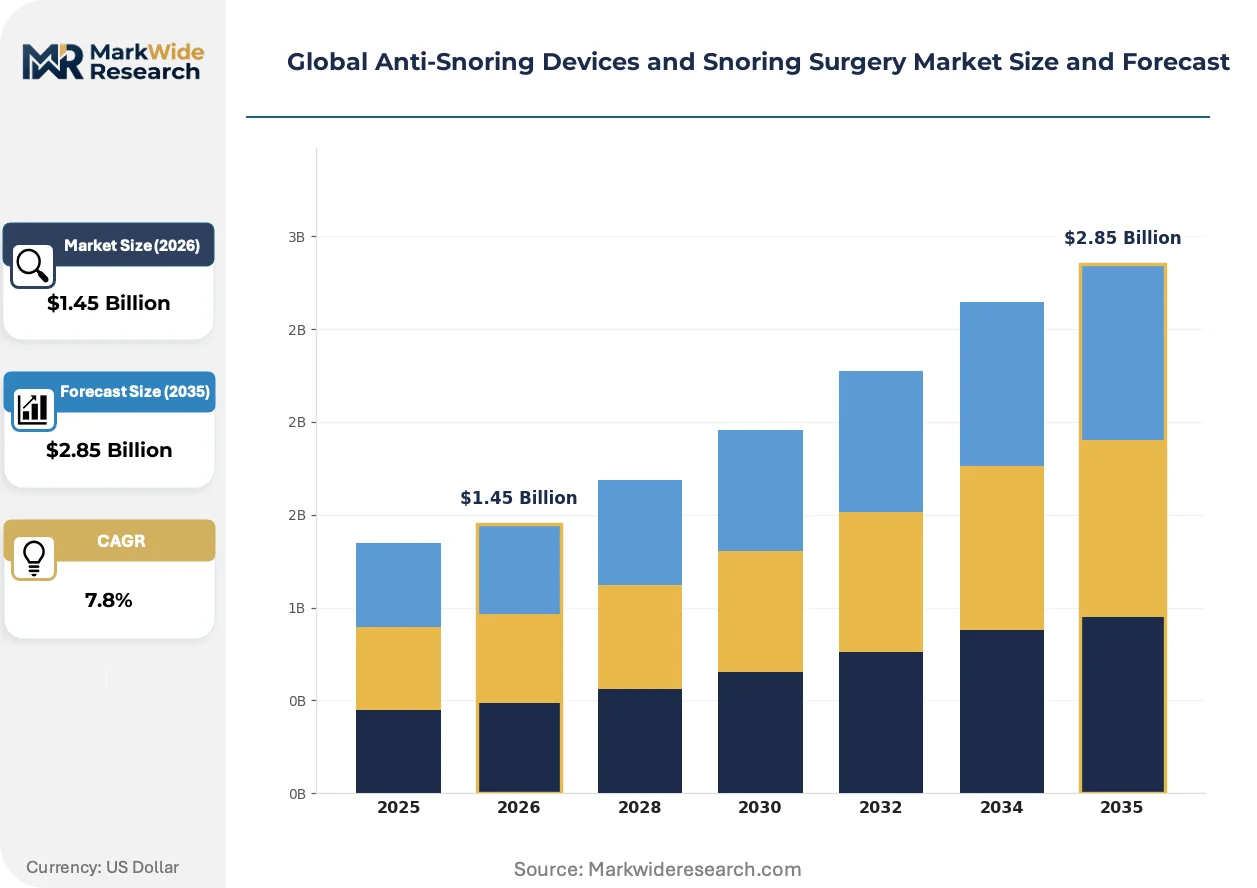
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.85 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mandibular Advancement Devices, Tongue Stabilizing Devices, Nasal Dilators, CPAP Machines, Uvulopalatopharyngoplasty Tools Technology: Electromechanical, Ultrasonic, Laser, Radiofrequency, Acoustic, Thermal Application: Obstructive Sleep Apnea, Primary Snoring, Central Sleep Apnea, Mixed Type Snoring End User: Sleep Clinics, Dental Offices, ENT Specialists, Surgical Centers |
| Companies Covered | Vivos Therapeutics, Koninklijke Philips, ResMed, Airway Management, Apnea Sciences, SomnoMed, Fisher & Paykel Healthcare, Tomed Dr. Toussaint GmbH, ProSomnus Sleep Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Anti-Snoring Devices and Snoring Surgery Market Shifts & Advancements
Digital manufacturing workflows and regulatory data integrity requirements are simultaneously elevating device precision standards and compressing development timelines across oral appliance and surgical intervention categories.
Smart mandibular advancement devices with embedded pressure sensors and Bluetooth connectivity are decomposing the traditional trial-and-error fitting process. Sleep clinics in Germany and the United States are piloting these systems to capture objective adherence metrics. Real-time data transmission is compressing the feedback loop between dental practitioners and sleep physicians, enabling iterative protrusion adjustments without repeat office visits.
EU MDR post-market surveillance requirements are mandating systematic clinical follow-up for mandibular advancement devices previously cleared under less stringent directives. Manufacturers must now maintain periodic safety update reports and vigilance databases. Dental laboratories across France, Italy, and Spain are restructuring quality agreements to accommodate notified body unannounced audits.
Patient acquisition patterns are fragmenting as direct-to-consumer oral appliance brands bypass traditional dental channel intermediaries. Subscription-based replacement programs for thermoplastic devices are displacing one-time acrylic purchases in North American and Australian markets. This channel shift concentrates marketing spend on digital sleep health platforms rather than professional dental society relationships.
Global Anti-Snoring Devices and Snoring Surgery Market Segmentation
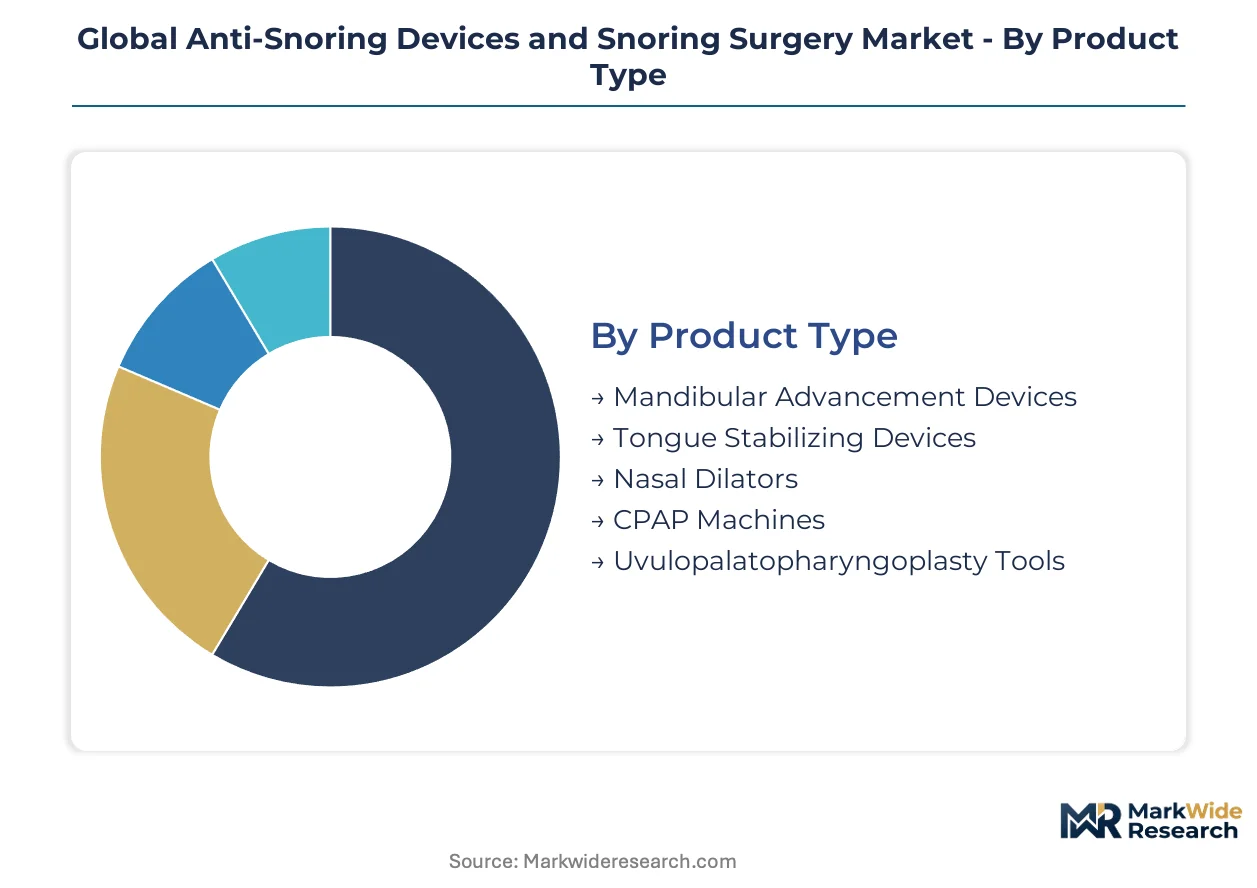
Anti-snoring interventions fragment across mechanical, thermal, and electromechanical modalities, each carrying distinct regulatory pathways and reimbursement profiles. Segmentation clarity enables stakeholders to align R&D investment with specific clinical evidence requirements and channel economics.
Product Type:
Mandibular advancement devices face intensifying substitution pressure from direct-to-consumer thermoplastic alternatives that bypass dental impression workflows.
- Mandibular Advancement Devices:Biocompatible acrylic resin constructions with adjustable protrusion mechanisms dominate dental office dispensing. Sleep clinics in the United States and Germany prioritize these devices for mild-to-moderate obstructive sleep apnea cases where CPAP intolerance prevails.
- CPAP Machines:Continuous positive airway pressure systems integrate respiratory humidification and pressure sensing for severe apnea management. Japan's metropolitan sleep centers maintain procurement concentration despite documented patient adherence challenges that drive complementary oral appliance demand.
- Tongue Stabilizing Devices:Suction-based thermoplastic retainers target edentulous patients excluded from mandibular advancement therapy.
- Nasal Dilators:External adhesive strips and internal nasal valves address nasal airway obstruction as standalone or adjunctive therapy.
- Uvulopalatopharyngoplasty Tools:Surgical instrument sets for palatal tissue resection and uvular remodeling support ENT specialist outpatient procedures.
Mandibular advancement devices retain volume leadership; CPAP machines hold the steepest expansion curve in severe apnea segments.
Technology:
Cost tier stratification separates capital-intensive surgical platforms from disposable oral appliance manufacturing, with reimbursement parity driving technology selection.
- Radiofrequency:Controlled thermal energy delivery to palatal and lingual tissues enables outpatient ENT procedures with reduced recovery timelines. German and United States surgical centers concentrate adoption where laser infrastructure remains capital-constrained.
- Electromechanical:Motorized mandibular positioning systems with embedded sensors capture objective adherence metrics. Bluetooth-enabled devices are gaining share fastest among dental practices pursuing remote patient monitoring capabilities.
- Laser:CO2 and diode laser platforms for palatal stiffening and uvulectomy require specialized operator certification.
- Ultrasonic:High-frequency tissue ablation technologies reduce thermal collateral damage in delicate pharyngeal interventions.
- Acoustic:Sound-based stimulation therapies for positional sleep apnea remain investigational across most regulatory jurisdictions.
- Thermal:Controlled radiofrequency and laser-derived heat applications dominate soft palate remodeling protocols.
Electromechanical platforms command premium positioning; radiofrequency applications are climbing the fastest in outpatient surgical volume.
Application:
Diagnostic coding specificity determines reimbursement eligibility, with polysomnography-confirmed obstructive sleep apnea commanding distinct payment schedules from primary snoring interventions.
- Obstructive Sleep Apnea:Complete or partial upper airway collapse during sleep drives the largest addressable patient population. United States dental offices with sleep medicine cross-training capture expanding reimbursement for oral appliance therapy as first-line intervention.
- Primary Snoring:Simple snoring without apnea events targets direct-to-consumer channels and cosmetic procedure markets. Australian and North American subscription-based device programs concentrate marketing spend on this segment.
- Central Sleep Apnea:Neurological origin requiring adaptive servo-ventilation rather than mechanical airway intervention limits oral appliance applicability.
- Mixed Type Snoring:Combined obstructive and central etiologies necessitate hybrid therapeutic approaches with complex reimbursement navigation.
Obstructive sleep apnea retains volume leadership; primary snoring holds the steepest expansion curve in direct-to-consumer channels.
End User:
Channel concentration varies by geography, with dental-sleep medicine integration most advanced in North American and German reimbursement frameworks.
- Dental Offices:General and sleep-focused dental practitioners dispense mandibular advancement devices with growing polysomnography interpretation capabilities. FDA 510(k) clearance pathways and stabilized reimbursement codes in the United States anchor channel expansion.
- Sleep Clinics:Multidisciplinary diagnostic and therapeutic centers in Tokyo, Osaka, and metropolitan Germany coordinate physician-dentist collaboration for integrated care pathways.
- ENT Specialists:Otolaryngologists concentrate radiofrequency and laser surgical capacity in urban United States and German medical centers.
- Surgical Centers:Outpatient facilities perform uvulopalatopharyngoplasty and related palatal interventions under ambulatory surgery billing codes.
Dental offices retain volume leadership; sleep clinics hold the steepest expansion curve in integrated care model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways in the United States and EU MDR technical documentation standards in Germany are accelerating cross-border quality investments among mandibular advancement device manufacturers seeking multi-jurisdiction market access.
United States
Dental offices with sleep medicine cross-training drive oral appliance dispensing across metropolitan corridors. FDA maintains streamlined 510(k) premarket notification for mandibular advancement devices with predicate device pathways. Sleep clinics in Boston, Minneapolis, and Denver anchor integrated physician-dentist care models with stabilized reimbursement codes.
Germany
Metropolitan sleep centers in Munich and Hamburg scale procurement of electromechanical mandibular positioning systems. EU MDR notified body unannounced audits are restructuring quality agreements between dental laboratories and device manufacturers. The Rhine-Ruhr and Bavarian medical technology clusters concentrate ENT surgical capacity for radiofrequency palatal interventions.
Japan
Tokyo and Osaka sleep clinics prioritize oral appliance therapies as first-line interventions for mild-to-moderate obstructive sleep apnea. The country's national pharmaceutical regulator imposes additional sleep therapy device classifications that extend registration timelines. Kanto and Kansai regions host concentrated diagnostic infrastructure driving device procurement.
India
Tier-two cities including Pune, Ahmedabad, and Hyderabad present whitespace for mandibular advancement device partnerships with expanding dental chains. CDSCO medical device rules are harmonizing with global standards for imported sleep therapy equipment. Maharashtra and Gujarat industrial corridors are incubating domestic thermoplastic device manufacturing.
Australia
Subscription-based direct-to-consumer oral appliance programs concentrate marketing spend on primary snoring segments in Sydney and Melbourne. TGA medical device regulations require Australian Register of Therapeutic Goods inclusion for mandibular advancement devices. The southeastern coastal corridor hosts telehealth-enabled dental impression platforms disrupting traditional dispensing economics.
Global Anti-Snoring Devices and Snoring Surgery Market Competitive Landscape
Player mix skews toward respiratory technology conglomerates with sleep-specific divisions alongside specialized mandibular advancement device fabricators. Market structure concentrates around three archetypes: platform respiratory companies with humidification integration capabilities, dental-channel specialists with direct practitioner relationships, and emerging direct-to-consumer brands with subscription replacement models. Competitive moves center on telehealth-enabled fitting protocols and quality management system certifications that compress FDA 510(k) clearance timelines.
Within the platform respiratory tier, ResMed and Fisher & Paykel Healthcare exemplify scale-driven integration of humidification and sensing technologies. SomnoMed occupies a position as a dental-channel specialist with mandibular advancement expertise. Among European fabricators, Tomed Dr. Toussaint GmbH represents precision manufacturing archetypes serving specialized ENT surgical segments. These three anchors illustrate divergent competitive vectors: platform breadth versus channel depth versus surgical specialization.
| Leading Market Players |
|---|
| Vivos Therapeutics |
| Koninklijke Philips |
| ResMed |
| Airway Management |
| Apnea Sciences |
| SomnoMed |
| Fisher & Paykel Healthcare |
| Tomed Dr. Toussaint GmbH |
| ProSomnus Sleep Technologies |
| Others |
Supply & Pricing Matrix
Capacity utilization at specialized dental polymer foundries in Germany and the United States shapes both supply concentration and price floors for mandibular advancement devices. Manufacturers achieving ISO 13485 certification at scale capture pricing power through reduced batch rejection rates and accelerated FDA 510(k) clearance timelines that smaller competitors cannot match.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers in this market. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 maturity, FDA 510(k) predicate device lineage, and dental laboratory quality agreement depth. Cost compression in economy thermoplastic segments is intensifying because direct-to-consumer brands bypass professional fitting fees. Hospital sleep clinics exhibit lowest price sensitivity due to bundled reimbursement protocols; individual dental patients in cash-pay markets show highest elasticity.
Supply Chain Analysis
Container availability from Rotterdam and Hamburg ports constrains inbound logistics for biocompatible acrylic resin shipments sourced from specialized chemical manufacturers. Germany, the United States, and Japan concentrate precision dental polymer production; China and India feed growing thermoplastic component assembly. Supply chains draw from medical-grade methyl methacrylate, cobalt-chromium alloy frameworks, and pressure-sensor microelectronics. Single-source vulnerability concentrates in EU MDR-notified body auditing capacity for quality system certification. Distribution runs through dental laboratory networks, direct-to-consumer platforms, and hospital procurement consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer thermoplastic substitutes threaten incumbent positioning in primary snoring segments, forcing defensive adaptation across certification and channel strategies.
For Market Incumbents: Fortify dental-channel control through exclusive quality agreements with ISO 13485-certified laboratories in Germany and the United States. Deepen backward integration into biocompatible resin formulation to capture margin compression from Asian thermoplastic competitors. Prioritize FDA 510(k) clearance velocity as defensive moat against direct-to-consumer entrants lacking predicate device pathways. For New Entrants and Emerging Players: FDA 510(k) streamlined review pathways for moderate-risk devices offer fastest regulatory traction for capital-constrained entrants. India's tier-two dental chains present whitespace for mandibular advancement partnerships ahead of CDSCO harmonization completion. Telehealth-enabled intraoral scanning protocols enable direct-to-patient acquisition outside entrenched dental office dispensing economics. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among electromechanical device platforms with embedded sensor subscription services. Five-to-ten year viability favors manufacturers with dual FDA-EU MDR clearance portfolios and established dental GPO relationships. Watch reimbursement parity legislation between dental-administered oral appliances and physician-prescribed CPAP systems as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Streamlined Review | Accelerated clearance timelines compress competitive entry barriers for predicate-backed mandibular devices. |
| EU MDR Quality Agreement Restructuring | Unannounced notified body audits force dental laboratory consolidation toward compliant manufacturing partners. |
| Telehealth Dental Impression Platform | Remote intraoral scanning protocols bypass traditional dental office dispensing channel intermediaries. |
| Biocompatible Resin Backward Integration | In-house polymer formulation captures margin from specialized chemical suppliers and secures supply continuity. |
| Reimbursement Parity Strategy | Sleep medicine coding equivalence with CPAP systems expands addressable patient population in United States dental offices. |
Research Methodology
Operator-level perspectives from dental sleep medicine practitioners, biomedical engineers at mandibular device manufacturers, GPO contracts managers, and FDA regulatory consultants anchored the qualitative base. Primary interviews combined with secondary validation against FDA 510(k) premarket notification databases, EU MDR technical documentation filings, hospital procurement contract repositories, and dental laboratory quality certification records. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation cross-verified segment sizing.
Sensitivity analysis tested forecast robustness across regulatory timeline scenarios and reimbursement policy shifts. Segmentation dimensions modeled include product type, technology platform, application severity, and end-user channel across the projection horizon. CAGRs derived from polynomial trend fitting of historical clearance volumes and dental office dispensing economics. Forecast inputs incorporated ISO 13485 certification pipeline data and sleep clinic infrastructure expansion rates by metropolitan region.
The analysis sits within stated boundaries; outcomes outside FDA 510(k) predicate device availability or EU MDR notified body capacity constraints would require recalibration. Forecasts reflect documented assumptions regarding reimbursement code stabilization and dental-sleep medicine workforce pipeline development. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Atrial Appendage Occluder Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Hydrogel Contact Lenses Market
Medical Devices
Global Angiographic Catheters Market
Medical Devices
Bariatric Beds Market
Medical Devices
Global Venous Stents Market
Medical Devices
Thyroid Ablation Devices Market
Medical Devices
Human Anatomical Models Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Bone Screw System Market
Medical Devices
Posterior Chamber Lens Market
Medical Devices
Veterinary Ultrasound Scanners Market
Medical Devices
Electrophysiology Market
Medical Devices
Artificial Disc Market
Medical Devices
US Trauma Fixation Devices Market
Medical Devices
Micro-Bypass Systems Market