
 Vise-Grip Pliers Market | 2026-2036
Vise-Grip Pliers Market Size, Share, and Industry Trends Forecast 2026-2036
Vise-Grip Pliers Market Analysis
ISO 9001 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Stanley Black & Decker leverages its captive forging capacity to control alloy sourcing for high-torque locking pliers. Milwaukee Tool differentiates through Milwaukee ONE-KEY platform integration, while Tekton competes aggressively on direct-to-consumer pricing with minimal channel markup.
Vise-grip pliers are adjustable hand tools featuring a compound lever locking mechanism, typically forged from chrome-vanadium or chrome-molybdenum steel with hardened jaws rated to specific clamping pressures, designed to grip, clamp, or hold workpieces without continuous hand pressure. The product type dimension shows locking pliers commanding the dominant share due to their irreplaceability in welding and fabrication, while needle nose variants capture premium margins from electrical work applications. End user segmentation reveals contractors as the volume anchor, though DIY enthusiasts represent the fastest-growing channel as home improvement retail expands.
OSHA hand tool safety standards in the United States, CE marking requirements under EU machinery directives, and China's GB standards for hand tool mechanical performance collectively elevate minimum product specifications and filter out uncertified imports. The EU's REACH regulation further constrains coating chemistries for corrosion-resistant finishes. Stakeholders must monitor evolving alloy cost volatility and certification reciprocity agreements between major tooling jurisdictions to secure supply positions.
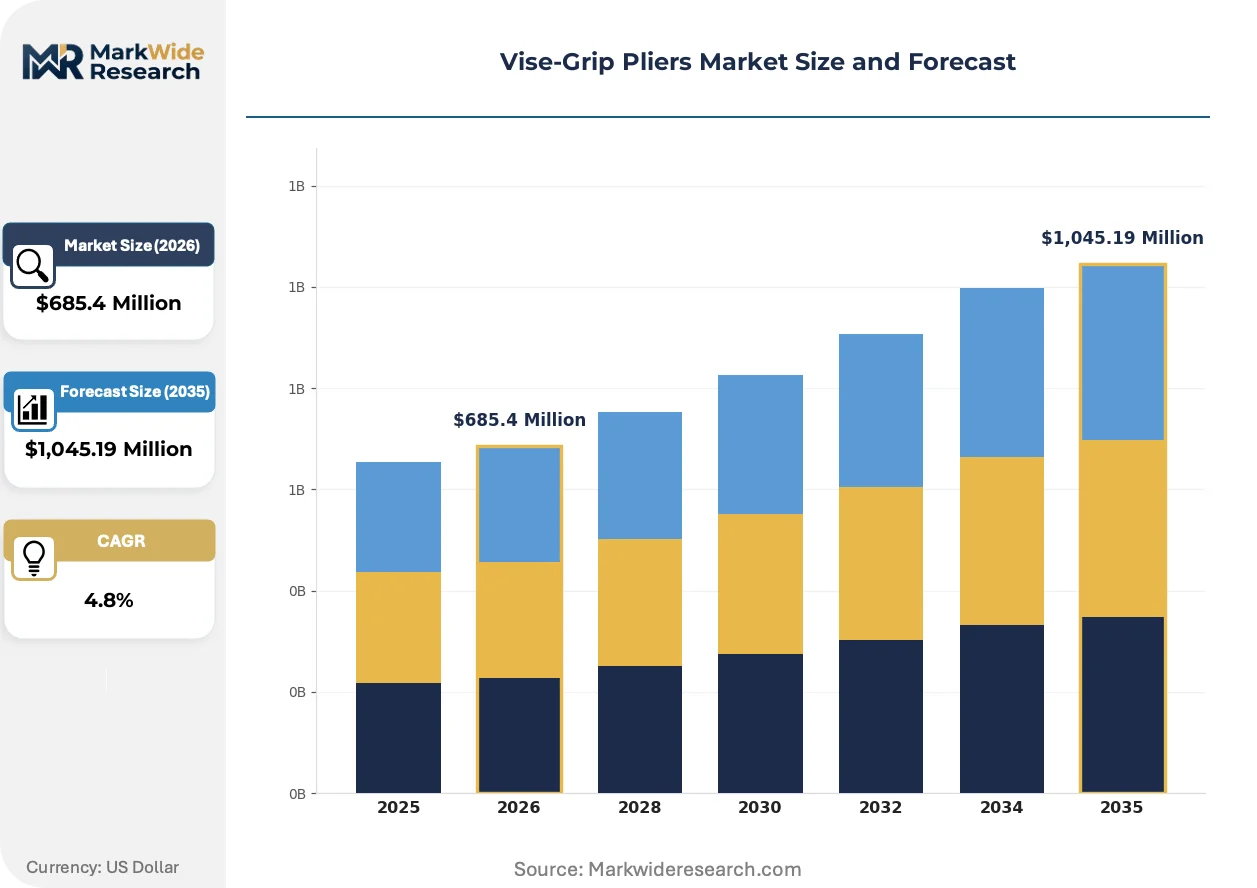
Market Dynamics
ISO 9001 certification requirements are bifurcating supplier bases into qualified and marginal participants, while captive forging capacity and alloy sourcing control separate durable margin holders from price competitors in locking pliers procurement.
Growth Catalysts
- Automotive repair demand:Vehicle complexity escalation drives specialized tool requirements at independent repair shops and dealership service centers, expanding replacement cycle frequency for precision gripping equipment.
- Welding and fabrication irreplaceability:Locking pliers remain non-substitutable for fixture holding during thermal joining processes, cementing demand across metalworking and construction trades regardless of adjacent tool innovation.
- REACH coating compliance:EU chemical restrictions on hexavalent chromium finishes accelerate qualified supplier consolidation, advantaging certified manufacturers with compliant surface treatment capabilities.
Market Restraints
- Chrome-vanadium alloy volatility:Ferrovanadium price swings from South African and Russian supply concentration transmit directly to forged component costs, compressing margin predictability for non-integrated producers.
- Guangdong and Zhejiang supplier density:Hand tool forging clusters in these Chinese provinces create geographic concentration risk for Western distributors dependent on single-source procurement lanes.
- Clamp force standardization gaps:Absence of unified international testing protocols for jaw pressure ratings forces redundant certification investments across export markets.
Strategic Opportunities
- DIY enthusiast channel expansion:Home improvement retail growth in suburban United States markets creates direct-to-consumer positioning potential beyond traditional contractor distribution.
- ONE-KEY platform convergence:Integration of tool tracking and inventory management software with physical hand tools opens recurring revenue models for connected product ecosystems.
- India BIS certification pathway:Mandatory Bureau of Indian Standards registration for imported hand tools creates first-mover advantage for early compliance investment in a price-sensitive volume market.
Industry Challenges
- Heat treatment technician scarcity:Specialized metallurgical expertise for jaw hardening process control is aging out of workforce pipelines without adequate vocational replacement.
- Multi-jurisdiction certification lag:Sequential GB, CE, and OSHA approval timelines extend product launch cycles by 14-18 months for new locking mechanism designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vise-Grip Pliers Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,045.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Locking Pliers, Slip Joint Pliers, Needle Nose Pliers, Groove Joint Pliers End User: Contractors, DIY Enthusiasts, Automotive Technicians, Industrial Maintenance Material: Steel, Aluminum, Carbon Fiber, Plastic Application: Construction, Automotive Repair, Electrical Work, Plumbing |
| Companies Covered | Stanley Black & Decker, Irwin Tools, Malco, Newell Brands, Milwaukee Tool, Tekton, Eagle Grips, True Mechanic, Harbor Freight Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vise-Grip Pliers Market Emerging Trajectories
Tool connectivity and materials science are reshaping competitive differentiation in hand tools, while regulatory chemistry restrictions and procurement digitization compress traditional channel structures.
Composite-reinforced polymer handles with embedded torque sensors are fragmenting the premium segment by enabling real-time clamping force feedback. Automotive assembly technicians in Germany and the United States are adopting these instruments for precision gasket seating. The technology is fragmenting established price tiers by creating a connected-tool category between conventional mechanical pliers and fully automated fixturing systems.
EU REACH Annex XVII restrictions on nickel release rates are tightening surface finish specifications for corrosion-resistant coatings. Chrome-free passivation chemistries now dominate new product development pipelines for European market entry. Electrical contractors sourcing needle-nose variants face accelerated compliance documentation requirements from distributors.
Direct procurement from manufacturer websites is displacing wholesale distributor relationships among mid-sized fabrication shops. Amazon Business and specialized industrial marketplaces capture growing share of replacement tool purchases. This channel rotation is most visible in North American automotive aftermarket operations seeking reduced procurement cycle times.
Vise-Grip Pliers Market Segmentation
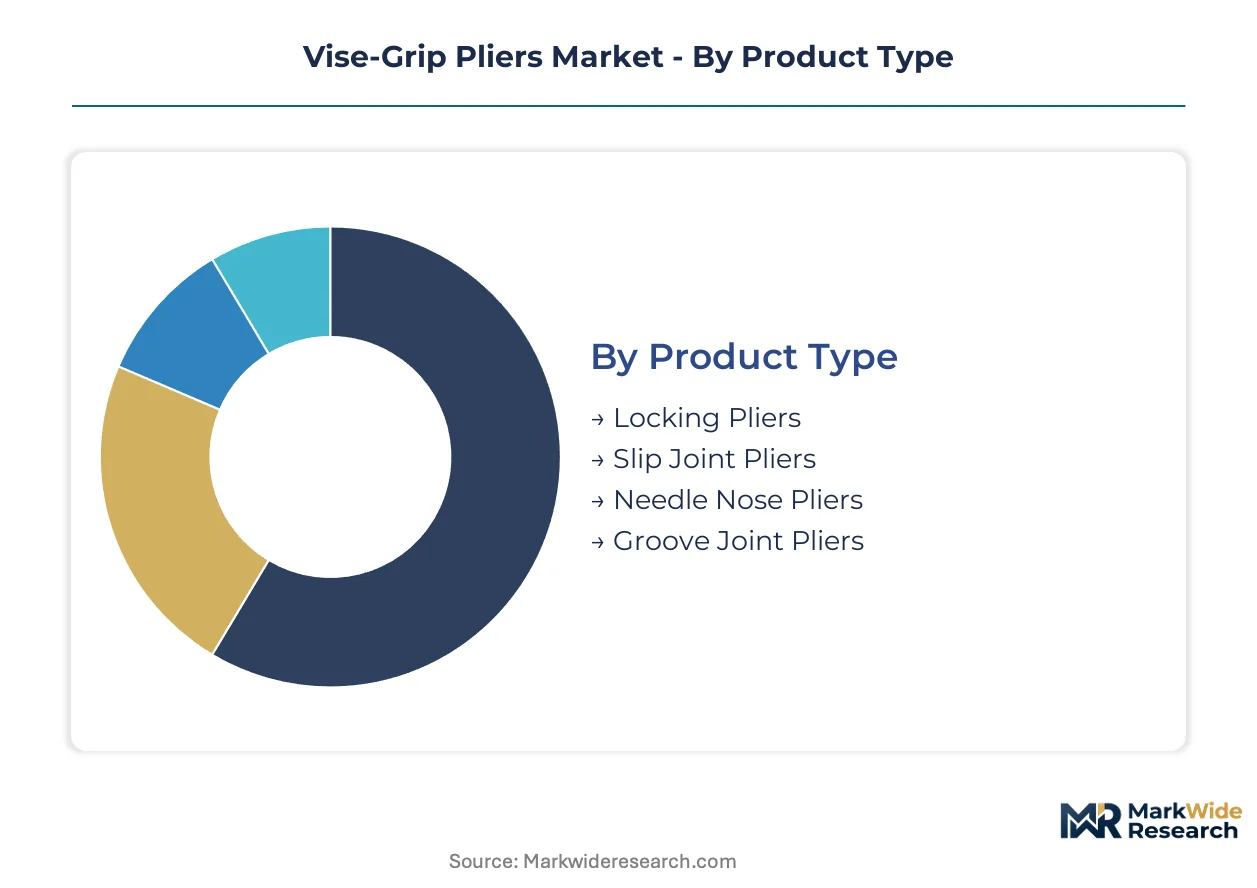
Vise-grip pliers segmentation reveals how regulatory compliance, material certification, and end-use specialization create distinct procurement channels. Each dimension carries specific technical standards that filter supplier qualification and pricing power.
Product Type:
CE marking and ISO 9001 certification requirements split product type performance tiers, with compliant surface treatments commanding premium positioning in European distribution.
- Locking Pliers:Forged from chrome-vanadium or chrome-molybdenum steel with compound lever mechanisms rated to specific clamping pressures. Demand concentrates at welding and fabrication shops across Germany and the United States, where thermal joining processes require non-substitutable fixture holding.
- Needle Nose Pliers:Extended tapered jaws with hardened tips for precision electrical termination work. Premium margins flow from electrical contractors in suburban United States markets facing accelerated REACH nickel release documentation requirements.
- Slip Joint Pliers:Adjustable pivot mechanism with serrated gripping surfaces for general mechanical tasks.
- Groove Joint Pliers:Multiple jaw positions for oversized fastener and pipe gripping in plumbing applications.
Established volume favors Locking Pliers; emerging adoption favors Needle Nose Pliers.
End User:
Cost tier differentiation separates professional-grade procurement from consumer-direct channels, with certification documentation requirements widening the gap between qualified and marginal supply sources.
- Contractors:Volume anchor segment sourcing through industrial distributors with mandatory ISO 9001 supplier verification. Procurement concentrates at construction and metalworking operations in China and Germany where tool replacement cycles track project completion timelines.
- DIY Enthusiasts:Fastest-expanding channel driven by home improvement retail growth in suburban United States markets. Amazon Business and manufacturer-direct websites displace traditional wholesale relationships for replacement purchases.
- Automotive Technicians:Specialized precision requirements at independent repair shops and dealership service centers.
- Industrial Maintenance:Planned maintenance schedules with captive tool inventory management systems.
Contractors anchor current procurement volumes; DIY Enthusiasts are climbing the fastest.
Material:
Application severity dictates material selection, with alloy sourcing control separating durable margin holders from price competitors in forged component supply.
- Steel:Chrome-vanadium and chrome-molybdenum alloys dominate high-torque locking pliers through controlled forging and heat treatment. Demand concentrates where OSHA hand tool safety standards and CE machinery directives enforce minimum mechanical performance specifications.
- Aluminum:Lightweight variants for overhead electrical work and aviation maintenance applications.
- Carbon Fiber:Emerging composite handles with embedded torque sensors for precision clamping feedback.
- Plastic:Molded polymer grips and composite-reinforced housings for corrosion-resistant finishes.
Steel commands established industrial procurement; Carbon Fiber is gaining share fastest in premium connected-tool categories.
Application:
Customer type specialization creates distinct specification requirements, with multi-jurisdiction certification timelines extending product launch cycles for new designs.
- Construction:Heavy-duty locking pliers for structural steel fabrication and temporary fixture holding. Procurement runs through qualified distributors serving metalworking trades in China, Germany, and the United States.
- Automotive Repair:Vehicle complexity escalation drives specialized tool requirements at independent shops and dealership service centers.
- Electrical Work:Insulated needle-nose variants with compliant surface treatments for live circuit work.
- Plumbing:Groove joint configurations for pipe fitting and fastener gripping in residential and commercial systems.
Construction holds established volume concentration; Automotive Repair shows steepest expansion trajectory from electrification complexity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ISO 9001 certification requirements and REACH coating compliance are redirecting procurement flows toward qualified suppliers in established manufacturing jurisdictions. China, Germany, and the United States concentrate tooling procurement volumes, while India and Japan present emerging certification-driven opportunities.
China
Guangdong and Zhejiang provinces anchor hand tool forging clusters supplying Western distributors with chrome-vanadium locking pliers. GB standards for hand tool mechanical performance filter out uncertified exports, tightening supplier qualification requirements. Shenzhen-based fabricators are expanding compliant surface treatment capabilities to meet EU REACH Annex XVII restrictions.
Germany
Automotive assembly technicians drive precision gripping equipment demand from Stuttgart and Munich industrial corridors. CE marking requirements under EU machinery directives enforce minimum mechanical performance specifications for professional-grade procurement. Solingen's metalworking tradition supports specialized heat treatment expertise for jaw hardening process control.
United States
Suburban home improvement retail expansion accelerates DIY enthusiast channel growth for replacement tool purchases. OSHA hand tool safety standards elevate minimum product specifications across contractor and automotive technician segments. Milwaukee and Chicago industrial distributors are consolidating procurement relationships with ISO 9001-verified forging suppliers.
India
Bureau of Indian Standards mandatory registration for imported hand tools creates first-mover advantage for early compliance investment. Maharashtra and Gujarat fabrication clusters are upgrading quality management systems to capture price-sensitive volume market share. Pune-based automotive component suppliers are driving specialized tool requirements from electrification complexity.
Japan
JIS standards for mechanical performance maintain premium positioning for precision gripping equipment in aviation maintenance applications. METI industrial policy supports vocational training programs addressing heat treatment technician scarcity. Osaka-Kobe manufacturing belt fabricators are integrating torque sensor technology for connected-tool development.
Vise-Grip Pliers Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive forging capacity alongside specialized hand tool manufacturers competing on direct-to-consumer channels. Market structure exhibits tiered consolidation with premium positioning held by quality-certified suppliers and price competition concentrated in unbranded import segments. Strategic archetypes include alloy-integrated manufacturers controlling upstream material flows, platform-integrated tool companies embedding connectivity features, and digitally-native brands bypassing wholesale distribution. Dominant competitive moves encompass backward integration into forging operations and strategic partnerships with industrial marketplace platforms.
Among North American diversified manufacturers, Stanley Black & Decker and Milwaukee Tool exemplify contrasting strategic positions within the premium tier. Stanley Black & Decker occupies a position anchored by captive forging capacity and alloy sourcing control, while Milwaukee Tool represents platform-integrated differentiation through connected product ecosystems. Tekton sits within the direct-to-consumer archetype, competing aggressively on minimal channel markup. Irwin Tools and Malco anchor mid-market positioning through established distribution relationships with industrial distributors serving welding and fabrication trades.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Irwin Tools |
| Malco |
| Newell Brands |
| Milwaukee Tool |
| Tekton |
| Eagle Grips |
| True Mechanic |
| Harbor Freight Tools |
| Others |
Supply Flow & Price Mechanics
Ninety-day order-to-delivery cycles for chrome-vanadium forged components concentrate pricing power with Guangdong-based suppliers holding captive heat-treatment capacity, while Western distributors face margin compression from ferrovanadium cost volatility and redundant certification investments across GB, CE, and OSHA jurisdictions.
Pricing Analysis
Certification grade creates the primary spread between premium and marginal supply tiers, with ISO 9001-verified and CE-marked locking pliers commanding substantial premiums over unbranded imports lacking compliant surface treatments. Three-tier pricing structure across premium, standard, and economy levels stratifies by alloy sourcing control and channel markup intensity, with direct-to-consumer brands like Tekton compressing middle-tier margins through minimal distribution overhead. Pricing pressure stems from ferrovanadium spot market swings transmitted directly to forged component costs, squeezing non-integrated manufacturers. DIY enthusiasts exhibit highest price sensitivity through Amazon Business and manufacturer-direct comparison shopping, while automotive dealership service centers show lowest sensitivity due to captive procurement systems and replacement cycle urgency.
Supply Chain Analysis
Container availability constraints on the Shanghai-Los Angeles trade lane amplify inbound logistics costs for Western distributors dependent on Guangdong and Zhejiang forging clusters. Supply concentrates in China, Germany, and the United States, with chrome-vanadium alloy, chrome-molybdenum steel, and REACH-compliant passivation chemistries as critical input dependencies. Single-source vulnerability runs through South African and Russian ferrovanadium supply concentration, exposing margin predictability to geopolitical disruption. Distribution runs through industrial distributors serving welding and fabrication trades, though Amazon Business and manufacturer-direct websites are displacing traditional wholesale relationships among mid-sized fabrication shops seeking reduced procurement cycle times.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vise-grip pliers market sits in early-cycle expansion as vehicle electrification complexity drives specialized tool requirements at independent automotive repair shops, expanding replacement frequency beyond traditional construction and metalworking demand anchors.
For Market Incumbents: Consolidate captive forging capacity and alloy sourcing control to defend margin position against ferrovanadium cost volatility, while accelerating ISO 9001 certification reciprocity investments to compress multi-jurisdiction approval timelines that currently extend product launch cycles. Prioritize backward integration into heat treatment operations to address technician scarcity and secure jaw hardening process control capabilities that are aging out of workforce pipelines. For New Entrants and Emerging Players: Connected-tool service layers where incumbents under-serve present white-space opportunity, specifically torque sensor integration for precision clamping feedback in automotive assembly applications. Target suburban United States DIY enthusiast segments through direct-to-consumer positioning with minimal channel markup, leveraging Amazon Business marketplace infrastructure to bypass established distributor relationships. Pursue India BIS certification early to capture price-sensitive volume market share before mandatory registration barriers harden. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because ISO 9001 certification requirements are bifurcating supplier bases and advantaging scaled manufacturers with compliant surface treatment capabilities and captive forging capacity. Acquisition targets should prioritize mid-tier forging operations with GB standards compliance and expanding REACH-compliant passivation chemistry pipelines. Watch ferrovanadium spot price stabilization as the signal indicating margin compression relief and valuation recovery window for non-integrated producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Forging Operations | Captive chrome-vanadium alloy sourcing controls cost volatility from South African supply concentration. |
| Connected-Tool Platform Integration | Milwaukee ONE-KEY convergence opens recurring revenue from torque sensor embedded handle ecosystems. |
| Multi-Jurisdiction Certification Investment | Simultaneous GB, CE, and OSHA approval compression reduces 14-18 month launch cycle penalties. |
| Direct-to-Consumer Channel Expansion | Amazon Business and manufacturer-direct positioning bypass wholesale markups in suburban DIY markets. |
| REACH-Compliant Surface Treatment Scale-Up | Shenzhen-based chrome-free passivation capacity secures European market entry against Annex XVII restrictions. |
Methodological Framework
A standing panel of procurement directors at automotive dealership service centers, welding shop owners, industrial distributor category managers, and heat treatment process engineers provided ongoing calibration across primary interview cycles, with secondary validation drawing from customs trade data, SEC 10-K filings of diversified tool manufacturers, OSHA hand tool safety standard documentation, and EU REACH Annex XVII regulatory filings. Bottom-up segment sizing triangulated against top-down market envelope checks ensured dimensional consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon, with analytical frameworks modeling product type, end user, material, and application dimensions alongside regional certification cluster variations. CAGRs derived from historical trajectory analysis and adoption curve positioning incorporated automotive electrification complexity indices and home improvement retail expansion rates as industry-specific forecast inputs.
Material uncertainties — ferrovanadium supply disruption from geopolitical events, REACH coating chemistry restriction expansion, and heat treatment technician workforce attrition — sit outside the modeled envelope. Forecasts reflect documented assumptions about certification reciprocity progression and alloy cost stabilization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Automatic Lathe Machines Market
Tools
Hydraulic Tools Market
Tools
Floor Polishing Machine Market
Tools
Nut Runner Market
Tools
Handheld Blower Market
Tools
Grease Gun Market
Tools
3D Milling Machines Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Screwdriver Market
Tools
Global Cordless Power Tools Market
Tools
Land Survey Equipment Market
Tools
Press Machine Market
Tools
Drill Bit Market
Tools
Laser Engraving Machine Market
Tools
Steel Measuring Tape Market
Tools
Drill Set Market