
 Automatic Lathe Machines Market | 2026-2036
Automatic Lathe Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Lathe Machines Market Outlook
Direct-to-factory digital sales channels is reshaping how automatic lathe machines reach end users, bypassing traditional distributor networks in favor of online configuration tools and remote commissioning services. DMG Mori leverages its integrated digital twin platform to control the pre-sales engineering process. Yamazaki Mazak anchors its competitive stance through extensive service center networks across manufacturing belts. Tsugami specializes in compact Swiss-type configurations for medical and electronics micro-machining.
An automatic lathe machine executes material removal operations through computer-controlled spindle rotation and multi-axis tool positioning, achieving tolerances within micrometers for cylindrical components. These machines serve as production backbone equipment for industries requiring high-volume precision turning of metals and engineered polymers. CNC Lathes dominate installed base value due to their versatility across batch sizes and material classes, while Swiss-type Lathes capture disproportionate margin pools in medical device and electronics applications where bar stock diameters fall below 32 millimeters. The Aerospace end-user segment shows structural momentum from titanium alloy component demand, though cycle qualification timelines extend procurement decisions.
ISO 23125 safety standards for machine tools and the EU Machinery Directive constrain design architectures for equipment sold into European manufacturing facilities, elevating compliance costs for non-CE-certified suppliers. China's SAMR enforces GB standards for electromagnetic compatibility and operational safety that foreign OEMs must satisfy through in-country testing protocols. Japan's METI promotes smart factory adoption through JIS-aligned interoperability frameworks that shape R&D priorities for domestic builders. Stakeholders must monitor how adaptive control technology integration alters the competitive boundary between premium CNC platforms and mid-tier automatic control configurations.
Market Dynamics
Adaptive control technology integration is compressing the performance gap between premium CNC platforms and mid-tier automatic configurations, forcing builders to recalibrate R&D roadmaps and pricing architectures.
Growth Catalysts
- EU Machinery Directive compliance mandates:European facilities face accelerated replacement cycles for non-CE-certified equipment, creating pull for certified automatic lathe suppliers.
- Titanium alloy aerospace component demand:Structural momentum from jet engine and airframe programs drives specialized Swiss-type lathe procurement for hard-metal precision turning.
- Changwon precision manufacturing cluster expansion:South Korea's concentrated machining hub attracts dedicated service infrastructure and application engineering support.
Market Restraints
- High-purity bearing steel supply concentration:Japanese and German specialty steel mills control critical spindle component feedstock, exposing builders to input cost volatility.
- Extended aerospace qualification timelines:Tier-1 suppliers require 18-24 month cycle validation before production approval, stretching OEM cash conversion cycles.
- Electromagnetic compatibility testing requirements:China's SAMR enforces GB standards through in-country protocols that add certification friction for foreign OEMs.
Strategic Opportunities
- Medical device micro-machining white space:Bar stock diameters below 32 millimeters in orthopedic and cardiovascular implants favor compact Swiss-type configurations.
- Digital twin convergence with remote commissioning:Integrated pre-sales engineering platforms enable factory-direct configuration without distributor intermediaries.
- Japan's METI smart factory incentives:JIS-aligned interoperability frameworks subsidize domestic builder R&D for connected machining systems.
Industry Challenges
- CNC programming and mechatronics skill scarcity:Machine shops struggle to recruit operators capable of multi-axis adaptive control optimization.
- Legacy analog control system integration friction:Brownfield facilities face retrofit complexity when connecting new automatic lathes to existing shop-floor data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Lathe Machines Market |
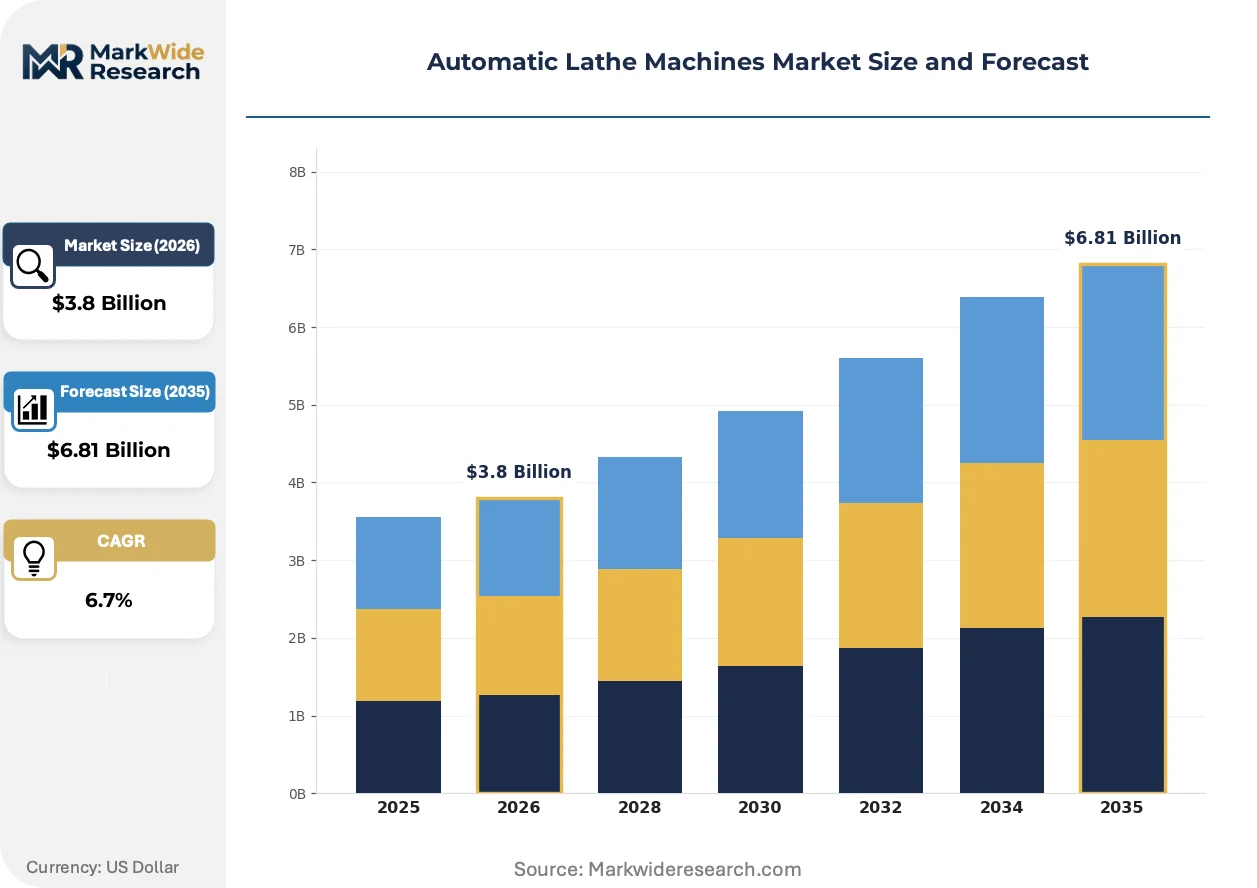
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CNC Lathes, Swiss-type Lathes, Hybrid Lathes, Turret Lathes End User: Aerospace, Automotive, Electronics, Medical Devices Size: Small, Medium, Large, Extra Large Technology: Digital Control, Manual Control, Automatic Control, Adaptive Control |
| Companies Covered | DMG Mori, Haas Automation, Yamazaki Mazak, Okuma, Tsugami, Star CNC, Tornos, Citizen Machinery, Doosan Machine Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Lathe Machines Market Strategic Shifts
Digital sales infrastructure and real-time machine connectivity are restructuring how automatic lathe capabilities reach end users, compressing the traditional specification-to-commissioning timeline.
Edge computing architectures with embedded spindle vibration analysis are collapsing the boundary between predictive maintenance and real-time process optimization. Medical device manufacturers in Switzerland and Germany adopt these systems fastest. The technology is collapsing service contract structures toward performance-guarantee models.
REACH substance restrictions on coolant chemistries and lubricant formulations are forcing reformulation of metalworking fluid systems used in precision turning operations. European OEMs face accelerated compliance deadlines through 2026. Swiss-type lathe builders serving orthopedic implant manufacturers are responding with minimum-quantity lubrication systems.
Factory-direct digital configuration tools now capture specification workflows previously managed by regional distributor technical teams. Japanese and German automotive suppliers lead adoption of online spindle-load simulation and remote factory acceptance testing. This channel shift is most visible in Yangtze River Delta machining hubs where buyers consolidate procurement across multiple facility locations.
Automatic Lathe Machines Market Segmentation
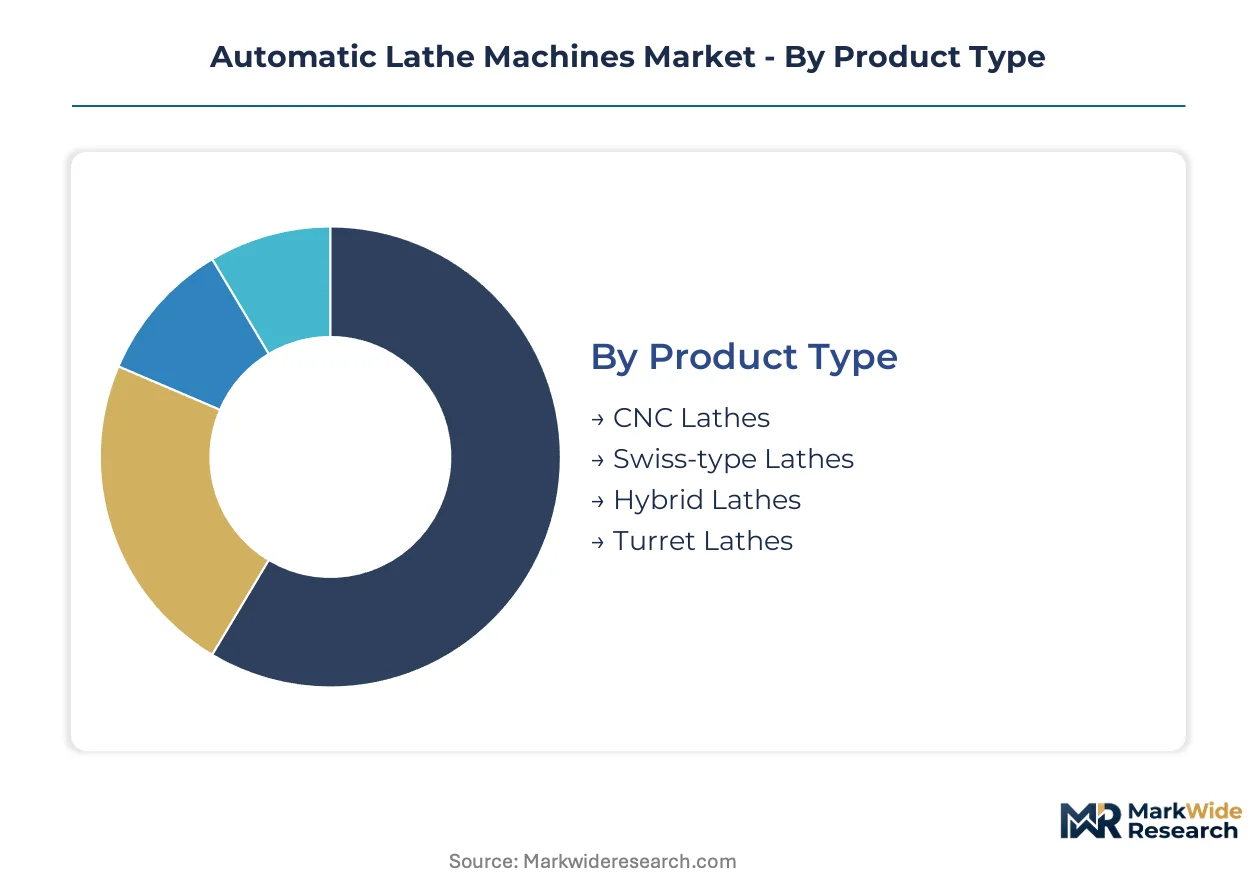
Automatic lathe machine purchasing decisions pivot on component precision requirements, production batch economics, and facility integration constraints. Segmentation reveals how Swiss-type configurations command premium positioning in micro-machining while CNC platforms dominate general-purpose manufacturing.
Product Type:
Use-case spectrum spans high-volume automotive powertrain production to single-piece aerospace component machining.
- CNC Lathes:Computer-numerical control architectures enable rapid program changeovers across batch sizes from prototype to mass production. Automotive suppliers in Germany and Japan anchor demand for multi-axis platforms handling diverse material classes from aluminum to hardened steel.
- Swiss-type Lathes:Sliding headstock designs with guide bushing support maintain micrometer tolerances on bar stock below 32 millimeters. Medical device manufacturers in Switzerland and orthopedic implant producers in Changwon drive disproportionate margin capture through precision component demand.
- Hybrid Lathes:Combined turning-milling centers reduce work-in-process inventory through single-setup completion of complex geometries.
- Turret Lathes:Six-station tool indexing supports medium-batch production of standardized cylindrical components with reduced operator intervention.
The dominant share belongs to CNC Lathes, while Swiss-type Lathes is closing the gap fastest.
End User:
Customer type differentiation separates capital-intensive qualification-driven procurement from price-sensitive volume purchasing.
- Aerospace:Titanium alloy jet engine components and airframe structural parts demand thermal-stable machine architectures with 18-24 month supplier qualification cycles. Boeing and Airbus Tier-1 networks concentrate procurement among builders with AS9100 certification and established FAA process approvals.
- Automotive:Powertrain precision components from transmission shafts to fuel injection parts require high spindle uptime and automated bar feed integration. German OEMs and Japanese keiretsu suppliers favor builders with localized service infrastructure.
- Electronics:Connector pins and miniature sensor housings favor compact Swiss-type configurations with sub-millimeter feature capability.
- Medical Devices:Orthopedic implants and cardiovascular instruments command sterile-process-compatible coolant systems and traceable quality documentation.
Automotive absorbs the largest equipment value, though Medical Devices shows the steepest expansion trajectory as aging demographics drive implant demand.
Size:
Volume-to-footprint ratios determine facility layout economics across manufacturing belt configurations.
- Small:Benchtop configurations under 500 kilograms serve job shops and R&D prototyping with single-phase power requirements.
- Medium:Floor-standing platforms with 200-500 millimeter swing capacity dominate general machining contractor installed bases.
- Large:Heavy-duty spindles handling 1000+ millimeter diameters support wind turbine component and industrial equipment shaft production.
- Extra Large:Specialized gantry-mounted systems machine marine propulsion shafts and power generation rotors requiring custom foundation engineering.
Medium specifications hold the majority position, while Large formats gain share fastest from renewable energy infrastructure investment.
Technology:
Control architecture maturity separates established installed base maintenance from next-generation capability deployment.
- Digital Control:Ethernet-connected CNC platforms with OPC-UA interoperability enable smart factory integration and predictive maintenance analytics. METI-subsidized Japanese builders and EU Machinery Directive-compliant European OEMs lead specification adoption.
- Adaptive Control:Real-time spindle load and vibration monitoring automatically optimize feed rates and tool paths. Edge computing implementations in German automotive supplier parks are collapsing the performance gap against premium CNC configurations.
- Automatic Control:Fixed-cycle cam and relay-logic systems persist in brownfield facilities with limited capital replacement budgets.
- Manual Control:Handwheel-operated platforms serve apprenticeship training and specialized artisan production with minimal lot sizes.
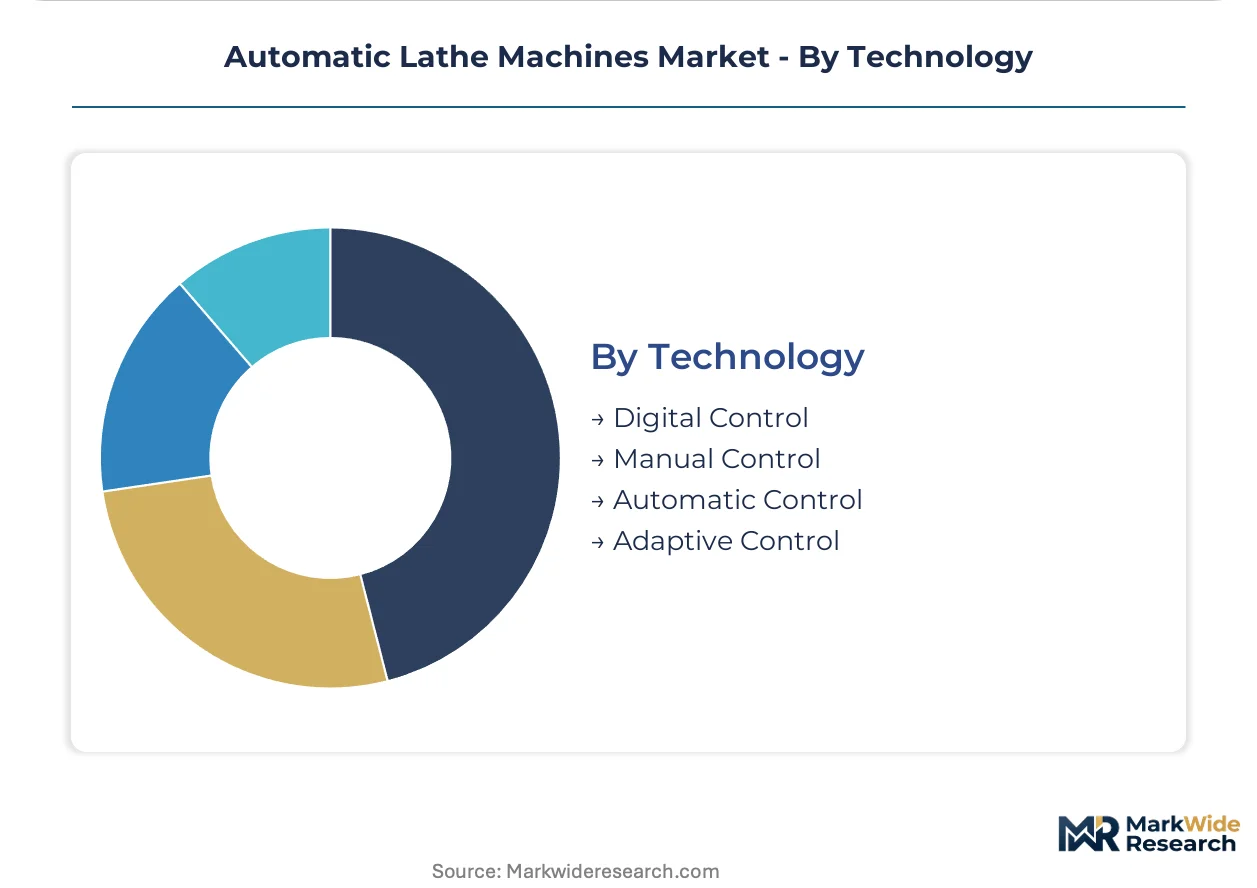
Digital Control maintains installed base dominance, while Adaptive Control climbs the fastest as builders recalibrate R&D roadmaps around real-time optimization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's smart factory subsidies and Japan's JIS interoperability frameworks anchor the most concentrated precision machining demand. National regulators in Germany, China, South Korea, and the United States enforce divergent certification protocols that fragment equipment specification standards.
Germany
Automotive powertrain manufacturers in Stuttgart and Munich drive multi-axis CNC lathe procurement for transmission shaft production. The EU Machinery Directive mandates CE certification with ISO 23125 safety compliance for all imported equipment. Baden-Württemberg's precision engineering belt concentrates builder service infrastructure and application engineering centers.
China
Yangtze River Delta machining hubs consolidate procurement across automotive and electronics component suppliers. SAMR enforces GB standards for electromagnetic compatibility through mandatory in-country testing protocols. Suzhou and Shanghai manufacturing parks attract dedicated technical support teams from Japanese and European OEMs.
South Korea
Changwon's precision manufacturing cluster expands Swiss-type lathe deployment for medical device and aerospace subcontractors. The country's industrial safety regulator aligns equipment certification with international standards while maintaining domestic testing requirements. Busan-Ulsan shipbuilding corridors drive heavy-duty large-format lathe demand for marine propulsion shafts.
Japan
Nagoya's automotive keiretsu suppliers and Tokyo medical device manufacturers anchor premium CNC and Swiss-type procurement. METI subsidizes JIS-aligned smart factory adoption that shapes domestic builder R&D priorities. Chubu region machine tool builders concentrate adaptive control development for connected machining systems.
United States
Aerospace Tier-1 suppliers in Seattle and Dallas-Fort Worth drive titanium alloy component machining demand with extended qualification cycles. FAA process approval requirements stretch OEM cash conversion timelines to 18-24 months. Midwest automotive belts in Michigan and Ohio favor builders with localized spare parts logistics.
Automatic Lathe Machines Market Competitive Environment
Full-service platform builders and specialized Swiss-type manufacturers split the market into distinct competitive spheres. The installed base concentrates among Japanese and German heritage firms with decades of aerospace and automotive qualification history. Three strategic archetypes dominate: integrated digital twin providers, compact precision specialists, and scale-driven volume suppliers. Consolidation pressure favors M&A activity among mid-tier automatic control builders, while technology licensing partnerships accelerate adaptive control deployment.
Within the precision-specialist tier, Tsugami and Star CNC exemplify compact Swiss-type configuration leadership for medical micro-machining applications. DMG Mori occupies a position as the integrated digital twin archetype with factory-direct configuration capabilities. These three anchors represent divergent responses to direct-to-factory channel displacement and remote commissioning service models.
| Leading Market Players |
|---|
| DMG Mori |
| Haas Automation |
| Yamazaki Mazak |
| Okuma |
| Tsugami |
| Star CNC |
| Tornos |
| Citizen Machinery |
| Doosan Machine Tools |
| Others |
Value Chain & Pricing Dynamics
Changwon's precision manufacturing cluster concentrates Swiss-type lathe production capacity, translating upstream spindle component scarcity into asymmetric pricing power for Japanese and German specialty steel mills serving premium machine builders.
Pricing Analysis
Price spreads between German-engineered CNC platforms and mid-tier Asian alternatives widen by 40-60% on equivalent swing capacity specifications. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified European builders with ISO 23125 compliance from non-certified competitors. Cost compression in the mid-tier segment intensifies because adaptive control technology erodes performance differentiation. Automotive powertrain suppliers in Stuttgart and Nagoya exhibit lowest price sensitivity due to qualification-driven procurement, while job shops in Yangtze River Delta machining hubs drive hardest bargain on per-spindle economics.
Supply Chain Analysis
High-purity bearing steel feedstock concentrates in Japanese and German specialty mills, with Swedish and Austrian producers holding secondary positions. Spindle assemblies, linear motion systems, and precision ball screws draw from these concentrated metallurgical sources. Single-source vulnerability in ceramic bearing elements exposes builders to 6-9 month lead time volatility when Kagoshima-based suppliers face capacity constraints. Distribution runs through factory-direct digital channels for premium configurations, while regional distributors retain grip on mid-tier automatic control systems in emerging manufacturing belts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Adaptive control convergence with edge computing architectures is disrupting traditional CNC premium-mid tier boundaries, forcing stakeholders to recalibrate positioning around real-time optimization capabilities rather than legacy control hierarchies.
For Market Incumbents: Insulate installed base value through captive aftermarket service contracts and predictive maintenance platform lock-in. Secure backward integration into spindle bearing supply through equity stakes in Kagoshima ceramic component specialists. Prioritize JIS-aligned interoperability certification to capture METI smart factory subsidy flows and exclude non-compliant challengers from Japanese keiretsu procurement networks.
For New Entrants and Emerging Players: Southeast Asian medical device manufacturing corridors offer underpenetrated demand for compact Swiss-type configurations with sub-32 millimeter bar stock capability. Target orthopedic implant subcontractors in Malaysia and Thailand with minimum-quantity lubrication systems that preempt REACH coolant compliance costs. Lead with remote factory acceptance testing capabilities to bypass established distributor technical teams and compress specification-to-commissioning timelines.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors adaptive control specialists with edge-computing IP portfolios over legacy CNC platform builders facing R&D roadmap obsolescence. Five-to-ten year viability hinges on software-defined machine architecture migration rather than mechanical precision heritage. Monitor aerospace Tier-1 supplier qualification pipeline velocity as inflection indicator for premium segment demand durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Control Platform Development | Edge computing implementations collapse performance gaps against premium CNC configurations in Stuttgart supplier parks. |
| CE Certification Fast-Track Investment | ISO 23125 compliance unlocks EU Machinery Directive-mandated replacement cycles in Baden-Württemberg manufacturing belt. |
| Minimum-Quantity Lubrication System Launch | REACH-compliant coolant architectures preempt regulatory deadlines for orthopedic implant manufacturers in Switzerland. |
| Digital Twin Integration Partnership | Remote commissioning capabilities disintermediate regional distributors in Yangtze River Delta procurement consolidation. |
| Ceramic Bearing Supply Agreement | Long-term offtake contracts with Kagoshima specialists mitigate spindle component lead time volatility exposure. |
Study Parameters
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in documented compliance trajectories. Plant engineers at Changwon precision manufacturing clusters, OEM procurement teams in Stuttgart automotive keiretsu, and aftermarket service heads at Japanese builders provided operational perspective. Trade customs data, METI smart factory subsidy disclosures, EU Machinery Directive implementation reports, and SAMR GB standards bulletins supplied external validation. Bottom-up equipment shipment tracking and top-down manufacturing value-add estimates triangulate market sizing.
Calibration against historical CAGRs from adjacent precision machinery categories informs the projection framework across the analysis window. Segmentation models incorporate product type, end-user industry, machine size tier, and control technology architecture dimensions. Aerospace qualification cycle timelines, automotive powertrain capital expenditure patterns, and medical device implant demand demographics feed industry-specific forecast inputs. Growth rates derive from elasticity-adjusted equipment replacement schedules and greenfield facility commissioning pipelines.
Practitioners should monitor REACH substance restriction implementation pace and aerospace Tier-1 supplier financial health for early signals of demand inflection. Forecasts reflect assumptions about regulatory compliance cost pass-through and adaptive control adoption velocity. Cross-checking against Japanese Machine Tool Builders' Association shipment aggregates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Yard Scraper Market
Tools
Book Binding Machines Market
Tools
Turning Tools Market
Tools
Rotary Hammer Drill Market
Tools
Brazing Torch Market
Tools
Rotary Tools Market
Tools
Construction Nails Market
Tools
Entrenching Tool Market
Tools
Indexable Tool Inserts Market
Tools
Pneumatic Marking Machines Market
Tools
Portable Pressure Washer Market
Tools
US Hitter Based Hand Tools Market
Tools
Oxy-Fuel Torches Market
Tools
Drain Cleaning Equipment Market
Tools
Automatic Heat Press Machines Market
Tools
Machine Tools Market