
 Pliers Market | 2026-2036
Pliers Market Size, Share, and Industry Trends Forecast 2026-2036
Pliers Market Analytics
Advanced alloy metallurgy is reconfiguring how pliers achieve hardness-to-toughness ratios in high-stress applications. Apex Tool Group leverages captive forging capacity to control cost structures across its North American distribution network. Knipex Tools sustains premium positioning through precision-ground jaw geometries that reduce slippage in electrical termination work. Klein Tools anchors its growth in utility-sector procurement channels where insulated handle specifications dominate purchasing criteria.
Pliers are hand-operated gripping tools forged from alloy steel with induction-hardened jaws, designed to cut, bend, twist, or hold materials across mechanical and electrical tasks. Carbon content typically ranges from 0.45% to 0.80% to balance wear resistance with impact durability, while multi-stage heat treatment ensures Rockwell hardness of 54-62 HRC at the cutting edges. The type dimension shows locking pliers capturing expanding share in automotive maintenance due to self-adjusting jaw mechanisms that reduce technician hand fatigue. Material-grade segmentation reveals chrome vanadium steel commanding the largest volume position, though aluminum variants are carving niche share in aviation MRO where weight reduction governs tool selection.
ISO 5743 and ISO 5745 govern plier dimensional tolerances and cutting performance testing, while OSHA 1910.269 mandates insulated handle ratings for live electrical work in the United States. REACH compliance in Europe restricts hexavalent chromium in surface plating, pushing manufacturers toward zinc-nickel and ceramic conversion coating alternatives. Stakeholders must track how evolving ESG disclosure rules under CSRD reshape supplier qualification timelines for European industrial distributors.
Market Dynamics
ISO 5743 and ISO 5745 certification tightening is forcing manufacturers to retool heat-treatment lines and recalibrate dimensional tolerances, compressing margins for non-compliant suppliers while advantaging precision-forging specialists.
Growth Catalysts
- Automotive fleet aging:Extended vehicle lifespans in Germany and the United States are expanding workshop tool replacement cycles for locking plier variants.
- REACH plating restrictions:Hexavalent chromium bans under European chemical regulations are accelerating zinc-nickel and ceramic conversion coating adoption, creating premium-tier differentiation.
- Aviation MRO weight mandates:Aluminum alloy pliers are displacing steel in aircraft maintenance kits where every kilogram drives fuel cost calculations.
Market Restraints
- Alloy steel price volatility:Chrome vanadium feedstock costs fluctuate with nickel and molybdenum exchange pricing, squeezing mid-tier forging operations.
- Chinese supply concentration:Locking plier volume clusters in Zhejiang and Guangdong provinces create single-geography exposure for global distributors.
- Insulated handle technical ceiling:OSHA 1910.269 dielectric ratings max out at 1,000V AC, limiting product applicability in high-voltage utility segments.
Strategic Opportunities
- Indian infrastructure buildout:National highway and rail electrification projects are opening procurement channels for insulated-handle pliers compliant with CEA safety codes.
- ESG disclosure tailwinds:CSRD supplier qualification timelines in Europe favor manufacturers with documented carbon footprint reduction across forging and coating processes.
- Direct-to-workshop platforms:Digital procurement portals are bypassing industrial distributors, capturing margin from independent automotive repair shops.
Industry Challenges
- Precision grinding skill scarcity:Jaw geometry tolerances below 0.05mm require specialized machinists that vocational pipelines in North America and Europe no longer produce at scale.
- Multi-standard certification complexity:Simultaneous ISO, VDE, and UL testing protocols extend product launch timelines by 8-14 months for insulated tool variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pliers Market |
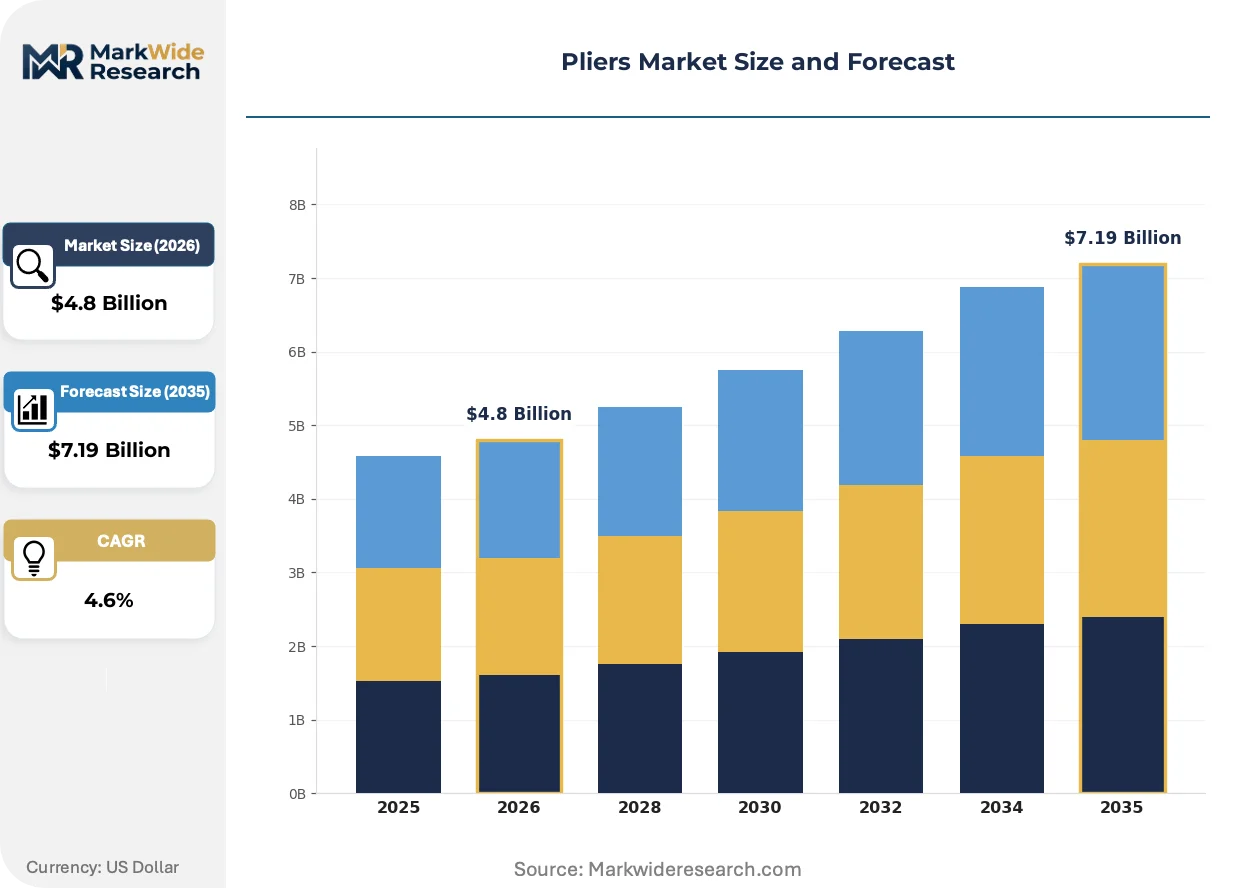
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Slip Joint, Needle Nose, Locking, Diagonal Material: Steel, Carbon Fiber, Aluminum, Plastic Use Case: Electrical, Automotive, Construction, General Purpose Handle Type: Insulated, Ergonomic, Non-slip, Straight |
| Companies Covered | Apex Tool Group, Klein Tools, Knipex Tools, Snap-on, Channellock, Irwin Tools, Akar Tools, CHISEN Tools, Park Tool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pliers Market Evolving Landscape
Metallurgical innovation and regulatory chemistry shifts are reconfiguring how pliers balance hardness, weight, and environmental compliance across end-use verticals.
Induction-hardened cutting edges are migrating from uniform 58-62 HRC specifications toward gradient hardness profiles that preserve core toughness while maximizing edge retention. Aerospace MRO buyers in France and Germany are specifying these variants for titanium and Inconel fastening work. This migration from monolithic heat treatment is compressing the addressable market for conventional forged products without secondary surface engineering.
REACH Annex XVII restrictions on hexavalent chromium in surface coatings are compelling plier manufacturers to validate zinc-nickel and trivalent chrome alternatives through accelerated corrosion testing. The industrial consequence is extended qualification cycles for European industrial distributors who must document coating chemistry to downstream automotive and energy clients. Electrical termination tool suppliers serving German utility procurement channels are most affected, with several forging operations relocating electroplating lines to CSRD-aligned facilities.
Workshop procurement through integrated supplier platforms is displacing traditional two-step distribution through regional industrial distributors. Independent automotive repair shops in the United States are consolidating purchases through national parts chains that demand private-label plier SKUs with guaranteed ISO 5743 compliance. This channel consolidation is most visible in California and Texas, where multi-location workshop groups negotiate master service agreements replacing spot-buying from local tool distributors.
Pliers Market Segmentation
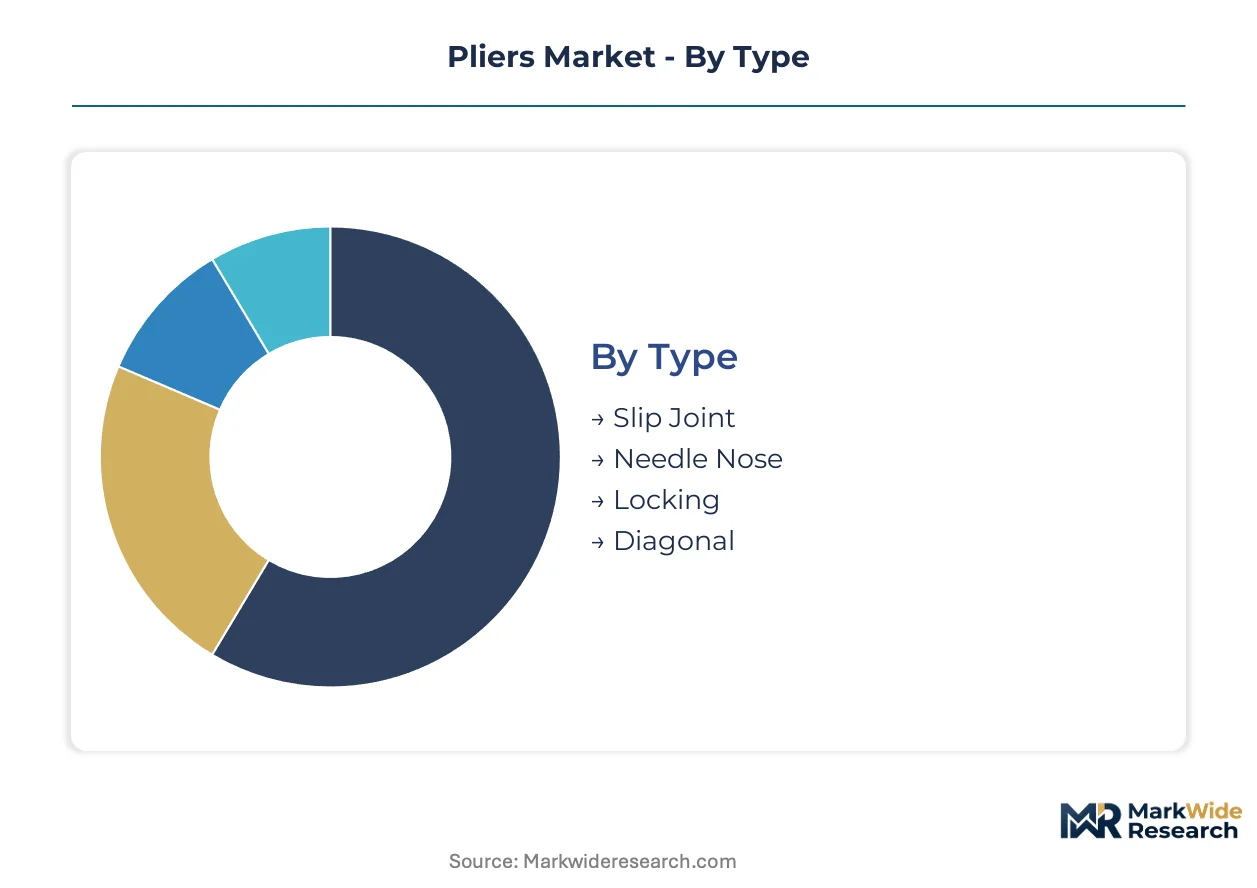
Pliers manufacturers configure product portfolios around four distinct segmentation axes. Each dimension governs different purchasing criteria across end-use verticals, from dielectric ratings in live electrical work to weight constraints in aviation maintenance.
Type:
Replacement cycles vary dramatically by jaw mechanism complexity, with self-adjusting variants turning over fastest in high-volume workshop environments.
- Slip Joint:Adjustable pivot point allows jaw opening to scale with fastener diameter, making these the default choice for general mechanical assembly. German automotive suppliers specify these for production line tool cribs where versatility reduces SKU proliferation.
- Needle Nose:Elongated tapered jaws enable access to confined electrical enclosures and jewelry-scale precision work. Demand concentrates in North American electrical contracting where OSHA 1910.269 mandates insulated variants for termination tasks in live panels.
- Locking:Self-adjusting jaw mechanisms with release lever reduce hand fatigue during sustained clamping operations.
- Diagonal:Offset cutting edges optimized for soft wire and cable shearing in electrical installation.
Slip Joint pliers anchor the volume base while Locking variants gain share at the steepest rate.
Material:
Raw material selection directly determines forging cost structures and end-use weight allowances across aviation and portable tool applications.
- Steel:Chrome vanadium and carbon steel alloys deliver Rockwell hardness of 54-62 HRC through induction hardening. Automotive repair workshops in the United States specify these for durability under impact loading.
- Carbon Fiber:Reinforced polymer handles reduce conductive pathways while maintaining structural rigidity.
- Aluminum:Density of 2.7 g/cm³ versus 7.85 g/cm³ for steel enables MRO kit weight reduction. French and German aviation maintenance operations specify these for line-replaceable unit access panels where every kilogram affects fuel burn calculations.
- Plastic:Glass-filled nylon variants serve single-use or corrosion-immune applications in chemical processing environments.
Steel dominates unit economics while Aluminum climbs the fastest in value terms.
Use Case:
Procurement specifications diverge sharply between regulated electrical work and general mechanical service.
- Electrical:Dielectric handle ratings and VDE certification govern purchasing for live circuit work. German utility procurement channels require documented 1,000V AC withstand testing under IEC 60900.
- Automotive:Fleet aging in the United States and Germany extends tool replacement cycles for locking and slip joint variants in independent repair shops.
- Construction:High-leverage jaw designs predominate for rebar tying and formwork fastening.
- General Purpose:Unspecified duty cycles drive volume through retail hardware channels.
Automotive anchors the volume base while Electrical gains share fastest on regulatory tailwinds.
Handle Type:
Ergonomics and safety certification create price-tier separation in commercial and industrial channels.
- Insulated:Dual-layer construction with inner structural core and outer dielectric coating rated to 1,000V AC. OSHA compliance mandates these for US utility and electrical contracting procurement.
- Ergonomic:Bi-material overmolding reduces repetitive strain injury risk in high-volume assembly operations.
- Non-slip:Textured rubber or thermoplastic elastomer grips improve control in oil-contaminated environments.
- Straight:Uncoated metal handles serve lowest-cost retail segments and controlled-environment applications.
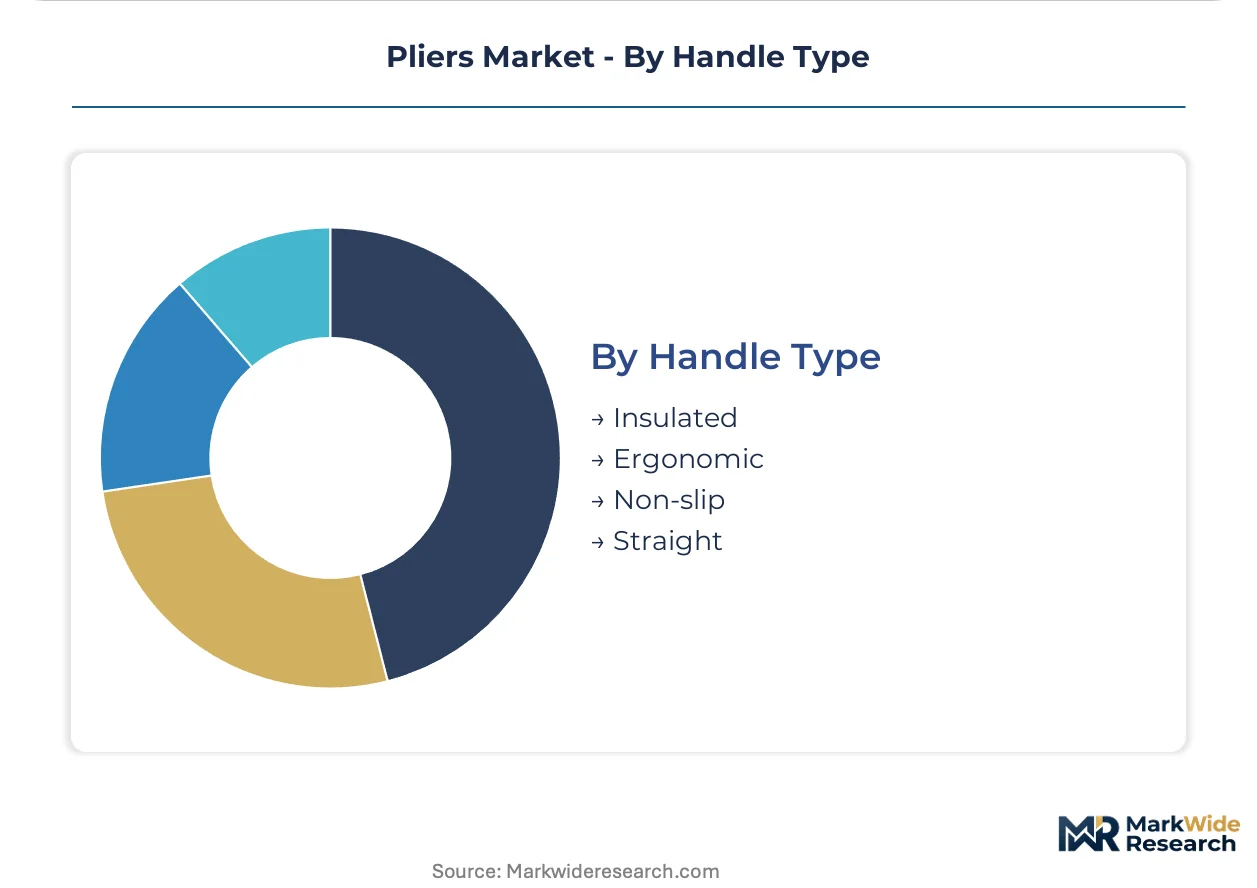
Straight handles anchor the volume base while Insulated variants expand most quickly on safety regulation tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows from Chinese forging clusters dominate global trade balances, while import demand concentrates in automotive-repair-intensive economies. Germany and the United States absorb premium-grade locking pliers for aged fleet maintenance. India's infrastructure electrification is opening new procurement channels for insulated-handle variants.
United States
Automotive repair workshops in California and Texas drive replacement cycles for locking and slip joint pliers as vehicle fleet age exceeds 12 years. OSHA 1910.269 mandates dielectric handle ratings for live electrical work, compressing supplier qualification to UL-certified manufacturers. Milwaukee and Chicago anchor distribution networks serving independent workshop groups consolidating purchases through national parts chains.
Germany
Precision-ground jaw geometries command premium positioning in electrical termination and automotive assembly tool cribs. REACH Annex XVII restrictions on hexavalent chromium plating force electroplating line relocations to CSRD-aligned facilities. Solingen's forging heritage sustains captive heat-treatment capacity for Rockwell 58-62 HRC cutting edges serving French and German aviation MRO buyers.
China
Zhejiang and Guangdong provinces concentrate locking plier volume for export markets, creating single-geography exposure for global distributors. GB standards and MIIT industrial policy guide alloy steel sourcing for chrome vanadium feedstock. Ningbo and Wenzhou manufacturing clusters supply mid-tier forging operations competing on cost structures against precision-forging specialists.
India
National highway and rail electrification projects under CEA safety codes expand procurement for insulated-handle pliers compliant with 1,000V AC withstand testing. Maharashtra and Gujarat infrastructure buildout channels demand through state-level contractor registration systems. Pune and Ahmedabad industrial zones host forging operations serving domestic automotive OEM tool crib specifications.
France
Aviation MRO operations at Toulouse and Paris-Charles de Gaulle specify aluminum alloy pliers for line-replaceable unit access panels where weight reduction governs fuel cost calculations. ECHA enforcement of REACH plating restrictions accelerates zinc-nickel coating validation through accelerated corrosion testing. Lyon-based industrial distributors document coating chemistry for downstream automotive and energy clients under tightening ESG disclosure rules.
Pliers Market Competitive Landscape
On the supply side, the industry is tiered between precision-forging specialists with captive heat-treatment capacity and mid-tier operations dependent on outsourced surface engineering. Consolidation pressure favors manufacturers with backward integration into alloy steel sourcing and in-house electroplating lines. Three archetypes dominate: premium-grade precision specialists, scale-driven cost competitors, and regional private-label suppliers. Competitive moves concentrate on M&A to secure captive forging capacity and strategic partnerships with industrial distributor platforms.
Among precision-forging specialists, Apex Tool Group and Knipex Tools exemplify premium-tier positioning through controlled cost structures and precision-ground jaw geometries. Klein Tools anchors utility-sector procurement channels where insulated handle specifications dominate purchasing criteria. These three represent the archetype of manufacturers leveraging captive technical capabilities to defend margin position against mid-tier competitors.
| Leading Market Players |
|---|
| Apex Tool Group |
| Klein Tools |
| Knipex Tools |
| Snap-on |
| Channellock |
| Irwin Tools |
| Akar Tools |
| CHISEN Tools |
| Park Tool |
| Others |
Value Network & Pricing Analysis
Zhejiang and Guangdong forging clusters dictate downstream pricing power through chrome vanadium steel sourcing leverage and captive electroplating capacity. Mid-tier manufacturers in Wenzhou and Ningbo compress margins for precision-forging specialists by competing on cost structures rather than ISO 5743 certification premiums.
Pricing Analysis
Gradient-hardened cutting edges command 15-25% premiums over conventional monolithic heat-treated variants, while aluminum alloy aviation-grade pliers price at 40-60% above steel equivalents. Pricing stratifies across premium, standard, and economy tiers based on VDE/UL certification status and jaw geometry tolerances. Cost compression in mid-tier locking pliers is intensifying because Chinese export capacity expansion outpaces German and US workshop demand growth. Independent automotive repair shops exhibit highest price sensitivity, while aviation MRO procurement channels prioritize weight reduction over unit cost.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for North American distributors sourcing locking plier variants. Production gravity centers on Zhejiang and Guangdong provinces for forged components, with Germany's Solingen cluster retaining precision-ground specialty output. Raw material sourcing draws from chrome vanadium feedstock suppliers in China and nickel-molybdenum alloy producers in Russia and South Africa. Distribution runs through integrated supplier platforms displacing traditional two-step industrial distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pliers market is entering a cyclical recovery phase driven by automotive fleet aging extending tool replacement cycles in German and US workshop channels.
For Market Incumbents: Insulate margin position by deepening backward integration into captive heat-treatment capacity and securing CSRD-aligned electroplating certifications before European ESG disclosure deadlines tighten. Precision-forging specialists must defend against mid-tier Chinese competitors by accelerating gradient-hardening technology deployment and locking in multi-year procurement contracts with aviation MRO buyers.
For New Entrants and Emerging Players: Pursue white-space opportunities in Indian insulated-handle pliers serving CEA-compliant highway and rail electrification projects, where domestic forging capacity lags infrastructure buildout timelines. Direct-to-workshop digital procurement platforms in California and Texas offer the most penetrable channel entry point, with private-label SKU development for national parts chains representing the optimal go-to-market angle.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-forging specialists with captive alloy steel sourcing and in-house VDE certification capabilities over asset-light mid-tier competitors. Long-term viability through the next decade rests on securing aviation MRO procurement relationships and CSRD-compliant coating process documentation. The critical inflection signal to monitor is REACH Annex XVII enforcement accelerating zinc-nickel coating validation timelines for European industrial distributors.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Heat-Treatment Capacity Expansion | Secures Rockwell 58-62 HRC cutting edge consistency for aviation MRO specifications. |
| Zinc-Nickel Coating Line Relocation | Aligns electroplating operations with CSRD disclosure requirements for European distributor qualification. |
| Gradient Hardness R&D Investment | Enables titanium and Inconel fastening work for French and German aerospace buyers. |
| Direct-to-Workshop Platform Partnership | Bypasses traditional distributor margins in California and Texas automotive repair consolidation. |
| CEA Safety Code Certification | Unlocks procurement channels for Indian highway and rail electrification infrastructure projects. |
Research Methodology
Initial hypotheses were tested against primary input from forging plant managers, automotive workshop procurement leads, aviation MRO technical buyers, and industrial distributor category managers and refined through secondary validation against customs trade data, SEC filings from listed tool manufacturers, ISO certification registries, and REACH Annex XVII compliance databases. Bottom-up demand modeling from end-use verticals was triangulated against top-down supply capacity assessments across Chinese, German, and Indian forging clusters.
Demand-supply-balance dynamics across the analysis window were modeled through segmented projections by plier type, material grade, handle specification, and end-use vertical, with CAGRs derived from regression analysis of replacement cycle data and fleet age demographics. Forecast inputs incorporated chrome vanadium steel price volatility indices, OSHA 1910.269 enforcement patterns, and aviation MRO weight reduction procurement mandates.
Sensitivities concentrate around alloy steel feedstock cost fluctuations, REACH plating restriction enforcement timelines, and Chinese export capacity expansion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Fiber Laser Cutting Machines Market
Tools
Industrial Plate Bending Machines Market
Tools
Lathe Machines Market
Tools
US Hitter Based Hand Tools Market
Tools
Vinyl Bending Machine Market
Tools
Gear Hobbing Cutter Market
Tools
Electric Power Tools Market
Tools
Mallets and Sledgehammers Market
Tools
Painting Tools Market
Tools
Industrial Floor Scrubber Market
Tools
Tape Measure Market
Tools
Rocket Wrench Market
Tools
Portable Pressure Washer Market
Tools
Concrete Saw Market
Tools
Woodworking Circular Saw Blades Market
Tools
Surface Planer Market