
 Thermal Spray Equipment Market | 2026-2036
Thermal Spray Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Thermal Spray Equipment Market Outlook
Modular equipment bundling is shifting buyer choice in the thermal spray equipment landscape, as end-users favor integrated systems combining powder feed units, robotic motion platforms, and real-time process monitoring over standalone torch purchases. Oerlikon Metco leverages its vertical integration across consumables and automation to capture recurring revenue streams. Lincoln Electric anchors its position through dense distribution networks in heavy manufacturing regions. Kennametal differentiates via carbide-based feedstock formulations tailored for extreme wear applications.
Thermal spray equipment encompasses systems that heat and accelerate metallic or ceramic materials onto substrates to build protective coatings, typically operating at particle velocities exceeding 300 m/s for HVOF configurations and deposition temperatures ranging from ambient to 16,000°C for plasma processes. The technology serves primarily to extend component life in corrosive, erosive, or thermally stressed environments across capital-intensive industries. Plasma spray technology leads the product type landscape due to its versatility across ceramic and metallic feedstocks, while cold spray represents the fastest-expanding segment as solid-state deposition avoids oxidation and phase transformation in temperature-sensitive substrates. Powder feed technology commands the dominant technology position, though wire feed systems retain strongholds in high-volume automotive underbody and infrastructure corrosion protection where cost-per-kilogram metrics govern procurement.
FAA airworthiness directives for turbine engine hot-section components mandate rigorous coating qualification protocols that elevate equipment precision requirements and barrier-to-entry thresholds for new market participants. EPA NESHAP standards for hazardous air pollutants from surface coating operations restrict traditional flame spray deployments, redirecting capital toward closed-loop HVOF and inert-gas plasma systems that capture overspray and reduce hexavalent chromium exposure. OSHA permissible exposure limits for metalworking fluids and airborne particulates further shape shop-floor equipment specifications, particularly in US-based job shops serving aerospace and energy OEMs. Stakeholders must monitor evolving ISO 14918 certification requirements for thermally sprayed coatings, as accreditation breadth increasingly determines contract eligibility for Tier 1 and Tier 2 suppliers in consolidated supply chains.
Market Dynamics
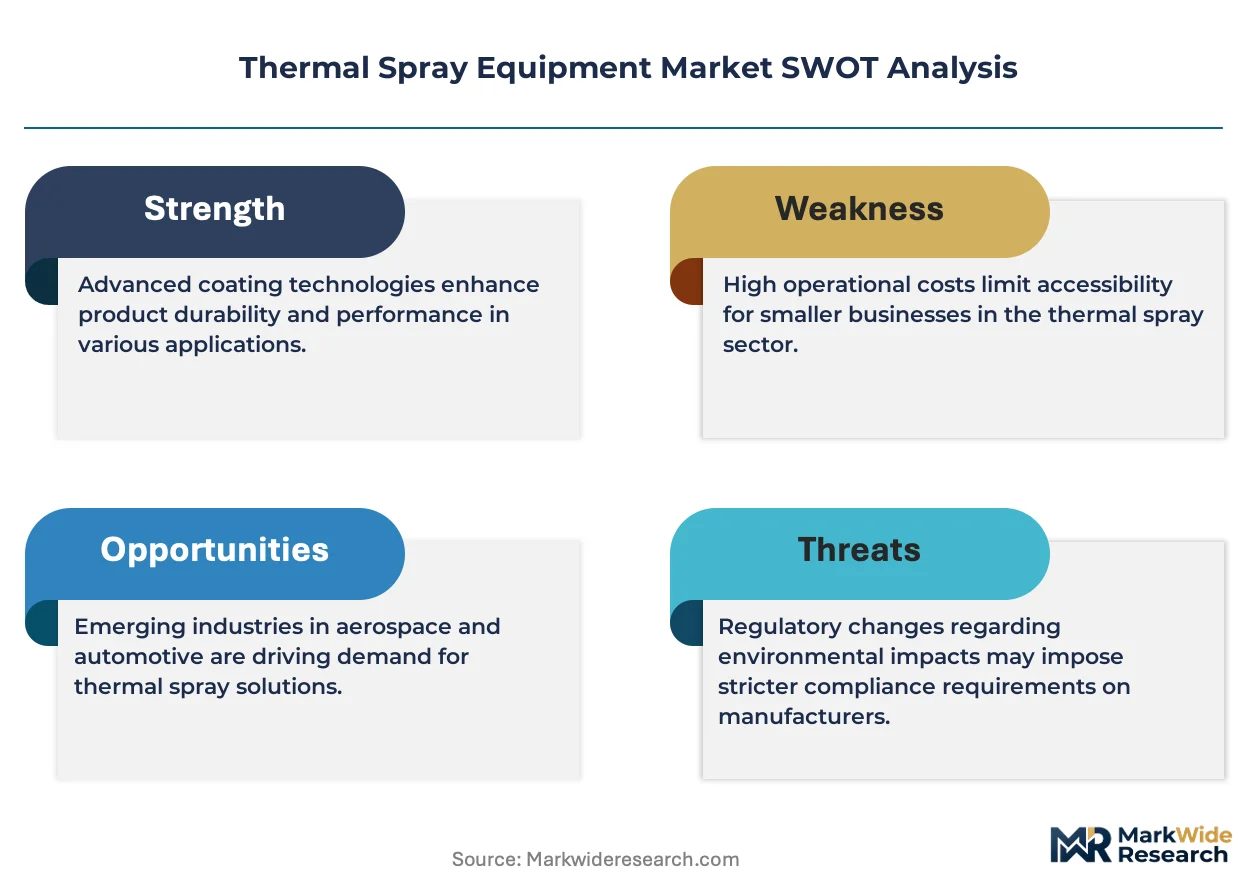
Equipment replacement cycles are compressing as aerospace OEMs and automotive suppliers confront EPA NESHAP emissions deadlines and FAA coating qualification mandates simultaneously. The collision of environmental compliance and airworthiness precision is forcing capital allocation toward closed-loop HVOF and inert-gas plasma configurations that satisfy both regulatory regimes.
Growth Catalysts
- FAA Airworthiness Directives:Turbine engine hot-section component mandates elevate equipment precision requirements, expanding demand for plasma spray systems capable of depositing thermal barrier coatings that meet rigorous qualification protocols.
- Germany's Precision Manufacturing Corridor:Automotive suppliers and energy component fabricators co-locate with specialized coating service providers, creating dense equipment demand clusters that favor automated, high-throughput thermal spray installations.
- Cold Spray Technology Maturation:Solid-state deposition avoids oxidation and phase transformation in temperature-sensitive substrates, opening applications in electronics and medical device manufacturing previously closed to thermal spray processes.
Market Restraints
- Helium Supply Concentration:Plasma spray operations depend on helium for inert-gas shielding; supply disruptions from Qatar and the US federal helium reserve create input cost volatility and operational uncertainty for coating job shops.
- Capital Intensity Thresholds:Closed-loop HVOF systems with integrated overspray capture and hexavalent chromium filtration require capital outlays that exclude smaller Tier 3 suppliers from EPA-compliant equipment procurement.
- Laser Cladding Substitution:Directed energy deposition technologies compete for wear-protection applications in oil and gas components, threatening thermal spray market share in high-value repair and remanufacturing segments.
Strategic Opportunities
- India's Defense Industrial Base:Indigenous aerospace engine programs and naval shipbuilding create underpenetrated demand for thermal barrier coating capacity, with BIS standards evolving to accommodate advanced thermal spray qualifications.
- Wire-Arc Spray Automation:Convergence of robotic motion platforms with real-time arc monitoring enables high-volume automotive underbody coating at cost-per-kilogram metrics competitive with liquid paint systems.
- EU Green Deal Industrial Funding:Decarbonization incentives for remanufacturing and component life extension redirect capital toward thermal spray repair technologies as alternatives to virgin material production.
Industry Challenges
- ISO 14918 Certification Timelines:Accreditation breadth increasingly determines contract eligibility for Tier 1 and Tier 2 suppliers, yet certification bodies face backlogs that delay market entry for equipment vendors and coating service providers alike.
- Process Control Specialist Scarcity:Real-time monitoring of particle velocity, temperature, and trajectory requires cross-trained technicians fluent in both materials science and automation engineering, a skill combination concentrated among aging workforce cohorts in the US and Germany.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermal Spray Equipment Market |
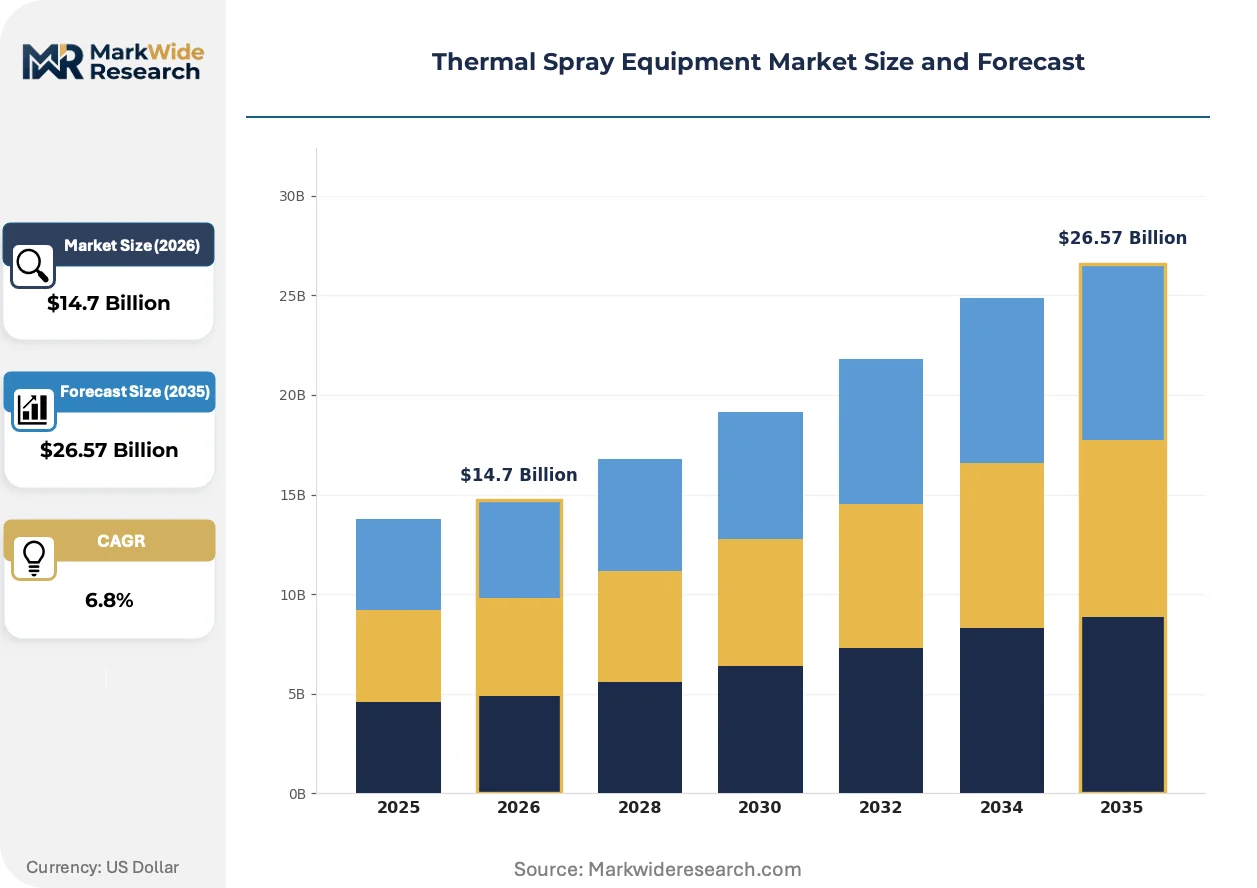
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasma Spray, Flame Spray, HVOF, Cold Spray End User: Aerospace, Automotive, Energy, Manufacturing Technology: Wire Feed, Powder Feed, High Velocity Oxy-Fuel, Rotary Application: Coatings, Repair, Wear Resistance, Thermal Barrier |
| Companies Covered | Linde, Oerlikon Metco, Saint Gobain, Curtiss-Wright, Hoganas, Kennametal, Bodycote, Lincoln Electric, AMETEK Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermal Spray Equipment Market Strategic Shifts
Digital thread integration is redefining how thermal spray equipment generates, captures, and validates process data. The shift from torch-centric purchases to fully instrumented coating cells is compressing equipment procurement cycles while elevating software and sensor content in vendor value propositions.
Real-time process monitoring hardware is integrating with cloud-based coating qualification databases to enable predictive parameter adjustment during deposition. Aerospace OEMs in the US and France are deploying these systems for turbine blade thermal barrier coating to satisfy FAA and EASA traceability requirements. The technology is integrating quality assurance directly into production workflows, reducing post-process inspection bottlenecks.
EPA NESHAP standards for hazardous air pollutants from surface coating operations are redirecting capital toward closed-loop HVOF configurations that capture overspray and eliminate hexavalent chromium exposure. Job shops serving aerospace and energy OEMs face equipment replacement deadlines that favor inert-gas plasma systems with integrated filtration. The regulation is forcing consolidation among smaller US-based coating service providers unable to absorb compliance-related capital outlays.
After-sales service unbundling is fragmenting traditional equipment vendor relationships as end-users seek specialized third-party calibration and maintenance providers. German automotive suppliers and Japanese precision manufacturers are separating equipment procurement from long-term service contracts, pressuring OEM margins. This pattern is most visible in North Rhine-Westphalia and Nagoya industrial clusters where coating service providers operate dense equipment fleets across multiple vendor platforms.
Thermal Spray Equipment Market Segmentation
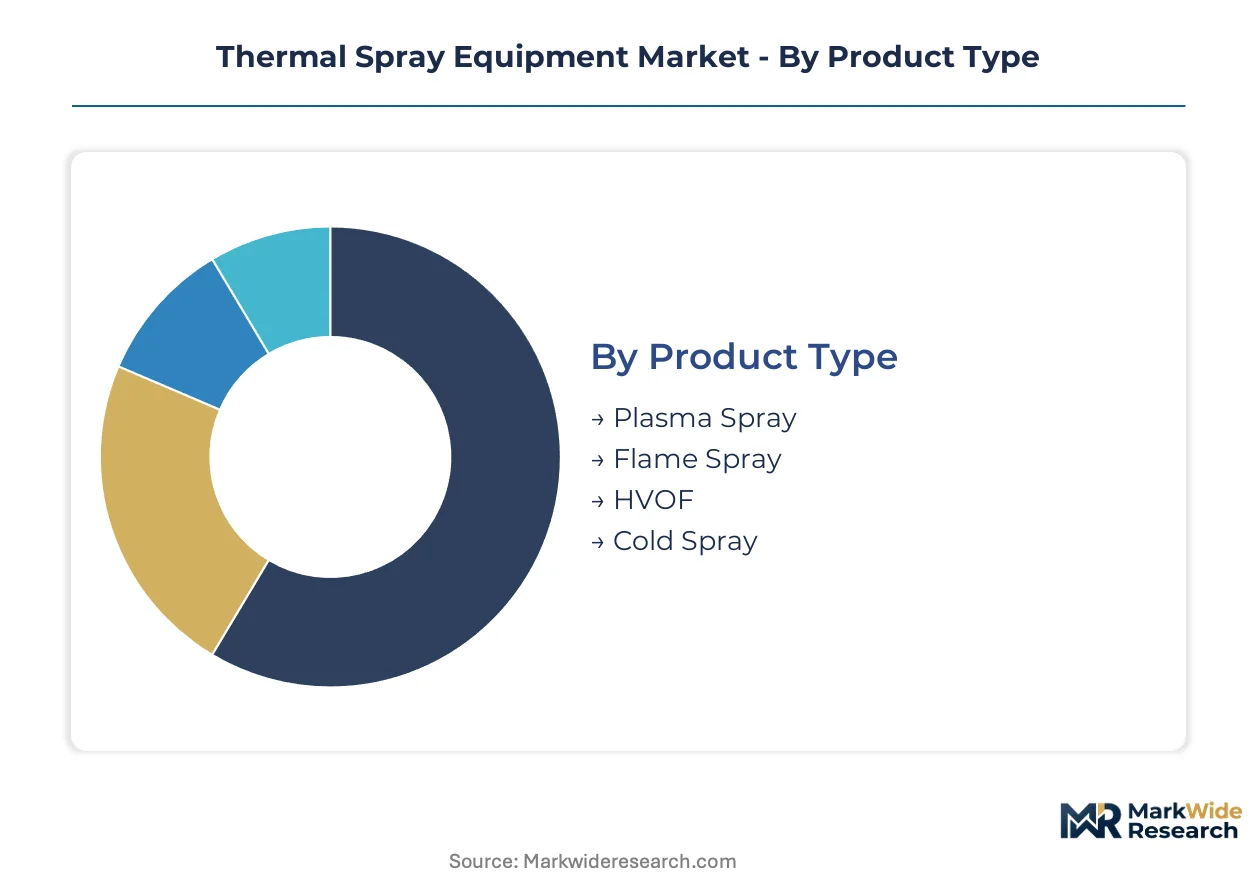
Thermal spray equipment segmentation reveals distinct technology-performance trade-offs that govern procurement decisions across capital-intensive industries. Equipment specifications directly determine coating deposition rates, substrate compatibility, and regulatory compliance thresholds.
Product Type:
Deposition temperature and particle velocity define the technical axis for equipment selection across aerospace, energy, and precision manufacturing applications.
- Plasma Spray:Operates at temperatures reaching 16,000°C using inert-gas plasma arcs to melt ceramic and metallic feedstocks. FAA airworthiness directives for turbine blade thermal barrier coatings concentrate demand in US and French aerospace OEM facilities where qualification protocols mandate precise temperature control and repeatable deposition parameters.
- HVOF:Accelerates particles through supersonic combustion flames exceeding 300 m/s velocity. EPA NESHAP emissions standards are redirecting capital toward closed-loop HVOF configurations with integrated overspray capture, particularly among US-based job shops serving energy component fabricators.
- Flame Spray:Conventional oxy-fuel combustion systems for lower-cost corrosion protection applications.
- Cold Spray:Solid-state deposition at ambient temperatures avoids oxidation and phase transformation. Electronics and medical device manufacturers in Germany's precision manufacturing corridor are adopting cold spray for temperature-sensitive substrates previously excluded from thermal spray applications.
Mature deployment sits with plasma spray systems in established aerospace supply chains. Newer deployment is concentrated in cold spray configurations serving electronics and medical device manufacturing.
End User:
Component life extension requirements and regulatory exposure determine equipment procurement intensity across vertical markets.
- Aerospace:Turbine engine hot-section components require thermal barrier coatings meeting FAA and EASA qualification protocols. OEMs in the US and France deploy plasma spray systems with real-time process monitoring to satisfy traceability mandates for next-generation blade architectures.
- Automotive:Underbody corrosion protection and powertrain component wear resistance drive high-volume wire-arc installations. German automotive suppliers in North Rhine-Westphalia favor automated coating cells combining robotic motion platforms with powder feed systems for cost-per-kilogram competitiveness.
- Energy:Gas turbine components and nuclear pressure vessels demand coating precision for extreme thermal and erosive environments.
- Manufacturing:General industrial repair and remanufacturing applications across tooling and machinery sectors.
Capital allocation intensity peaks in aerospace for qualification-critical applications. Volume concentration is strongest in automotive for high-throughput corrosion protection.
Technology:
Feedstock form factor and delivery mechanism govern deposition economics and coating property control.
- Powder Feed:Dominant technology enabling precise metering of ceramic and metallic particulates across plasma and HVOF configurations. Aerospace OEMs specify powder feed systems for thermal barrier coating applications where particle size distribution directly impacts coating porosity and thermal conductivity.
- Wire Feed:Lower-cost metallic deposition for high-volume infrastructure and automotive underbody applications. Japanese precision manufacturers deploy wire-arc automation for cost-competitive corrosion protection at automotive scale.
- High Velocity Oxy-Fuel:Specialized supersonic combustion systems for dense, low-porosity metallic coatings.
- Rotary:Specialized configurations for cylindrical component processing in oil and gas repair operations.
Powder feed systems anchor revenue in aerospace and energy qualification environments. Wire feed automation is expanding fastest in automotive volume applications.
Application:
Functional coating requirements determine equipment specification priorities across repair versus new manufacturing contexts.
- Thermal Barrier:Ceramic coatings for turbine hot-section components operating above metal melting points. FAA airworthiness directives mandate rigorous qualification protocols that elevate equipment precision requirements and consolidate procurement among certified coating service providers.
- Wear Resistance:Carbide and cermet coatings for tooling, mining equipment, and industrial machinery. German energy component fabricators specify HVOF systems for erosion-resistant coatings on gas turbine hardware.
- Coatings:General protective and functional surface treatments across industrial sectors.
- Repair:Component restoration and dimensional restoration for remanufacturing applications.
Thermal barrier coatings command premium equipment specifications for aerospace qualification. Wear resistance applications are diversifying fastest across energy and industrial machinery sectors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States where precision manufacturing and aerospace OEMs anchor equipment demand, while consumption spreads across industrial corridors in Japan and India where coating service providers expand capacity to meet localized component repair needs.
United States
FAA airworthiness directives for turbine engine hot-section components drive plasma spray system procurement among aerospace OEMs in Connecticut and Ohio. EPA NESHAP emissions standards for hazardous air pollutants redirect capital toward closed-loop HVOF configurations with integrated overspray capture. The Greater Cincinnati industrial cluster hosts dense concentrations of coating job shops serving energy component fabricators confronting compliance deadlines.
Germany
Automotive suppliers and energy component fabricators in North Rhine-Westphalia generate sustained demand for automated thermal spray installations. EU Green Deal industrial funding for remanufacturing and component life extension redirects capital toward repair-focused coating technologies. The precision manufacturing corridor spanning Cologne, Düsseldorf, and Dortmund co-locates OEMs with specialized coating service providers operating high-throughput powder feed systems.
Japan
Wire-arc spray automation for automotive underbody corrosion protection drives equipment procurement among precision manufacturers in Aichi Prefecture. METI industrial standards for surface treatment processes elevate equipment qualification requirements for export-oriented suppliers. The Nagoya industrial cluster concentrates robotic coating cell deployments where cost-per-kilogram metrics govern high-volume procurement decisions.
India
Indigenous aerospace engine programs and naval shipbuilding create underpenetrated demand for thermal barrier coating capacity in Bengaluru and Hyderabad. BIS standards are evolving to accommodate advanced thermal spray qualifications for defense industrial base suppliers. The Maharashtra-Gujarat industrial corridor attracts coating service providers targeting remanufacturing opportunities in power generation and oil and gas sectors.
France
EASA traceability requirements for turbine blade coatings sustain plasma spray system demand among aerospace OEMs in the Île-de-France region. REACH regulations on hazardous substance restrictions shape feedstock formulation specifications for coating service providers. The Toulouse aerospace cluster integrates real-time process monitoring hardware to satisfy qualification protocols for next-generation engine architectures.
Thermal Spray Equipment Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across a market structure that consolidates around integrated system vendors while fragmenting among regional coating service equipment providers. Three strategic archetypes dominate: full-line industrial gas and materials conglomerates with captive equipment divisions, specialized thermal spray technology pure-plays with deep process expertise, and diversified welding and fabrication equipment manufacturers extending into automated coating cells. Competitive moves center on backward integration into consumables production and technology licensing partnerships that expand geographic reach without direct capital deployment.
Within the diversified conglomerate tier, Linde and Saint Gobain exemplify players leveraging industrial gas and materials science foundations to anchor equipment offerings. Oerlikon Metco occupies a position representing pure-play specialists with vertical integration across consumables and automation. Lincoln Electric sits within the welding equipment extension archetype, utilizing dense distribution networks in heavy manufacturing regions to penetrate adjacent thermal spray applications. These three company patterns illustrate how vendor strategies diverge based on legacy industrial positioning rather than converging on identical capability builds.
| Leading Market Players |
|---|
| Linde |
| Oerlikon Metco |
| Saint Gobain |
| Curtiss-Wright |
| Hoganas |
| Kennametal |
| Bodycote |
| Lincoln Electric |
| AMETEK Inc. |
| Others |
Value Chain & Pricing Dynamics
EPA NESHAP emissions standards for hazardous air pollutants from surface coating operations gate qualified supply access and premium-tier pricing power, as only equipment vendors with closed-loop HVOF and inert-gas plasma configurations can serve aerospace and energy OEMs confronting compliance deadlines. This regulatory filter concentrates procurement leverage among certified Tier 1 and Tier 2 suppliers while excluding smaller job shops from premium contract eligibility.
Pricing Analysis
Margin tightening in mid-tier equipment reflects helium supply volatility from Qatar and the US federal helium reserve, which elevates operating costs for plasma spray job shops. Three-tier pricing structure across qualification-critical, standard industrial, and economy corrosion-protection levels separates FAA-certified aerospace systems from automotive wire-arc installations. Cost-down pressure on economy-tier flame spray accelerates because EPA NESHAP deadlines force capital migration toward compliant configurations. Automotive underbody coating buyers exhibit highest price sensitivity, while aerospace OEMs prioritize traceability and certification over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's defense industrial base and evolving BIS standards are reshaping sourcing patterns for thermal barrier coating capacity in indigenous aerospace programs. Equipment manufacturing concentrates in Germany, the United States, and Japan, with precision motion platforms and real-time monitoring hardware drawing from specialized automation suppliers in North Rhine-Westphalia and Aichi Prefecture. Helium supply concentration from Qatar and the US federal reserve creates single-source vulnerability for inert-gas plasma operations. Distribution runs through authorized equipment dealers and direct OEM relationships with coating service providers in dense industrial clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA NESHAP emissions standards and FAA airworthiness directives erect barrier-to-entry moats favoring capital-rich incumbents with certified equipment portfolios.
For Market Incumbents: Deepen backward integration into powder feedstock formulations and robotic motion platforms to capture recurring revenue streams and defend against laser cladding substitution in oil and gas repair segments. Expand service unbundling capabilities in German and Japanese industrial clusters where coating service providers separate equipment procurement from long-term maintenance contracts. ISO 14918 certification breadth remains the priority lever for Tier 1 supplier contract eligibility. For New Entrants and Emerging Players: Capture underpenetrated demand in India's defense industrial base where indigenous aerospace engine programs and naval shipbuilding lack qualified thermal barrier coating capacity. Cold spray technology for electronics and medical device manufacturing offers the most penetrable segment given temperature-sensitive substrate requirements previously closed to thermal spray processes. Pursue technology licensing partnerships with established European automation vendors to bypass direct capital deployment barriers. For Investors and Strategic Acquirers: FAA airworthiness directive expansion for next-generation turbine blade architectures is the leading indicator that qualification-critical equipment demand will concentrate among vertically integrated pure-plays with captive consumables production. Long-term viability favors acquisition targets combining powder feedstock manufacturing with automated coating cell integration. Monitor helium supply disruption frequency as the signal for input cost volatility exposure across plasma spray-dependent coating service providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Feedstock | Captures margin from carbide and ceramic formulations for extreme wear aerospace applications. |
| Closed-Loop HVOF System Deployment | Satisfies EPA NESHAP mandates while eliminating hexavalent chromium exposure in US job shops. |
| Cold Spray Technology Licensing | Opens electronics and medical device segments without oxidation risks for temperature-sensitive substrates. |
| Real-Time Process Monitoring Integration | Meets FAA and EASA traceability requirements for turbine blade thermal barrier coatings. |
| Wire-Arc Spray Automation Scale-Up | Targets automotive underbody corrosion protection at cost-per-kilogram competitiveness with liquid paint. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this thermal spray equipment analysis, combining primary interviews with coating service provider operations managers, aerospace OEM procurement leads, plant engineers at energy component fabricators, and thermal spray process specialists with bottom-up and top-down triangulation. Secondary validation drew from EPA NESHAP compliance databases, FAA airworthiness directive filings, ISO 14918 accreditation registries, and equipment import-export documentation from US Census Bureau and Eurostat trade statistics.
Granularity-level modeling deployed separate projections for plasma spray, HVOF, cold spray, and flame spray product types; powder feed versus wire feed technology configurations; and thermal barrier, wear resistance, and corrosion protection applications across aerospace, automotive, energy, and precision manufacturing end-use segments. CAGRs were derived from equipment replacement cycle analysis intersecting regulatory compliance deadlines with technology maturation curves, incorporating helium supply volatility indices and defense industrial base expansion rates as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EPA enforcement intensity, helium reserve privatization decisions, and cold spray technology adoption rates in medical device manufacturing. Forecasts reflect documented assumptions regarding regulatory timeline adherence and technology substitution thresholds. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Crane Aftermarket Market
Construction Equipment
Mobile Elevating Work Platform (MEWP) Market
Construction Equipment
Hydraulic Intensifiers Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Static and Rotating Equipment Market
Construction Equipment
Backhoe Bucket Market
Construction Equipment
Trash Rack Cleaning Machine Market
Construction Equipment
Piles Turner Market
Construction Equipment
India Construction Equipment Market
Construction Equipment
Engine Driven Welders Market
Construction Equipment
Mini Cranes Market
Construction Equipment
LAMEA Stud Welding Machine Market
Construction Equipment
Jib Crane Market
Construction Equipment
Wood Chipping Machinery Market
Construction Equipment
Tower Crane Rental Market
Construction Equipment
Construction Power Rental Market