
 Industrial Belt Drives Market | 2026-2036
Industrial Belt Drives Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Belt Drives Market Outlook
The capital-intensity gap between integrated manufacturers and component assemblers is collapsing as precision molding and aramid cord technology become table stakes. Gates Industrial Corp. Plc leverages captive rubber compounding to sustain margin structures across heavy-duty V-belt lines. Mitsuboshi Belting Ltd. anchors its position through proprietary tooth-profile patents in synchronous drive systems. Schaeffler AG differentiates via integrated condition-monitoring packages that bundle belt drives with sensor-enabled pulley assemblies.
Industrial belt drives transmit mechanical power between rotating shafts through friction or positive engagement, typically employing elastomeric compounds reinforced with polyester, aramid, or glass fiber cords and operating within temperature ranges from minus thirty to plus one hundred twenty degrees Celsius. These systems reduce vibration, accommodate misalignment, and enable speed ratio flexibility across manufacturing equipment. V-belts retain the largest installed base due to retrofit compatibility and low replacement cost, though timing belts are gaining share in precision packaging machinery where synchronous motion control eliminates slip losses. Flat belts occupy niche positions in high-speed textile and paper processing lines where wrap-angle efficiency exceeds wrapped V-belt performance.
OSHA machine-guarding standards in the United States mandate physical enclosure of belt drive assemblies, increasing demand for compact, enclosed belt systems that simplify compliance. REACH and RoHS frameworks in Europe restrict hazardous substance content in rubber compounds, compelling compounders to reformulate adhesion promoters and anti-degradant packages. The EU F-Gas Regulation indirectly shapes belt specifications by driving HVAC equipment efficiency targets that favor optimized drive ratios. Stakeholders must monitor how polymer price volatility and evolving efficiency certifications reshape sourcing strategies for reinforced elastomer components.
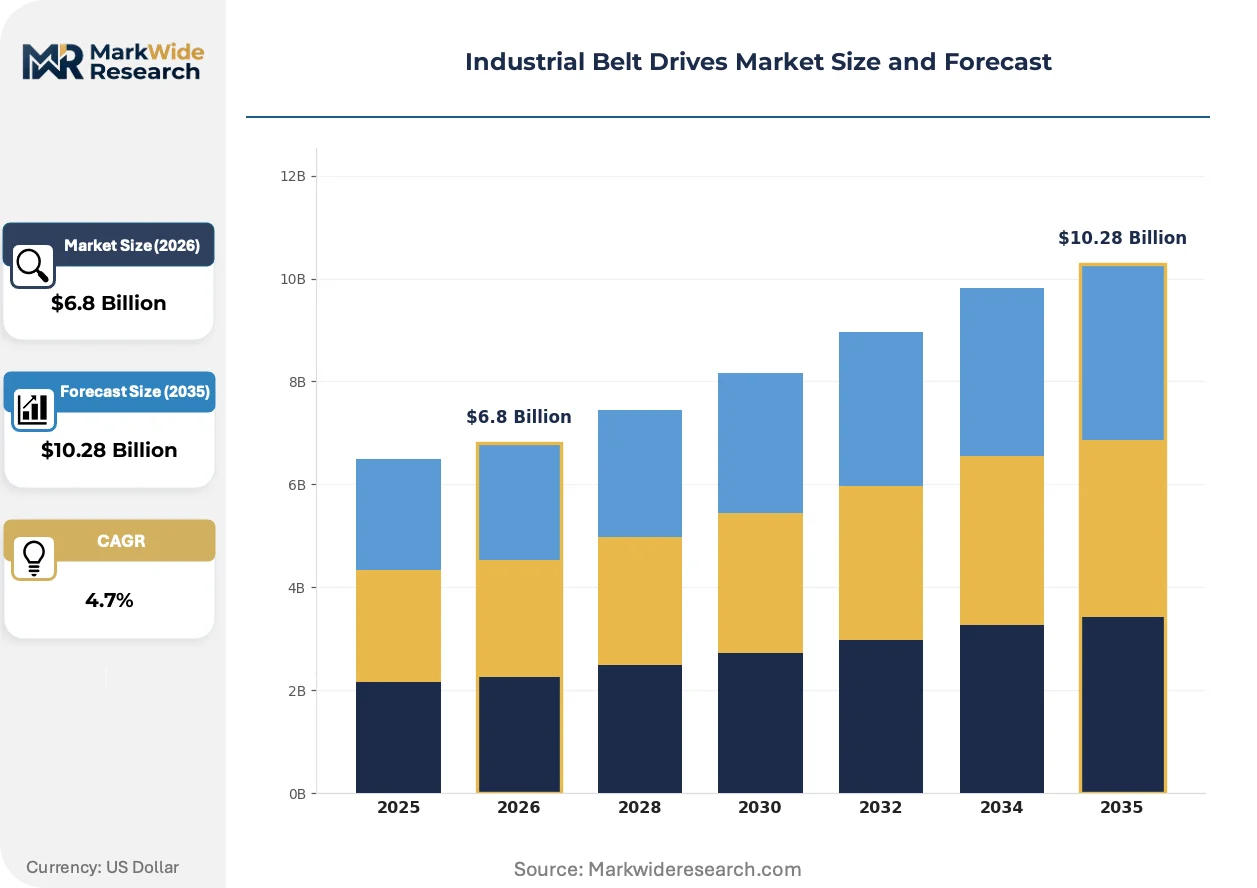
Market Dynamics
Aramid-reinforced synchronous belt systems are compressing the performance gap between friction drives and precision gearboxes, forcing incumbent V-belt suppliers to defend installed bases through material upgrades and service bundling.
Growth Catalysts
- EU F-Gas Regulation:HVAC equipment efficiency mandates in Germany and France are accelerating replacement cycles for optimized drive ratios in compressor systems.
- Mining procurement:Australian bulk material operations are expanding conveyor belt drive orders to match iron ore and coal export capacity additions.
- Ruhr industrial cluster modernization:Automotive and machinery producers across North Rhine-Westphalia are retrofitting legacy drive trains with synchronous systems.
Market Restraints
- Natural rubber price volatility:Compounders face margin compression when Thai and Indonesian latex supply fluctuates with monsoon patterns.
- Specialized cord supply concentration:High-tenacity aramid fiber production concentrates among three chemical conglomerates, creating single-source risk for tier-two belt manufacturers.
- REACH substance restrictions:ECHA's evolving candidate list forces reformulation of adhesion promoters, extending R&D validation timelines by 8-14 months.
Strategic Opportunities
- Condition-monitoring integration:Sensor-enabled pulley assemblies that predict belt wear are opening premium service contracts in food processing and pharmaceutical packaging.
- OSHA compliance simplification:Compact enclosed belt systems that satisfy machine-guarding standards without custom fabrication are capturing retrofit demand in US metalworking shops.
- Textile machinery speed demands:High-speed flat belt configurations for Korean and Taiwanese synthetic fiber lines represent an underpenetrated precision segment.
Industry Challenges
- Compound formulation expertise:REACH-compliant rubber chemistry requires polymer scientists with dual competence in elastomer mechanics and regulatory toxicology, a skill set concentrated among retiring European specialists.
- Legacy system integration:Synchronous belt retrofits into 1970s-era machine tools demand custom pulley machining and shaft alignment protocols that extend commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Belt Drives Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: V-Belts, Timing Belts, Flat Belts, Rubber Belts Application: Material Handling, Packaging Machinery, Conveyor Systems, HVAC Equipment End User: Manufacturing, Food & Beverage, Mining, Automotive Technology: Mechanical, Electronic, Hydraulic, Pneumatic |
| Companies Covered | AB SKF, Gates Industrial Corp. Plc, Mitsuboshi Belting Ltd., Bando Chemical Industries Ltd., Schaeffler AG, The Timken Co., Dayco IP Holdings LLC, Optibelt GmbH, MEGADYNE S.P.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Belt Drives Market Strategic Shifts
Material science advances and regulatory efficiency mandates are converging to redraw competitive boundaries between friction-based and positive-engagement power transmission architectures.
Carbon fiber tensile cords are displacing traditional polyester and glass fiber reinforcements in heavy-duty synchronous belts rated above 50 kW. Mining equipment OEMs in Western Australia specify these configurations for overland conveyors operating in 50°C ambient conditions. The shift is compressing replacement intervals while opening premium pricing tiers for suppliers with captive carbon fiber supply arrangements.
REACH and RoHS frameworks are compelling European compounders to eliminate cobalt-based adhesion promoters and certain anti-degradant packages from rubber formulations. Belt manufacturers serving German automotive tier-ones must now validate alternative chemistries through accelerated aging protocols that add 6-9 months to qualification cycles. The regulatory pressure is most acute in synchronous timing belts for engine camshaft drives, where failure modes carry warranty liability exposure.
Maintenance departments at US manufacturing plants are unbundling belt replacement from comprehensive service contracts, instead procuring direct from distributors with in-house predictive maintenance capabilities. This disintermediation is compressing distributor margins while rewarding regional players with localized inventory and same-day technical support. The pattern is most visible in Chicago-Milwaukee industrial corridors, where metal fabrication and food processing density supports dedicated belt specialists.
Industrial Belt Drives Market Segmentation
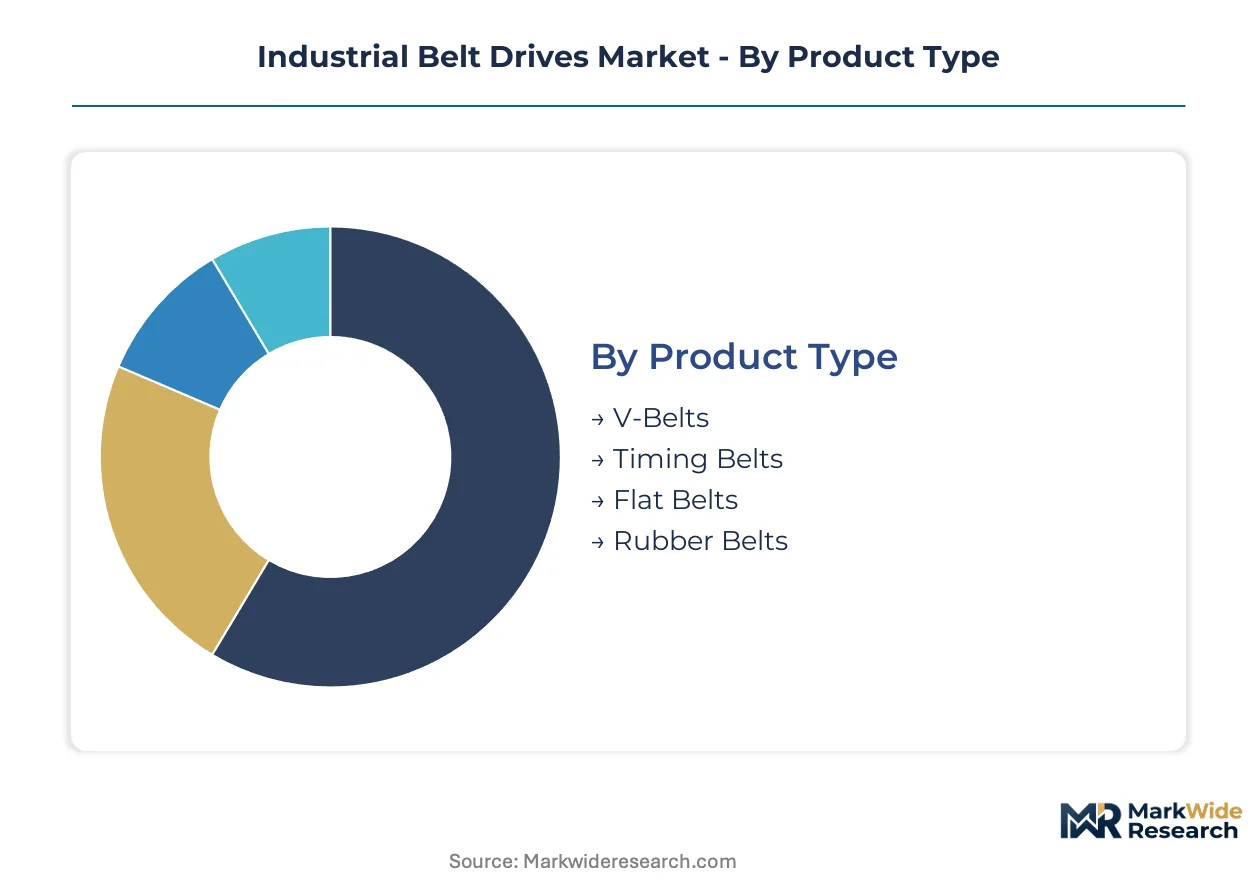
Belt drive procurement patterns diverge sharply between maintenance-led replacement cycles and OEM specification decisions. Understanding where each segment concentrates helps suppliers align inventory depth with actual demand velocity.
Product Type:
V-belts dominate domestic aftermarket channels across German, French, and US industrial corridors. Timing belt demand concentrates in export-oriented precision machinery OEMs serving East Asian packaging and automotive markets.
- V-Belts:Trapezoidal cross-section elastomeric belts with polyester or aramid cord reinforcement tolerate misalignment and shock loading. Demand concentrates in US metalworking and Midwest manufacturing maintenance departments where retrofit compatibility preserves installed pulley investments. OSHA machine-guarding compliance costs favor enclosed V-belt configurations over open alternatives.
- Timing Belts:Synchronous toothed belts with glass fiber or carbon fiber tensile cords eliminate slip through positive engagement. German automotive tier-ones and Ruhr machinery OEMs specify these for camshaft drives and precision positioning axes where angular accuracy prevents warranty exposure. REACH-compliant compound reformulation extends qualification timelines.
- Flat Belts:Thin-profile elastomer or leather-composite belts achieve high wrap-angle efficiency at speeds exceeding V-belt limits. Korean and Taiwanese synthetic fiber textile lines represent concentrated demand pockets.
- Rubber Belts:General-purpose constructions using natural rubber or SBR compounds serve cost-sensitive bulk material handling in Australian mining conveyors.
V-belts command the established base. The steepest expansion runs through timing belts.
Application:
Material handling applications cluster in heavy-industry geographies with bulk commodity export exposure. Packaging machinery demand tracks pharmaceutical and food processing investment waves in regulated markets.
- Material Handling:Heavy-duty belt drives for cranes, hoists, and bulk transport equipment operate under intermittent shock loading. Australian iron ore and coal export capacity additions drive procurement concentration. Natural rubber price volatility compresses compounder margins during monsoon supply disruptions.
- Packaging Machinery:Synchronous belt systems for filling, sealing, and labeling equipment demand precise motion control. German pharmaceutical packaging OEMs specify REACH-validated compounds to satisfy ECHA substance restrictions. Predictive maintenance integration opens premium service contract opportunities.
- Conveyor Systems:Continuous-duty belt drives for bulk material and unit handling span mining, warehousing, and distribution. Carbon fiber cord configurations penetrate Western Australian overland conveyor specifications.
- HVAC Equipment:Fan and compressor drive systems face EU F-Gas Regulation efficiency mandates. German and French equipment OEMs optimize drive ratios to meet tightening energy standards.
Material handling absorbs the largest equipment investment. Packaging machinery offers the highest margin expansion trajectory.
End User:
Manufacturing end-users distribute demand across mature industrial economies with legacy equipment bases. Mining procurement concentrates in commodity-exporting geographies with capacity expansion cycles.
- Manufacturing:General machinery, metal fabrication, and industrial equipment producers span Chicago-Milwaukee corridors and German industrial clusters. Maintenance departments increasingly disintermediate distributors through direct procurement with predictive analytics capabilities.
- Food & Beverage:Processing and packaging operations demand FDA-compliant belt materials with documented cleanability. US dairy and meat processing regions specify enclosed belt systems satisfying OSHA guarding standards without custom fabrication.
- Mining:Bulk material operations in Western Australia specify heavy-duty synchronous configurations for overland conveyors. Carbon fiber tensile cords rated above 50 kW displace traditional reinforcements in 50°C ambient conditions.
- Automotive:Engine camshaft drives and accessory systems require synchronous timing belts with validated failure modes. German OEMs impose extended qualification protocols for REACH-compliant adhesion promoters.
Manufacturing represents the deepest installed base. Mining demonstrates the most aggressive specification upgrading.
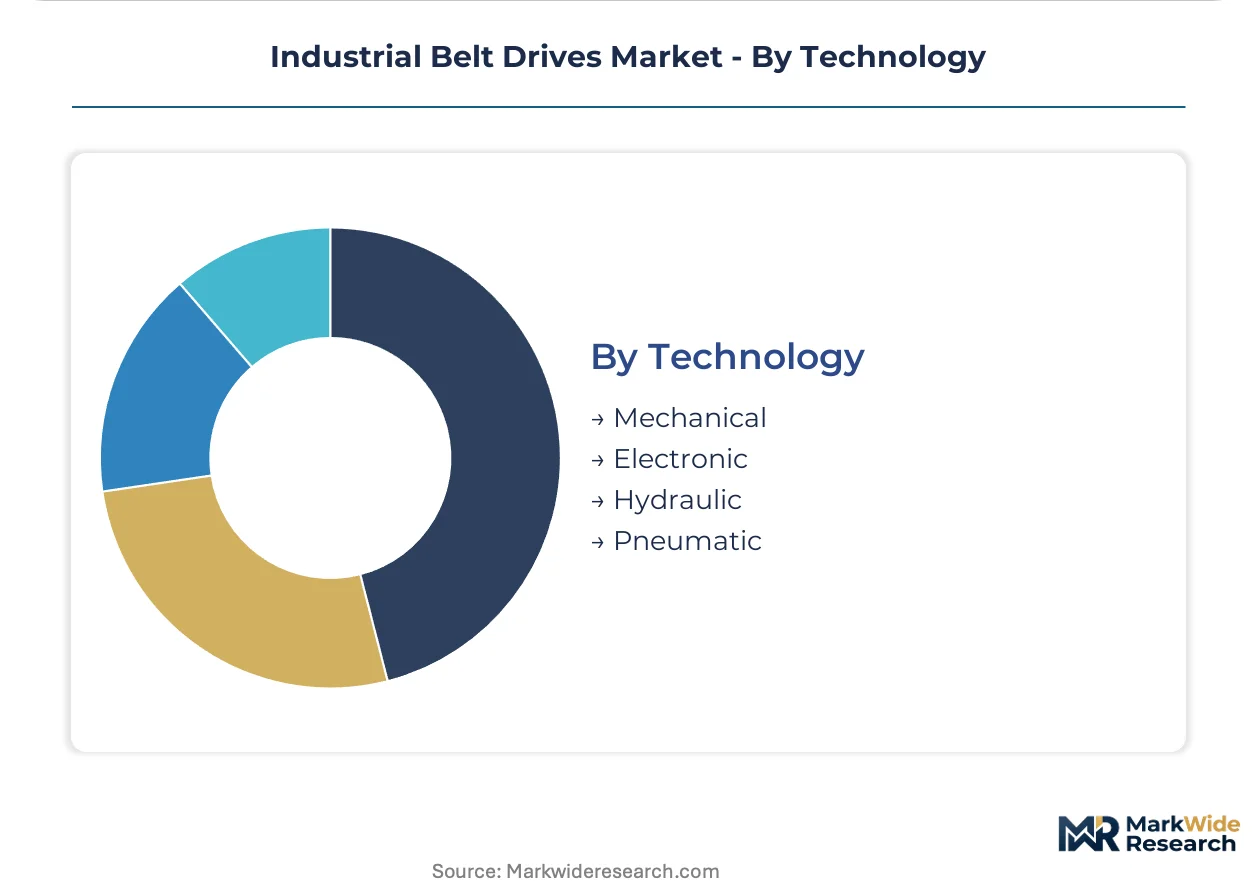
Technology:
Mechanical belt drives retain dominance across cost-sensitive retrofit markets. Electronic and hydraulic alternatives penetrate precision applications where motion control complexity justifies capital investment.
- Mechanical:Friction and positive-engagement belt systems without external power or control interfaces. V-belt and synchronous configurations span 90% of installed industrial base across US, German, and Australian operations.
- Electronic:Sensor-integrated belt systems with condition-monitoring capabilities predict wear and alignment drift. Schaeffler's integrated pulley assemblies exemplify this segment's premium positioning in food processing and pharmaceutical packaging.
- Hydraulic:Fluid-power actuation for tensioning and variable-speed belt drives serves specialized heavy-equipment applications with extreme load variation.
- Pneumatic:Compressed-air tensioning and clutching mechanisms occupy niche positions in explosive-atmosphere environments where electrical ignition risks dominate specification criteria.
Mechanical systems anchor volume. Electronic integration captures value expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australian mining buyers absorb specification upgrades with limited price elasticity, while US metalworking maintenance departments negotiate aggressively on V-belt replacement cycles. German automotive tier-ones occupy the middle ground, trading margin for REACH-compliant validation security.
Germany
Ruhr industrial cluster machinery OEMs and automotive tier-ones drive synchronous belt procurement for camshaft and precision positioning applications. EU F-Gas Regulation efficiency mandates accelerate HVAC compressor drive ratio optimization. North Rhine-Westphalia's belt manufacturers face extended qualification timelines for REACH-compliant adhesion promoter reformulations.
United States
Chicago-Milwaukee metal fabrication corridors and food processing belts sustain V-belt aftermarket volume through retrofit compatibility priorities. OSHA machine-guarding standards elevate demand for enclosed belt configurations that simplify compliance without custom fabrication. Midwest maintenance departments increasingly disintermediate distributors through direct procurement partnerships with predictive analytics capabilities.
Australia
Western Australian iron ore and coal export capacity expansions drive heavy-duty synchronous belt orders for overland bulk material conveyors. Carbon fiber tensile cord configurations penetrate specifications for 50°C ambient operating conditions. Mining equipment OEMs specify premium configurations that compress replacement intervals while opening higher pricing tiers.
South Korea
Synthetic fiber textile machinery producers in Gyeonggi and Busan-Ulsan industrial zones demand high-speed flat belt configurations exceeding V-belt velocity limits. KOSHA occupational safety frameworks parallel OSHA guarding requirements for enclosed drive systems. Domestic machinery OEMs export precision packaging equipment to pharmaceutical markets requiring synchronous motion control.
Japan
Kanto and Chubu regional automotive component suppliers specify timing belts with validated failure mode documentation for engine camshaft drives. METI energy efficiency guidelines shape industrial equipment procurement specifications favoring optimized drive ratios. Yokohama-based belt manufacturers maintain proprietary tooth-profile patents in synchronous systems.
Industrial Belt Drives Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with integrated compounders commanding material science premiums while regional assemblers compete on logistics proximity. The vendor base organizes into three tiers: captive rubber compounders with backward integration into polymer supply, precision molding specialists with proprietary cord-treatment processes, and distribution-anchored assemblers serving maintenance-led replacement cycles. Dominant competitive moves include M&A targeting condition-monitoring capabilities and geographic expansion into Australian mining procurement corridors.
Among European-integrated manufacturers, Schaeffler AG exemplifies the sensor-enabled pulley assembly archetype, while Optibelt GmbH occupies a position within precision synchronous belt specialization. Gates Industrial Corp. Plc represents the captive compounding model with sustained margin structures across heavy-duty lines. Mitsuboshi Belting Ltd. anchors the Japanese proprietary technology tier through tooth-profile patent positions. These three archetypes—integrated electronics, precision synchronous specialization, and captive material science—define the competitive vectors reshaping procurement relationships with German automotive tier-ones and Australian mining OEMs.
| Leading Market Players |
|---|
| AB SKF |
| Gates Industrial Corp. Plc |
| Mitsuboshi Belting Ltd. |
| Bando Chemical Industries Ltd. |
| Schaeffler AG |
| The Timken Co. |
| Dayco IP Holdings LLC |
| Optibelt GmbH |
| MEGADYNE S.P.A |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day compound qualification timelines for REACH-compliant adhesion promoters concentrate pricing power among European compounders with captive polymer science capabilities, while Asian assemblers without backward integration face persistent margin compression during natural rubber supply disruptions. This lead-time asymmetry stratifies procurement relationships: German automotive tier-ones absorb premium validation costs for synchronous belt specifications, whereas US metalworking maintenance departments negotiate aggressively on V-belt replacement cycles.
Pricing Analysis
After-market service contracts and predictive maintenance subscriptions now drive lifetime value more than initial equipment sales. Three-tier pricing structure across premium carbon fiber synchronous systems, standard aramid-reinforced configurations, and economy polyester V-belts reflects certification grade and cord technology differentiation. Pricing pressure stems from maintenance departments disintermediating distributors through direct procurement partnerships. US metalworking buyers exhibit highest price sensitivity; Australian mining OEMs show least elasticity for specification upgrades.
Supply Chain Analysis
Inventory compression to thirty-to-forty-five days among tier-two belt manufacturers signals just-in-time vulnerability to aramid fiber supply disruptions. Manufacturing concentrates in Germany, Japan, and Thailand; carbon fiber cord sources from US and Japanese chemical conglomerates. The supply chain draws from natural rubber plantations in Thailand and Indonesia, aramid fiber production among three global suppliers, and specialized rubber compounding equipment concentrated in European industrial clusters. Single-source vulnerability in high-tenacity cord supply creates structural risk. Distribution runs through regional distributors with localized inventory and technical support capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial belt drive incumbents face substitution defense against precision gearbox and direct-drive motor technologies that aramid-reinforced synchronous systems only partially offset. The imperative is securing specification lock-in through compound science differentiation and embedded service contracts.
For Market Incumbents: Compound proprietary rubber formulations with REACH-validated adhesion chemistry to extend qualification timelines that freeze out challengers. Anchor specification positions through integrated condition-monitoring packages that bundle sensor-enabled pulley assemblies with predictive maintenance subscriptions. Carbon fiber cord supply arrangements with Japanese chemical conglomerates defend against tier-two competitors lacking backward integration.
For New Entrants and Emerging Players: CE marking fast-track for enclosed belt configurations satisfying OSHA machine-guarding standards without custom fabrication opens retrofit demand in US metalworking corridors. Target South Korean synthetic fiber textile machinery producers with high-speed flat belt configurations exceeding V-belt velocity limits. Partner with regional distributors possessing predictive analytics capabilities to bypass incumbent service relationships.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because compound formulation expertise concentrates among retiring European polymer scientists with dual competence in elastomer mechanics and regulatory toxicology. Acquisition targets include precision molding specialists with proprietary cord-treatment processes and electronic integration capabilities for sensor-enabled pulley assemblies. Watch carbon fiber cord adoption rates in Western Australian mining specifications as inflection indicator for premium tier expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rubber Compounding | Gates Industrial's captive compounding sustains margin structures across heavy-duty V-belt lines. |
| Proprietary Tooth-Profile Patent Development | Mitsuboshi Belting anchors Japanese market position through synchronous drive system differentiation. |
| Condition-Monitoring Integration | Schaeffler bundles sensor-enabled pulley assemblies with belt drives for pharmaceutical packaging premium. |
| REACH-Compliant Compound Reformulation | European compounders validate alternative adhesion promoters through extended aging protocols. |
| Carbon Fiber Cord Supply Arrangement | Mining OEMs in Western Australia specify premium configurations for 50°C ambient conveyor operations. |
Study Parameters
Operator-level perspectives from maintenance directors at US metalworking plants, OEM procurement teams in Germany's Ruhr cluster, and aftermarket service heads at Australian mining operations anchored the qualitative base. Secondary validation drew from SEC 10-K filings of listed belt manufacturers, ECHA substance restriction updates, and customs trade data on natural rubber and aramid fiber imports. Bottom-up demand modeling across end-use segments triangulated with top-down market sizing from equipment installation bases.
Sensitivity analysis tested forecast robustness against natural rubber price volatility scenarios and REACH candidate list expansion timelines. Segmentation dimensions spanned product type, application, end user, and technology integration level across the projection horizon. CAGRs derived from equipment replacement cycle analysis, capacity expansion announcements in Australian mining, and efficiency mandate implementation schedules in EU member states. Carbon fiber cord penetration rates and predictive maintenance adoption curves served as industry-specific forecast inputs.
Underlying assumptions cover stable monsoon patterns in Southeast Asian rubber plantations and gradual REACH substance restriction implementation, with deviation risk concentrated in aramid fiber supply disruptions and accelerated direct-drive motor substitution. Forecasts reflect these conditions without scenario-weighting. Revision becomes warranted when carbon fiber cord cost curves cross polyester reinforcement thresholds or when EU F-Gas Regulation efficiency mandates accelerate beyond modeled compressor system replacement cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Vertical Lift Module (VLM) Market
Material Handling Equipment
Dynamic Compactor Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Heavy Hex Nuts Market
Material Handling Equipment
Construction Lifts Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Precision Gearbox Machinery Market
Material Handling Equipment
Autonomous Material Handling Equipment Market
Material Handling Equipment
Industrial Hoists Market
Material Handling Equipment
Vapor Blasting Equipment Market
Material Handling Equipment
Air Classifying Mill Market
Material Handling Equipment
Automated Material Handling (AMH) Equipment Market
Material Handling Equipment
Decoiler Machine Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
Hydraulic Cylinder Rod Market