
 Hydraulic Tools Market | 2026-2036
Hydraulic Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Hydraulic Tools Market Intelligence
North American forging houses and cylinder foundries are recalibrating capacity toward high-pressure alloy components. Enerpac Tool Group Corp. leverages its century-old pedigree in controlled force technology to dominate infrastructure maintenance channels. Atlas Copco North America LLC anchors the mining and construction segments through integrated power solutions. LUKAS Hydraulik GmbH specializes in rescue and industrial applications where compact force delivery matters.
Hydraulic tools transmit force through confined fluid pressure, typically operating between 700 bar and 3,000 bar depending on application severity, with piston-seal integrity determining cycle life. Their primary purpose spans heavy lifting, precision fastening, and structural deformation in industrial settings. Hydraulic torque wrenches command premium positioning in the product mix due to calibration-critical applications in energy and aerospace. Among end users, aerospace manufacturing exhibits the steepest specification escalation as airframe assembly tolerances tighten. Manual technology retains volume leadership in field service, though hybrid electric-hydraulic systems capture the fastest growth in fixed-plant environments.
OSHA mandates govern portable hydraulic press safety in US workplaces, while the EU Machinery Directive imposes CE conformity on force-generating equipment sold across member states. Japan's METI enforces JIS B 8366 standards for hydraulic cylinders, creating compliance costs for exporters. Stakeholders must monitor how carbon-border adjustments and embedded-emissions tracking reshape sourcing decisions for cast-iron pump housings and chrome-plated rods.
Market Dynamics
Electrification mandates from the EPA are forcing OEMs to redesign hydraulic power units around battery-electric architectures, compressing the traditional internal-combustion supply base while opening procurement channels for high-voltage actuator specialists.
Growth Catalysts
- EPA Tier 4 Final emissions standards:Off-road equipment manufacturers must retrofit or replace diesel-driven hydraulic systems, accelerating demand for electrified power packs in construction and agriculture.
- Aerospace torque calibration protocols:Airframe assembly tolerances now require closed-loop hydraulic wrench systems with real-time pressure feedback, pulling precision tool demand upward.
- Germany's automotive manufacturing corridor:Assembly operations in Stuttgart, Wolfsburg, and Munich require synchronized multi-point fastening systems for EV battery tray installation.
Market Restraints
- Chrome-plated rod supply concentration:Foundry capacity for high-pressure cylinder rods clusters in Eastern European and Chinese steel districts, exposing buyers to alloy price volatility and logistics bottlenecks.
- Cast-iron pump housing lead times:Sand-casting facilities in India and Brazil face energy cost spikes that extend OEM procurement cycles by 8-14 weeks.
- Pneumatic tool substitution in light assembly:Compressed-air systems retain cost advantages below 500 bar operating pressure, limiting hydraulic penetration in consumer goods manufacturing.
Strategic Opportunities
- Wind turbine maintenance fleets:Offshore installations in the North Sea and Baltic coast require portable hydraulic torque systems for blade bolt tensioning in corrosive environments.
- EU Green Deal embedded-emissions tracking:Carbon-border adjustments favor suppliers with documented low-carbon casting processes, creating first-mover advantages for certified foundries.
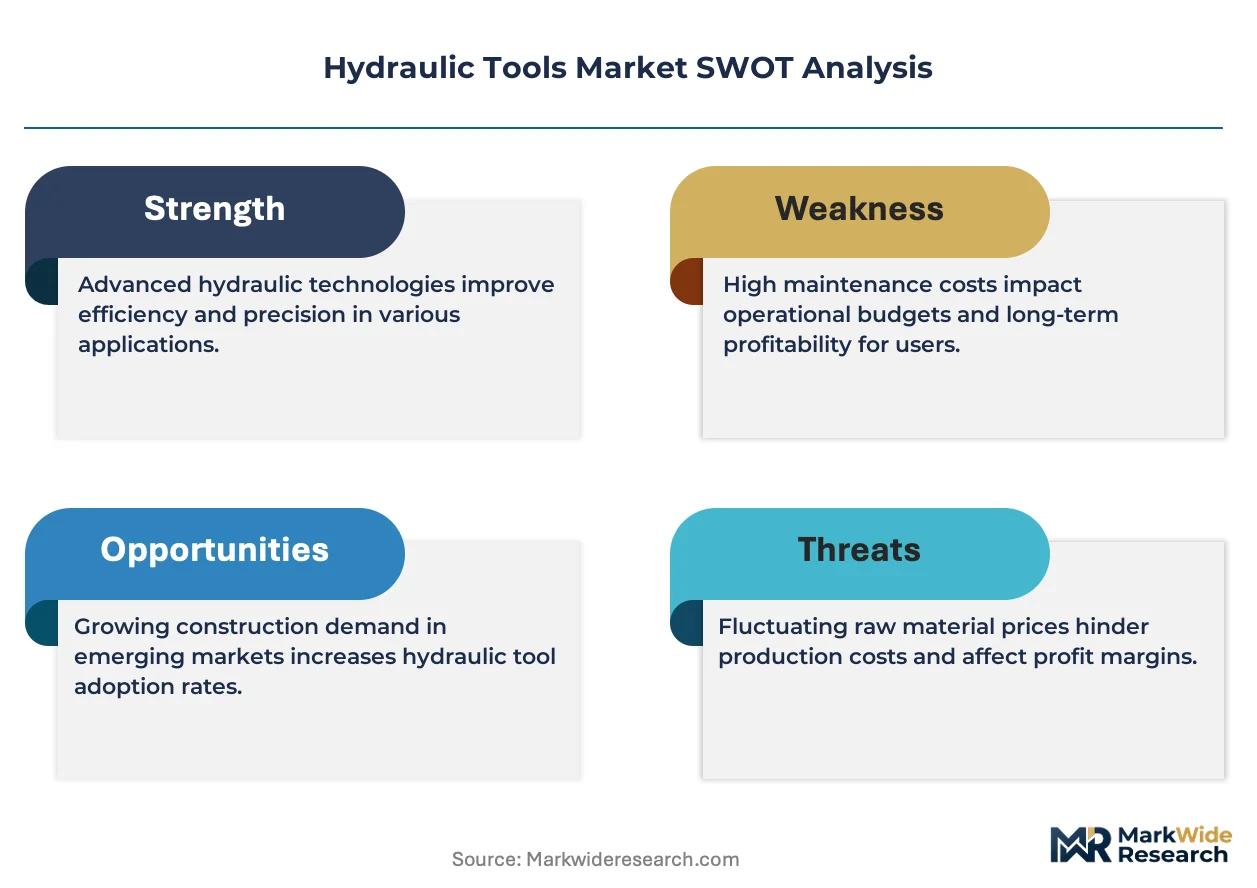
- Telematics-enabled predictive maintenance:Sensor-integrated hydraulic tools allow rental fleet operators to monetize usage data and shift from unit sales to subscription models.
Industry Challenges
- High-pressure seal technician shortage:Compound elastomer specification and piston groove machining require skills that vocational programs in North America and Western Europe have deprioritized.
- CE Machinery Directive certification timelines:Third-party conformity assessment for force-generating equipment now averages 14-18 months, delaying product launches.
- Legacy pneumatic infrastructure integration:Fixed-plant customers face capital write-downs when retrofitting electric-hydraulic systems into existing compressed-air distribution networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydraulic Tools Market |
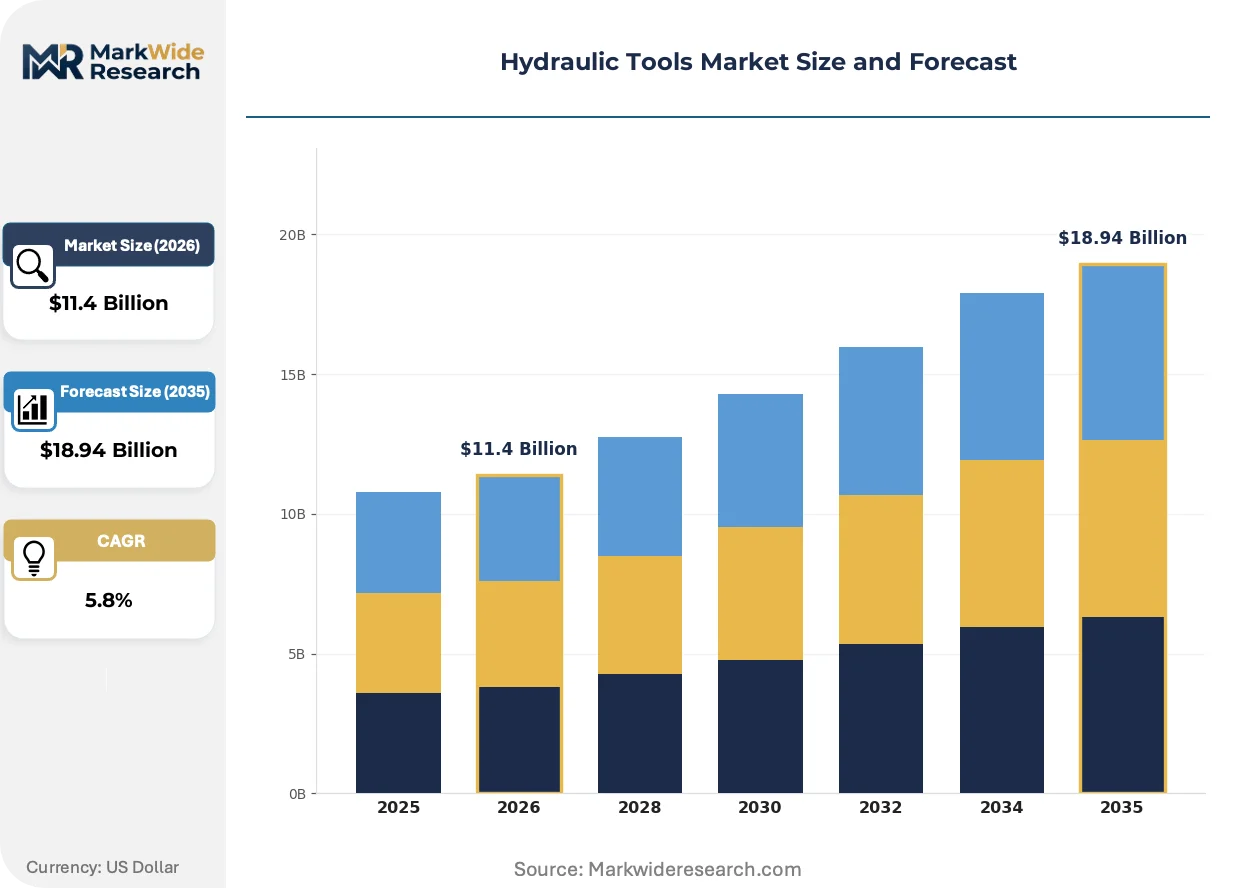
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Jacks, Hydraulic Pumps, Hydraulic Cylinders, Hydraulic Torque Wrenches End User: Construction, Manufacturing, Automotive, Aerospace Application: Heavy Lifting, Pipe Bending, Engine Repair, Assembly Operations Technology: Manual, Electric, Pneumatic, Hybrid |
| Companies Covered | Atlas Copco North America LLC, BVA Hydraulics, Cembre S.p.A., Emerson Electric Co., Enerpac Tool Group Corp., Hi-Force Limited, HTL Group Ltd., LUKAS Hydraulik GmbH, SPX Flow Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydraulic Tools Market Strategic Shifts & Innovations
Intelligent force control and embedded sensing are compressing the gap between manual field tools and automated plant systems, with regulatory pressure and buyer procurement discipline accelerating the transition.
Electro-hydraulic actuation is consolidating position in fixed-plant environments where precision and repeatability outweigh portability requirements. Automotive battery assembly lines in Germany and South Korea now specify servo-controlled hydraulic presses with sub-millimeter positional accuracy. This architecture is consolidating maintenance contracts and spare parts pools around integrated mechatronic suppliers rather than discrete component vendors.
REACH restrictions on chromium VI compounds in surface treatments are forcing cylinder manufacturers to migrate toward plasma-transferred arc coatings and laser-clad alternatives. The industrial consequence is elevated coating equipment capital requirements and tighter supplier qualification windows. High-pressure agricultural and construction equipment sold into EU member states faces the most acute compliance timeline pressure.
Equipment-as-a-service contracting is displacing outright purchase in North American energy maintenance channels. Mid-size pipeline contractors now lease calibrated torque wrench systems with bundled recertification and field support. This pattern is most visible in Texas and Alberta, where volatile project cadence makes fixed asset ownership economically unattractive.
Hydraulic Tools Market Segmentation
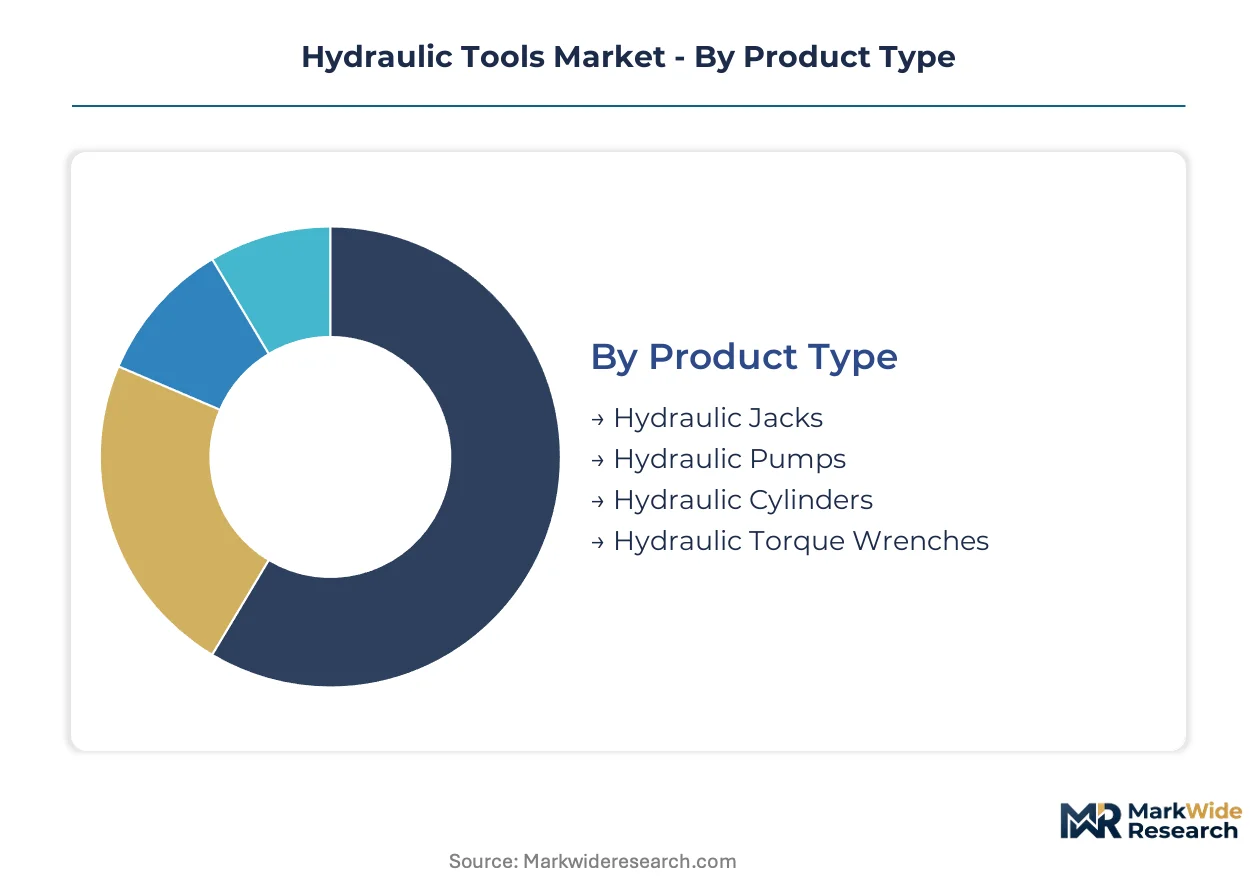
Segmentation in hydraulic tools reflects divergent buyer priorities across capital intensity, precision requirements, and mobility constraints. Procurement patterns split sharply between fixed-plant automation investments and portable field-service equipment.
Product Type:
Buyer selection hinges on force magnitude, cycle frequency, and calibration criticality rather than unit cost alone.
- Hydraulic Torque Wrenches:Closed-loop pressure feedback systems deliver calibrated fastening force for critical bolted joints. Aerospace assembly lines in Germany and energy infrastructure contractors in Texas concentrate procurement here, driven by specification escalation in airframe tolerances and pipeline integrity mandates.
- Hydraulic Pumps:Power units convert mechanical energy into pressurized fluid flow, with electrified architectures displacing diesel-driven variants under EPA Tier 4 Final pressure. OEMs in construction and agriculture face forced retrofit cycles, compressing lead times for high-voltage actuator integration.
- Hydraulic Cylinders:Linear actuators with chrome-plated rods and compound elastomer seals dominate heavy lifting applications; foundry capacity constraints in Eastern Europe and China expose buyers to alloy price volatility.
- Hydraulic Jacks:Portable lifting devices retain volume leadership in field service and maintenance channels; manual technology persists where electrical infrastructure is absent.
Volume sits with hydraulic cylinders; growth tilts toward hydraulic torque wrenches.
End User:
Capital deployment cycles and regulatory exposure differentiate buyer segments more than operational scale.
- Aerospace:Airframe assembly tolerances now demand real-time pressure feedback and closed-loop calibration protocols, pulling specification escalation fastest in this segment. Stuttgart and Hamburg manufacturing clusters anchor European demand.
- Automotive:EV battery tray installation requires synchronized multi-point fastening systems; assembly corridors in Germany and South Korea specify servo-controlled precision.
- Construction:Infrastructure retrofitting drives procurement of portable torque systems; North American contractors face compressed project cadence that favors rental over ownership models.
- Manufacturing:Fixed-plant environments capture hybrid electric-hydraulic adoption where repeatability outweighs portability; pneumatic substitution limits penetration below 500 bar.
Construction commands installed base volume; aerospace exhibits the steepest specification trajectory.
Application:
Force delivery geometry and access constraints shape tool configuration more than raw load capacity.
- Assembly Operations:Multi-point synchronization systems dominate automotive and aerospace fastening; precision requirements exclude manual alternatives in certified production environments.
- Heavy Lifting:Structural deformation and load positioning applications favor hydraulic cylinders with hardened alloy rods; wind turbine maintenance fleets in the North Sea require corrosion-resistant portable systems.
- Pipe Bending:Conduit and pipeline fabrication demands controlled radial force application; energy contractors in Alberta and Texas concentrate demand for calibrated field equipment.
- Engine Repair:Maintenance, repair, and overhaul operations retain manual tool penetration where electrical supply is unreliable; aviation MRO facilities excepted.
Heavy lifting anchors revenue scale; assembly operations climb fastest on automation investment.
Technology:
Power source selection reflects the trade-off between precision control and field mobility.
- Hybrid:Electric-hydraulic architectures consolidate in fixed-plant environments where sub-millimeter positional accuracy justifies capital intensity; automotive battery lines in Germany and South Korea specify these systems exclusively.
- Manual:Human-powered pumps and wrenches retain cost advantages in remote field service; infrastructure maintenance in developing economies sustains volume.
- Electric:Battery-driven units face EPA emissions pressure as diesel replacements; high-voltage actuator specialists gain procurement access previously closed to traditional suppliers.
- Pneumatic:Compressed-air systems defend position below 500 bar operating pressure; legacy infrastructure in consumer goods manufacturing limits hydraulic displacement.
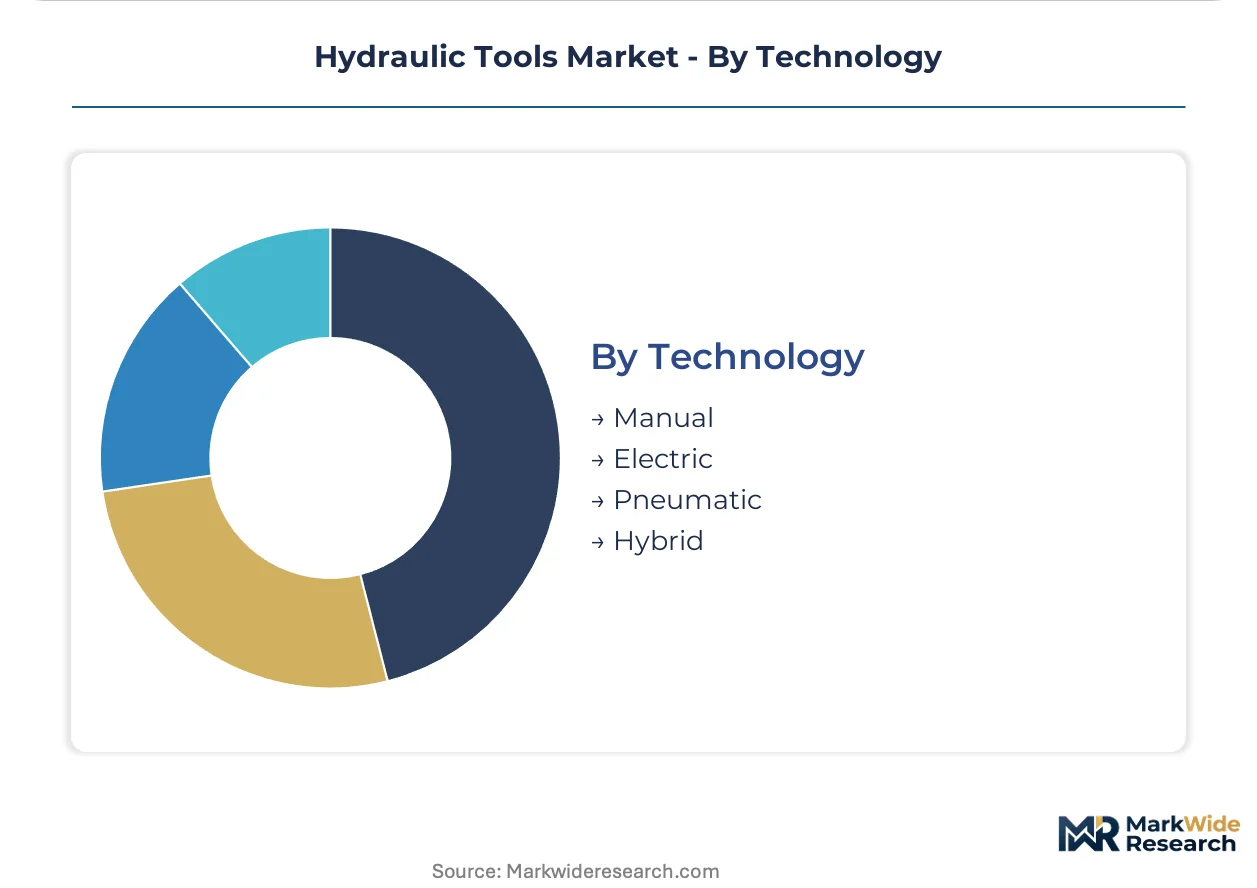
Manual technology holds volume leadership; hybrid systems expand most quickly in controlled environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chrome-plated rod foundry capacity clusters in Eastern European and Chinese steel districts, conditioning procurement patterns for hydraulic cylinder manufacturers worldwide. Regional demand splits between infrastructure retrofitting in mature economies and industrial capacity expansion in emerging manufacturing corridors.
United States
Infrastructure retrofitting drives demand for portable torque systems among pipeline contractors in Texas and Alberta-facing maintenance fleets. OSHA mandates govern portable hydraulic press safety in workplaces, elevating compliance costs for domestic fabricators. Houston anchors energy-sector procurement, where volatile project cadence accelerates rental-over-ownership contracting models.
Germany
Automotive battery tray installation requires synchronized multi-point fastening systems across Stuttgart, Wolfsburg, and Munich assembly corridors. The EU Machinery Directive imposes CE conformity on force-generating equipment, compressing third-party assessment timelines. Baden-Württemberg manufacturing clusters specify servo-controlled precision for EV production lines.
China
Construction equipment OEMs face compressed lead times for high-voltage actuator integration under domestic dual carbon goals. GB standards and MIIT regulations shape hydraulic power unit redesign requirements. Yangtze River Delta foundries supply cast-iron pump housings, though energy cost spikes extend procurement cycles.
Japan
Precision torque equipment demand concentrates in aerospace and automotive sub-assembly operations. METI enforces JIS B 8366 standards for hydraulic cylinders, creating certification barriers for imported components. Nagoya manufacturing corridors anchor closed-loop calibration protocol adoption.
India
Infrastructure development drives hydraulic jack and cylinder procurement for construction and mining applications. BIS standards govern equipment safety certification, while PLI scheme incentives attract component manufacturing investment. Maharashtra industrial corridors concentrate forging and fabrication capacity expansion.
Hydraulic Tools Market Key Industry Players
Global majors compete with regional champions across technology tiers and geographic coverage, producing a tiered structure where scale-driven integrators, precision specialists, and regional fabricators occupy distinct competitive spaces. Market concentration varies by product category, with torque wrench systems showing tighter vendor consolidation than commodity cylinders. Three archetypes dominate: century-old controlled-force technology houses, integrated power solution providers, and compact-force delivery specialists. Competitive moves center on electrification partnerships for battery-electric power packs and predictive maintenance platform development.
Among North American-based providers, Atlas Copco North America LLC and Enerpac Tool Group Corp. occupy positions anchoring infrastructure maintenance and controlled-force technology segments respectively. LUKAS Hydraulik GmbH exemplifies the compact-force specialist archetype with German GmbH structure. These three represent the geographic and structural diversity of the vendor base, spanning integrated power solutions, precision calibration systems, and rescue-industrial applications where portability determines specification.
| Leading Market Players |
|---|
| Atlas Copco North America LLC |
| BVA Hydraulics |
| Cembre S.p.A. |
| Emerson Electric Co. |
| Enerpac Tool Group Corp. |
| Hi-Force Limited |
| HTL Group Ltd. |
| LUKAS Hydraulik GmbH |
| SPX Flow Inc. |
| Others |
Cost & Logistics Intelligence
Energy-sector rental fleets in Texas and Alberta concentrate procurement decisions around bundled recertification contracts rather than unit-acquisition models, compressing transactional pricing for standalone torque wrench systems while elevating lifetime service-revenue multiples for integrated suppliers.
Pricing Analysis
Warranty and field-service bundling separates premium-tier suppliers from economy competitors, with calibration-critical aerospace applications demanding comprehensive maintenance contracts. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 17025 certification status, alloy-grade specifications, and geographic service density. Cost compression in standard-tier hydraulic pumps is intensifying because electrified power pack retrofit cycles compress OEM margins. Construction contractors exhibit highest price sensitivity due to volatile project cadence, while aerospace manufacturers prioritize calibration traceability over unit cost.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme and China's dual carbon goals are reshaping sourcing patterns for cast-iron pump housings and chrome-plated cylinder rods. Foundry capacity for high-pressure alloy components clusters in China, Eastern European steel districts, and India's Maharashtra corridor. Raw material dependencies center on specialty steel alloys, compound elastomer seals, and high-voltage actuator electronics. Single-source vulnerability in Eastern European rod supply exposes buyers to alloy price volatility and logistics bottlenecks. Distribution runs through OEM direct sales for large fleet contracts and specialized industrial distributors for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around electrification-capable suppliers, with EPA Tier 4 Final compliance costs forcing smaller pneumatic-tool converters into exit or acquisition.
For Market Incumbents: Cement dominance in aerospace calibration channels by acquiring JIS B 8366-certified cylinder specialists in Japan, insulating against METI compliance barriers for imported components. Deepen backward integration into plasma-transferred arc coating equipment to capture REACH-compliant surface-treatment revenue as chromium VI restrictions tighten. For New Entrants and Emerging Players: The price-point gap between premium servo-controlled systems and manual field tools offers white-space entry for mid-tier hybrid electric-hydraulic units targeting wind turbine maintenance fleets. Focus initial penetration on Baltic and North Sea offshore installations where corrosion-resistant portable torque systems face supply shortages. Pursue equipment-as-a-service contracting models to bypass capital-purchase barriers among mid-size pipeline contractors. For Investors and Strategic Acquirers: The window for entry favors precision-torque specialists with embedded telematics capabilities ahead of predictive-maintenance platform consolidation. Long-term viability hinges on controlling sensor-integrated tool data streams rather than hardware manufacturing alone. Monitor CE Machinery Directive certification timeline compression as an inflection signal—suppliers achieving sub-12-month conformity assessments will capture share from delayed competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Electrified Power Pack Development | Battery-electric architectures displace diesel systems under EPA Tier 4 Final pressure. |
| Predictive Maintenance Platform Launch | Sensor-integrated tools enable subscription revenue from Texas rental fleet operators. |
| REACH-Compliant Coating Investment | Plasma-transferred arc capacity captures EU surface-treatment demand as chromium VI phases out. |
| CE Certification Acceleration | Compressed third-party assessment timelines differentiate suppliers in German automotive corridors. |
| Wind Turbine Service Partnership | Corrosion-resistant portable systems address maintenance gaps in North Sea offshore installations. |
Research Approach
Multi-period observation of EPA enforcement patterns, CE certification timelines, and alloy price volatility anchored the trend analysis, supplemented by interviews with maintenance directors at energy infrastructure contractors, plant engineers in German automotive assembly corridors, aftermarket service heads at rental fleet operators, and procurement teams at construction equipment OEMs. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive conformity assessment records, customs trade data for hydraulic component imports, and SEC filings from controlled-force technology suppliers. Bottom-up demand modeling triangulated against top-down industrial equipment capex projections.
Input-output matrices mapped hydraulic torque wrench, pump, cylinder, and jack demand across end-use segments, technology tiers, and regional regulatory clusters over the projection horizon. CAGRs were derived from segment-level demand elasticity coefficients and replacement-cycle compression factors. Forecast inputs incorporated electrification retrofit mandates, REACH compliance cost pass-through rates, and embedded-emissions tracking adoption curves under the EU Green Deal.
Underlying measurement precision varies by segment; aerospace torque calibration and automotive battery assembly applications carry tighter precision than commodity hydraulic jack demand in developing economies. Forecasts reflect assumptions about regulatory enforcement continuity and alloy supply stability that external shocks could revise. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Stationary Wood Planer Market
Tools
Post Drivers Market
Tools
Steel Measuring Tape Market
Tools
Extensometer Market
Tools
Drywall Tool Market
Tools
Hand Saw Market
Tools
Floor Scraper Market
Tools
Rocket Wrench Market
Tools
Global Cordless Power Tools Market
Tools
Pruning Saw Market
Tools
Wood-Burning Tool Market
Tools
Multi-Tasking Machine Tools Market
Tools
Telescopic Tool Boxes Market
Tools
Quick Release Pins Market
Tools
Collated Screws Market
Tools
Pipe Alignment Clamps Market