
 Spain Construction Market | 2026-2036
Spain Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Construction Market Analytics
Public infrastructure is pivoting toward rail and water resilience projects as Spain allocates recovery funds to sustainable mobility. Ferrovial dominates transport concession development through its specialized infrastructure unit. ACS leverages its engineering scale across multiple megaprojects simultaneously. Acciona differentiates through integrated renewable energy construction capabilities.
Spain construction encompasses the erection, renovation, and civil engineering of buildings and infrastructure using concrete, steel, timber, and composite assemblies governed by structural load specifications and thermal performance criteria. The sector serves housing provision, commercial activity, industrial production, and public service delivery. Residential project types currently lead total output as housing shortages persist in major metropolitan zones. Infrastructure project types represent the fastest expansion corridor driven by EU recovery facility allocations and climate adaptation priorities. Sustainable building codes are concentrating margin pools among contractors certified to deliver nearly zero-energy structures.
Spain's Código Técnico de la Edificación and EU Green Deal alignment through the Renovation Wave directive are tightening envelope performance standards and embodied carbon thresholds. The Ministry of Transport and Sustainable Mobility coordinates rail and port investments that redirect contractor specialization. Local planning authorities in autonomous communities enforce varying density and heritage protections that fragment permitting timelines. Stakeholders must monitor regulatory divergence between Madrid's streamlined urban development frameworks and Barcelona's stricter heritage conservation requirements.
Market Dynamics
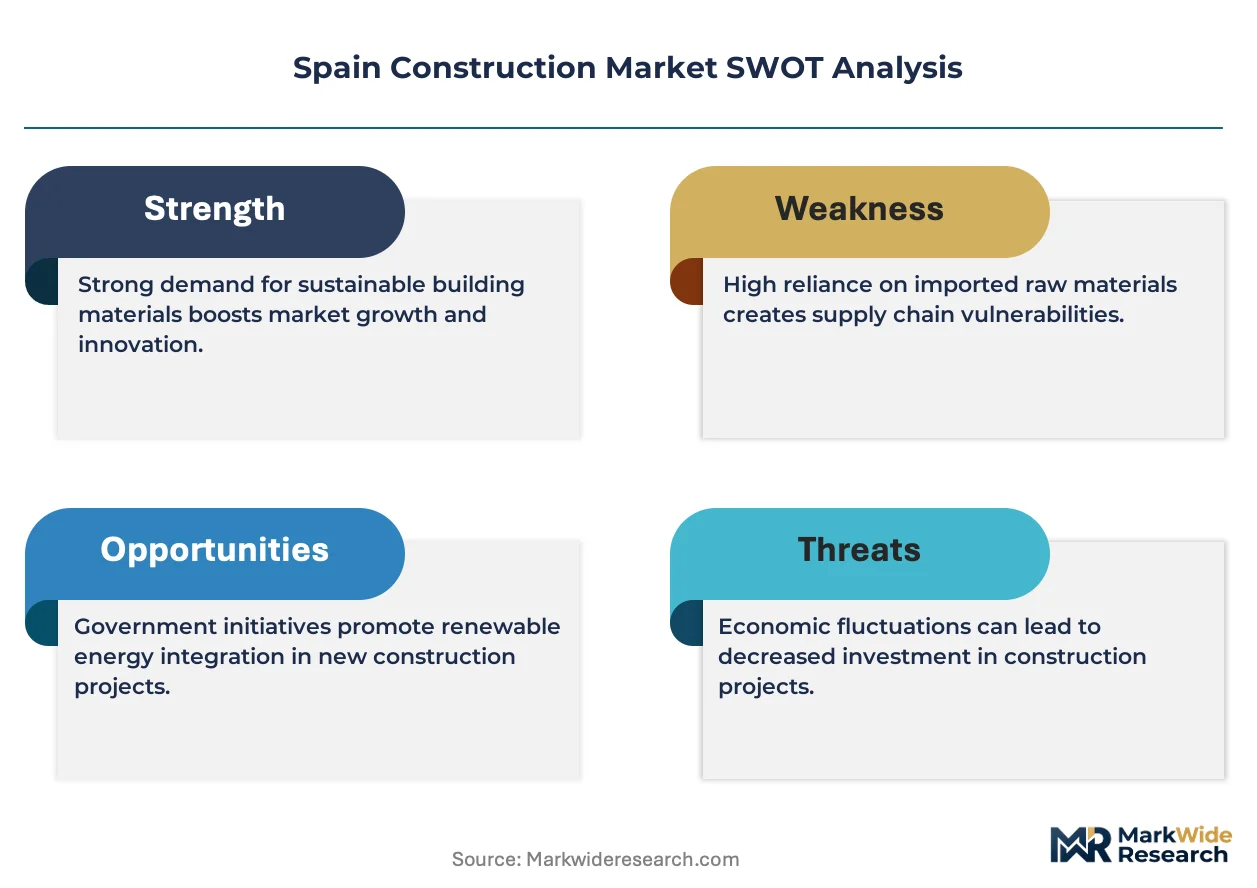
Spain's construction sector is reconfiguring around EU recovery fund deployment timelines and the Código Técnico de la Edificación's near-zero energy mandates, which are compressing contractor certification windows and concentrating execution capacity among pre-qualified firms.
Growth Catalysts
- Next Generation EU allocation:Spain's recovery plan directs substantial funding toward rail modernization and water infrastructure, creating sustained demand for civil engineering contractors with concession experience.
- Residential retrofit mandates:The Renovation Wave directive tightens envelope performance standards across existing housing stock, accelerating demand for thermal rehabilitation specialists in Madrid and Barcelona metropolitan zones.
- Mass timber engineering:Cross-laminated timber adoption is expanding beyond residential into commercial and institutional typologies as fire engineering protocols mature and carbon accounting favors biogenic materials.
Market Restraints
- Portland cement cost volatility:Energy-intensive clinker production faces input cost pressure from natural gas and carbon pricing, squeezing margin pools in concrete-dependent infrastructure segments.
- Specialized contractor concentration:Nearly zero-energy certification capacity clusters in Madrid and Barcelona, creating execution bottlenecks for projects in Andalusia and Galicia with equivalent compliance deadlines.
- Heritage overlay friction:Barcelona's strict conservation requirements under autonomous community planning law extend permitting timelines by 8-14 months versus Madrid's streamlined urban development frameworks.
Strategic Opportunities
- Andalusian solar-hybrid construction:Seville and Málaga present underpenetrated demand for building-integrated photovoltaics as regional temperature extremes intensify cooling load requirements.
- Industrialized offsite production:Modular bathroom and kitchen pods manufactured in Valencia's logistics corridor reduce on-site labor dependency and compress high-rise residential construction schedules.
- Hydrogen-ready infrastructure:The Ministry of Transport's alternative fuel corridor planning creates first-mover advantage for contractors capable of integrating electrolyzer-compatible electrical and piping systems.
Industry Challenges
- Passive house certifier scarcity:Spain maintains fewer than 200 certified designers and consultants capable of documenting compliance with the Código Técnico's enhanced thermal bridge requirements, creating project documentation backlogs.
- Digital twin integration complexity:BIM Level 2 mandates clash with legacy paper-based subcontractor workflows on mid-sized residential projects, requiring transitional training investments that erode near-term project margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Construction Market |
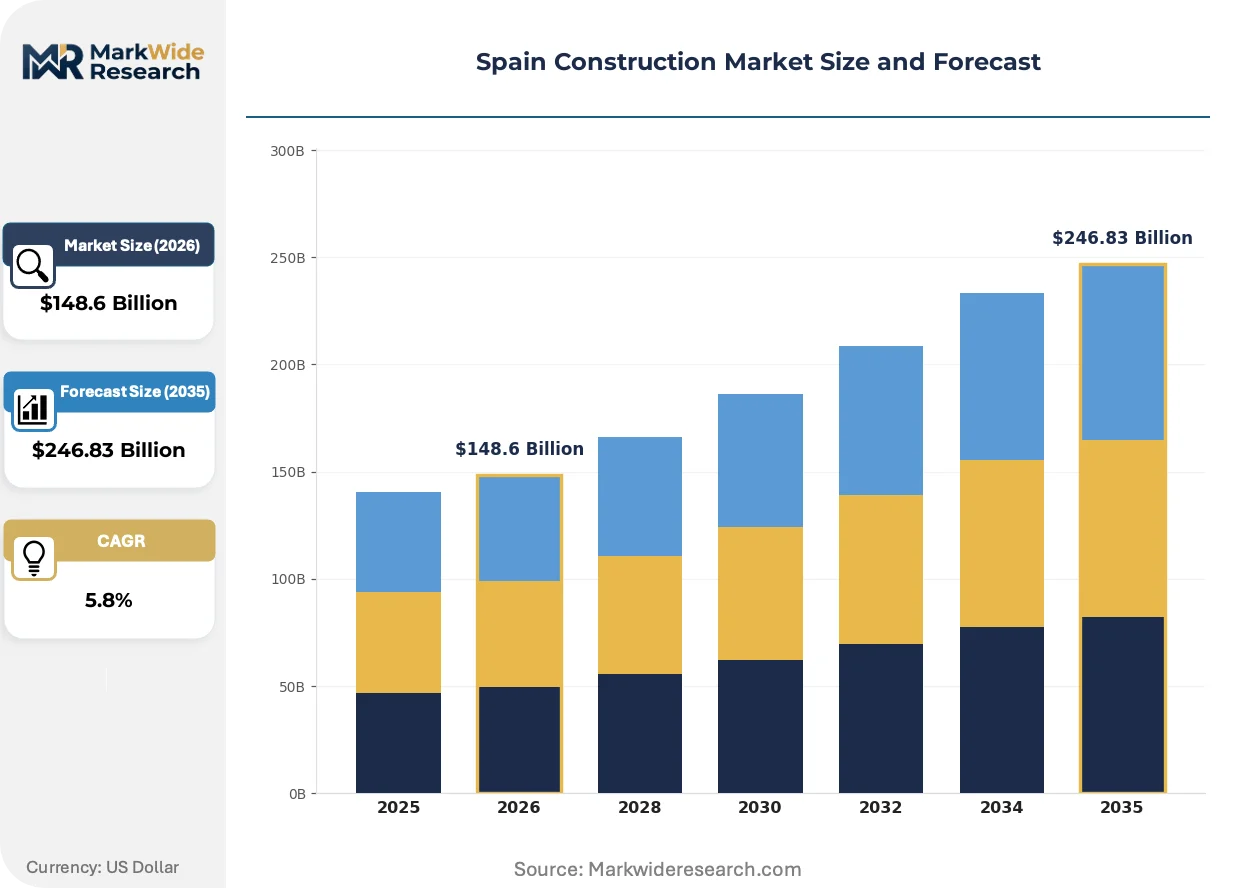
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $246.83 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Industrial, Infrastructure Material Type: Concrete, Steel, Wood, Glass Building Code: Local, National, International, Sustainable Funding Source: Private Investment, Government Grants, Public-Private Partnerships, International Aid |
| Companies Covered | ACS, Actividades de Construcción y Servicios, Ferrovial, Acciona, FCC, Sacyr, Dragados, Obrascón Huarte Lain (OHLA), Elecnor, Grupo San José, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Construction Market Evolving Landscape
Construction methodology in Spain is pivoting toward industrialized production systems and digital fabrication as labor availability tightens and compliance documentation demands intensify. Three interconnected developments are compressing traditional execution models.
Cross-laminated timber is unifying structural and finish functions in mid-rise residential and commercial buildings. Developers in Barcelona and Bilbao are specifying exposed CLT soffits to eliminate suspended ceiling systems. This convergence is compressing mechanical coordination timelines and reducing embodied carbon calculations by 25-40% versus conventional steel-concrete hybrid frames.
The EU Green Deal's Renovation Wave directive is tightening energy performance certificates and linking them to mortgage financing conditions. Spanish lenders are beginning to differentiate interest rates based on building energy labels. Residential retrofit contractors in Madrid are responding by bundling envelope upgrades with heat pump installations to secure favorable project financing for clients.
Public procurement authorities are consolidating project awards into design-build-operate concessions with 15-25 year service periods. Transport infrastructure tenders from the Ministry of Transport now require bidders to demonstrate lifecycle carbon modeling capabilities. This behavioral shift favors engineering groups with in-house asset management divisions over traditional construction-only contractors.
Spain Construction Market Segmentation
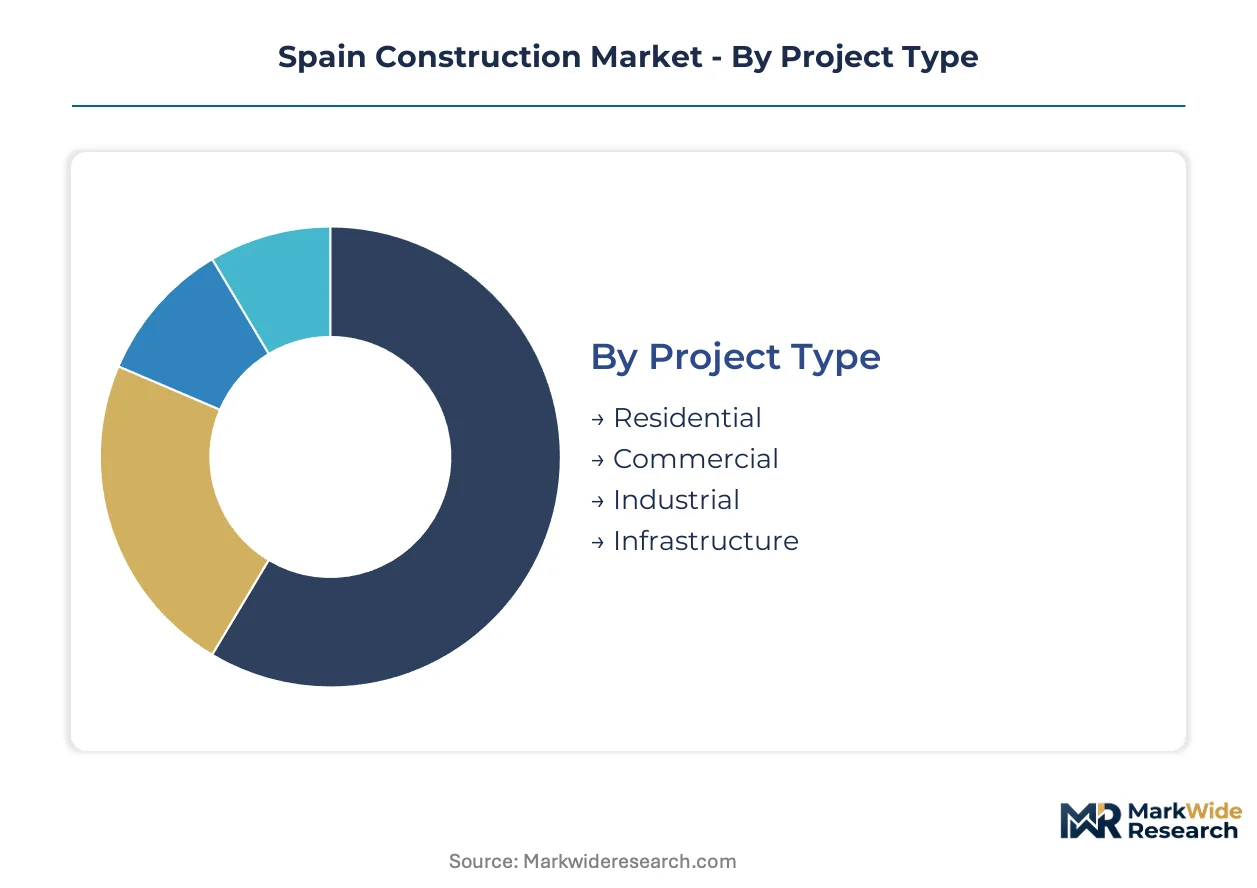
Spain's construction market fragments across project typologies, material specifications, regulatory compliance tiers, and capital structures. Each dimension shapes contractor specialization requirements and margin profiles differently across Madrid's transit corridors, Barcelona's heritage zones, and Andalusia's emerging solar-hybrid developments.
Project Type:
Standalone developments dominate capital deployment, while embedded infrastructure work requires deeper concession expertise and longer asset management horizons.
- Residential:Mid-rise apartment construction and single-family housing estates absorb the largest share of contractor capacity across Madrid and Barcelona metropolitan zones. Persistent housing shortages in these cities are compressing delivery timelines and concentrating demand among developers with pre-approved modular construction partnerships.
- Infrastructure:Rail modernization, water resilience systems, and port expansions funded through Next Generation EU allocations are expanding most quickly. The Ministry of Transport's design-build-operate concessions now demand 15-25 year service commitments that favor engineering groups with in-house asset management capabilities.
- Commercial:Office and retail developments in Valencia and Bilbao are integrating cross-laminated timber structural systems to meet tightening embodied carbon thresholds under the Código Técnico de la Edificación.
- Industrial:Logistics warehouses and manufacturing facilities in Zaragoza's distribution corridor are specifying hydrogen-ready electrical infrastructure ahead of Ministry of Transport alternative fuel corridor deployment.
Residential leads volumes today; Infrastructure is gaining share fastest.
Material Type:
Cost tiers stratify sharply between commodity bulk materials and certified low-carbon alternatives that command premium positioning in public procurement.
- Concrete:Portland cement-based systems remain the default for civil engineering and foundation work despite energy-intensive clinker production facing natural gas cost volatility. Contractors in Andalusia and Galicia are absorbing margin compression as carbon pricing intensifies.
- Wood:Cross-laminated timber and glulam assemblies are climbing the fastest as fire engineering protocols mature for commercial and institutional typologies. Barcelona developers are specifying exposed CLT soffits to eliminate suspended ceiling systems and reduce embodied carbon calculations by 25-40%.
- Steel:Structural sections and reinforcing bars serve high-rise residential and industrial frameworks, with procurement patterns shifting toward electric arc furnace producers to satisfy EU Green Deal circularity requirements.
- Glass:High-performance envelope glazing with triple-pane configurations and low-emissivity coatings is concentrating demand among facade specialists certified to deliver nearly zero-energy structures.
Concrete dominates tonnage deployed; Wood is expanding most quickly.
Building Code:
Customer type differentiation separates speculative developers from institutional owners with long-dated compliance obligations and access to favorable project financing.
- National:The Código Técnico de la Edificación's near-zero energy mandates and thermal bridge documentation requirements are compressing contractor certification windows. Fewer than 200 certified Passive House designers and consultants are creating project documentation backlogs across the country.
- Sustainable:EU Green Deal alignment through the Renovation Wave directive is tightening energy performance certificates and linking them to mortgage financing conditions. Spanish lenders are differentiating interest rates based on building energy labels.
- Local:Autonomous community planning authorities enforce varying density and heritage protections that fragment permitting timelines, with Barcelona's strict conservation requirements extending approvals by 8-14 months versus Madrid's streamlined frameworks.
- International:Foreign direct investment projects and EU-funded developments are specifying ISO 14001 environmental management and LEED or BREEAM certification for institutional investor compliance.
National code compliance absorbs the most consultant capacity; Sustainable certification is climbing the fastest.
Funding Source:
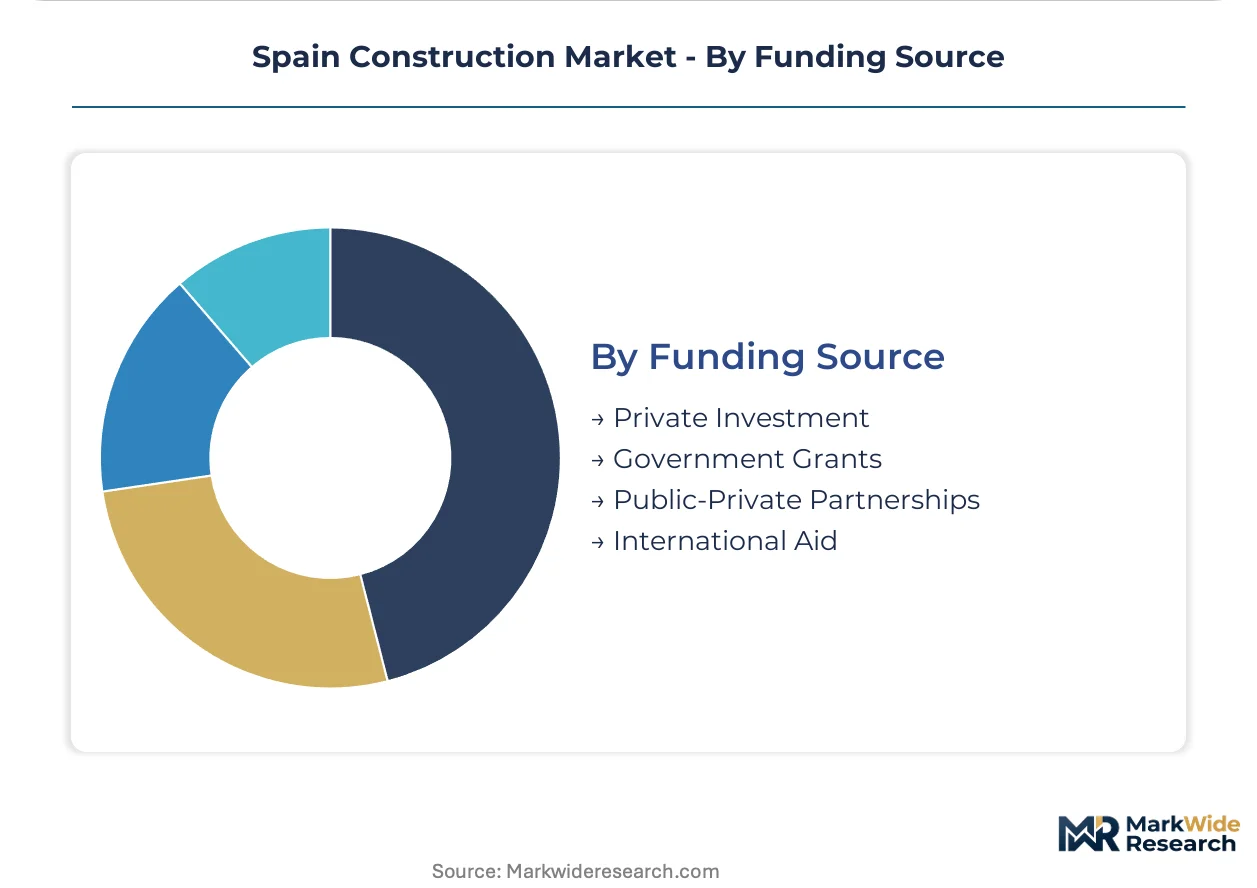
Supply concentration clusters in Madrid and Barcelona for complex blended finance structures, while straightforward private capital flows to regional contractors.
- Public-Private Partnerships:Transport infrastructure tenders now require bidders to demonstrate lifecycle carbon modeling capabilities and concession experience. Ferrovial and ACS are consolidating awards through specialized infrastructure units with 15-25 year operational commitments.
- Government Grants:Next Generation EU recovery fund deployment is directing sustained demand toward rail modernization and water infrastructure, with the Ministry of Transport coordinating investment timelines that redirect contractor specialization.
- Private Investment:Residential developers and commercial real estate funds are financing speculative construction in Madrid and Barcelona metropolitan zones, with lenders increasingly screening projects for energy label compliance.
- International Aid:EU structural funds and development bank financing are supporting climate adaptation projects in peripheral autonomous communities with lower private capital penetration.
Public-Private Partnerships command the largest project values; Government Grants are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Contractor certification costs are fragmenting execution capacity across Spain's autonomous communities, with Madrid's streamlined permitting frameworks attracting specialized firms from Barcelona's heritage-constrained zones. This regulatory-arbitrage dynamic is redistributing construction activity toward jurisdictions with faster approval timelines and lower compliance documentation burdens.
Madrid
Transit corridor extensions and high-rise residential towers are absorbing the largest share of national contractor capacity. The city's streamlined urban development frameworks under the regional planning authority compress permitting timelines by 8-14 months versus Catalan jurisdictions. CLT structural specialists and nearly zero-energy certifiers are clustering in the capital's logistics belt to serve concurrent public and private megaprojects.
Catalonia
Barcelona's strict heritage conservation requirements under autonomous community law are extending project approvals and concentrating demand among contractors with specialized conservation credentials. The Renovation Wave directive is tightening envelope performance standards across the metropolitan housing stock. Mass timber engineering firms in the Barcelona-Bilbao corridor are specifying exposed CLT soffits to eliminate suspended ceiling systems.
Basque Country
Industrialized offsite production of modular bathroom and kitchen pods is scaling in Bilbao's logistics corridor to reduce on-site labor dependency. The region's port infrastructure investments are creating demand for contractors with design-build-operate concession experience. Fire engineering protocols for cross-laminated timber are maturing fastest here, enabling commercial typology adoption beyond residential.
Andalusia
Seville and Málaga present underpenetrated demand for building-integrated photovoltaics as regional temperature extremes intensify cooling load requirements. Portland cement cost volatility from natural gas and carbon pricing is squeezing margin pools in concrete-dependent infrastructure segments. The Ministry of Transport's alternative fuel corridor planning is creating first-mover positioning for hydrogen-ready electrical contractors.
Valencia
High-performance envelope glazing with triple-pane configurations is concentrating demand among facade specialists serving the Mediterranean commercial market. The logistics warehouse and manufacturing facility pipeline in Zaragoza's distribution corridor is specifying hydrogen-ready infrastructure ahead of national deployment timelines. Local contractors are bundling envelope upgrades with heat pump installations to secure favorable project financing.
Spain Construction Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with transport infrastructure concessions consolidating around engineering groups with in-house asset management divisions. The vendor base clusters into three tiers: diversified infrastructure conglomerates with 15-25 year operational commitments, regional residential specialists with modular construction partnerships, and niche facade and timber contractors certified to nearly zero-energy standards. Dominant competitive moves include vertical integration into concession operations and geographic expansion into underpenetrated autonomous communities with equivalent compliance deadlines.
Among Spanish-based infrastructure conglomerates, ACS, Actividades de Construcción y Servicios and Ferrovial occupy positions within the transport concession development tier, while Acciona exemplifies the renewable energy-integrated construction archetype. These entities represent the scale-driven end of public procurement consolidation, where lifecycle carbon modeling capabilities and specialized infrastructure units are redirecting award patterns away from traditional construction-only contractors.
| Leading Market Players |
|---|
| ACS, Actividades de Construcción y Servicios |
| Ferrovial |
| Acciona |
| FCC |
| Sacyr |
| Dragados |
| Obrascón Huarte Lain (OHLA) |
| Elecnor |
| Grupo San José |
| Others |
Value Network & Pricing Analysis
Next Generation EU procurement mandates for lifecycle carbon documentation are forcing contractors toward certified material suppliers, compressing margin pools as premium-tier inputs displace commodity alternatives. The Código Técnico de la Edificación's near-zero energy standards are redirecting demand toward Passive House-certified designers and cross-laminated timber specialists, creating price stratification between compliant and non-compliant supply tiers.
Pricing Analysis
Distributor margins on cross-laminated timber and high-performance glazing concentrate among facade specialists certified to nearly zero-energy standards. Three-tier pricing structure across premium certified, standard compliant, and economy conventional tiers separates contractors by documentation capability. Pricing pressure stems from Portland cement cost volatility as natural gas and carbon pricing squeeze concrete-dependent infrastructure segments. Public procurement authorities exhibit lowest price sensitivity due to concession-based long-term offtake structures, while speculative residential developers face highest sensitivity to financing conditions tied to energy label compliance.
Supply Chain Analysis
Freight costs from Nordic timber suppliers and German engineered wood producers concentrate CLT availability in Barcelona-Bilbao and Madrid logistics corridors. Raw material dependencies center on Swedish and Finnish spruce laminations, Portuguese cork insulation systems, and domestic Portland cement clinker. Supply chain risk hinges on single-source vulnerability for certified Passive House components, with fewer than 200 qualified designers creating documentation bottlenecks. Distribution runs through specialized contractors with direct mill relationships, bypassing traditional bulk distributors for certified low-carbon assemblies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's construction market functions as a geographic-arbitrage play where Madrid's streamlined permitting timelines attract capacity from Barcelona's heritage-constrained zones, exploiting an 8-14 month approval differential to compress project delivery costs.
For Market Incumbents: Deepen backward integration into modular bathroom and kitchen pod manufacturing to reduce on-site labor dependency and compress high-rise residential schedules. Secure concession experience through design-build-operate transport infrastructure awards from the Ministry of Transport, as emerging pure-construction contractors lack 15-25 year operational commitment capabilities. Counter Portland cement margin compression by anchoring procurement in electric arc furnace steel and mass timber alternatives. For New Entrants and Emerging Players: Launch via industrialized offsite production partnerships in Valencia's logistics corridor to bypass on-site labor scarcity and accelerate project delivery timelines. Target Andalusian solar-hybrid construction in Seville and Málaga, where building-integrated photovoltaics demand remains underpenetrated despite intensifying cooling load requirements. Differentiate through hydrogen-ready electrical infrastructure certification ahead of Ministry of Transport alternative fuel corridor deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with niche facade and timber contractors certified to nearly zero-energy standards, where capability scarcity concentrates pricing power among fewer than 200 qualified designers. Five-to-ten year viability favors engineering groups with in-house asset management divisions over construction-only contractors as public procurement consolidates around lifecycle carbon modeling requirements. Monitor Renovation Wave directive implementation velocity as the signal indicating retrofit contractor valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Modular Production | Captures Valencia logistics corridor capacity to reduce on-site labor dependency in high-rise residential. |
| Concession Experience Accumulation | Secures Ministry of Transport design-build-operate awards requiring 15-25 year operational commitments. |
| Passive House Certification Investment | Addresses documentation bottleneck among fewer than 200 qualified designers under Código Técnico mandates. |
| Hydrogen-Ready Infrastructure Capability | Positions for first-mover advantage in Ministry of Transport alternative fuel corridor deployment. |
| Cross-Laminated Timber Specialization | Captures 25-40% embodied carbon reduction demand from Barcelona and Bilbao commercial developers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with project developers at ACS and Ferrovial, procurement officers at regional modular manufacturers, Passive House certifiers in Madrid and Barcelona, and Ministry of Transport planning officials with secondary validation against EU Recovery Fund disbursement records, Spanish building permit databases, and Código Técnico de la Edificación compliance filings. Bottom-up project pipeline analysis and top-down sectoral expenditure estimates were triangulated to anchor market sizing.
Segment-weighting across project typology, material specification, regulatory compliance tier, and capital structure shaped the analytical framework over the projection horizon. Residential, infrastructure, commercial, and industrial project types were modeled against concrete, wood, steel, and glass material deployments, with national, sustainable, local, and international building code tiers cross-referenced against public-private partnership, government grant, private investment, and international aid funding sources. CAGRs were derived from expenditure trajectory analysis and contractor capacity utilization patterns, with EU Green Deal alignment velocity and Renovation Wave implementation pace serving as key forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated EU recovery fund deployment or prolonged heritage permitting delays in Catalonia. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Australia Construction Market
Building Construction
3D Printing Building Construction Market
Building Construction
Mezzanine Floor Market
Building Construction
El Salvador Construction Market
Building Construction
Europe Prefabricated Buildings Market
Building Construction
GCC Cement Market
Building Construction
North America Modular Construction Market
Building Construction
Ireland Data Center Construction Market
Building Construction
Eastern Europe Construction Market
Building Construction
Indonesia Prefabricated Buildings Market
Building Construction
Qatar Construction Market
Building Construction
United States Commercial Construction Market
Building Construction
Precast Construction Market
Building Construction
India Commercial Construction Market
Building Construction
Italy Construction Market
Building Construction
Vietnam Construction Market