
 Floor Polishing Machine Market | 2026-2036
Floor Polishing Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Floor Polishing Machine Market Analysis
Market Context
European cleaning equipment manufacturers is broadening production capacity to serve rebounding commercial real estate maintenance across Western Europe. Tennant Company leverages its North American service network to sustain recurring revenue from fleet management contracts. Alfred Kärcher SE & Co. KG anchors its position through deep product specialization in high-pressure and surface preparation systems. Nilfisk competes aggressively on battery platform standardization across its scrubber-dryer and polisher portfolios.
Technical Definition and Segment Structure
A floor polishing machine is a motorized surface treatment device employing rotating abrasive pads or brushes at speeds typically ranging from 150 to 3,000 RPM to restore gloss, remove scratches, or prepare substrates for coating. These machines serve primarily commercial and industrial facilities where foot traffic degradation demands periodic restoration of vinyl, terrazzo, polished concrete, and natural stone surfaces. Electric-powered units still occupy the largest installed base, though battery variants represent the fastest-growing power source segment as lithium-ion chemistry improves runtime for cordless orbital and rotary models. Pad-type machines dominate residential and light commercial applications where maneuverability outweighs productivity, while single-disc and rotary configurations capture margin pools in heavy-duty concrete and marble restoration.
Regulatory Environment and Outlook
OSHA workplace noise exposure limits and EU machinery directive safety standards compel manufacturers to redesign motor housings and add vibration dampening, directly influencing R&D allocation and model certification timelines. REACH chemical restrictions on maintenance consumables and evolving EPA energy efficiency benchmarks for corded equipment further constrain formulation and motor choices available to producers. Stakeholders must monitor battery end-of-life regulations in multiple jurisdictions, as extended producer responsibility frameworks for lithium-ion packs threaten to reshape total cost of ownership calculations and service model economics.
Market Dynamics
Battery chemistry improvements and OSHA noise enforcement are compressing the replacement cycle for corded equipment while forcing manufacturers to redesign motor housings and invest in lithium-ion platform development.
Growth Catalysts
- EU machinery directive safety standards:Tighter emissions and noise thresholds for indoor cleaning operations are compelling facility managers to upgrade to compliant battery-powered units.
- Polished concrete flooring:Warehouse and logistics construction across the United States is expanding the addressable surface area requiring periodic restoration.
- Lithium-ion runtime improvements:Extended cordless operation is enabling overnight cleaning crews in German hospitality to abandon trailing power cords entirely.
Market Restraints
- Copper and rare earth magnet costs:Motor and battery supply chains face input price volatility that compresses OEM margins on mid-tier equipment.
- Extended producer responsibility frameworks:EU battery end-of-life regulations threaten to reshape total cost of ownership calculations for fleet operators.
- Manual burnishing alternatives:Low-wage cleaning labor in emerging markets delays mechanization adoption for small commercial facilities.
Strategic Opportunities
- India commercial real estate:Underpenetrated facility management services in Tier-2 cities create whitespace for rental and leasing models.
- Robotics convergence:Autonomous navigation modules paired with orbital polishing heads open unattended overnight operation in German retail.
- US Inflation Reduction Act efficiency incentives:Energy-efficient motor certifications unlock tax-advantaged procurement for municipal and federal building fleets.
Industry Challenges
- Skilled technician scarcity:Concrete restoration and terrazzo polishing require specialized training that outpaces vocational program output in aging workforces.
- REACH compliance timelines:Chemical restrictions on maintenance consumables force reformulation cycles that delay new product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Floor Polishing Machine Market |
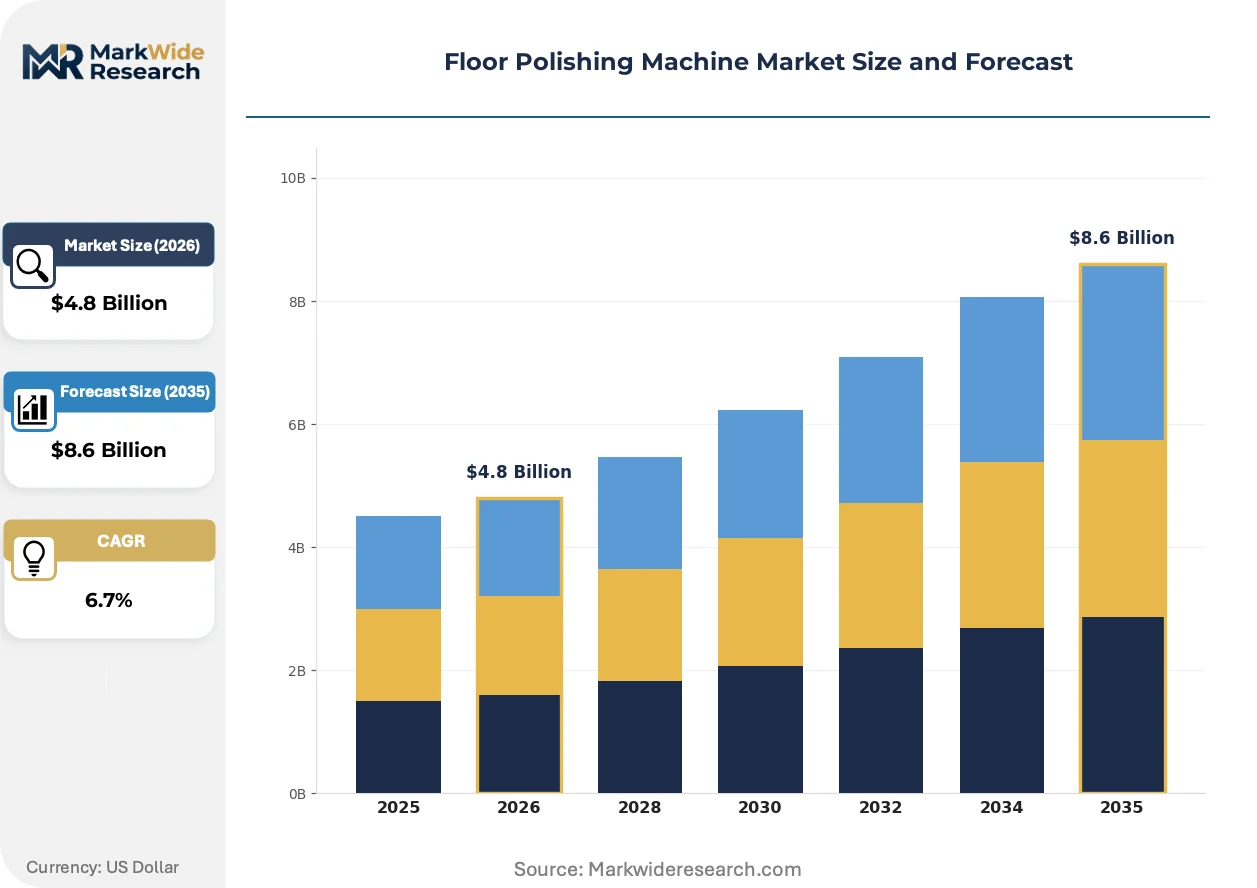
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Disc, Rotary, Pad, Orbital End User: Industrial, Commercial, Residential, Automotive Power Source: Electric, Battery, Gas, Manual Application: Concrete, Wood, Tile, Marble |
| Companies Covered | Nilfisk, POWER A/S, Alfred Kärcher SE & Co. KG, Minuteman International Inc., Tornado Industries, Tennant Company, Fimap S.p.A., KLindex, Hako B.V, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Floor Polishing Machine Market Emerging Trajectories
Equipment architecture is fragmenting into interoperable subsystems that let buyers mix power sources, pad configurations, and telemetry modules rather than accepting monolithic designs.
Brushless DC motor platforms paired with swappable battery packs are modularizing how fleet operators configure machine specifications. Large retail chains in the United States now specify standardized battery interfaces across scrubbers and polishers to simplify spare parts logistics. This interoperability is compressing vendor lock-in and accelerating private-label equipment sourcing.
OSHA workplace noise exposure limits are forcing redesigns of motor housings and the addition of vibration dampening to meet certification timelines. Manufacturers must retool production lines to accommodate these acoustic engineering requirements. The heaviest impact falls on rotary configurations above 1,500 RPM, where legacy designs face the steepest compliance costs.
Facility management procurement departments are unbundling after-sales service from equipment purchase contracts. Third-party maintenance providers in Germany now compete directly with OEM service networks for multi-site hospitality contracts. This disintermediation is most pronounced in airport and convention center verticals where centralized procurement favors independent service audits.
Floor Polishing Machine Market Segmentation
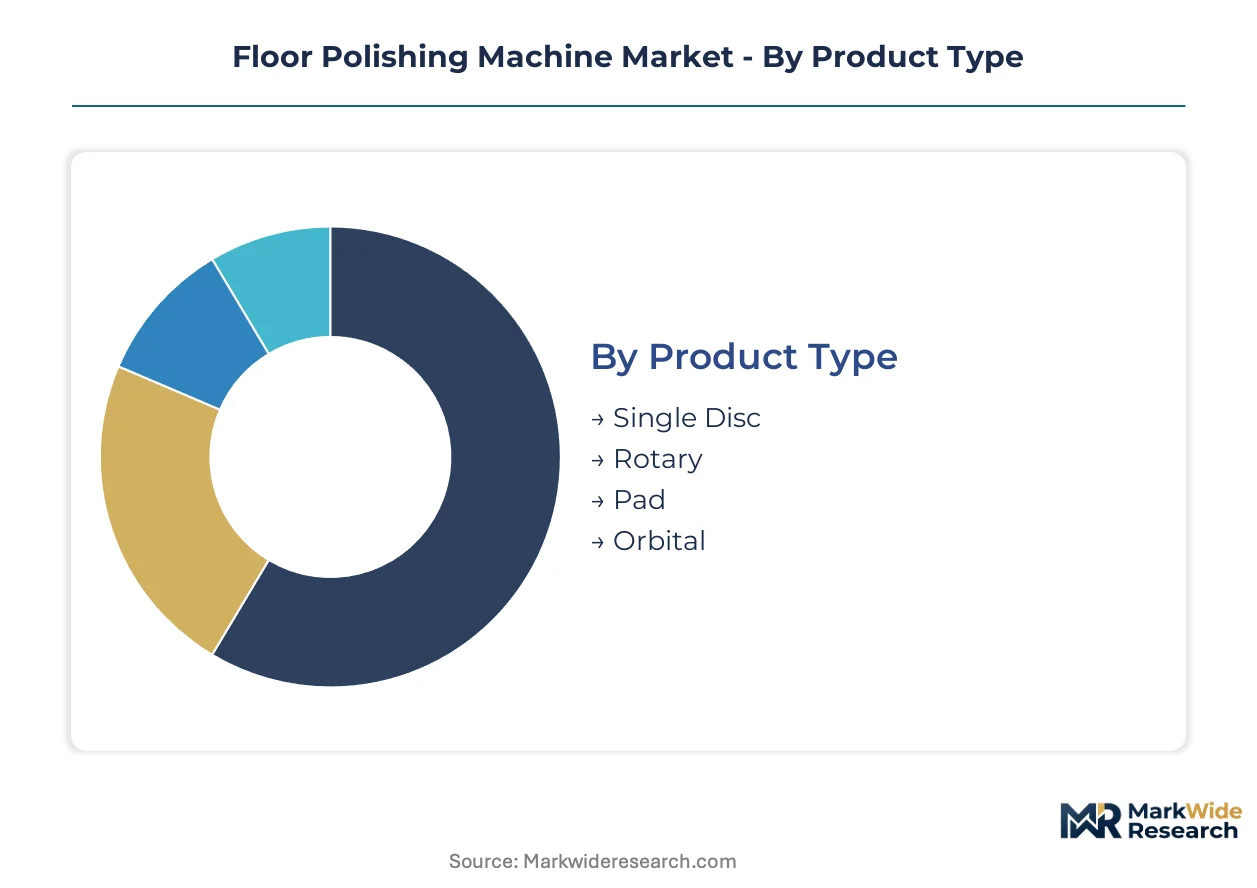
Floor polishing machine procurement patterns diverge sharply between high-frequency commercial operators and intermittent residential users. Equipment specifications, power configurations, and surface compatibility requirements create distinct margin pools that manufacturers must navigate through targeted platform development.
Product Type:
Volume concentrates in pad and orbital configurations for routine maintenance, while premium margins attach to specialized restoration equipment.
- Single Disc:Heavy-duty rotary platforms operating at 1,000–3,000 RPM for aggressive material removal on concrete and terrazzo. German facility management contractors specify these for airport and convention center restoration cycles where substrate damage demands intensive intervention.
- Rotary:High-torque direct-drive systems dominating marble and natural stone polishing in Italian hospitality and heritage building maintenance. OSHA noise enforcement is forcing motor housing redesigns that add cost but create compliance differentiation.
- Pad:Lightweight maneuverable units for vinyl and sealed wood surfaces in US retail and office environments.
- Orbital:Random-pattern motion systems gaining preference for scratch-sensitive finishes in Scandinavian commercial interiors.
Today's leader: Rotary. Tomorrow's challenger: Orbital.
End User:
Application intensity determines equipment durability specifications and service contract attachment rates.
- Industrial:Continuous-duty machines for manufacturing and logistics facilities where 24-hour operational availability mandates redundant fleet deployment. US warehouse construction is expanding the installed base requiring periodic concrete restoration.
- Commercial:Mid-duty cycles in hospitality, retail, and healthcare where battery runtime and noise compliance drive replacement decisions. German hotel chains are abandoning corded equipment entirely for overnight cleaning operations.
- Residential:Intermittent-use machines sold through retail channels with minimal service attachment.
- Automotive:Specialized detailing equipment for dealership showrooms and service center customer areas.
Commercial users generate recurring service revenue. Industrial contracts anchor fleet management profitability.
Power Source:
Regulatory pressure is fragmenting the installed base between legacy corded infrastructure and cordless replacement platforms.
- Electric:Corded AC motors retaining cost advantage in fixed-installation environments with reliable grid access. EPA energy efficiency benchmarks are compressing margins on non-certified motor designs.
- Battery:Lithium-ion platforms with swappable packs enabling cordless operation in German retail and US hospitality settings. EU machinery directive emissions standards are accelerating displacement of gas alternatives in enclosed spaces.
- Gas:Declining share confined to outdoor and remote construction applications where electrical infrastructure is absent.
- Manual:Minimal presence limited to spot repair and edge work in emerging markets with low labor costs.
Battery platforms are climbing the fastest. Electric retains volume dominance through installed base inertia.
Application:
Surface hardness and porosity dictate abrasive selection, pad chemistry, and machine weight distribution.
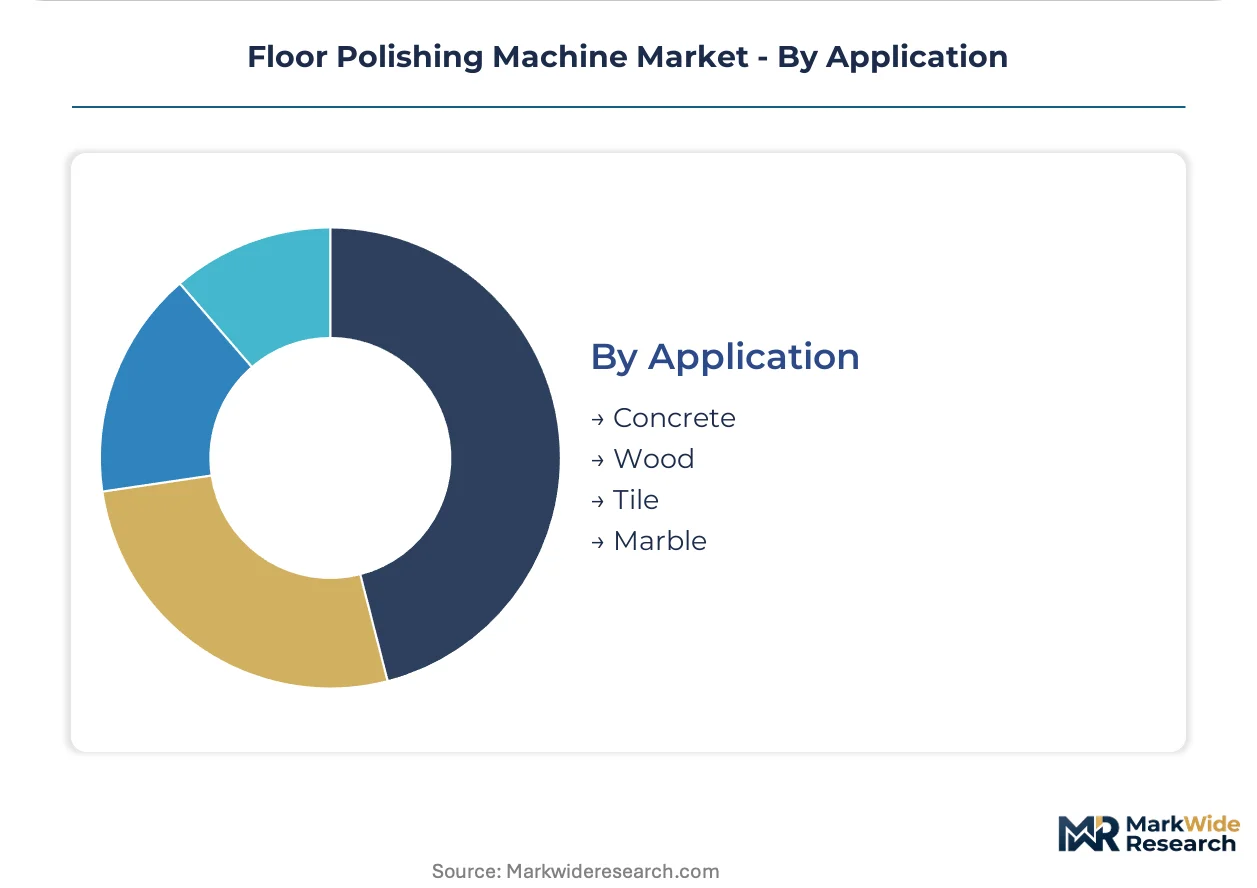
- Concrete:Polished concrete flooring in US logistics and distribution centers requires planetary-head machines for densifier application and gloss restoration. Warehouse construction cycles sustain replacement demand.
- Wood:Sports hall and parquet restoration in Central European municipal facilities demands specialized sanding-polishing hybrid equipment.
- Tile:Ceramic and porcelain maintenance in Mediterranean hospitality relies on lower-RPM orbital systems to preserve grout integrity.
- Marble:Natural stone restoration in Italian and Greek heritage buildings commands premium pricing for skilled technician deployment.
Concrete applications are expanding most quickly. Marble restoration retains the steepest margin structure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as producers relocate assembly to jurisdictions with lower compliance burdens for battery disposal and noise certification. Cost-of-compliance gaps between jurisdictions exceed equipment margins on mid-tier machines.
United States
Logistics warehouse construction across Texas and Georgia sustains demand for concrete restoration equipment. EPA energy efficiency benchmarks for corded motors compress margins on legacy designs. Chicago-area facility management contractors deploy battery fleets for overnight airport terminal maintenance.
Germany
EU machinery directive emissions thresholds accelerate displacement of gas-powered units in enclosed commercial spaces. REACH chemical restrictions on maintenance consumables force reformulation cycles. Bavarian hospitality chains specify standardized battery interfaces across scrubber-polisher fleets.
China
Commercial real estate stock in Shanghai and Shenzhen requires periodic polishing of polished concrete and terrazzo surfaces. MIIT battery safety standards for industrial equipment shape platform development timelines. Yangtze River Delta manufacturers expand capacity for lithium-ion pack integration.
India
Tier-2 city commercial development creates whitespace for equipment rental models as facility management services penetrate beyond metros. BIS certification requirements for electrical safety extend product launch timelines. Maharashtra-based contractors pilot battery machines for Mumbai hospitality contracts.
Japan
Aging building stock in Tokyo and Osaka sustains replacement demand for marble and natural stone restoration equipment. METI energy efficiency labeling for commercial appliances influences procurement specifications. Kansai-region heritage building maintenance commands premium pricing for skilled technician deployment.
Floor Polishing Machine Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue autonomous navigation and robotics convergence. The vendor base clusters around three maturity levels: century-old European specialists with deep service networks, mid-cap regional fabricators with price-competitive battery platforms, and venture-backed automation developers targeting unattended operation. Two archetypes dominate competitive positioning: integrated manufacturers controlling motor and battery supply chains, and asset-light assemblers sourcing modular subsystems from specialized tier-two suppliers. Capacity expansion and strategic partnerships represent the primary competitive moves as firms secure lithium-ion cell allocation and certify redesigned housings for OSHA noise compliance.
Among Danish and German specialists, Nilfisk and Alfred Kärcher SE & Co. KG exemplify the integrated archetype with standardized battery platforms across surface preparation portfolios. Tennant Company anchors the North American service-network tier, leveraging recurring fleet management contracts to defend position against disintermediation from third-party maintenance providers. These three entities represent distinct strategic postures: battery platform standardization, deep product specialization in high-pressure systems, and service-network monetization respectively.
| Leading Market Players |
|---|
| Nilfisk |
| POWER A/S |
| Alfred Kärcher SE & Co. KG |
| Minuteman International Inc. |
| Tornado Industries |
| Tennant Company |
| Fimap S.p.A. |
| KLindex |
| Hako B.V |
| Others |
Supply Flow & Price Mechanics
Brushless DC motor platform adoption is compressing cost curves for mid-tier equipment while concentrating lithium-ion cell procurement leverage among integrated manufacturers with captive battery assembly lines. This dual effect rewards scale players who internalize motor-controller production and penalizes asset-light assemblers exposed to copper and rare earth magnet price volatility.
Pricing Analysis
Distributor margins absorb the steepest compression as OEMs pursue direct fleet management contracts with US retail and German hospitality chains. Three-tier pricing structure across premium, standard, and economy levels stratifies by OSHA noise certification tier and battery runtime specification, with certified cordless units commanding substantial premiums over legacy corded alternatives. Pricing pressure stems from EPA energy efficiency benchmarks squeezing margins on non-certified AC motor designs. Small commercial facilities and emerging market buyers exhibit highest price sensitivity, while airport and convention center operators prioritize compliance and uptime over unit economics.
Supply Chain Analysis
OSHA and EU machinery directive certification gating restricts component sourcing to qualified motor housing and vibration-dampening subsystem suppliers with proven acoustic engineering capabilities. Manufacturing concentrates in China, Germany, and the United States, with Yangtze River Delta facilities dominating lithium-ion pack integration and Bavarian plants specializing in precision motor assembly. Supply chains rest on copper winding wire, neodymium permanent magnets, and injection-molded polymer housings. Single-source vulnerability in rare earth magnet processing creates exposure to export restriction shocks. Distribution runs through authorized dealer networks for commercial fleet sales and direct e-commerce channels for residential intermittent-use equipment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU machinery directive emissions thresholds and OSHA noise enforcement create mandatory replacement demand that insulates volume from cyclical downturns.
For Market Incumbents: Lock in battery platform standardization across scrubber-dryer and polisher portfolios to entrench fleet-wide spare parts logistics and resist disintermediation from third-party maintenance providers. Secure lithium-ion cell allocation through long-term supply agreements with Yangtze River Delta manufacturers. Invest in acoustic engineering R&D to capture OSHA compliance differentiation ahead of certification deadline compression.
For New Entrants and Emerging Players: Tier-2 city facility management contractors in India represent an underserved buyer archetype with whitespace for rental and leasing models as commercial real estate development penetrates beyond metropolitan cores. Target battery-powered orbital configurations for scratch-sensitive Scandinavian commercial interiors where established players lack specialized product depth. Pursue direct procurement relationships with centralized airport and convention center procurement departments to bypass incumbent dealer networks.
For Investors and Strategic Acquirers: Roll-up economics work for regional service-network operators because fleet management contract recurring revenue streams and technician training asset bases resist commoditization pressure from equipment-only competitors. Target mid-cap fabricators with certified OSHA-compliant rotary platforms and established German hospitality customer relationships. Monitor EU battery end-of-life regulation implementation timelines as inflection indicator for total cost of ownership recalculation and service model restructuring.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Nilfisk and Kärcher leverage standardized interfaces to lock in fleet-wide spare parts logistics across multi-site hospitality contracts. |
| OSHA Compliance Certification Investment | Rotary configuration manufacturers retool motor housings to capture premium positioning ahead of noise enforcement deadlines. |
| Direct Fleet Management Contracting | Tennant bypasses distributor margin compression by monetizing recurring service revenue from US retail chain deployments. |
| Regional Manufacturing Footprint Expansion | Yangtze River Delta capacity additions secure lithium-ion cell allocation for cordless platform scaling. |
| Autonomous Navigation Module Development | Venture-backed entrants target unattended overnight operation in German retail through robotics convergence with orbital polishing heads. |
Methodological Framework
Multiple input streams — facility management procurement director interviews, OEM product manager discussions, and aftermarket service provider consultations — were reconciled against customs trade data, EPA energy efficiency filings, and EU machinery directive certification registries. Primary fieldwork captured replacement cycle timing, battery runtime specification priorities, and service contract attachment rate economics across US, German, and Chinese operator bases. Secondary validation drew from SEC equipment manufacturer disclosures, MIIT industrial battery safety standard drafts, and BIS electrical certification timelines. Bottom-up unit shipment estimates by power source and product configuration were triangulated against top-down addressable surface area calculations by commercial real estate stock.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions to derive volume and value trajectories. Segmentation dimensions modeled include product type, end-use intensity tier, power source architecture, and surface application substrate. CAGRs were computed from annualized shipment growth rates adjusted for replacement cycle compression effects. Forecast inputs incorporated lithium-ion chemistry improvement curves, OSHA enforcement phase-in schedules, and commercial construction permit trends by metropolitan statistical area.
Underlying measurement precision varies by segment; battery-powered equipment and commercial end-use categories carry tighter precision than gas-powered alternatives and residential intermittent-use sales. Forecasts reflect documented assumptions regarding regulatory implementation timing and raw material cost trajectories. A model refresh is warranted upon material change in EU battery end-of-life regulation enforcement or rare earth magnet export restriction policy.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Cutting Equipment Market
Tools
Welding Guns Market
Tools
United States Machine Tools Market
Tools
Global Electric Portable Drill Market
Tools
Cordless Blind Rivet Gun Market
Tools
Wood Router Market
Tools
Tape Measure Market
Tools
Automatic Heat Press Machines Market
Tools
Stand Tile Saw Market
Tools
Shredder Blades Market
Tools
Measuring Wheels Market
Tools
Cutting Tool Inserts Market
Tools
Thickness Planers Market
Tools
Portable Milling Machine Market
Tools
2D Laser Cutting Machine Market
Tools
Multi-Tasking Machine Tools Market