
 Drill Set Market | 2026-2036
Drill Set Market Size, Share, and Industry Trends Forecast 2026-2036
Drill Set Market Analytics
Aftermarket service revenue for bit sharpening and battery refurbishment is fragmenting across competing channel models. BOSCH leverages its service-center network to capture recurring spend from professional contractors. Milwaukee differentiates through subscription-based tool-tracking platforms that lock in fleet operators. Makita competes on geographic dominance in Asia-Pacific service infrastructure.
A drill set comprises rotating cutting tools and their power delivery systems, engineered with flute angles between 118 and 135 degrees for chip evacuation and point geometries ground from solid carbide or high-speed steel blanks for hardness retention above 62 HRC; the assembly serves to bore precise cylindrical holes in metal, wood, masonry, and composite substrates for assembly, fastening, and fabrication workflows. Twist drill configurations occupy the largest volume pool across industrial procurement, while carbide material grades command premium positioning in automated CNC metalworking cells where tool life directly governs throughput economics. DIY application segments sustain volume through retail channel turnover despite thinner per-unit margins relative to contractor-grade professional lines.
OSHA workplace safety standards govern noise exposure and hand-arm vibration limits for powered drilling equipment in US manufacturing and construction environments, while EPA regulations restrict cobalt and tungsten particulate discharge from grinding operations that produce cutting edges. REACH compliance in Europe mandates disclosure of Substances of Very High Concern in surface coatings applied to high-speed steel bits, reshaping supplier qualification criteria for EU-distributed product. Stakeholders must monitor how battery chemistry regulations and raw material sourcing disclosure requirements will reshape cost structures and supplier accountability across the value chain.
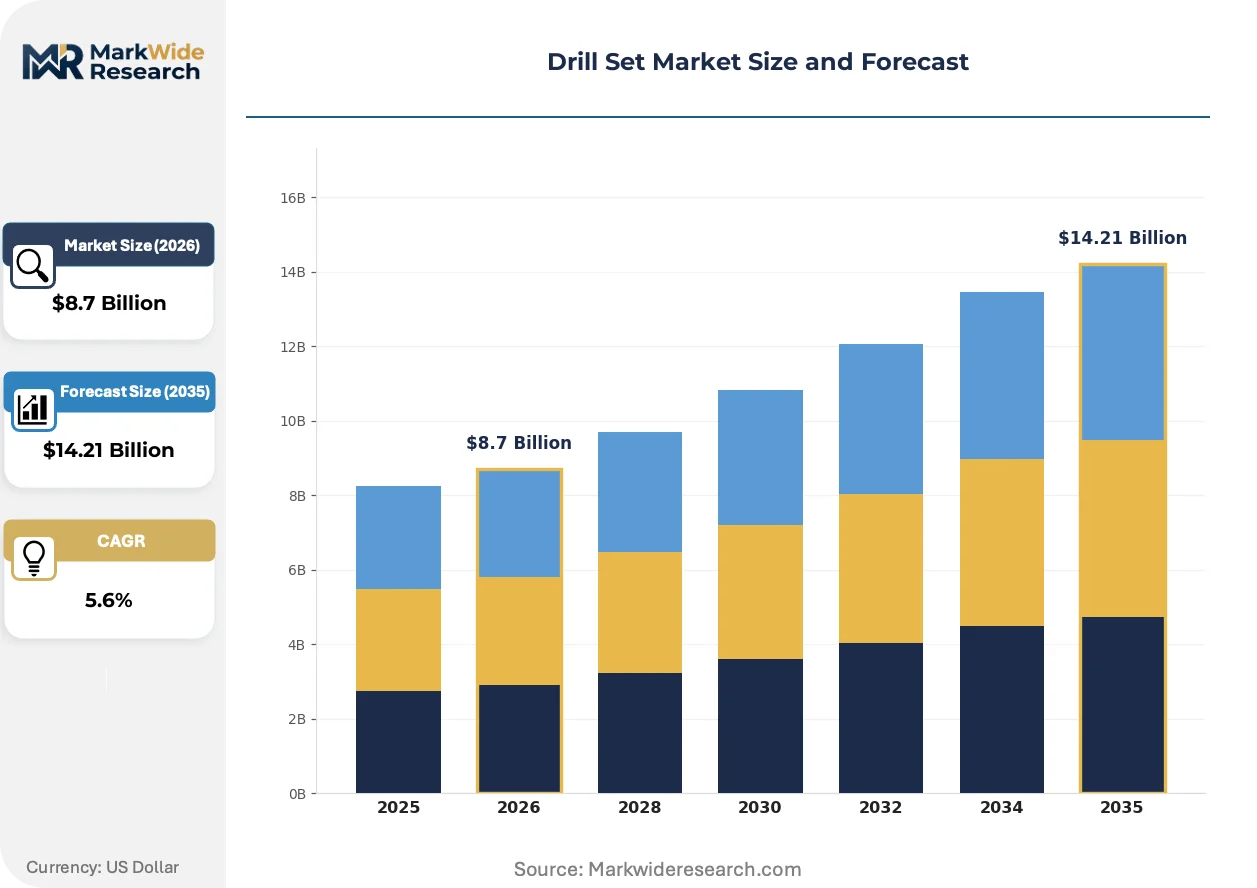
Market Dynamics
EPA tightened volatile organic compound regulations on solvent-based metalworking fluids are accelerating cordless lithium-ion drill adoption among construction contractors, while cobalt-grade bit specifications from automotive OEMs in Germany's precision engineering corridor concentrate demand for hardened steel applications.
Growth Catalysts
- REACH compliance mandates:ECHA disclosure requirements for Substances of Very High Concern in surface coatings are reshaping supplier qualification criteria across EU distribution networks.
- OSHA workplace safety standards:Noise exposure and hand-arm vibration limits for powered drilling equipment are driving equipment replacement cycles in US manufacturing environments.
- Solid carbide material grades:Automated CNC metalworking cells specify these for hardness retention above 62 HRC, directly governing throughput economics in precision fabrication.
Market Restraints
- Cobalt and tungsten input volatility:EPA restrictions on particulate discharge from grinding operations raise compliance costs for cutting edge production.
- Battery chemistry regulatory uncertainty:Emerging raw material sourcing disclosure requirements threaten to reshape cost structures across cordless power tool supply chains.
- High-speed steel substitution pressure:Carbide material grades displace traditional twist drill configurations in volume-sensitive industrial procurement.
Strategic Opportunities
- Aftermarket service fragmentation:Bit sharpening and battery refurbishment revenue pools are splitting across competing channel models, creating entry points for specialized operators.
- Asia-Pacific service infrastructure gaps:Geographic dominance in professional-grade tool maintenance remains underdeveloped outside established manufacturing corridors.
- EU Green Deal alignment:Battery refurbishment and circular economy tool-tracking platforms qualify for emerging sustainability-linked procurement preferences.
Industry Challenges
- Flute angle engineering talent scarcity:Precision grinding expertise for 118 to 135 degree chip evacuation geometries concentrates among aging specialist workforces in Stuttgart and Solingen.
- Multi-substrate certification complexity:Bits must qualify simultaneously for metal, wood, masonry, and composite applications, extending validation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drill Set Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Twist Drill, Masonry Drill, Step Drill, Spade Bit Material: High-Speed Steel, Carbide, Cobalt, Diamond Application: Metalworking, Woodworking, Construction, DIY End User: Contractors, Homeowners, Manufacturers, Retailers |
| Companies Covered | BOSCH, DeWalt, Milwaukee, Makita, Ryobi, Craftsman, SKIL, KPT, JCB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drill Set Market Evolving Landscape
Digital tool-tracking platforms and battery chemistry advances are compressing ownership models and reshaping how professional contractors manage fleet economics across cordless drilling equipment.
Brushless motor technology paired with solid-state battery cells is virtualizing the traditional distinction between corded and cordless performance tiers. Heavy-duty construction contractors in North American metropolitan markets now specify these systems for applications previously reserved for pneumatic or mains-powered tools. The technology is virtualizing procurement categories that hardware distributors historically separated by power source.
EPA volatile organic compound regulations on solvent-based metalworking fluids are eliminating mineral oil-based cutting lubricants from metal fabrication workflows. Metalworking shops serving automotive and aerospace supply chains must convert to synthetic or semi-synthetic alternatives, raising tool cooling requirements. German precision engineering clusters are responding by specifying cobalt-grade bits with enhanced heat resistance for hardened steel boring operations.
Subscription-based fleet management platforms are displacing outright equipment ownership among professional contractors. Tool-tracking software bundled with maintenance services now locks in multi-year relationships with fleet operators, squeezing traditional distributor margins. This shift concentrates most visibly in North American commercial construction, where general contractors consolidate vendor relationships to simplify job-site logistics and warranty administration.
Drill Set Market Segmentation
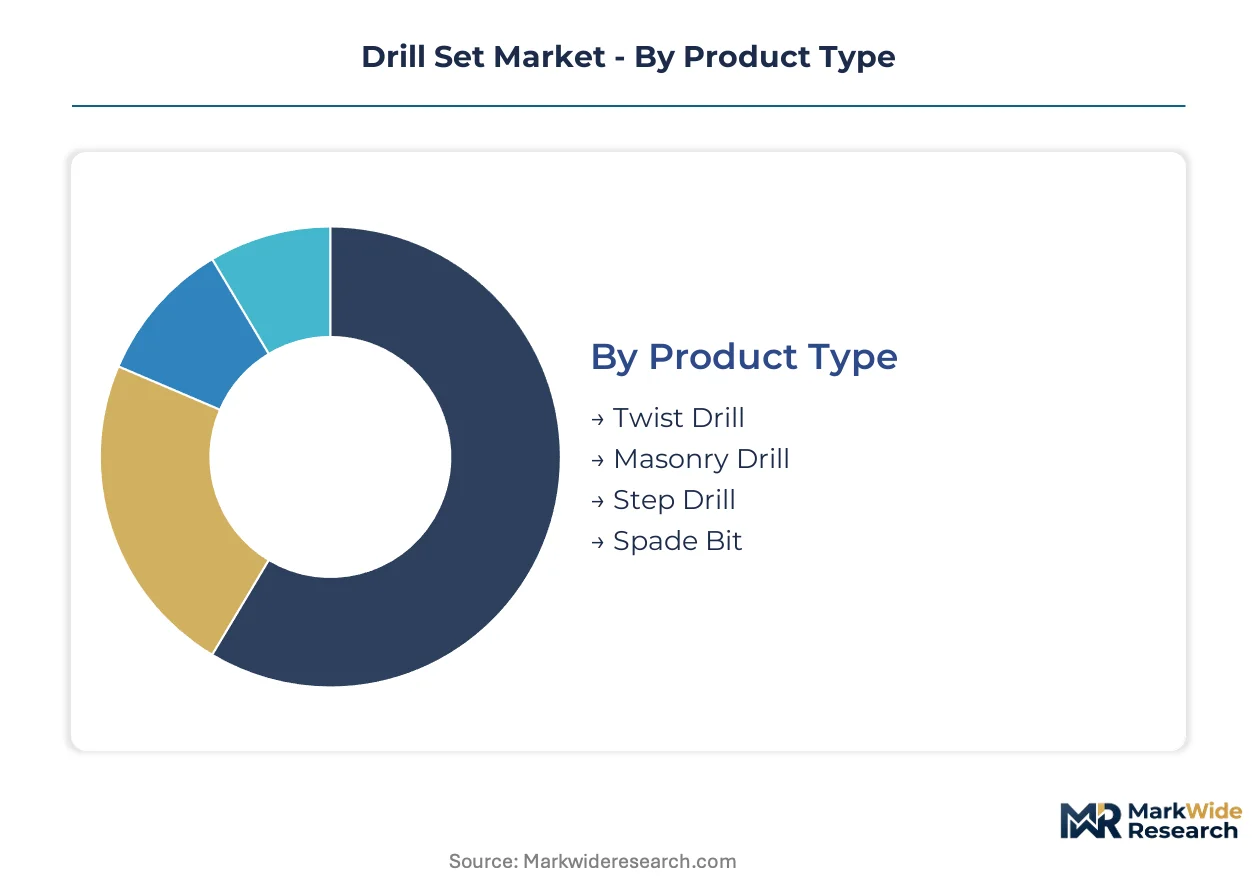
Drill set segmentation reveals divergent service intensity patterns across product tiers. High-frequency professional use segments generate recurring aftermarket revenue through bit sharpening and battery refurbishment, while intermittent DIY applications concentrate volume through retail turnover with minimal post-sale engagement.
Product Type:
Aftermarket service intensity varies sharply across cutting geometries, with flute complexity dictating resharpening economics and replacement frequency.
- Twist Drill:Fluted helical design with 118 to 135 degree point angles governs chip evacuation in metal and wood substrates. German automotive OEMs in Stuttgart's precision engineering corridor specify these for hardened steel boring above 62 HRC, where heat resistance directly governs throughput economics in automated CNC cells.
- Masonry Drill:Tungsten carbide brazed tips with spiral flutes penetrate concrete, brick, and stone substrates. North American construction contractors deploying these in cordless lithium-ion configurations face EPA volatile organic compound compliance costs on solvent-based metalworking fluids, accelerating synthetic lubricant adoption.
- Step Drill:Conical profile with multiple diameter stages enables sheet metal deburring without bit changes.
- Spade Bit:Flat paddle geometry with centering spur bores rough holes in softwood and composite materials.
Twist drill configurations hold the largest share; momentum sits with masonry drill variants as cordless platform adoption accelerates in construction workflows.
Material:
Cost tier stratification separates premium performance grades from commodity substitutes, with hardness retention and heat resistance governing price positioning.
- Carbide:Sintered tungsten carbide with cobalt binder achieves hardness above 92 HRA for automated CNC metalworking cells. Solid carbide blanks command premium positioning where tool life directly determines throughput economics in German precision engineering clusters serving aerospace supply chains.
- Cobalt:M35 and M42 grades with 5-8% cobalt content enhance red hardness for stainless steel and titanium alloys. REACH compliance mandates on Substances of Very High Concern in surface coatings are reshaping EU supplier qualification criteria for cobalt-grade distribution networks.
- High-Speed Steel:M2 and M7 grades balance toughness and grindability for general-purpose metalworking.
- Diamond:Polycrystalline diamond compact edges machine abrasive composites and non-ferrous materials.
High-speed steel holds the largest share; carbide grades are climbing the fastest as CNC automation penetrates precision fabrication.
Application:
Volume concentration and margin structure diverge across professional and consumer use cases, with procurement channel and specification authority determining supplier access.
- Metalworking:Precision boring, reaming, and threading operations in automotive, aerospace, and general fabrication. OSHA workplace safety standards on noise exposure and hand-arm vibration limits are driving equipment replacement cycles in US manufacturing environments.
- Construction:Structural steel, concrete anchoring, and mechanical fastening in commercial and residential builds. North American metropolitan contractors now specify brushless motor systems with solid-state batteries for applications previously reserved for pneumatic tools.
- Woodworking:Furniture manufacturing, millwork, and carpentry requiring clean chip evacuation.
- DIY:Intermittent residential repair and hobbyist fabrication sustaining retail channel turnover.
Metalworking holds the largest share; construction applications are expanding most quickly as cordless platform performance virtualizes traditional power source categories.
End User:
Customer type dictates procurement authority, specification complexity, and aftermarket service attachment rates across the value chain.
- Contractors:Professional fleet operators managing multi-tool inventories across job sites. Subscription-based tool-tracking platforms now lock in multi-year relationships with North American general contractors, squeezing traditional distributor margins while consolidating vendor administration.
- Manufacturers:Industrial procurement teams specifying cutting tools for captive production cells. German automotive OEMs in the precision engineering corridor demand cobalt-grade bits with certified heat resistance for hardened steel applications.
- Homeowners:Intermittent residential users purchasing through retail channels with minimal technical support requirements.
- Retailers:Distributor and dealer networks managing inventory and warranty logistics for mixed customer bases.
Contractors hold the largest share; manufacturers are gaining share fastest as in-house fabrication capabilities expand among mid-tier industrial operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German automotive OEMs absorb premium cobalt-grade pricing without volume compression, while Indian construction contractors trade down to high-speed steel substitutes when lithium-ion platform costs spike.
United States
Commercial construction contractors in metropolitan markets specify brushless motor systems with solid-state batteries for heavy-duty applications. OSHA workplace safety standards on noise exposure and hand-arm vibration limits drive equipment replacement cycles in manufacturing environments. Detroit-area automotive fabricators demand carbide-grade bits for hardened steel boring in automated CNC cells.
Germany
Automotive OEMs in Stuttgart's precision engineering corridor specify cobalt-grade bits with certified heat resistance above 62 HRC. ECHA REACH compliance mandates on Substances of Very High Concern in surface coatings reshape supplier qualification criteria for EU distribution networks. Solingen grinding specialists concentrate precision flute-angle expertise for 118 to 135 degree chip evacuation geometries.
China
Domestic manufacturers expand captive production of solid carbide blanks for CNC metalworking cells serving aerospace supply chains. MEE regulations on cobalt and tungsten particulate discharge from grinding operations raise compliance costs for cutting edge production. Yangtze River Delta fabrication clusters virtualize traditional corded-cordless procurement categories through brushless motor adoption.
Japan
Precision engineering firms specify polycrystalline diamond compact edges for abrasive composite machining in electronics manufacturing. METI battery chemistry disclosure requirements reshape cost structures across cordless power tool supply chains. Nagoya-area automotive suppliers demand certified heat resistance for titanium alloy boring operations.
India
Construction contractors in Maharashtra and Gujarat accelerate cordless lithium-ion adoption amid infrastructure build-out programs. BIS certification requirements for power tool safety standards extend validation timelines for multi-substrate bit qualifications. Bangalore precision engineering clusters develop domestic carbide blank capabilities for mid-tier metalworking applications.
Drill Set Market Competitive Landscape
Capability concentration sits with specialized grinding houses possessing precision flute-angle expertise; scale advantage sits with diversified power tool platforms distributing through consolidated retail channels. The market structures around three tiers: premium-grade carbide specialists serving CNC automation, mid-tier cobalt-grade suppliers for automotive specification, and volume-driven high-speed steel producers for construction interchangeability. Dominant competitive moves include geographic expansion into underdeveloped Asia-Pacific service infrastructure and portfolio diversification into subscription-based fleet management platforms.
Among diversified power tool manufacturers, BOSCH, Milwaukee, and Makita occupy distinct positioning archetypes. BOSCH leverages its German engineering heritage to anchor premium-tier specification in European automotive supply chains. Milwaukee exemplifies the subscription-model disruptor consolidating North American contractor relationships through tool-tracking software bundling. Makita represents geographic infrastructure dominance, with service network density across Asia-Pacific manufacturing corridors that competitors have yet to replicate.
| Leading Market Players |
|---|
| BOSCH |
| DeWalt |
| Milwaukee |
| Makita |
| Ryobi |
| Craftsman |
| SKIL |
| KPT |
| JCB |
| Others |
Value Network & Pricing Analysis
Overcapacity in Chinese carbide blank production is compressing input costs for mid-tier bit manufacturers while simultaneously eroding pricing power across standard-grade product lines. This utilization imbalance forces German precision grinding houses to defend premium positioning through certified heat-resistance specifications that commodity producers cannot replicate.
Pricing Analysis
Aftermarket service revenue from bit sharpening and battery refurbishment drives lifetime value differentiation across the competitive landscape. Pricing stratifies across premium, standard, and economy tiers based on material certification grade and geographic service infrastructure density. Cost compression in high-speed steel substitutes is intensifying because cordless platform commoditization accelerates retail channel turnover. DIY homeowners exhibit highest price sensitivity, while German automotive OEMs absorb cobalt-grade premiums without volume compression.
Supply Chain Analysis
Upstream tungsten and cobalt concentrate feedstock draws from Chinese mining operations, Russian metallurgical processing, and Congolese extraction corridors. Solid carbide blanks, cobalt binder alloys, and lithium-ion cell chemistries constitute critical input dependencies. Single-source vulnerability concentrates in rare earth processing capacity located outside established manufacturing clusters. Distribution runs through consolidated retail channels for DIY segments and direct fleet-management platforms for professional contractor procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision grinding expertise for 118 to 135 degree flute geometries concentrates among aging specialist workforces in Stuttgart and Solingen, creating a bottleneck that will constrain premium-tier supply expansion regardless of capital investment.
For Market Incumbents: Pre-empt cobalt-grade bit substitution by securing certified heat-resistance specifications from German automotive OEMs before REACH compliance mandates reshape supplier qualification criteria. Backward integration into solid carbide blank production insulates margin structures from Chinese overcapacity-driven price volatility. Channel control through subscription-based tool-tracking platforms locks in fleet operator relationships against distributor disintermediation. For New Entrants and Emerging Players: Pursue aftermarket service infrastructure gaps across Asia-Pacific manufacturing corridors where geographic dominance remains underdeveloped. Battery refurbishment and bit sharpening services in India and Southeast Asia represent the most penetrable white-space target. A go-to-market angle anchored in EU Green Deal sustainability-linked procurement preferences differentiates against established competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among fleet-management platform operators bundling tool-tracking software with maintenance services. Long-term viability over the next decade hinges on exposure to cordless lithium-ion platform adoption curves rather than corded equipment replacement cycles. Acquisition targets should demonstrate precision grinding capability or solid-state battery integration partnerships. The signal to watch is EPA regulatory acceleration on volatile organic compound restrictions that would compress solvent-based lubricant-dependent competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Grinding Capability Acquisition | Secures scarce Stuttgart and Solingen flute-angle engineering talent before competitive attrition. |
| Solid-State Battery Integration Partnership | Positions brushless motor systems for heavy-duty construction applications previously reserved for pneumatic tools. |
| EU Green Deal Certification Pathway | Qualifies battery refurbishment operations for emerging sustainability-linked procurement preferences. |
| Asia-Pacific Service Infrastructure Buildout | Captures fragmented aftermarket revenue pools across underdeveloped professional-grade tool maintenance networks. |
| REACH Compliance-Ready Coating Investment | Ensures continued EU distribution access as ECHA disclosure requirements reshape supplier qualification criteria. |
Research Methodology
Operator-level perspectives from maintenance directors at automotive OEMs, plant engineers in metalworking fabrication cells, aftermarket service heads at power tool distributors, and procurement leads at commercial construction firms anchored the qualitative base. Primary interview insights combined with secondary validation from SEC filings of listed power tool manufacturers, customs and trade data on tungsten and cobalt imports, OSHA workplace safety standard documentation, and ECHA REACH compliance databases. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from production capacity disclosures.
Scenario-bracketing framed analytical projections across the analysis window, with volume and value outputs reflecting segmentation by product type, material grade, application workflow, and end-user procurement authority. CAGRs derived from historical shipment data and forward-looking capacity expansion announcements. Forecast inputs incorporated cordless platform adoption curves in North American construction and CNC automation penetration rates in German precision engineering clusters.
Sensitivities concentrate around battery chemistry regulatory shifts, cobalt and tungsten input price volatility, and precision grinding workforce attrition. Forecasts reflect documented assumptions on technology substitution rates and regional platform standardization timelines. Material shifts in EPA volatile organic compound enforcement intensity or ECHA REACH substance restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Plate Bending Machines Market
Tools
Woodcarving Tool Market
Tools
Cold and Hot Tool Steel Market
Tools
Shape Moulding Machines Market
Tools
US Chalk Reel and Line Market
Tools
Steel Measuring Tape Market
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Wood Floor Grinding Machine Market
Tools
Power Nibbler Market
Tools
Stationary Wood Planer Market
Tools
Riveting Tools Market
Tools
Gear Honing Machines Market
Tools
Power Drill Market
Tools
Portable Heat Press Machine Market
Tools
Wire Cutters Market
Tools
Sanding Machine Market