
 Land Survey Equipment Market | 2026-2036
Land Survey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Land Survey Equipment Market Analysis
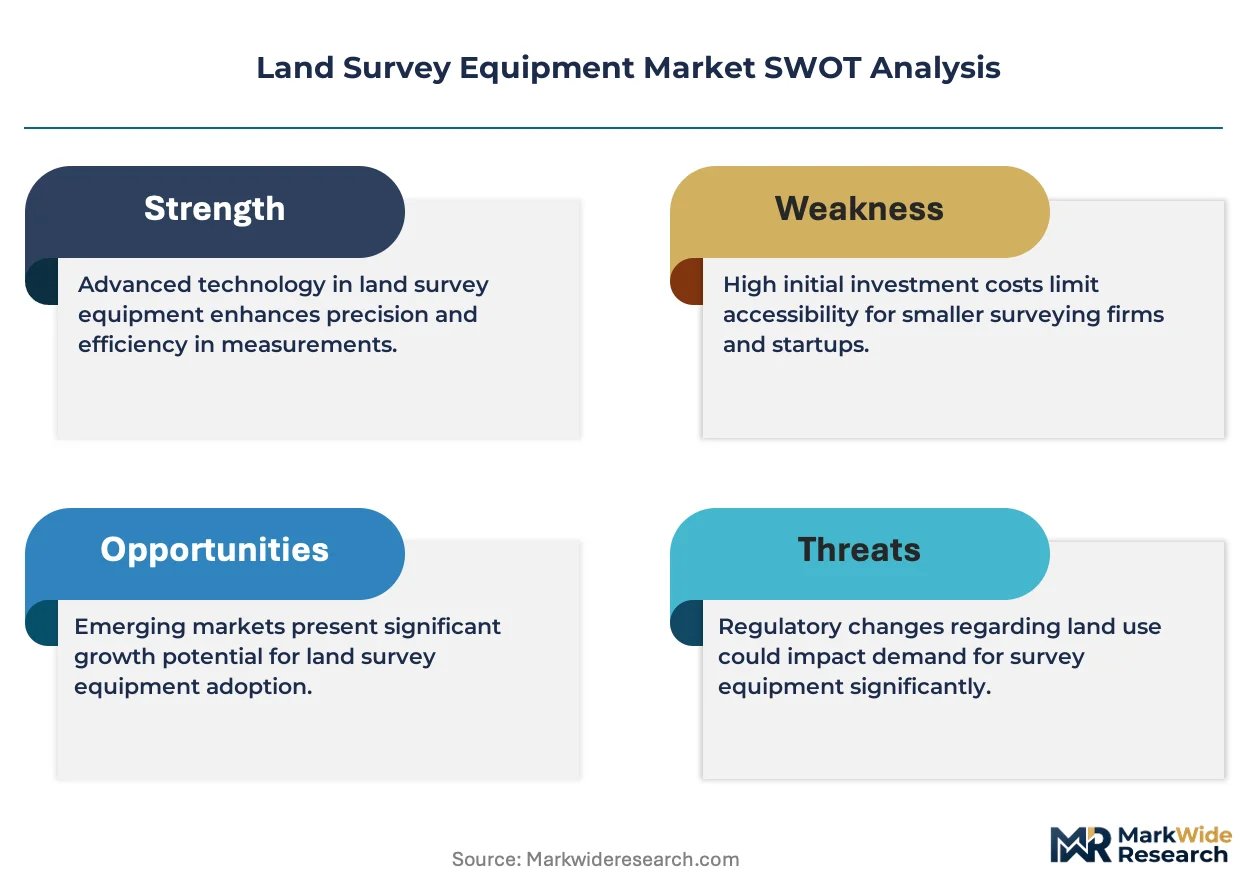
Integration of multi-constellation GNSS with inertial measurement units is fragmenting the traditional total station hierarchy. Trimble Inc. leverages its R&D intensity to dominate high-precision agriculture and construction workflows. Hexagon AB anchors its position through backward integration into sensor manufacturing and software ecosystems. Topcon Corporation competes aggressively on price-performance in the mid-tier robotics segment across Asian markets.
Land survey equipment comprises optical, electronic, and satellite-based instruments engineered to measure angles, distances, and elevations with sub-centimeter precision, serving cadastral boundary determination, topographic mapping, and engineering layout control. GPS/GNSS receivers lead value generation due to their indispensability in real-time kinematic positioning for machine guidance, while robotics-enabled total stations represent the fastest-expanding margin pool as labor costs rise on complex sites. Construction absorbs the dominant share of unit demand, though mining applications command premium pricing because of hazardous-environment durability requirements.
ISO 17123 governs field test procedures for geodetic instruments, while the FAA regulates unmanned aerial systems increasingly deployed for photogrammetric survey in the United States. China's SAMR enforces GB standards for electronic measurement accuracy, creating compliance barriers for imported equipment. India's CEA mandates digital terrain modeling for new transmission corridor approvals, expanding the addressable base for 3D laser scanning solutions. Stakeholders must weigh captive software development against interoperability partnerships as platform ecosystems consolidate control over data workflows.
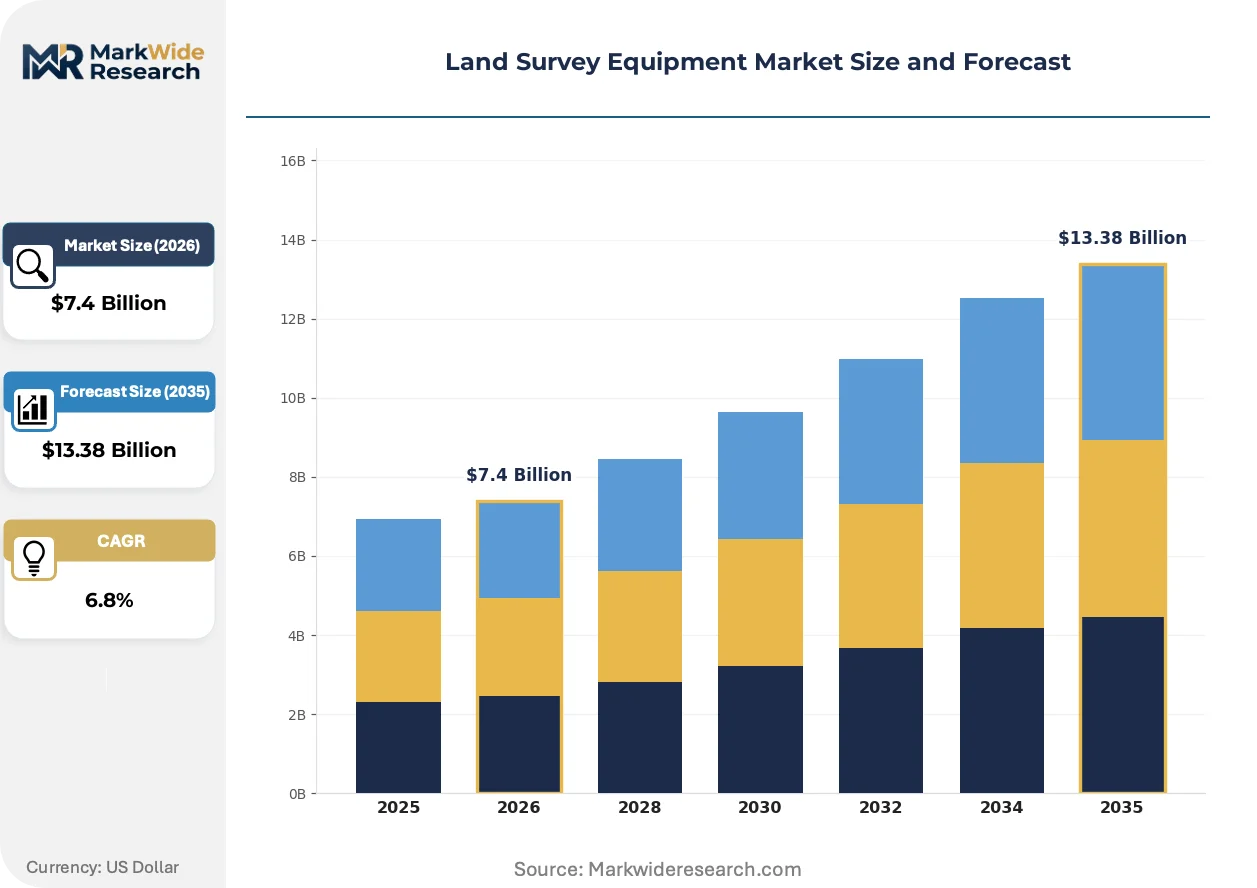
Market Dynamics
Multi-constellation GNSS integration with inertial measurement units is fragmenting the traditional total station hierarchy, forcing manufacturers to recalibrate sensor architectures and software ecosystems simultaneously.
Growth Catalysts
- Federal Infrastructure Modernization:Germany's rail and highway programs mandate millimeter-grade surveying accuracy, pulling high-precision GNSS receivers and robotics-enabled total stations into public procurement pipelines.
- Digital Terrain Mandates:India's CEA requires 3D laser scanning for new transmission corridor approvals, expanding addressable demand for LiDAR-based survey solutions in utility infrastructure.
- Machine Guidance Integration:Construction firms across the United States deploy satellite-guided positioning tools for automated earthmoving and grading operations, embedding survey-grade accuracy directly into heavy equipment workflows.
Market Restraints
- Input Cost Volatility:Precision MEMS sensors and high-grade optical components face supply concentration in East Asian foundries, exposing manufacturers to raw material price swings and allocation constraints.
- Regulatory Friction:China's MIIT tightened certification requirements for GNSS receivers used in cadastral mapping, creating compliance barriers that delay product launches and inflate testing expenditures for foreign suppliers.
- Technical Limitation:Signal multipath in urban canyon environments degrades real-time kinematic performance, limiting GNSS-only deployments in dense metropolitan construction zones without auxiliary inertial correction.
Strategic Opportunities
- Mining Automation:Hazardous-environment durability requirements in underground and open-pit operations command premium pricing for ruggedized survey instruments with explosion-proof certifications.
- Regulatory Tailwind:The FAA's expanding framework for unmanned aerial systems enables photogrammetric survey via certified drone platforms, opening new service revenue streams for equipment-software bundles.
- Technology Convergence:Integration of SLAM-based mobile mapping with traditional total station workflows allows single-operator capture of complex interior and exterior environments, collapsing survey timelines for facility documentation.
Industry Challenges
- Geodetic Expertise Scarcity:Field crews proficient in ISO 17123 test procedures and network adjustment mathematics are retiring faster than training pipelines replenish, constraining deployment velocity for high-precision projects.
- Certification Timeline Compression:GB standards enforcement by China's SAMR and parallel EU CE marking requirements force parallel testing tracks, stretching product validation cycles and delaying market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Land Survey Equipment Market |
| Market Size in 2026 | $7.4 Billion |
| Market Size in 2035 | $13.38 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Equipment Type: Theodolites, Total Stations, GPS/GNSS Receivers, Levels Application: Construction, Mapping, Mining, Agriculture End User: Civil Engineering Firms, Government Agencies, Surveying Companies, Architects Technology: Optical Instruments, Electronic Measurement, Satellite Navigation, Robotics |
| Companies Covered | Trimble Inc., Hexagon AB, Topcon Corporation, Leica Geosystems AG, CHC Navigation, South Surveying & Mapping Instrument Co., Ltd., STONEX Srl, Shanghai Huace Navigation Technology Ltd., Sokkia Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Land Survey Equipment Market Emerging Trajectories
Survey instrumentation is converging around software-defined measurement architectures that decouple hardware acquisition from data processing workflows, compressing the traditional equipment-service boundary.
LiDAR scanning is migrating from static tripod-mounted configurations to handheld and vehicle-integrated mobile platforms. Mining operators and transportation agencies deploy these systems for rapid as-built documentation and clearance verification. This migration from fixed-base to dynamic capture modes is collapsing survey crew sizes and compressing project timelines from weeks to days.
REACH restrictions on hazardous substances in electronics, coupled with EU Green Deal circularity requirements, are forcing redesigns of battery-powered field instruments. Manufacturers must substitute lead-acid and certain lithium chemistries while maintaining IP ratings and thermal tolerance. European environmental compliance is now a gatekeeper for premium channel access, with distributors demanding full material disclosure upstream.
Equipment-as-a-service models are displacing capital purchase structures among mid-tier construction contractors. Rental and subscription channels now bundle hardware, calibration, and cloud-based data processing into single monthly fees. This shift concentrates most visibly in the United States, where contractor bonding constraints and project-based cash flows favor operational expenditure treatment over balance-sheet asset ownership.
Land Survey Equipment Market Segmentation
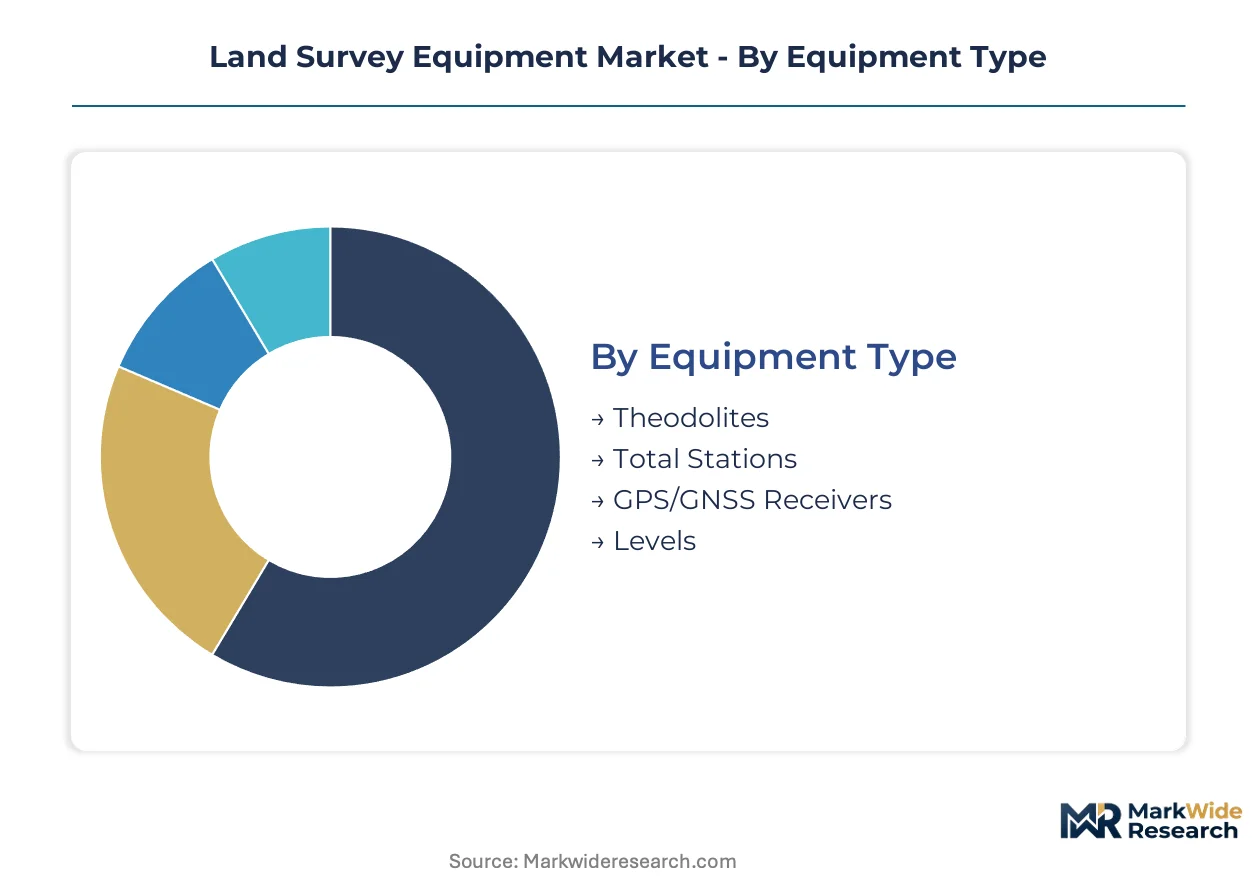
Segmentation in land survey equipment determines service contract structures and calibration revenue streams. Manufacturers configure after-sales networks differently across equipment types and end-user profiles, with precision-grade instruments demanding intensive field support.
Equipment Type:
After-sales-service intensity varies sharply by equipment category, with high-precision GNSS receivers requiring continuous firmware updates and network correction subscriptions.
- GPS/GNSS Receivers:Satellite-based positioning systems integrate multi-constellation signal processing with real-time kinematic correction. Demand concentrates in United States construction automation, where FAA-regulated drone integration and machine guidance adoption pull high-margin receiver sales. Firmware update subscriptions and network correction services generate recurring revenue streams that exceed hardware margins over equipment lifecycles.
- Total Stations:Electronic theodolite-distance meter combinations deliver angular and linear measurements through integrated reflectorless EDM technology. Germany's federal rail and highway programs mandate millimeter-grade accuracy specifications, pulling robotics-enabled units into public procurement pipelines. These instruments demand intensive calibration protocols under ISO 17123 standards, creating captive service relationships between manufacturers and surveying contractors.
- Theodolites:Optical angle-measurement instruments serve educational and legacy cadastral applications with minimal electronic complexity. India's CEA transmission corridor mandates bypass these units in favor of 3D-capable alternatives.
- Levels:Elevation-determination instruments span automatic, digital, and laser configurations for grading and drainage layout. China's MIIT certification requirements for cadastral equipment increasingly exclude basic optical levels from government contract eligibility.
GPS/GNSS Receivers hold the largest share; momentum sits with Total Stations as labor costs rise on complex sites.
Application:
Cost tier stratification separates hazardous-environment mining deployments from commoditized agricultural guidance systems.
- Construction:Site preparation, structural layout, and machine guidance operations absorb dominant unit demand across infrastructure and commercial building verticals. United States contractors embed satellite-guided positioning directly into earthmoving equipment workflows, collapsing traditional survey crew structures. Project-based cash flows favor rental and subscription models over capital purchases.
- Mining:Underground and open-pit operations require explosion-proof certifications and hazardous-environment durability specifications. Premium pricing reflects thermal tolerance, ingress protection, and shock resistance requirements that exceed standard construction-grade instruments. Australia's surface mining automation and Chile's copper extraction operations command the steepest price premiums for ruggedized LiDAR and robotic total station deployments.
- Mapping:Cadastral boundary determination and topographic documentation serve government land administration and utility corridor planning. China's tightened GB standards enforcement elevates precision requirements for state-contracted survey operations.
- Agriculture:Precision farming applications leverage sub-meter GNSS guidance for planting, spraying, and harvesting automation. Price compression dominates as equipment commoditizes and subscription-based correction services displace hardware differentiation.
Construction commands the largest volume base; Mining delivers the steepest margin expansion trajectory.
End User:
Customer type dictates procurement authority and platform ecosystem lock-in susceptibility.
- Civil Engineering Firms:Infrastructure designers and construction managers integrate survey data directly into BIM workflows. These users prioritize interoperability with Autodesk and Bentley software ecosystems over hardware brand loyalty. Germany's rail modernization contractors exemplify this integration-heavy profile.
- Surveying Companies:Professional land surveyors maintain instrument fleets across multiple technology generations. Calibration certification requirements and technician training investments create high switching costs. India's CEA-mandated digital terrain modeling expands their addressable service scope into 3D laser scanning.
- Government Agencies:Cadastral authorities and transportation departments specify precision grades through procurement regulations. China's MIIT and SAMR certification frameworks constrain foreign supplier participation in state-funded mapping projects.
- Architects:Building designers deploy handheld and terrestrial scanning for as-built documentation and heritage preservation. SLAM-based mobile mapping adoption is climbing fastest among this segment as single-operator capture collapses facility survey timelines.
Civil Engineering Firms represent the deepest account penetration; Surveying Companies are gaining share fastest through mandated 3D service expansion.
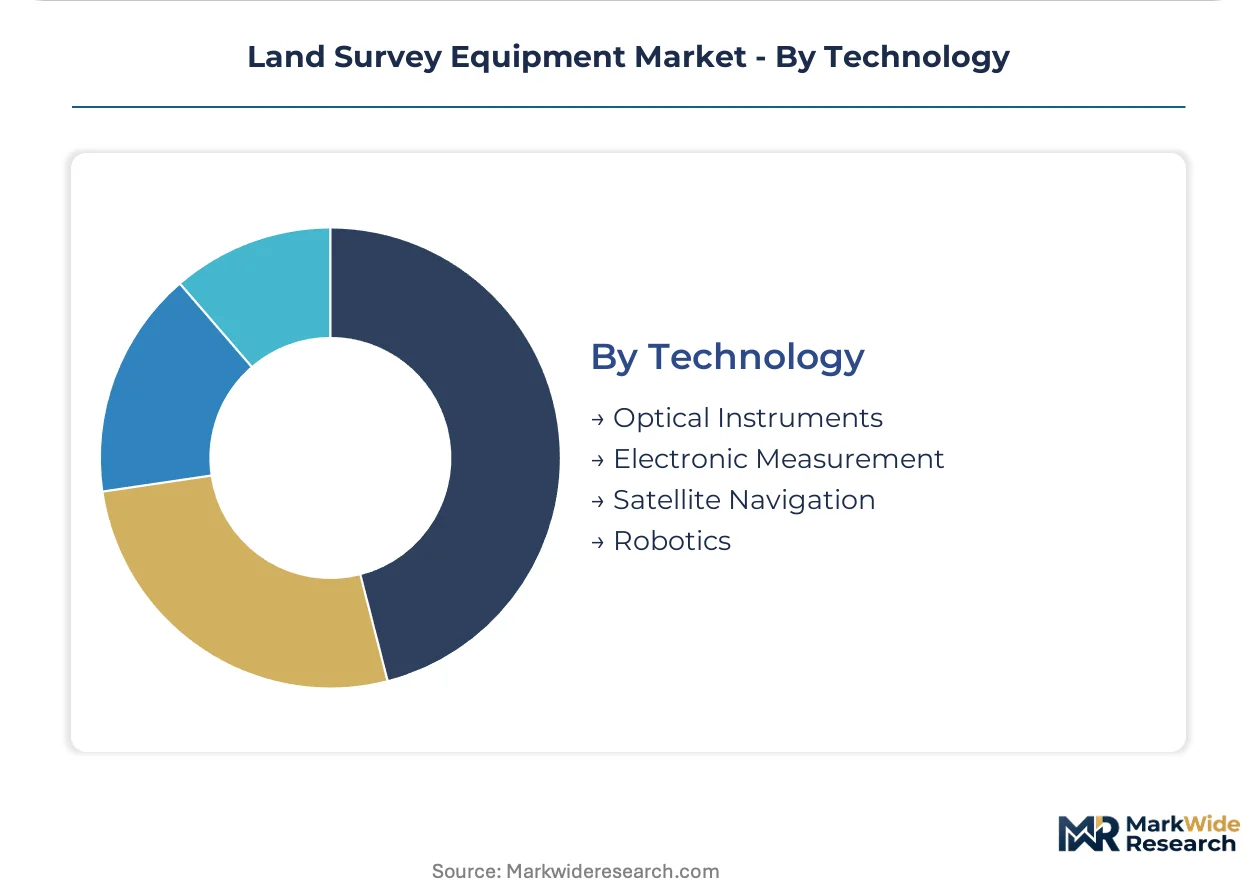
Technology:
Maturity gradients separate established optical methods from converging robotics and satellite navigation architectures.
- Satellite Navigation:Multi-constellation GNSS with inertial measurement unit fusion enables real-time positioning without line-of-sight constraints. Signal multipath in urban canyons limits standalone deployment, driving auxiliary sensor integration. United States construction automation and German rail surveying anchor demand concentration.
- Robotics:Motorized total stations with automatic target recognition enable single-operator surveying on complex sites. Labor cost inflation across Japan's aging construction workforce and South Korea's infrastructure programs accelerates replacement of manual instruments. These units command the steepest price premiums and generate intensive service attachment.
- Electronic Measurement:Digital levels, laser distance meters, and electronic theodolites occupy mid-tier precision applications. China's GB standards enforcement increasingly mandates electronic verification protocols that accelerate obsolescence of analog alternatives.
- Optical Instruments:Traditional transit and level configurations persist in educational and developing-market applications. REACH restrictions and EU Green Deal circularity requirements force battery and material redesigns that erode cost advantages.
Satellite Navigation maintains the largest installed base; Robotics is expanding most quickly as workforce constraints intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision instrumentation exports flow predominantly to United States infrastructure contractors and Chinese state mapping bureaus, establishing a bilateral trade corridor that shapes regional equipment specifications and certification standards.
United States
FAA-regulated unmanned aerial systems and machine-guided earthmoving equipment absorb high-precision GNSS receivers across Texas and California megaprojects. Construction automation mandates from federal highway programs compress survey timelines. Dallas-Fort Worth and Houston metro corridors concentrate contractor fleet upgrades.
Germany
Federal rail and highway modernization programs mandate millimeter-grade surveying accuracy, pulling robotics-enabled total stations into public procurement. KBA transportation standards intersect with EU CE marking requirements for cross-border equipment certification. Bavaria and Baden-Württemberg host precision manufacturing clusters serving domestic and export demand.
China
MIIT tightened certification requirements for GNSS receivers used in cadastral mapping, elevating barriers for imported equipment. SAMR enforces GB standards for electronic measurement accuracy. Yangtze River Delta and Pearl River Delta manufacturing bases dominate domestic sensor production and state-contracted survey operations.
India
CEA-mandated digital terrain modeling for transmission corridor approvals expands demand for 3D laser scanning solutions. BIS standards enforcement accelerates obsolescence of analog optical instruments. Maharashtra and Gujarat infrastructure corridors concentrate utility-scale survey contracting activity.
Australia
Surface mining automation across Western Australia and Queensland commands premium pricing for ruggedized LiDAR and robotic total stations. Hazardous-environment durability specifications exceed standard construction-grade requirements. Perth and Brisbane serve as distribution hubs for Asia-Pacific mining operations.
Land Survey Equipment Market Vendor Landscape
Channel-controlling players compete with product-specialist players across tiered equipment categories. The vendor base stratifies between precision-grade GNSS providers, robotics-enabled total station manufacturers, and mid-tier electronic instrument fabricators. Three archetypes dominate: integrated sensor-software platforms, component-specialist assemblers, and rental-service channel operators. Consolidation pressure intensifies through backward integration into MEMS sensor manufacturing and geographic expansion via distributor acquisition.
Among North American and European platform providers, Trimble Inc. and Hexagon AB exemplify the integrated sensor-software archetype with captive ecosystem control. Topcon Corporation anchors the robotics-specialist tier with concentrated presence across Japanese and broader Asian construction automation markets. These three entities occupy positions that span premium pricing bands and intensive service-attachment revenue pools.
| Leading Market Players |
|---|
| Trimble Inc. |
| Hexagon AB |
| Topcon Corporation |
| Leica Geosystems AG |
| CHC Navigation |
| South Surveying & Mapping Instrument Co., Ltd. |
| STONEX Srl |
| Shanghai Huace Navigation Technology Ltd. |
| Sokkia Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Overcapacity in East Asian MEMS sensor foundries is compressing component pricing while simultaneously eroding supplier bargaining power, forcing equipment manufacturers to absorb margin pressure or accelerate backward integration into captive sensor production.
Pricing Analysis
Technology-generation pricing gaps separate current-gen multi-constellation GNSS receivers from prior-gen single-frequency units and emerging SLAM-integrated mobile mapping platforms. The dominant pricing structure combines hardware transaction with recurring subscription tiers for firmware updates and network correction services. Price differentiation hinges on ISO 17123 certification grade and after-sales service bundling intensity. Cost compression in mid-tier electronic instruments is intensifying because China's GB standards enforcement accelerates analog obsolescence. Agricultural guidance buyers exhibit highest price sensitivity; mining automation purchasers show lowest sensitivity due to hazardous-environment durability requirements.
Supply Chain Analysis
Upstream feedstock dependencies center on precision MEMS accelerometers, high-grade optical glass, and lithium-ion battery cells. Manufacturing concentrates in China, Japan, and Germany for sensor fabrication, optical component grinding, and final assembly respectively. Supply chain risk rests on single-source vulnerability for military-grade inertial measurement units subject to export control restrictions. Distribution runs through authorized dealer networks with captive calibration laboratories, though equipment-as-a-service platforms are consolidating channel control in the United States.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity is expanding as multi-constellation GNSS integration with inertial measurement units fractures the traditional total station hierarchy, creating specialized niches for robotics-enabled single-operator systems and SLAM-based mobile mapping platforms.
For Market Incumbents: Insulate high-precision agriculture and construction workflow dominance through backward integration into MEMS sensor manufacturing and software ecosystem lock-in. Accelerate R&D intensity in machine guidance integration to preempt substitute threats from drone-based photogrammetry platforms. Channel control through captive calibration networks remains essential for robotics-enabled total station segments.
For New Entrants and Emerging Players: Pursue white-space expansion in India's CEA-mandated 3D laser scanning solutions for transmission corridor approvals and Australia's ruggedized mining automation equipment. The most penetrable segment lies in mid-tier construction robotics across Southeast Asian infrastructure markets. A software-defined measurement architecture go-to-market angle collapses hardware differentiation barriers.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across equipment-as-a-service subscription platforms, shifting value capture from manufacturing scale toward data workflow control. Long-term viability favors integrated sensor-software platform archetypes with recurring revenue attachment rates exceeding hardware margins. The signal to watch is FAA unmanned aerial systems certification velocity as a proxy for photogrammetric survey substitution pressure.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MEMS Sensor Manufacturing | Captive supply of precision inertial components reduces exposure to East Asian foundry allocation constraints. |
| Software-Defined Measurement Architecture Launch | Decouples hardware acquisition from cloud-based data processing workflows, compressing equipment-service boundaries. |
| Equipment-as-a-Service Platform Expansion | Bundles calibration, firmware updates, and network corrections into monthly subscriptions favored by project-based contractors. |
| SLAM-Based Mobile Mapping Integration | Enables single-operator capture of complex interior-exterior environments, collapsing facility survey timelines for architects. |
| Certification Investment in China's MIIT Framework | Unlocks state-contracted cadastral mapping procurement pipelines previously restricted to domestic suppliers. |
Methodological Framework
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Primary research incorporated structured discussions with surveying company fleet managers, civil engineering firm BIM integration leads, mining operations automation directors, and government cadastral authority procurement officers. Secondary validation drew from FAA UAS certification databases, China's MIIT equipment approval registries, India's CEA transmission corridor documentation requirements, and ISO 17123 calibration protocol standards. Bottom-up equipment shipment analysis and top-down infrastructure spending allocation models were reconciled through iterative triangulation.
Calibration against historical CAGRs and elasticity parameters derived from construction automation adoption curves shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include equipment type, application vertical, end-user procurement authority, and technology maturity tier. CAGRs were derived from slope-intercept fitting to infrastructure spending trajectories and machine guidance penetration assumptions. Industry-specific forecast inputs incorporated Germany's federal rail modernization procurement timelines and United States FAA unmanned aerial systems regulatory velocity.
Sensitivities concentrate around China's MIIT certification timeline compression and REACH restriction enforcement on battery chemistry redesigns. Forecasts reflect assumptions regarding multi-constellation GNSS signal availability and inertial measurement unit cost curves. Cross-checking against Germany's KBA transportation equipment approval benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Bottle Jack Market
Tools
Horizontal Milling Machine Market
Tools
Stand Tile Saw Market
Tools
Portable Tools Market
Tools
Grabber Pole Market
Tools
Mechanical Hand Tools Market
Tools
Vise-Grip Pliers Market
Tools
DIY Ball Mill Market
Tools
Auger Drill Bits Market
Tools
Europe Machine Tools Market
Tools
Portable Rolling Toolbox Market
Tools
Power Press Machines Market
Tools
Drill Set Market
Tools
Clamps Market
Tools
Air Hammer Market
Tools
Trim Press Market