
 Steel Measuring Tape Market | 2026-2036
Steel Measuring Tape Market Size, Share, and Industry Trends Forecast 2026-2036
Steel Measuring Tape Market Analytics
The EU Green Deal's embodied carbon disclosure mandates for construction inputs is consolidating procurement standards across European building supply chains. Stanley Black & Decker leverages its North American distribution density to sustain volume leadership in contractor-grade tapes. Hultafors anchors Nordic premium positioning through hardened steel blade formulations and ergonomic casing patents. Tajima competes aggressively in Asian precision trades with specialized metric-dominant product lines.
A steel measuring tape consists of a thin, flexible steel ribbon housed within a coiled spring mechanism, typically graduated in metric or imperial units and engineered with concave cross-sectional curvature to maintain rigidity when extended horizontally. Blade thickness commonly ranges from 0.10 mm to 0.15 mm, with nylon or polyester coatings applied to resist abrasion and corrosion in jobsite conditions. Heavy Duty tapes command the largest revenue share among product types due to contractor replacement cycles and theft-related repurchase frequency. The DIY Enthusiast end-user segment exhibits the fastest volume expansion, driven by home improvement retail penetration and online tutorial-driven tool acquisition. Dual Scale measurement configurations are gaining preference in export-oriented manufacturing hubs where imperial-metric interoperability reduces inventory duplication.
REACH chemical compliance in Europe and OSHA blade-edge safety guidelines in the United States both elevate testing costs for new market entrants while reinforcing incumbent quality reputations. China's GB standards for measuring tool accuracy classes and India's BIS certification requirements for steel products create parallel but non-harmonized compliance pathways that fragment supplier qualification overhead. Stakeholders must track evolving carbon border adjustment mechanisms and raw material traceability rules to anticipate which sourcing configurations will sustain market access.
Market Dynamics
The EU Green Deal's embodied carbon tracking mandates are forcing steel measuring tape manufacturers to requalify their supply chains around lower-carbon steel sourcing, compressing margins for non-compliant producers while advantaging early adopters with verified mill certificates.
Growth Catalysts
- Residential construction acceleration:Vietnam's urban corridor around Ho Chi Minh City generates sustained replacement demand for contractor-grade tapes as high-rise residential towers multiply.
- REACH chemical compliance:European regulatory pressure on coating formulations is consolidating procurement toward certified suppliers with verified nylon-polyester blend documentation.
- Dual Scale standardization:Export-oriented manufacturing hubs in Southeast Asia are converging on imperial-metric interoperability to reduce inventory duplication across trade lanes.
Market Restraints
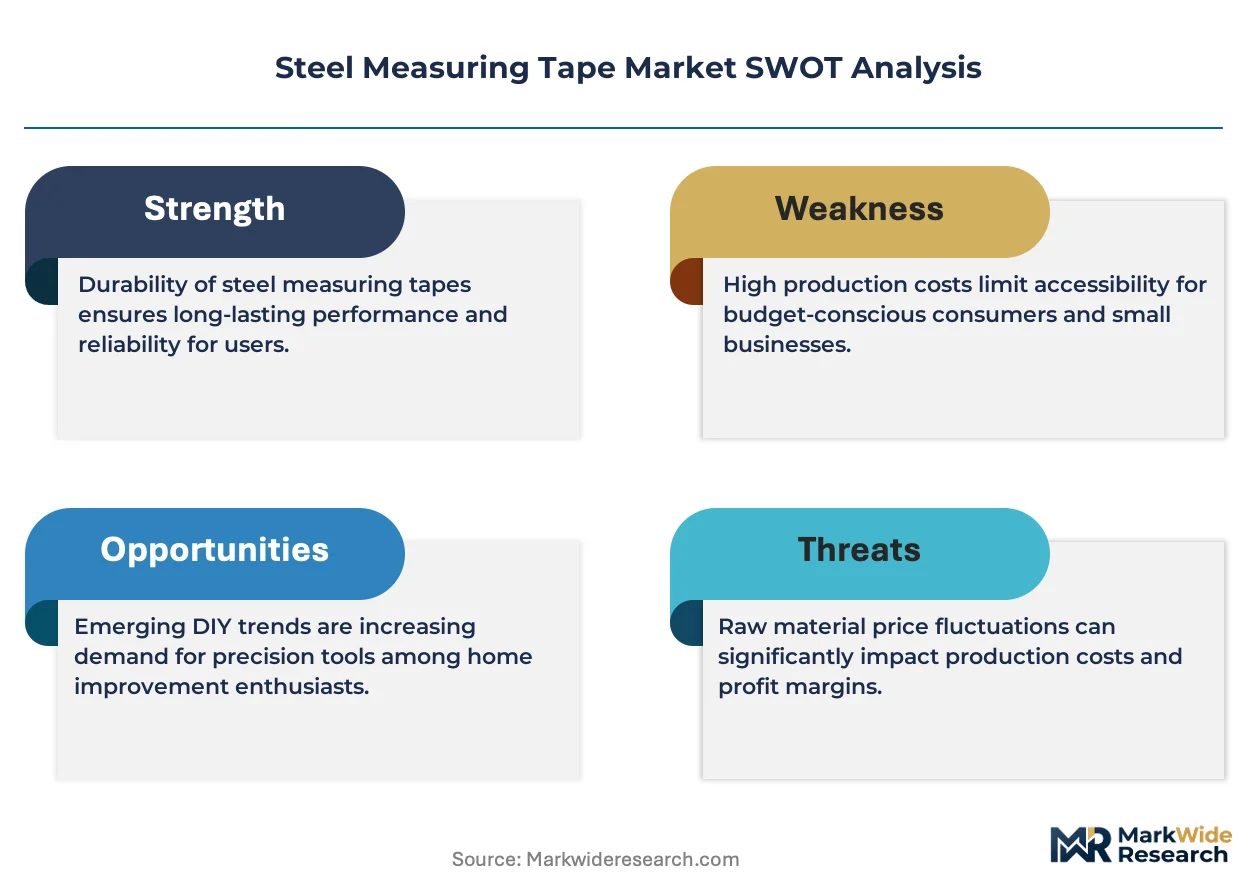
- Steel price volatility:Cold-rolled steel coil input costs fluctuate with energy-intensive European mill production curbs, squeezing blade manufacturing margins unpredictably.
- Supply concentration risk:Hardened steel blade substrate production clusters in a narrow band of German and Japanese specialty mills, creating single-source vulnerability.
- Digital measurement substitution:Laser distance meters and smartphone-based augmented reality measuring tools are capturing precision trades previously served by manual tapes.
Strategic Opportunities
- Carbon border adjustment positioning:The EU's CBAM implementation creates first-mover advantage for manufacturers with documented low-carbon steel procurement from Nordic electric-arc furnace mills.
- DIY retail channel expansion:Home improvement retail penetration in India's tier-2 cities enables volume scaling through organized distributor networks previously focused on professional trades.
- Ergonomic casing patent licensing:Premium ergonomic grip formulations developed for Nordic construction cold-weather use are licensable to Southeast Asian manufacturers seeking product differentiation.
Industry Challenges
- Cross-standard calibration expertise:Simultaneous compliance with China's GB accuracy classes and India's BIS certification requires specialized metrology talent scarce outside established manufacturing regions.
- Coating formulation requalification:REACH-compliant abrasion-resistant nylon-polyester blends demand 18-24 month testing cycles before European market entry, delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Steel Measuring Tape Market |
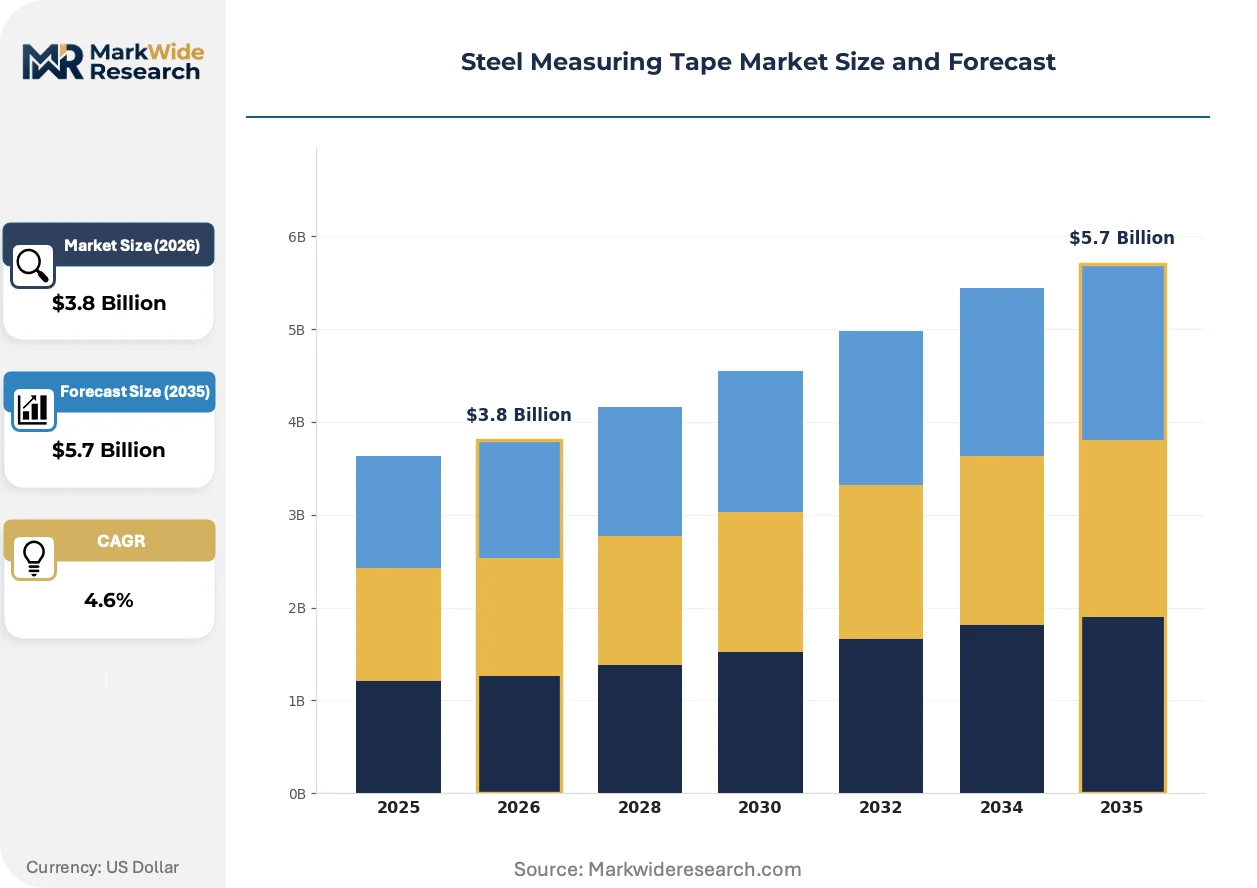
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Auto Lock, Heavy Duty, Pocket Size, Mini Tape End User: Construction, Carpentry, Civil Engineering, DIY Enthusiasts Length: 25 Feet, 50 Feet, 100 Feet, 16 Feet Measurement Unit: Imperial, Metric, Dual Scale, Custom |
| Companies Covered | Apex, Pro'skit, Stanley Black & Decker, Hultafors, Endura, Tajima, Starrett, Exploit, Komelon, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Steel Measuring Tape Market Evolving Landscape
Steel measuring tape technology is bifurcating between premium hardened-steel precision instruments and digitally-integrated measurement systems, with coating chemistry and blade metallurgy converging on sustainability-verified supply chains.
Blade metallurgy is overtaking conventional carbon steel formulations in contractor-grade segments. Hardened manganese steel alloys with Rockwell hardness exceeding 50 HRC are penetrating professional construction markets in Germany and Japan. These formulations extend blade life by reducing edge deformation under repeated extension-retraction cycles, compressing replacement frequency for high-use contractors from quarterly to semi-annual intervals.
REACH chemical disclosure requirements are reshaping coating supplier relationships across European building supply chains. Nylon-polyester hybrid coatings must now document full substance-of-very-high-concern screening through ECHA-registered supply chains. German distributors are demanding mill-level carbon intensity certificates for steel substrates, forcing tape assemblers to consolidate procurement around verified low-carbon European and Nordic mills.
Retail channel consolidation is displacing traditional hardware wholesaler networks in Southeast Asian urban markets. Organized home improvement retailers in Vietnam and Indonesia are capturing DIY enthusiast demand through in-store demonstration and bundled tool kit offerings. This shift concentrates volume with price-sensitive private-label suppliers while compressing branded premium positioning in residential renovation verticals.
Steel Measuring Tape Market Segmentation
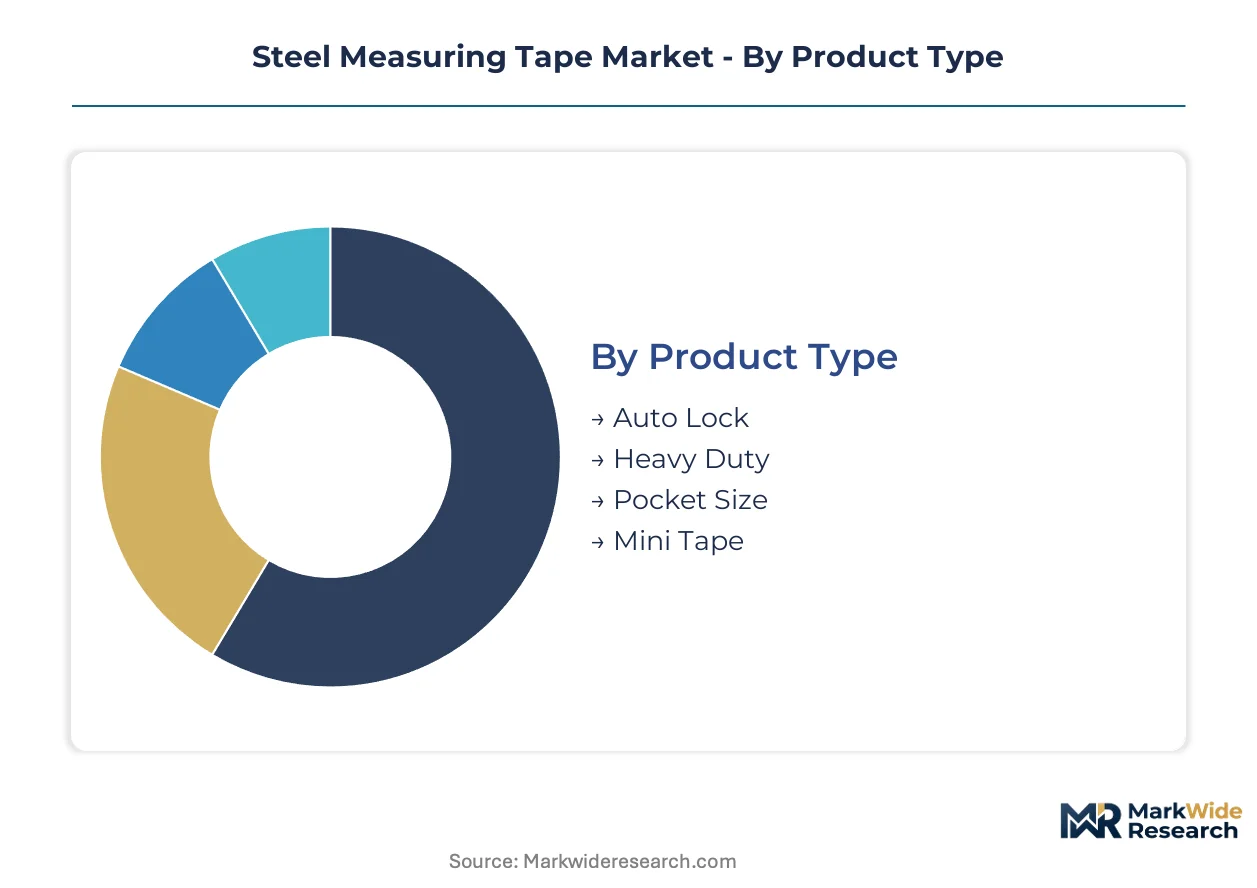
Steel measuring tape segmentation reveals how capital deployment, regulatory compliance, and end-use durability requirements fragment manufacturing priorities across blade metallurgy, casing engineering, and coating chemistry tiers.
Product Type:
Capital intensity peaks with hardened steel blade formulations and spring mechanism precision engineering.
- Heavy Duty:Reinforced blade substrates with Rockwell hardness exceeding 50 HRC withstand repeated extension-retraction cycles in high-use contractor environments. Demand concentrates in Germany and Japan where professional trades prioritize extended replacement intervals over upfront cost. REACH-compliant coating requalification elevates testing overhead for new entrants.
- Auto Lock:Spring-loaded braking mechanisms require tighter tolerance control in coiled housing assembly, raising per-unit tooling investment. Vietnam's Ho Chi Minh City urban corridor generates sustained replacement volume as high-rise residential construction accelerates.
- Pocket Size:Compact casing designs prioritize ergonomic grip patents over blade length capacity.
- Mini Tape:Reduced blade width demands specialized slitting equipment with narrower capital depreciation windows.
Most installed capacity flows through Heavy Duty. Expansion is steepest in Auto Lock.
End User:
Margin structure diverges sharply between price-sensitive retail channels and specification-driven professional procurement.
- Construction:Contractor-grade specifications mandate hardened manganese steel alloys with documented mill certificates for carbon intensity. German and Japanese specialty mills dominate substrate supply, creating single-source vulnerability for tape assemblers.
- DIY Enthusiasts:Home improvement retail penetration in India's tier-2 cities drives volume scaling through organized distributor networks. Online tutorial-driven tool acquisition accelerates replacement frequency beyond functional wear.
- Carpentry:Precision-focused trades demand metric-dominant product lines with fractional readability.
- Civil Engineering:Extended length requirements favor 100-foot configurations with reinforced blade rigidity.
Construction commands the largest revenue share. DIY Enthusiasts are climbing the fastest.
Length:
Blade extension physics and coiled housing diameter dictate manufacturing equipment scale economies.
- 25 Feet:Standard contractor configuration balancing portability with vertical measurement reach. Dual Scale standardization in Southeast Asian export hubs reduces inventory duplication across imperial-metric trade lanes.
- 100 Feet:Extended blade length requires thicker substrate to prevent horizontal sag, raising cold-rolled steel coil input costs. OSHA blade-edge safety guidelines elevate testing costs for new market entrants in the United States.
- 50 Feet:Intermediate specification serving mixed residential-commercial trades.
- 16 Feet:Compact format targeting household renovation and interior measurement tasks.
25 Feet dominates unit volume. 100 Feet shows the steepest margin compression from steel price volatility.
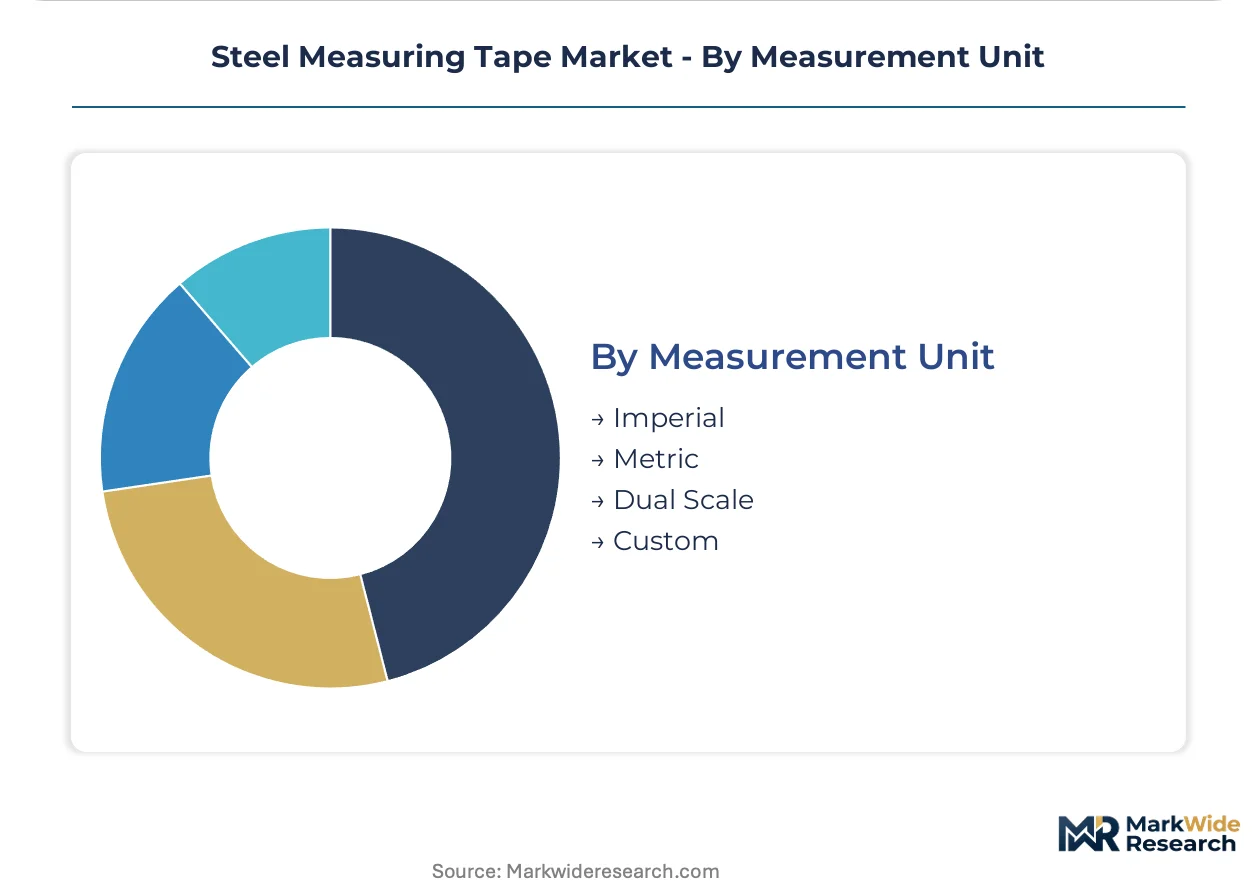
Measurement Unit:
Calibration infrastructure and metrology talent requirements fragment supplier qualification pathways.
- Dual Scale:Imperial-metric interoperability reduces inventory duplication for export-oriented manufacturers in Vietnam and Indonesia. Simultaneous compliance with China's GB accuracy classes and India's BIS certification demands specialized cross-standard expertise scarce outside established manufacturing regions.
- Metric:Dominant specification in European and Asian precision trades with established JIS and GB calibration protocols. EU Green Deal embodied carbon tracking mandates force requalification around lower-carbon steel sourcing.
- Imperial:North American standard with entrenched contractor preference patterns.
- Custom:Specialized graduations for nautical, surveying, or theatrical applications.
Dual Scale captures the fastest share gain. Metric retains the deepest installed base in professional trades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel measuring tape manufacturing originated in European and North American industrial centers during the late 19th century, with precision metalworking traditions in Germany and the United States establishing foundational blade metallurgy standards that persist today.
Germany
Professional construction trades in Bavaria and North Rhine-Westphalia drive specification-grade procurement of hardened manganese steel tapes. REACH chemical disclosure requirements through ECHA-registered supply chains mandate full substance-of-very-high-concern screening for coating formulations. German specialty mills in the Ruhr industrial corridor dominate hardened steel blade substrate production, creating concentrated sourcing for European tape assemblers.
United States
Contractor-grade replacement cycles and theft-related repurchase frequency sustain volume demand across residential and commercial construction verticals. OSHA blade-edge safety guidelines elevate testing costs for new market entrants while reinforcing incumbent quality reputations. Distribution density in the Midwest and Southeast manufacturing belt supports volume leadership positions for established tool brands.
Japan
Precision-focused trades in the Kanto and Kansai regions demand metric-dominant product lines with fractional readability and extended blade life. JIS calibration protocols establish metrology standards that professional contractors prioritize over upfront cost considerations. Specialty mills in the Chubu industrial region supply hardened steel substrates with Rockwell hardness exceeding 50 HRC for professional-grade tape formulations.
Vietnam
High-rise residential tower construction in the Ho Chi Minh City urban corridor generates sustained replacement demand for contractor-grade and auto-lock tape configurations. Export-oriented manufacturing hubs converge on dual-scale imperial-metric interoperability to reduce inventory duplication across trade lanes. Organized home improvement retailers in Hanoi and Da Nang are displacing traditional hardware wholesaler networks through bundled tool kit offerings.
India
Home improvement retail penetration in tier-2 cities drives volume scaling through organized distributor networks previously focused on professional trades. BIS certification requirements for steel products create compliance pathways that fragment supplier qualification overhead for new entrants. The Delhi-NCR and Maharashtra industrial clusters host emerging tape assembly operations serving domestic price-sensitive segments.
Steel Measuring Tape Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the steel measuring tape industry, with integrated blade metallurgy operations facing pressure from specialized assemblers sourcing substrates from third-party mills. The vendor base clusters around three strategic archetypes: diversified tool conglomerates with North American distribution density, Nordic premium specialists with ergonomic casing patents, and Asian precision players with metric-dominant product lines. Competitive moves concentrate on strategic partnerships with certified coating suppliers and geographic expansion through organized retail channel penetration.
Among diversified tool conglomerates, Stanley Black & Decker occupies a position exemplifying volume leadership through contractor-grade distribution networks. Hultafors AB represents the Nordic premium archetype with hardened steel blade formulations and ergonomic grip patents developed for cold-weather construction use. Tajima Tool Corporation anchors the Asian precision tier with specialized metric-dominant product lines serving professional trades across Japan and Southeast Asian export markets.
| Leading Market Players |
|---|
| Apex |
| Pro'skit |
| Stanley Black & Decker |
| Hultafors |
| Endura |
| Tajima |
| Starrett |
| Exploit |
| Komelon |
| Others |
Value Network & Pricing Analysis
The EU Green Deal's embodied carbon disclosure mandates gate both qualified supply and premium-tier pricing access, as tape assemblers with verified low-carbon mill certificates command contractor-grade price premiums while non-compliant producers absorb margin compression from carbon border adjustment exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by blade metallurgy grade and REACH certification status. Price differentiation separates hardened manganese steel formulations with Rockwell hardness exceeding 50 HRC from standard carbon steel and uncoated economy variants. Pricing pressure stems from cold-rolled steel coil input volatility driven by European mill production curbs. DIY enthusiasts exhibit highest price sensitivity, while German and Japanese professional trades prioritize extended replacement intervals over upfront cost.
Supply Chain Analysis
Specialized metrology talent scarcity in emerging assembly regions constrains capacity expansion outside established manufacturing corridors. Hardened steel blade substrate production concentrates in German and Japanese specialty mills, with coating chemistry sourcing anchored in ECHA-registered European supply chains. Raw material dependencies rest on cold-rolled steel coil, nylon-polyester hybrid coatings, and precision spring mechanisms. Single-source vulnerability in substrate supply creates structural risk. Distribution runs through organized home improvement retailers in Southeast Asia and contractor-grade distributors in North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through carbon-verified supply chain repositioning, as early adopters of Nordic electric-arc furnace steel procurement capture premium pricing power under advancing EU border adjustment mechanisms.
For Market Incumbents: Cement supply chain defensibility through backward integration into verified low-carbon steel procurement from Nordic mills, insulating against carbon border adjustment exposure. Deepen ergonomic casing patent licensing revenue streams to Southeast Asian manufacturers seeking cold-weather construction differentiation. Prioritize REACH-compliant coating requalification to maintain European market access against tightening ECHA substance screening. For New Entrants and Emerging Players: A mid-tier price-point gap between Hultafors premium positioning and private-label economy suppliers creates white-space opportunity in India's tier-2 home improvement retail channels. Target auto-lock tape configurations for Vietnam's Ho Chi Minh City high-rise construction corridor. Pursue dual-scale metric-imperial interoperability as the primary go-to-market angle for export-oriented manufacturing hubs. For Investors and Strategic Acquirers: Roll-up economics work for regional tape assemblers with dormant BIS certification pathways because India's fragmented tier-2 retail expansion rewards scaled distributor networks. Long-term viability hinges on carbon intensity documentation capabilities. Watch for CBAM implementation acceleration as the inflection signal triggering premium-tier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Carbon-Verified Steel Procurement | Secures EU market access under advancing border adjustment mechanisms while commanding contractor-grade price premiums. |
| REACH-Compliant Coating Requalification | Elevates testing overhead that consolidates procurement toward certified suppliers with ECHA-registered supply chains. |
| Ergonomic Casing Patent Licensing | Monetizes Nordic cold-weather construction IP through Southeast Asian manufacturers seeking product differentiation. |
| Dual-Scale Manufacturing Convergence | Reduces inventory duplication for Vietnam and Indonesia export hubs serving imperial-metric trade lanes. |
| Tier-2 Retail Channel Expansion | Captures DIY enthusiast volume scaling through India's organized distributor networks beyond professional trades. |
Research Methodology
Coverage spans Germany, Japan, Vietnam, India, and the United States, with primary inputs from each region's construction procurement managers, tape assembly plant engineers, coating formulation specialists, and home improvement retail category buyers. Secondary validation drew from customs trade data, SEC filings of diversified tool manufacturers, BIS certification registries, and ECHA substance screening databases. Bottom-up unit demand modeling triangulated against top-down construction spending correlations.
Granularity extended to blade metallurgy tier, casing mechanism type, end-user trade vertical, and measurement unit configuration across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by replacement cycle frequency and channel mix shifts. Industry-specific forecast inputs incorporated carbon border adjustment implementation timelines and REACH requalification cycle durations.
Caveats apply where EU carbon border adjustment acceleration or REACH substance list expansion could materially shift the outlook for qualified supply access and premium-tier pricing power. Material deviation in these regulatory triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Broaching Tools Market
Tools
Woodworking Sanders Market
Tools
End Mill Holder Market
Tools
Machine Vise Market
Tools
US Chalk Reel and Line Market
Tools
Cordless Power Drill Market
Tools
Cutting Pipe and Perforating Pipe Drilling Tools Market
Tools
Pipe Alignment Clamps Market
Tools
Global Scarifiers Market
Tools
Global Protractor Market
Tools
Welding Products Market
Tools
Electric Power Tools Market
Tools
Rotary Knife Cutters Market
Tools
Workholding Tools Market
Tools
Digital Laser Levels Market
Tools
Woodcarving Tool Market