
 Handheld Blower Market | 2026-2036
Handheld Blower Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Blower Market Foresight
A shortage of certified small-engine technicians is unwinding traditional service-network advantages for gas-powered models. STIHL leverages its captive dealer-repair infrastructure to sustain loyalty among landscaping professionals who depend on uptime guarantees. Husqvarna anchors its position through geographic dominance in Nordic markets where cold-weather debris cleanup extends seasonal selling windows. Makita competes by extending its battery-platform ecosystem, allowing contractors to share power cells across blowers, trimmers, and saws.
Handheld blowers are portable air-moving devices, typically generating airflow velocities between 100 and 250 miles per hour through centrifugal fan or axial impeller designs, engineered to displace leaves, light debris, and snow from residential, commercial, and municipal surfaces. Gas blowers retain structural importance in commercial fleets where runtime demands exceed current battery energy density, though battery-powered blowers represent the fastest-expanding product category as lithium-ion cell costs decline and charge intervals shrink. Landscaping professionals command the most concentrated margin pool among end users, while homeowners drive absolute unit volume through seasonal replacement cycles at lower price points.
EPA emission standards for small spark-ignition engines are tightening allowable exhaust outputs, compelling manufacturers to invest in catalytic converter integration or abandon two-stroke architectures entirely. OSHA noise-exposure limits for outdoor workers are reshaping product development priorities, with decibel reduction becoming a competitive specification rather than a secondary feature. Stakeholders must monitor how municipal fleet electrification mandates propagate across jurisdictions, as these procurement rules will determine which technology platforms secure long-term institutional contracts.
Market Dynamics
Battery energy density improvements are compressing the runtime advantage that gas-powered handheld blowers held over electric alternatives, forcing manufacturers to reconfigure product portfolios and dealer training programs around cordless platforms.
Growth Catalysts
- EPA emission standards:Tightening exhaust limits on small spark-ignition engines are accelerating manufacturer investment in battery platforms and four-stroke alternatives.
- Landscaping contractor fleet expansion:Commercial groundskeeping contracts are multiplying across suburban municipalities, driving concentrated equipment procurement from professional-grade suppliers.
- Lithium-ion cost curves:Cell price declines are eroding the upfront cost gap between battery and gas blowers, expanding addressable markets for cordless units.
Market Restraints
- Cobalt and lithium supply concentration:Battery raw material sourcing clusters in the Democratic Republic of Congo and Chile create geopolitical exposure for cordless product lines.
- Small-engine technician scarcity:Certified repair infrastructure for gas models is contracting, stranding existing fleet owners without service options.
- Runtime physics:Current lithium-ion energy density fails to match gasoline energy-per-weight ratios for all-day commercial clearing operations.
Strategic Opportunities
- Municipal fleet electrification mandates:Procurement rules in California, New York, and Illinois are creating institutional demand corridors for battery-powered debris management equipment.
- Brushless motor convergence:Integration with existing contractor battery platforms for trimmers and saws enables cross-tool power cell sharing and brand lock-in.
- Snow removal application expansion:Cold-weather debris cleanup in Nordic markets extends seasonal selling windows beyond traditional leaf-clearing cycles.
Industry Challenges
- OSHA noise-exposure compliance:Outdoor worker decibel limits are forcing engineering trade-offs between airflow performance and acoustic suppression.
- Dealer network retraining costs:Transitioning captive service infrastructure from mechanical repair to electronic diagnostics demands capital investment and technician certification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Blower Market |
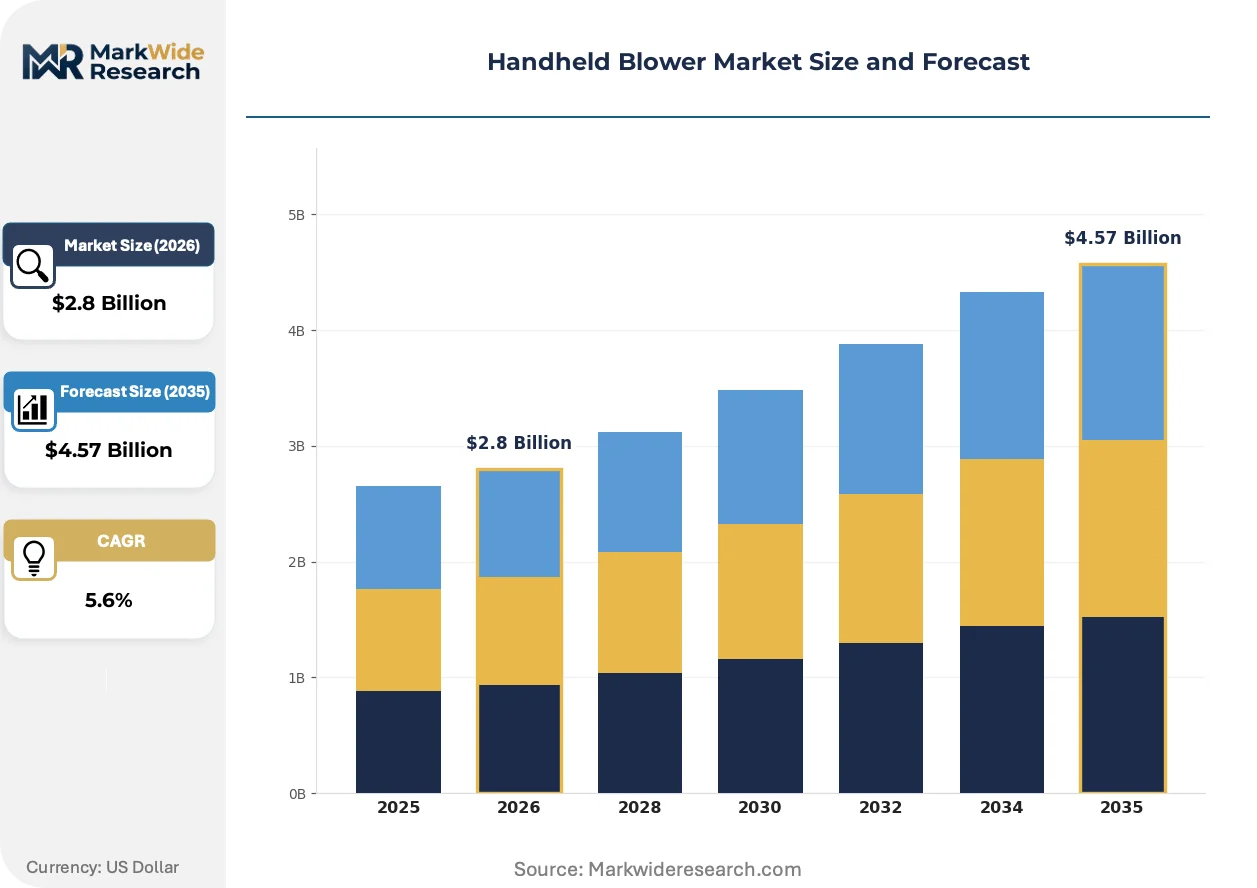
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.57 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Blowers, Gas Blowers, Battery-Powered Blowers, Backpack Blowers End User: Homeowners, Landscaping Professionals, Construction Companies, Municipalities Technology: Brushless Motors, Single Stage, Two Stage, Variable Speed Application: Garden Maintenance, Debris Cleanup, Snow Removal, Leaf Blowing |
| Companies Covered | STIHL, EGO Power+, Husqvarna, Makita, Ryobi, Echo, Black+Decker, Greenworks, Toro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Blower Market Shifts & Advancements
Product development trajectories in handheld blowers are converging on electrification, acoustic engineering, and platform ecosystem integration, with regulatory pressure compressing technology transition timelines.
Brushless DC motor architectures are supplanting brushed designs across mid-tier and premium blower segments. Landscaping contractors operating multi-tool fleets are specifying these motors to extend runtime per battery charge and reduce maintenance intervals. The shift is compressing margins for manufacturers locked into older motor supply contracts while rewarding those with in-house winding capabilities.
OSHA noise-exposure limits for outdoor workers are reshaping product development priorities in the United States, with decibel reduction becoming a competitive specification rather than a secondary feature. Manufacturers are investing in impeller aerodynamics and housing insulation to maintain airflow velocity while suppressing acoustic output. Commercial fleet buyers in California and New York are now specifying sub-65-decibel thresholds as mandatory bid requirements.
Contractor procurement patterns are consolidating around battery-platform ecosystems rather than single-tool purchases. Landscaping professionals are standardizing on brands that offer cross-compatible power cells across blowers, trimmers, and saws, reducing spare inventory costs and simplifying field logistics. This behavior is most visible in the United States, where large regional landscaping firms are negotiating fleet-wide supply agreements with single manufacturers.
Handheld Blower Market Segmentation
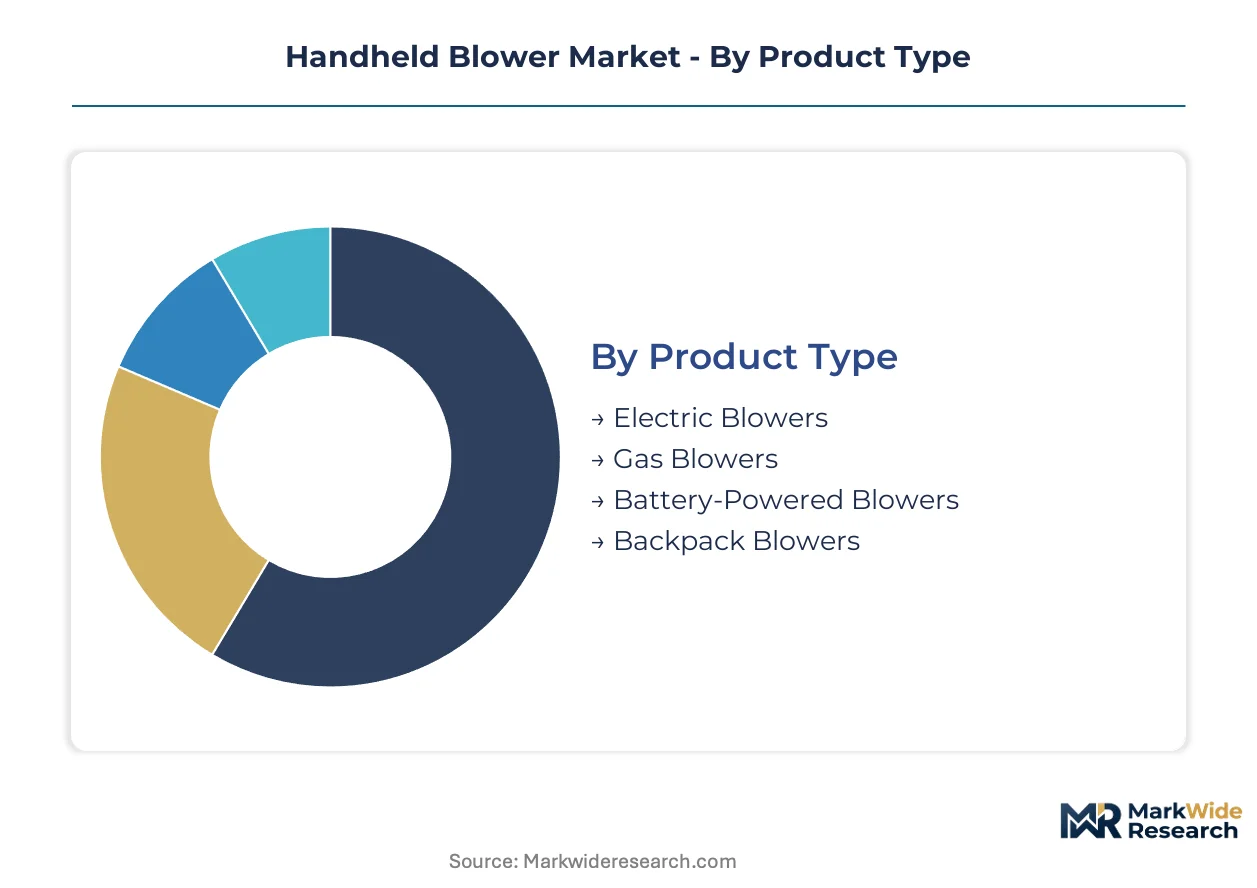
Segmentation in handheld blowers reveals divergent margin pools across powertrain technologies and end-use contracts. Channel strategies must align with whether buyers prioritize upfront acquisition cost, runtime reliability, or cross-platform battery compatibility.
Product Type:
Dealer networks and big-box retail channels carry distinct product mixes, with commercial distributors emphasizing runtime-tested gas units while home centers push cordless alternatives.
- Electric Blowers:Corded designs delivering continuous 120V power through universal residential outlets. Demand clusters in urban Japan and dense European housing where property footprints under 500 square meters eliminate runtime anxiety. OSHA noise thresholds favor these units for daytime municipal operations in noise-restricted districts.
- Gas Blowers:Two-stroke and four-stroke internal combustion engines generating 25cc to 65cc displacement. Landscaping contractors in the United States and Australia specify these for commercial clearing contracts exceeding six continuous hours where battery swap logistics prove uneconomical.
- Battery-Powered Blowers:Lithium-ion cell packs from 18V to 80V configurations. Gaining share fastest among regional landscaping fleets in California and New York where municipal electrification mandates restrict gas procurement.
- Backpack Blowers:Frame-mounted designs distributing engine weight across operator shoulders. Concentrated demand in Nordic markets for extended snow removal operations and in commercial groundskeeping contracts across the United States.
Gas blowers dominate installed base. Battery-powered configurations are where expansion concentrates.
End User:
Margin concentration varies sharply across buyer types, with fleet owners commanding volume discounts while municipalities impose certification burdens that filter supplier pools.
- Homeowners:Seasonal purchasers prioritizing storage compactness and seasonal price promotions. Volume concentrates in United States suburban counties where single-family detached housing exceeds 70% of stock.
- Landscaping Professionals:Commercial operators running 50+ unit fleets with standardized maintenance protocols. These buyers in the United States and Germany negotiate multi-year supply agreements tied to uptime guarantees and dealer service response times.
- Construction Companies:Site-clearing specialists requiring debris displacement ahead of concrete pours and framing. Demand tracks residential construction permit issuance in Australia and the United States Sun Belt.
- Municipalities:Institutional procurement through formal RFP processes with decibel and emission specifications. California, New York, and Illinois agencies are specifying battery platforms for park maintenance and storm debris response.
Homeowners drive absolute unit volume. Landscaping professionals concentrate margin capture.
Technology:
Component sourcing strategies differentiate competitive position, with in-house motor winding capabilities versus outsourced brushless controller procurement reshaping cost structures.
- Brushless Motors:Electronically commutated designs eliminating mechanical brush wear. Premium-tier blowers from Japanese and German manufacturers specify these for contractor fleets where maintenance interval extension justifies 40% price premiums.
- Single Stage:Direct-drive impeller configurations with fixed airflow velocity. Entry-level cordless units for homeowner segments in the United States and United Kingdom employ this simplified architecture.
- Two Stage:Separate fan and turbine stages amplifying pressure differential. Gas-powered commercial units for heavy debris and wet leaf displacement in Pacific Northwest climates.
- Variable Speed:Electronic throttle control enabling airflow modulation. Specified by OSHA-conscious municipalities in California seeking sub-65 decibel operation during restricted hours.
Brushless architectures are climbing the fastest in revenue share. Single-stage designs anchor entry-price positioning.
Application:
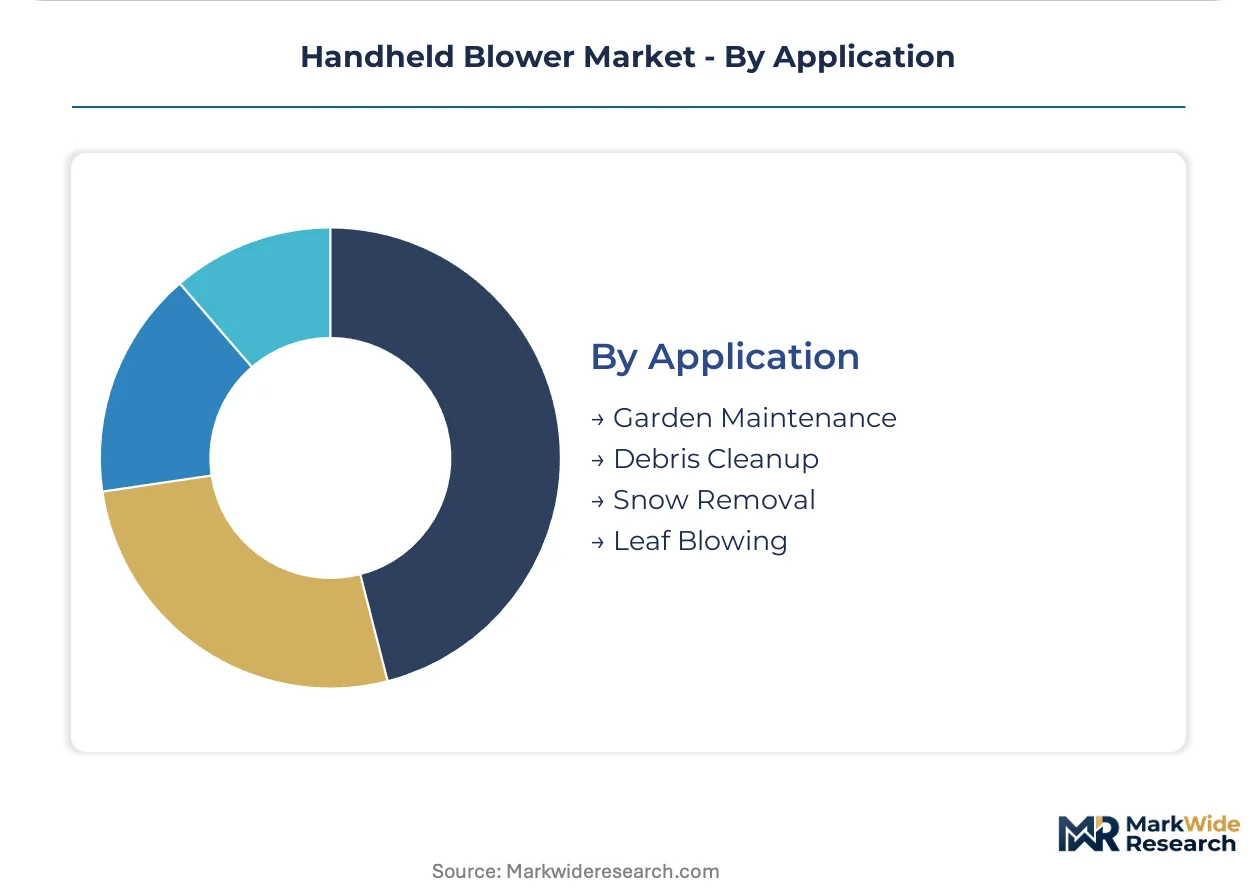
Seasonal demand patterns create inventory management challenges, with snow removal extending revenue windows in cold-climate markets while leaf blowing concentrates Q3 shipments.
- Garden Maintenance:Weekly residential upkeep of lawns, borders, and ornamental beds. Homeowners in the United Kingdom and Germany drive replacement cycles tied to spring retail promotions.
- Debris Cleanup:Post-storm and construction site clearing of gravel, dust, and scattered materials. Commercial contractors in Australia and the United States Gulf Coast specify high-velocity gas units for hurricane response contracts.
- Snow Removal:Cold-weather displacement of powder and packed snow from walkways and parking areas. Nordic markets in Sweden, Norway, and Finland extend selling seasons through February, with backpack configurations preferred for ergonomic load distribution.
- Leaf Blowing:Seasonal autumn clearing of deciduous shed in suburban environments. Municipalities in the United States Northeast run fleet procurement cycles synchronized with October budget renewals.
Leaf blowing dominates seasonal revenue concentration. Snow removal is where geographic expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
OSHA anchors the dominant geography where municipal fleet electrification mandates and suburban property maintenance cycles concentrate procurement volume. EPA emission standards for small spark-ignition engines are compressing technology transition timelines across commercial landscaping operations.
United States
Landscaping contractor fleet expansion and municipal debris management programs drive concentrated equipment procurement. California, New York, and Illinois agencies specify battery platforms through formal RFP processes with sub-65 decibel thresholds. The Pacific Northwest cluster around Seattle and Portland favors high-velocity gas units for wet leaf displacement in marine climates.
Germany
Commercial groundskeeping contracts and cold-weather debris cleanup extend seasonal selling windows. REACH compliance requirements for chemical substances in lubricants and coatings shape product specifications. The Baden-Württemberg industrial corridor hosts precision motor winding capabilities serving brushless DC architectures.
Japan
Urban property footprints under 500 square meters eliminate runtime anxiety for corded electric designs. METI efficiency standards for small electric motors accelerate brushless motor adoption in premium-tier segments. The Kanto region around Tokyo concentrates contractor fleet standardization on cross-compatible battery platforms.
Sweden
Snow removal applications and extended Nordic selling seasons through February drive backpack blower demand. EU Green Deal procurement guidelines favor battery-powered equipment in municipal park maintenance. The Stockholm-Uppsala corridor anchors geographic dominance for cold-weather debris cleanup equipment.
Australia
Construction site clearing and hurricane response contracts require high-velocity debris displacement capabilities. The country's national environmental regulator imposes noise restrictions on outdoor power equipment in urban districts. The Queensland-New South Wales corridor concentrates residential construction permit issuance driving site-clearing demand.
Handheld Blower Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive dealer-repair infrastructure and battery-platform ecosystems defining competitive moats. The structure consolidates around manufacturers controlling vertical integration into motor winding and those anchoring multi-tool compatibility. Three archetypes dominate: integrated engine manufacturers with captive service networks, power tool conglomerates leveraging battery ecosystem lock-in, and specialist outdoor power equipment brands with regional geographic focus. Dominant competitive moves include portfolio diversification into brushless motor architectures and strategic partnerships securing lithium-ion cell supply.
Within the integrated engine tier, STIHL and Husqvarna represent archetypes of dealer-network-dependent positioning, while Makita occupies a position exemplifying battery-platform ecosystem expansion. STIHL leverages its German GmbH structure to anchor professional-grade loyalty through uptime guarantees. Husqvarna's Swedish corporate form supports Nordic market dominance where cold-weather applications extend revenue windows. Makita's Japanese Co., Ltd. structure enables cross-tool power cell standardization across regional landscaping fleets in California and New York.
| Leading Market Players |
|---|
| STIHL |
| EGO Power+ |
| Husqvarna |
| Makita |
| Ryobi |
| Echo |
| Black+Decker |
| Greenworks |
| Toro |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between lithium-ion cell suppliers and handheld blower manufacturers lock in both cobalt access and price visibility across multi-year production cycles. These contracts insulate tier-one brands from spot-market volatility while stranding smaller competitors on quarterly procurement cycles.
Pricing Analysis
United States pricing runs 15-25% above Nordic markets due to dealer-service bundling and EPA compliance certification costs. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor contractor units from entry-level homeowner cordless designs. Cost compression in the battery-powered tier is intensifying because lithium cell prices are declining faster than gas-engine component costs. Homeowners exhibit the highest price sensitivity, while landscaping professionals prioritize uptime guarantees over per-unit acquisition cost.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell fabrication, with Japan supplying precision brushless motor controllers and Germany contributing injection-molded housing components. The industry draws from cobalt concentrates in the Democratic Republic of Congo, lithium brine from Chile, and rare-earth magnets from China's processing corridors. Single-source vulnerability concentrates in cathode active material supply, where three producers control over half of global capacity. Distribution runs through captive dealer networks for commercial-grade units and big-box retail for homeowner segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward regional landscaping firms consolidating fleet procurement under single-source agreements, compressing supplier margins and demanding extended warranty terms.
For Market Incumbents: Shield market share by deepening captive repair infrastructure for battery diagnostics and securing exclusive lithium cell offtake with tier-one chemistry suppliers. EPA emission tightening threatens gas-powered revenue streams; vertical integration into brushless motor winding preserves margin capture as platform ecosystems consolidate. For New Entrants and Emerging Players: Lead with municipal fleet electrification mandates in California, New York, and Illinois as the most penetrable demand corridor. Snow removal applications in Nordic markets remain underserved by battery-powered alternatives. A go-to-market angle emphasizing sub-65 decibel OSHA compliance unlocks institutional RFP access. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among manufacturers controlling cross-tool battery platform ecosystems. Long-term viability over the coming decade hinges on lithium chemistry access and dealer network density. Acquisition targets should display in-house motor controller design capabilities. The signal to watch is municipal procurement rule propagation across additional state jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Ecosystem Expansion | Cross-tool power cell compatibility locks in contractor fleet standardization across California and New York operations. |
| Brushless Motor Manufacturing Scale-Up | In-house winding capabilities in Germany's Baden-Württemberg corridor reduce dependency on outsourced controller procurement. |
| Dealer Network Diagnostic Retraining | Electronic troubleshooting certification addresses technician scarcity stranding gas-powered fleet owners without service options. |
| Snow Removal Application Development | Backpack configurations for Nordic markets extend revenue windows beyond traditional autumn leaf-clearing cycles. |
| Municipal Electrification Compliance Certification | Sub-65 decibel OSHA thresholds unlock California, New York, and Illinois institutional procurement corridors. |
Research Methodology
Cross-validation between primary field interviews and secondary regulatory filings anchors the qualitative findings in this study. Conversations with landscaping fleet managers, municipal procurement officers, dealer service technicians, and lithium cell supply planners informed demand-side dynamics. Secondary sources include EPA small engine emission databases, OSHA noise exposure enforcement records, customs trade data for power equipment imports, and SEC filings from publicly traded outdoor power equipment manufacturers. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Sensitivity analysis around lithium cost curves and municipal mandate adoption rates tests forecast robustness across the projection horizon. Segmentation dimensions modeled include powertrain technology, end-user archetype, motor architecture type, and regional regulatory cluster. CAGRs derive from logistic diffusion curves fitted to battery platform adoption patterns and replacement cycle data. Industry-specific inputs incorporate landscaping contractor fleet expansion rates and snow removal seasonal extension factors.
Forecasts assume regulatory continuity in EPA emission standards and OSHA noise exposure limits; material policy shifts would require re-modeling technology transition timelines. Supply concentration in cobalt and lithium sourcing, brushless motor controller availability, and dealer network retraining completion rates constitute specific revision triggers. Recalibration cycles align with material shifts in municipal procurement rule propagation and battery energy density milestones.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Industrial Cleaning Equipment Market
Tools
Woodworking CNC Tools Market
Tools
Machine Bench Vices Market
Tools
Global Tool Holder Adapters Market
Tools
Gear Honing Machines Market
Tools
Extensometer Market
Tools
Ratchet Wringer Market
Tools
Brushcutter Market
Tools
US Power Tools Market
Tools
Hydraulic Tools and Equipment Market
Tools
Global Cordless Power Tools Market
Tools
MIG Guns Market
Tools
Drain Cleaning Equipment Market
Tools
Metal Cutting Machine Market
Tools
Hand Tools Market
Tools
Gear Hobbing Cutter Market