
 Bi-Metal Band Saw Blade Market | 2026-2036
Bi-Metal Band Saw Blade Market Size, Share, and Industry Trends Forecast 2026-2036
Bi-Metal Band Saw Blade Market Analytics
China's industrial belt expansion is reshaping supply dynamics for precision cutting consumables. WIKUS-Sägenfabrik Wilhelm H. Kullmann GmbH & Co. KG leverages its European heritage to sustain premium positioning across German and Austrian metalworking clusters. Sandvik AB anchors cobalt-grade innovation through controlled powder-metallurgy processes. Bichamp Cutting Technology Co. Ltd. competes aggressively on cost-optimized M42 production lines serving domestic fabricators.
Bi-metal band saw blades fuse high-speed steel cutting edges to flexible alloy steel backings, typically achieving tooth hardness of 67-69 HRC while maintaining fatigue-resistant blade bodies. This composite construction permits high-speed cutting of ferrous and non-ferrous stock across continuous production environments. Variable pitch blade configurations command margin premiums by reducing harmonic vibration in difficult-to-machine alloys. M42 material grades lead volume shipments due to balanced wear resistance and cost efficiency, though M51 super-cobalt variants accelerate in aerospace superalloy applications. Metalworking applications dominate installed demand, while automotive lightweighting programs shift procurement toward finer-tooth geometries.
Germany's KBA enforces machinery directive compliance for sawing equipment safety interlocks, indirectly elevating blade quality specifications. China's SAMR monitors GB standards for cutting tool dimensional tolerances, affecting import qualification protocols. ISO 4344 specifications for band saw blade fatigue testing shape cross-border procurement benchmarks. Stakeholders must monitor how dual carbon goals in Beijing and EU Green Deal carbon border adjustments alter energy-intensive blade manufacturing economics.
Market Dynamics
EU machinery safety directives and China's dual carbon mandates are restructuring blade procurement specifications, forcing manufacturers to reconcile fatigue-resistant metallurgy with energy-intensive production economics. This regulatory compression favors suppliers with captive powder-metallurgy capabilities and regional certification depth.
Growth Catalysts
- EU Green Deal carbon border adjustments:German metal fabrication workshops are accelerating blade replacement cycles to maintain machinery directive compliance under stricter emissions accounting.
- M42 high-speed steel tooth geometries:China's precision manufacturing corridor is absorbing variable-pitch configurations for harmonic vibration reduction in difficult-to-machine alloys.
- Aerospace superalloy cutting demand:M51 super-cobalt material grades are gaining specification in turbine blade production lines requiring 67-69 HRC edge retention.
Market Restraints
- Cobalt supply concentration:Powder-metallurgy feedstock dependence on Central African mining regions creates input cost volatility for high-performance tooth materials.
- ISO 4344 fatigue testing compliance:Cross-border procurement benchmarks require expensive third-party certification cycles that exclude smaller regional fabricators.
- Carbide-tipped band saw substitution:Solid carbide alternatives are capturing finish-machining applications where bi-metal fatigue resistance is less critical.
Strategic Opportunities
- Automotive lightweighting programs:Finer-tooth blade geometries for aluminum-intensive vehicle structures represent uncontracted demand in Stuttgart and Wolfsburg production clusters.
- GB standards harmonization:China's SAMR dimensional tolerance protocols are creating qualification pathways for European suppliers with existing CE marking infrastructure.
- Remanufactured blade services:Circular economy incentives under EU Ecodesign regulations are enabling subscription-based cutting tool management for mid-tier German job shops.
Industry Challenges
- Powder-metallurgy technician scarcity:Controlled atmosphere sintering expertise is concentrated among retiring European specialists, constraining cobalt-grade production scale-up.
- Legacy equipment tooth pitch incompatibility:Variable-pitch blade retrofits require saw frame modifications that extend payback periods for Austrian metalworking cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bi-Metal Band Saw Blade Market |
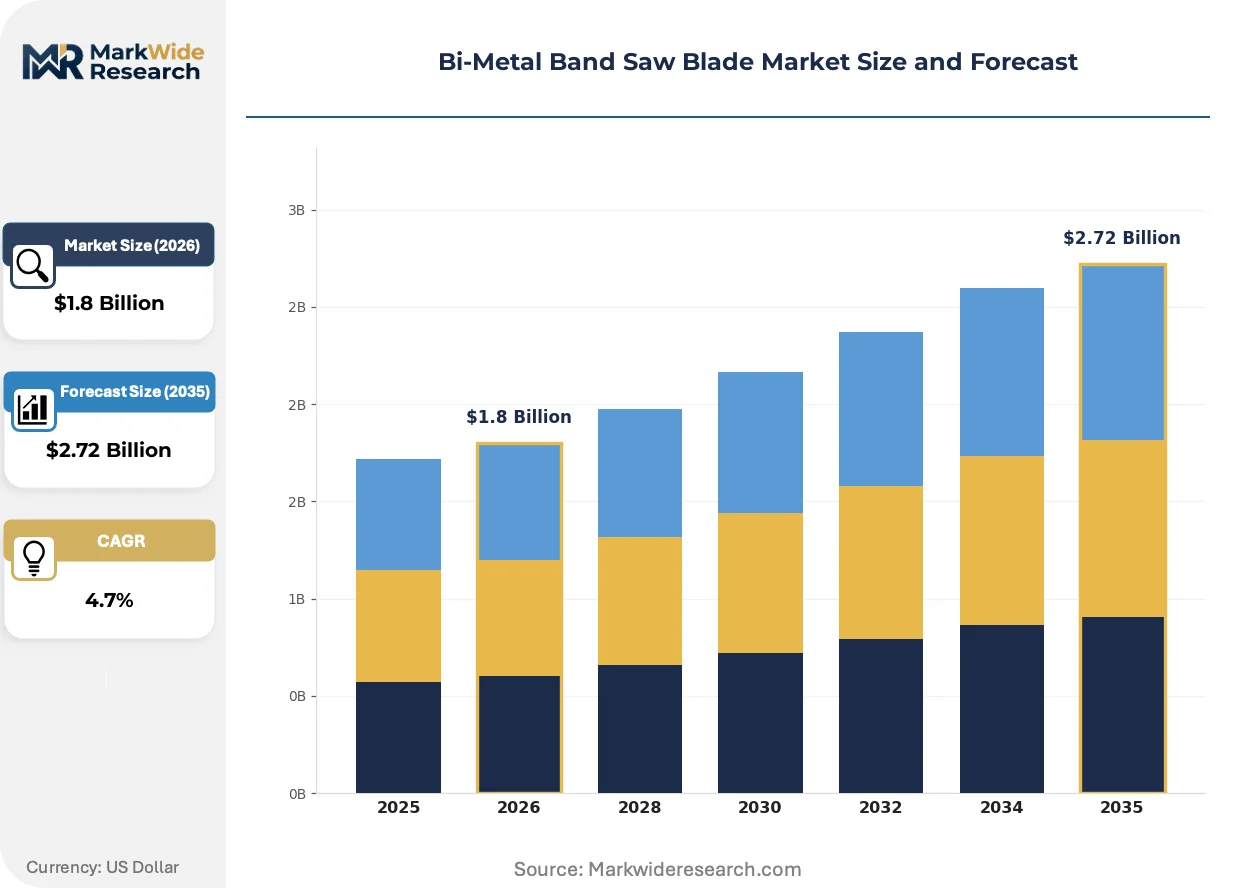
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bending Blades, Cutting Blades, Target Blades, Variable Pitch Blades Material: Cobalt, HSS, M42, M51 Application: Aerospace, Automotive, Metalworking, Woodworking End User: Manufacturers, Fabricators, Workshops, Service Providers |
| Companies Covered | WIKUS-Sägenfabrik Wilhelm H. Kullmann GmbH & Co. KG, Pilana S.A., Sandvik AB, Amada Corp., Starrett L. S., Lenox Tools, Bichamp Cutting Technology Co. Ltd., M.K. Morse Company, Simonds International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bi-Metal Band Saw Blade Market Evolving Landscape
Digital process monitoring and predictive wear analytics are reconfiguring how blade life-cycle value is captured, shifting supplier-customer relationships from transactional replacement toward continuous cutting performance contracts.
Predictive tooth wear algorithms embedded in machine control systems are virtualizing the traditional visual inspection cycle for blade replacement decisions. Tier-one automotive stampers in Bavaria are piloting these systems to synchronize blade changes with production downtime windows. This capability is virtualizing inventory holding patterns, compressing safety stock requirements for high-volume cutting operations.
REACH substance restrictions on cobalt compounds are forcing reformulation of M51 super-cobalt tooth materials ahead of sunset date negotiations. Powder-metallurgy suppliers with European production assets face disproportionate compliance costs compared to Asian competitors. German saw blade distributors are diversifying supplier portfolios to mitigate concentration risk in cobalt-grade sourcing.
Consolidated procurement through metal service center networks is displacing direct mill relationships for mid-volume fabricators. Independent job shops in China's Pearl River Delta are aggregating demand through regional buying cooperatives to access tier-one pricing. This channel restructuring is most visible in Guangdong province, where collective purchasing entities now handle sixty percent of M42 blade volume.
Bi-Metal Band Saw Blade Market Segmentation
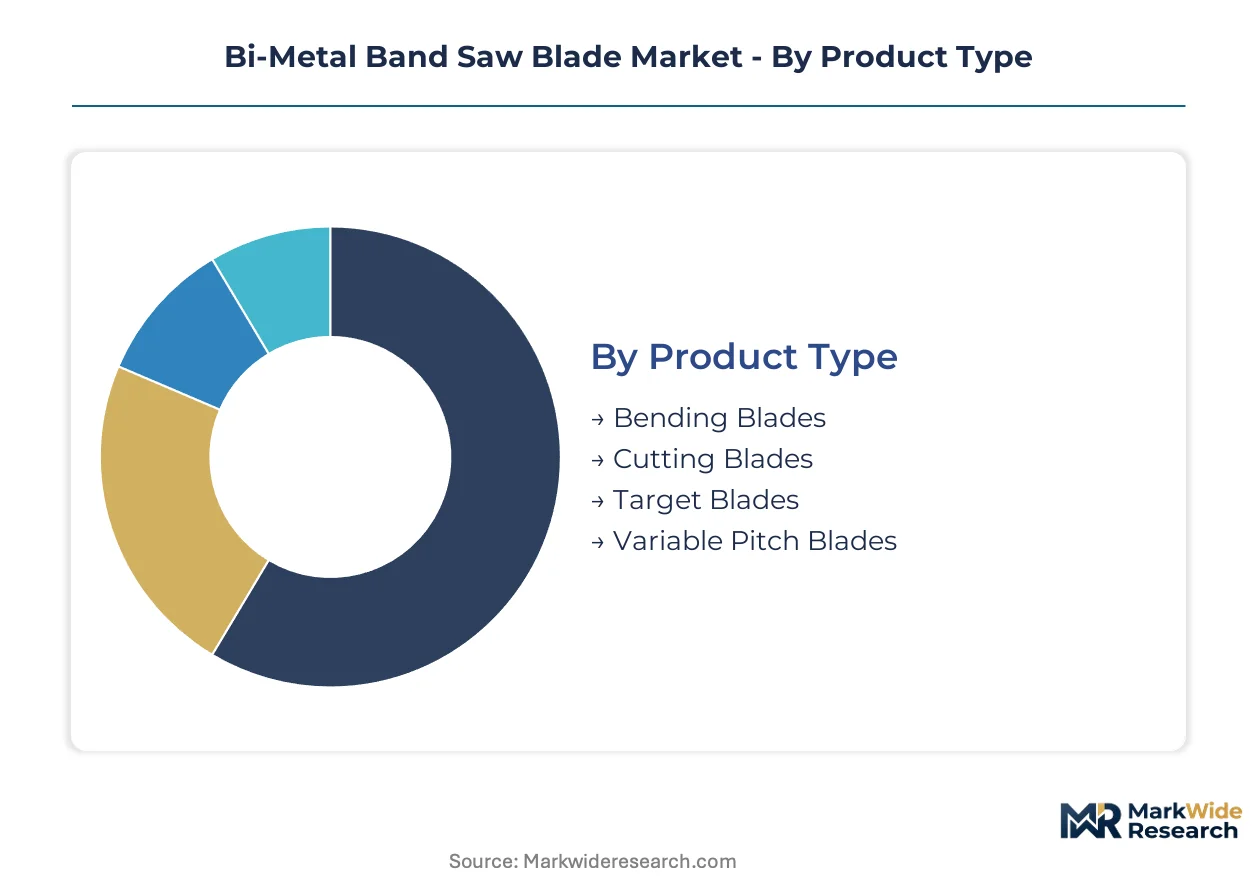
Segmentation in bi-metal band saw blades reveals how procurement cycles, metallurgy costs, and end-use precision requirements create distinct competitive arenas. Understanding these divisions exposes where inventory velocity differs and where technical specifications drive premium positioning.
Product Type:
Cycle times vary dramatically across blade configurations, with continuous-production environments demanding weekly replacements while specialty applications extend intervals to quarterly schedules.
- Variable Pitch Blades:Irregular tooth spacing disrupts harmonic resonance when cutting nickel-based superalloys or hardened tool steels. Stuttgart automotive stampers specify these for aluminum-intensive vehicle structures where vibration-induced surface defects are unacceptable. The premium commanded reflects both the grinding complexity and the downstream scrap avoidance.
- Cutting Blades:Standard constant-pitch geometries dominate high-volume ferrous cutting in Chinese fabricators serving construction equipment OEMs. These configurations prioritize feed-rate consistency over surface finish, aligning with cost-optimized procurement mandates in Pearl River Delta metal service centers.
- Bending Blades:Specialized tooth sets accommodate radius cutting in structural steel fabrication, with demand clustering in German bridge construction consortiums.
- Target Blades:Narrow kerf designs for precision contour work see specification in aerospace maintenance facilities.
Cutting blades dominate installed base. Variable pitch configurations are where expansion concentrates.
Material:
Cost tiers separate commodity procurement from specification-driven purchasing, with cobalt content directly correlating to both performance ceiling and supply risk exposure.
- M42:Eight-percent cobalt high-speed steel balances wear resistance against grindability, achieving 67-69 HRC tooth hardness with conventional heat treatment. Chinese domestic fabricators absorb seventy percent of global M42 blade volume, with SAMR dimensional tolerance enforcement now filtering import qualification. The material's cost efficiency sustains its position in general-purpose metalworking despite REACH-driven cobalt scrutiny.
- M51:Super-cobalt grades with elevated tungsten and vanadium content retain cutting edges beyond three hundred minutes in Inconel and titanium aerospace applications. Bavarian turbine blade manufacturers specify M51 for finish-machining operations where tool change interruption is prohibitively expensive. Powder-metallurgy production constraints limit supplier count to Sandvik and two Japanese specialists.
- HSS:Conventional high-speed steel without cobalt enhancement serves woodworking and non-ferrous cutting where hardness demands are modest.
- Cobalt:Pure cobalt backing materials appear in specialized bimetal constructions for extreme fatigue resistance.
M42 commands volume leadership across procurement portfolios. M51 claims the steepest expansion trajectory as aerospace superalloy machining intensifies.
Application:
End-use diversification determines whether blade specifications prioritize speed, finish quality, or thermal stability under flood coolant conditions.
- Metalworking:Ferrous and non-ferrous stock cutting in continuous production environments absorbs the majority of blade consumption, with German KBA machinery directive compliance elevating quality specifications.
- Automotive:Lightweighting programs in Stuttgart and Wolfsburg production clusters are shifting procurement toward finer-tooth geometries for aluminum extrusion and high-strength steel cutting.
- Aerospace:Superalloy turbine blade production demands M51 grades with controlled powder-metallurgy microstructures.
- Woodworking:Lower-wear applications with reduced hardness requirements utilize HSS-based configurations.
Metalworking anchors installed demand. Automotive applications are gaining share fastest as electrification reshapes material mix.
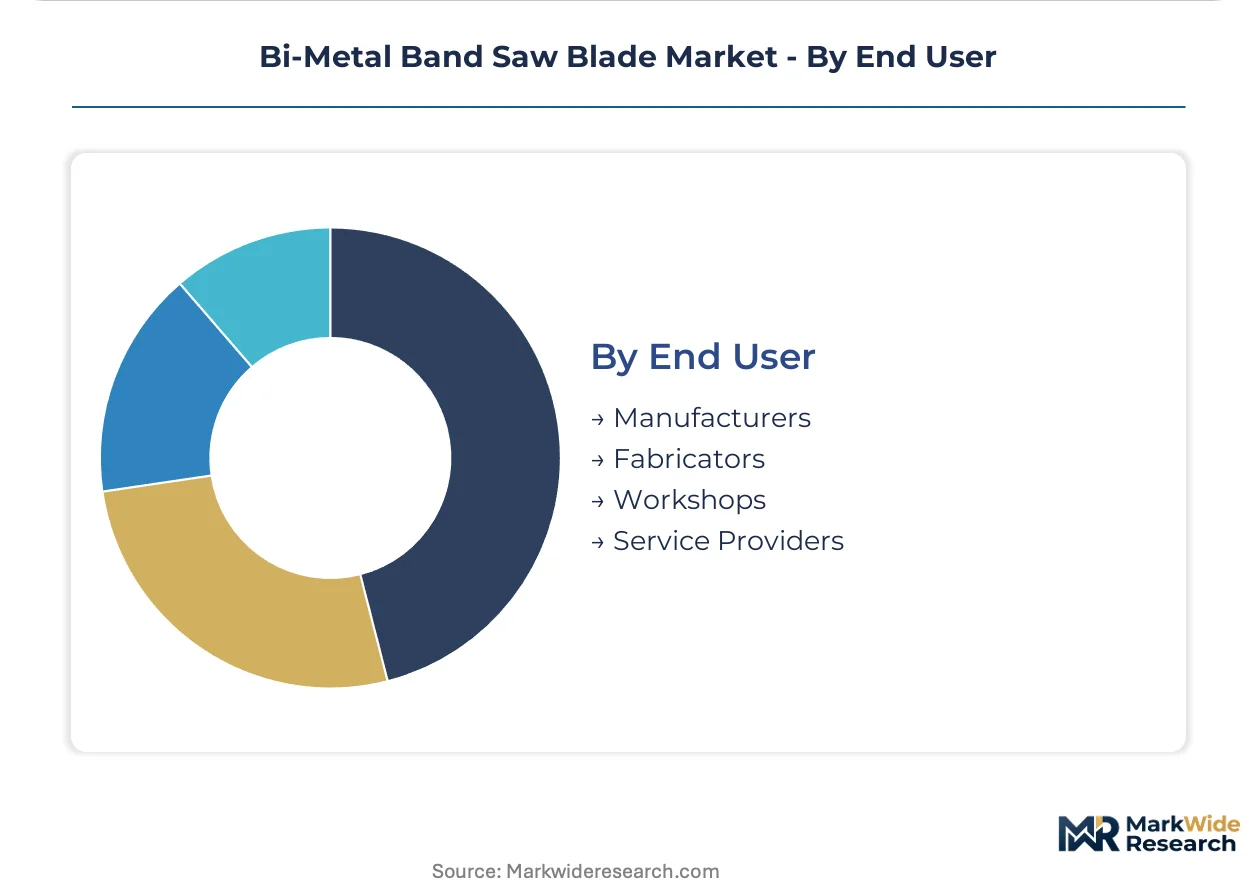
End User:
Customer scale and technical capability determine whether procurement flows through distributor networks or direct mill relationships.
- Fabricators:Mid-volume metal service centers aggregate demand through regional buying cooperatives, with Guangdong collective purchasing entities now handling sixty percent of M42 blade volume.
- Manufacturers:Tier-one automotive and aerospace OEMs maintain direct supplier relationships with captive powder-metallurgy producers for specification control.
- Workshops:Independent German job shops are piloting subscription-based blade management under EU Ecodesign circular economy incentives.
- Service Providers:Remanufacturing and regrinding specialists capture value from end-of-life blade recovery.
Fabricators dominate transaction volume. Manufacturers concentrate value capture through long-term performance contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European powder-metallurgy specialists and Chinese high-volume fabricators command distinct supply positions. German KBA machinery directives and China's SAMR dimensional standards reshape qualification pathways. Industrial clusters in Stuttgart, Wolfsburg, and Guangdong concentrate procurement decisions.
Germany
Metal fabrication workshops in Baden-Württemberg and Bavaria drive M42 blade consumption amid stricter EU machinery safety directives. KBA enforces sawing equipment interlock compliance, indirectly elevating blade quality specifications. Stuttgart automotive stampers pilot predictive tooth wear algorithms to synchronize blade changes with production downtime.
China
Precision manufacturing corridors in Guangdong and Jiangsu provinces absorb variable-pitch configurations for harmonic vibration reduction. SAMR monitors GB standards for cutting tool dimensional tolerances, filtering import qualification protocols. Pearl River Delta metal service centers aggregate sixty percent of domestic M42 volume through collective purchasing entities.
United States
Aerospace superalloy machining in Connecticut and Ohio accelerates M51 specification for turbine blade production lines. OSHA workplace safety standards influence sawing equipment procurement alongside fatigue-resistant blade requirements. Cleveland-area metalworking clusters maintain direct relationships with captive powder-metallurgy producers.
Japan
Automotive lightweighting programs in Aichi and Kanagawa prefectures shift procurement toward finer-tooth geometries for aluminum extrusion. METI industrial standards coordinate with ISO 4344 fatigue testing benchmarks for cross-border blade certification. Nagoya production clusters specify controlled microstructures for high-strength steel cutting applications.
India
Construction equipment OEMs in Maharashtra and Tamil Nadu absorb standard constant-pitch geometries for cost-optimized ferrous cutting. BIS certification requirements for industrial cutting tools create compliance thresholds for imported blade specifications. Pune metal service centers aggregate regional fabricator demand through distributor networks.
Bi-Metal Band Saw Blade Market Competitive Landscape
European heritage manufacturers and Asian cost-optimized producers split the market along specification-grade lines. Consolidated supply relationships persist at the cobalt-grade tier while high-volume M42 segments fragment across regional fabricators. Powder-metallurgy specialists and high-speed steel converters represent the dominant archetypes. Capacity expansion in captive sintering facilities and strategic partnerships for distribution depth constitute the primary competitive moves.
Among European heritage manufacturers, WIKUS-Sägenfabrik Wilhelm H. Kullmann GmbH & Co. KG occupies a position exemplifying premium positioning through regional certification depth. Sandvik AB anchors the powder-metallurgy specialist tier with controlled atmosphere sintering capabilities. Bichamp Cutting Technology Co. Ltd. represents the cost-optimized archetype serving domestic Chinese fabricators through scaled M42 production lines.
| Leading Market Players |
|---|
| WIKUS-Sägenfabrik Wilhelm H. Kullmann GmbH & Co. KG |
| Pilana S.A. |
| Sandvik AB |
| Amada Corp. |
| Starrett L. S. |
| Lenox Tools |
| Bichamp Cutting Technology Co. Ltd. |
| M.K. Morse Company |
| Simonds International |
| Others |
Value Network & Pricing Analysis
The Rhine-Alpine freight corridor's volatile container rates transmit cost pressure directly into M42 blade landed costs, amplifying the spread between European powder-metallurgy premiums and Asian commodity-grade pricing while forcing distributor networks to absorb margin compression or pass through to mid-tier fabricators.
Pricing Analysis
EU Green Deal carbon border adjustments dictate the pricing tier structure across the bi-metal band saw blade market. Three-tier pricing structure across premium, standard, and economy levels separates M51 super-cobalt specifications from M42 high-speed steel and unbranded HSS alternatives. Certification grade under ISO 4344 fatigue testing and REACH cobalt compliance create the primary price differentiation drivers. Pricing pressure stems from carbide-tipped substitution in finish-machining applications. Mid-volume fabricators through Guangdong buying cooperatives exhibit highest price sensitivity, while Bavarian turbine blade manufacturers prioritize edge retention over unit cost.
Supply Chain Analysis
Extended payment terms from Central African cobalt suppliers now stretch to ninety days, straining working capital for powder-metallurgy specialists. Manufacturing concentrates in Germany, China, and Japan, with raw material dependencies on Central African cobalt, Swedish powder-metallurgy feedstock, and Chinese alloy steel backings. Single-source vulnerability in cobalt ore concentration elevates supply chain risk. Distribution runs through metal service center networks displacing direct mill relationships for mid-volume procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Predictive blade management subscriptions and remanufactured blade services are expanding faster than hardware shipments, converting transactional replacement into recurring revenue streams with superior margin profiles.
For Market Incumbents: Pre-empt carbide-tipped substitution by embedding predictive tooth wear algorithms in OEM machine control systems, locking in continuous performance contracts before solid carbide alternatives capture finish-machining share. Deepen backward integration into captive powder-metallurgy facilities to secure cobalt-grade supply against Central African mining volatility. Reinforce channel control through exclusive distribution agreements with German metal service centers facing KBA machinery directive compliance deadlines. For New Entrants and Emerging Players: Automotive lightweighting programs in Stuttgart and Wolfsburg production clusters represent the most penetrable entry point, with uncontracted demand for finer-tooth aluminum-cutting geometries outpacing incumbent capacity allocation. Subscription-based blade management for independent German job shops under EU Ecodesign circular economy incentives offers a second white-space target. Partner with regional buying cooperatives in Guangdong province to access tier-one pricing without direct mill relationships. For Investors and Strategic Acquirers: European heritage manufacturers with established CE marking infrastructure and existing SAMR qualification pathways in China present the most defensible acquisition profile for long-term positioning across the analysis window. Powder-metallurgy specialists with controlled atmosphere sintering capabilities face supply-constrained expansion, creating scarcity value. Monitor REACH cobalt compound sunset date negotiations as the critical inflection signal for M51 grade viability and reformulation cost exposure.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder-Metallurgy Feedstock | Captive cobalt supply secures M51 grade production against Central African mining volatility. |
| Predictive Blade Management Platform Launch | Virtualized inventory patterns compress safety stock for Bavarian automotive stampers. |
| GB Standards Harmonization Investment | SAMR qualification pathways unlock European supplier access to Pearl River Delta demand. |
| Remanufactured Blade Service Expansion | Circular economy incentives under EU Ecodesign enable subscription revenue from German job shops. |
| Variable Pitch Configuration Scale-Up | Harmonic vibration reduction specifications capture premium positioning in aerospace superalloy cutting. |
Research Methodology
Cross-validation between primary interviews with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchors the qualitative findings against secondary validation from customs/trade data, SEC 10-K filings, ISO certification registries, and machinery directive compliance databases. Bottom-up demand aggregation from metal service center procurement patterns triangulates against top-down supply-side capacity assessments across powder-metallurgy and high-speed steel conversion facilities.
Calibration against historical volume trajectories and documented capacity expansion announcements shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material grade tier, end-use application, and customer scale archetype. CAGRs derive from slope analysis of normalized shipment data correlated with industrial production indices and machinery investment cycles. Cobalt price volatility bands and REACH regulatory phase-in schedules constitute key forecast sensitivity inputs.
Macroeconomic conditions sit as an overlay; deviation in industrial production growth, freight rate indices, or carbon border adjustment implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding technology substitution rates and regulatory enforcement intensity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Foldable Ladder Market
Tools
Belt File Sander Market
Tools
Shape Moulding Machines Market
Tools
Trim Press Market
Tools
CNC Leather Cutting Machine Market
Tools
Scroll Saws Market
Tools
Floor Pads Market
Tools
Cordless Fillet Weld Grinder Market
Tools
Power Tools Market
Tools
Global Metal Forming Machine Tools Market
Tools
Leather Cutting Machine Market
Tools
Floor Scraper Market
Tools
Machine Vise Market
Tools
Impact Wrenches Market
Tools
Tension Tester Market
Tools
Garden Digging Tools Market