
 Laser Engraving Machine Market | 2026-2036
Laser Engraving Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Engraving Machine Market Intelligence
Small-batch custom merchandisers is collapsing as the dominant buyer archetype, while prototyping labs and electronics contract manufacturers gain procurement share. Han's Laser leverages captive diode supply chains to dominate cost-sensitive Asian markets. Trotec Ltd. sustains premium positioning through galvo-scanning precision in European design studios. Trumpf anchors industrial-grade fiber laser demand across German automotive tier-one suppliers.
Laser engraving machines direct amplified coherent light through galvanometer-steered mirrors to ablate, anneal, or foam substrate surfaces with resolutions reaching 0.001 inches, serving permanent identification and decorative personalization across metals, polymers, and ceramics. Fiber laser systems lead in electronics labeling and aerospace component traceability due to superior beam quality on reflective metals, while CO2 platforms retain cost advantages in acrylic and wood personalization for design studios. UV laser adoption accelerates in research facilities handling heat-sensitive semiconductor substrates where cold marking prevents thermal damage.
FDA device-traceability rules and EU MDR instrument-marking mandates tighten compliance requirements for medical and dental tool engravers, expanding demand for high-contrast permanent marking systems. Germany's KBA and France's ANSM enforce divergent serialization standards that fragment equipment specification across European manufacturing plants. Stakeholders must monitor harmonization pressure between ISO 11553 safety standards and emerging CSRD supply-chain disclosure rules that will reshape capital allocation toward traceability-capable platform investments.
Market Dynamics
Jewelry artisans and medical instrument manufacturers are pulling laser engraving demand in divergent directions—precision personalization versus permanent traceability—forcing equipment suppliers to bifurcate their product architectures without fragmenting manufacturing scale.
Growth Catalysts
- FDA device-traceability mandates:Medical and dental tool engravers face expanded compliance requirements for high-contrast permanent marking systems, tightening procurement specifications across US healthcare supply chains.
- Fiber laser beam quality:Superior performance on reflective metals drives adoption in electronics labeling and aerospace component traceability where permanent identification withstands harsh operational environments.
- Stuttgart precision engineering corridor:Germany's concentration of automotive tier-one suppliers anchors industrial-grade fiber laser demand for component serialization and quality authentication.
Market Restraints
- Diode supply concentration:Captive supply chains in Asian manufacturing regions create cost advantages for integrated producers while independent equipment makers face input cost volatility and allocation uncertainty.
- EU regulatory fragmentation:Germany's KBA and France's ANSM enforce divergent serialization standards that force equipment specification changes across European manufacturing plants, raising compliance engineering overhead.
- CO2 wavelength limitations:Inability to mark uncoated metals without preprocessing restricts cost-advantaged CO2 platforms to acrylic and wood applications, capping addressable market expansion.
Strategic Opportunities
- UV laser cold marking:Heat-sensitive semiconductor substrate handling in research facilities creates white space where thermal damage prevention commands premium positioning.
- CSRD supply-chain disclosure alignment:Emerging EU rules will reshape capital allocation toward traceability-capable platform investments, favoring engravers with integrated data-logging architectures.
- Electronics contract manufacturers:Prototyping labs and production-scale PCB houses are gaining procurement share as small-batch custom merchandisers collapse, opening volume contract pathways.
Industry Challenges
- Galvo-scanning calibration expertise:Precision engineering talent capable of maintaining sub-thousandth-inch resolution across reflective and absorptive materials remains scarce in regional manufacturing hubs.
- ISO 11553 safety integration:Harmonization pressure between established laser safety standards and emerging disclosure frameworks forces engineering teams to redesign enclosure and interlock systems mid-product-cycle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Engraving Machine Market |
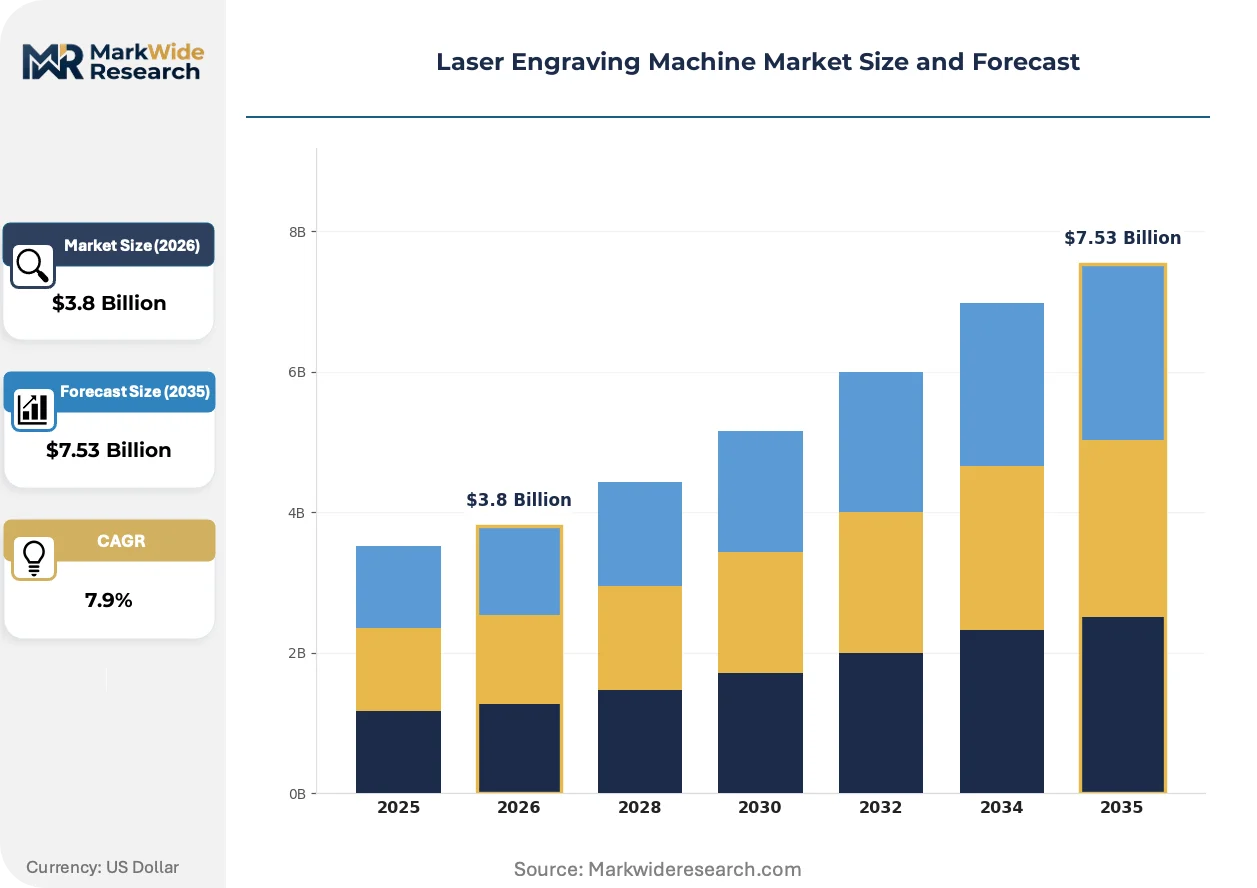
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.53 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CO2 Laser, Fiber Laser, Diode Laser, YAG Laser, UV Laser Technology: Galvo Scanning, Laser Marking, Laser Cutting, Laser Welding, Laser Micromachining Application: Personalization, Jewelry Marking, Electronics Labeling, Automotive Parts, Aerospace Components End User Industry: Manufacturing Plants, Design Studios, Research Facilities, Custom Merchandisers, Prototyping Labs |
| Companies Covered | Gravotech, Universal Laser Systems, Han's Laser, HeatSign, TYKMA Electrox, Trumpf, Trotec Ltd., Mecco, Videojet Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Engraving Machine Market Strategic Shifts & Innovations
Permanent identification requirements are hardening across regulated industries while personalization demand fragments into shorter production runs, compressing equipment design cycles toward modular architectures.
UV laser systems is supplanting infrared alternatives in semiconductor and polymer marking applications where thermal damage compromises substrate integrity. Research facilities handling gallium arsenide wafers and medical-grade polymers are adopting these platforms fastest. The shift is supplanting legacy CO2 and fiber installations in cleanroom environments, compressing the addressable market for heat-generating alternatives.
EU MDR instrument-marking mandates are tightening compliance requirements for medical device traceability across European manufacturing plants. The regulation forces permanent, high-contrast identifiers on surgical and dental instruments entering EU circulation. German and French medical tool producers are retrofitting production lines fastest, driving demand for fiber laser systems with integrated vision verification.
Independent artisans are collapsing the traditional distributor channel for jewelry marking equipment, purchasing directly from manufacturers through digital configuration platforms. Stuttgart-area design studios and Milan jewelry clusters demonstrate this pattern most visibly, where batch-size-one production runs favor equipment with cloud-based job programming over field-service-dependent installations.
Laser Engraving Machine Market Segmentation
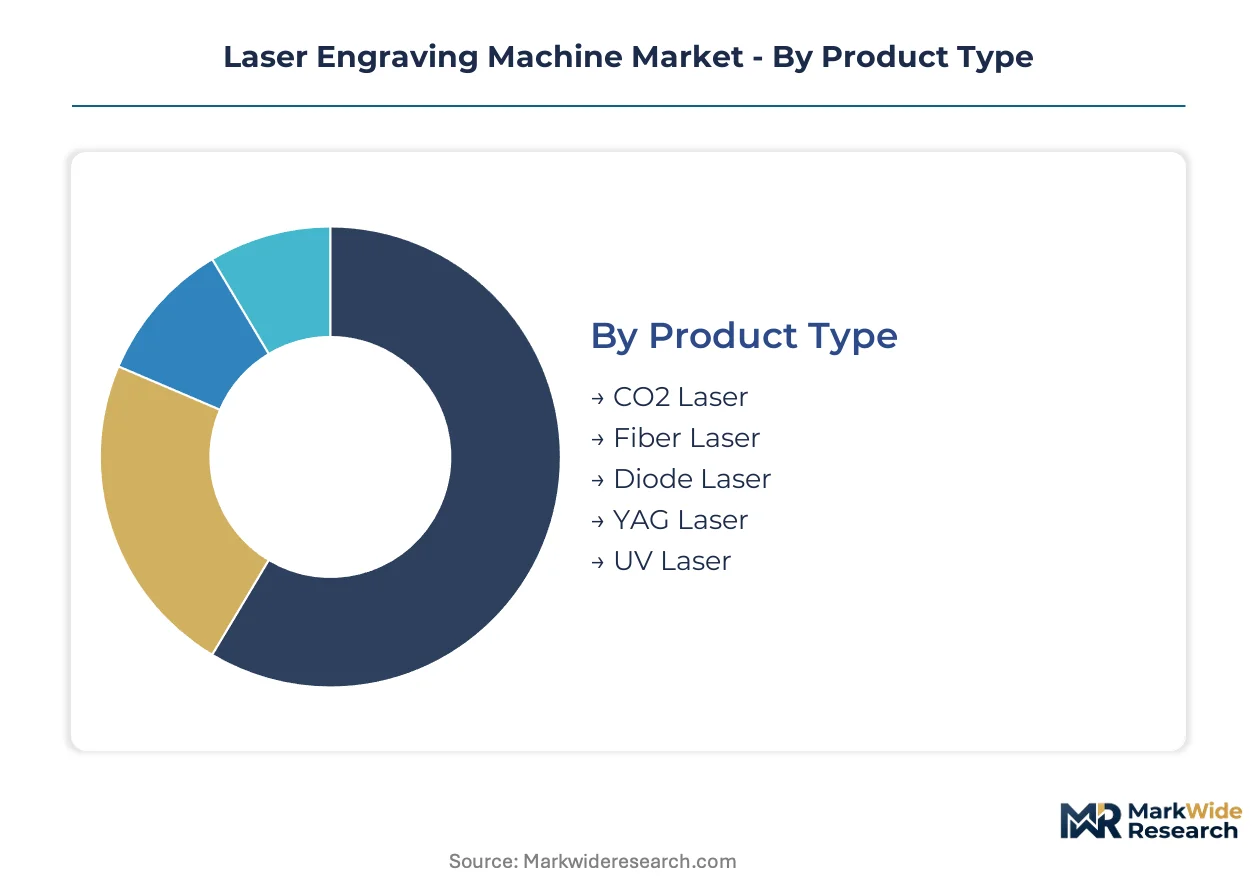
Laser engraving equipment procurement splits across five distinct dimensions, each reflecting divergent technical requirements and buyer economics. Understanding these fault lines clarifies where substitute technologies threaten incumbent platforms and where pricing power concentrates.
Product Type:
Substitution pressure runs hottest against thermal-damage-prone platforms as cold-marking alternatives capture semiconductor and medical-grade applications.
- Fiber Laser:Generates amplified coherent light at 1064nm wavelength with superior beam quality on reflective metals. Stuttgart-area automotive tier-one suppliers anchor industrial demand for component serialization and quality authentication.
- UV Laser:Produces 355nm cold marking through non-thermal ablation, preventing substrate damage on heat-sensitive materials. Research facilities handling gallium arsenide wafers and medical-grade polymers are adopting these platforms fastest.
- CO2 Laser:Cost-advantaged 10600nm systems dominate acrylic and wood personalization in design studios, though metal-marking limitations cap expansion.
- Diode Laser:Compact solid-state sources enable portable engraving units for field-service applications and on-site jewelry marking.
- YAG Laser:Legacy lamp-pumped systems retain installed-base presence in heavy industrial marking, though fiber platforms displace new purchases.
Fiber laser systems anchor the volume base while UV laser platforms gain share at the steepest rate.
Technology:
Cost tier stratification separates precision-engineered galvo systems from commodity flatbed configurations, with welding and micromachining commanding premium positioning.
- Galvo Scanning:High-speed mirror-steered beam delivery achieves 0.001-inch resolution through closed-loop servo control. European design studios and Milan jewelry clusters demand these systems for batch-size-one production runs.
- Laser Marking:Surface-level identification systems serve permanent traceability requirements under FDA device-traceability rules and EU MDR instrument-marking mandates.
- Laser Cutting:Through-material beam penetration systems address acrylic and thin-metal fabrication in prototyping labs.
- Laser Welding:Deep-penetration joining technology serves automotive battery pack assembly and medical instrument manufacturing.
- Laser Micromachining:Sub-thousandth-inch material removal enables PCB via drilling and semiconductor substrate patterning.
Laser marking technology anchors the volume base while galvo scanning gains share at the steepest rate.
Application:
Customer type fragmentation splits demand between regulated traceability mandates and discretionary personalization spending, with divergent procurement cycles and specification rigor.
- Electronics Labeling:Permanent identification on PCBs and components withstands harsh operational environments. Electronics contract manufacturers are gaining procurement share as small-batch custom merchandisers collapse.
- Aerospace Components:High-contrast marking on titanium and aluminum alloys satisfies FAA traceability requirements for flight-critical parts.
- Personalization:Decorative surface modification serves consumer goods and promotional merchandise, though this segment faces demand erosion.
- Jewelry Marking:Precision engraving on precious metals supports independent artisan adoption through direct manufacturer purchasing.
- Automotive Parts:Component serialization enables quality authentication across German automotive supply chains.
Electronics labeling anchors the volume base while aerospace components gain share at the steepest rate.
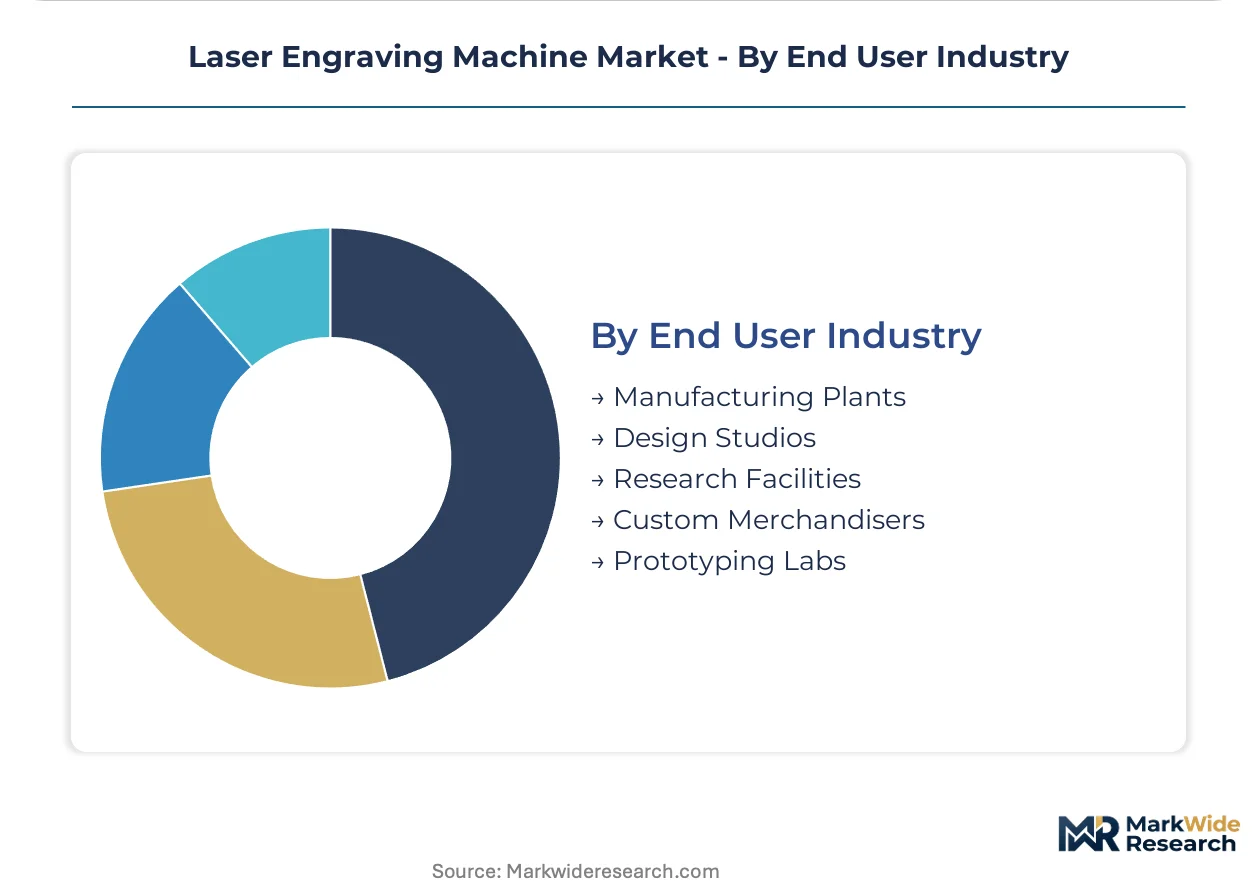
End User Industry:
Supply concentration in manufacturing plants contrasts with geographic dispersion among design studios, shaping divergent distribution and service models.
- Manufacturing Plants:High-volume production environments demand integrated vision verification and automated part handling. German and French medical tool producers are retrofitting production lines fastest under EU MDR mandates.
- Prototyping Labs:Rapid iteration facilities require modular architectures with cloud-based job programming over field-service-dependent installations.
- Design Studios:Stuttgart-area and Milan clusters demonstrate direct manufacturer purchasing patterns, collapsing traditional distributor channels.
- Research Facilities:Cleanroom-compatible cold-marking platforms serve semiconductor and polymer substrate handling.
- Custom Merchandisers:Small-batch consumer personalization providers face demand collapse as procurement concentrates in larger-scale users.
Manufacturing plants anchor the volume base while prototyping labs gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway corridor anchors European distribution for precision engraving equipment, connecting Stuttgart's engineering belt to Black Sea manufacturing outposts. This infrastructure underwrites Germany's role as the continent's equipment specification setter.
Germany
Automotive tier-one suppliers in Stuttgart's precision engineering corridor drive fiber laser demand for component serialization. KBA enforces divergent vehicle-part marking standards that force equipment specification changes across manufacturing plants. Munich-area medical tool producers retrofit production lines fastest under EU MDR instrument-marking mandates.
United States
FDA device-traceability rules tighten compliance requirements for medical and dental tool engravers across healthcare supply chains. FAA traceability requirements for flight-critical aerospace parts sustain demand for high-contrast marking on titanium alloys. Greater Boston's medical device cluster anchors East Coast procurement for permanent identification systems.
China
Electronics contract manufacturers in the Pearl River Delta gain procurement share as small-batch custom merchandisers collapse. MIIT standards for industrial laser safety reshape equipment enclosure specifications. Shenzhen prototyping labs favor modular architectures with cloud-based job programming over field-service-dependent installations.
Japan
Research facilities in the Kanto region adopt UV laser platforms fastest for gallium arsenide wafer handling. METI guidelines on semiconductor manufacturing equipment influence cleanroom-compatible system designs. Nagoya-area automotive suppliers integrate vision verification for quality authentication protocols.
France
ANSM enforces medical device serialization standards that fragment equipment specifications across European plants. Paris-area design studios demonstrate direct manufacturer purchasing patterns for jewelry marking equipment. Île-de-France prototyping labs collapse traditional distributor channels through digital configuration platforms.
Laser Engraving Machine Market Key Industry Players
Listed leaders compete with private specialists across technology tier and geographic reach, producing a bifurcated structure where scale-driven fiber laser producers face precision-focused galvo-scanning boutiques. The vendor base stratifies into three tiers: integrated diode manufacturers with captive supply chains, European precision-engineering houses, and Asian contract equipment fabricators. Dominant competitive moves include backward integration into laser source production and geographic expansion through digital direct-sales platforms.
Within the precision-engineering tier, Trotec Ltd. and Trumpf exemplify European galvo-scanning and industrial fiber laser archetypes respectively. Han's Laser occupies a position among Asian-scale producers with integrated supply chain control. Gravotech anchors the marking-system specialist segment with broad application coverage across metals and polymers.
| Leading Market Players |
|---|
| Gravotech |
| Universal Laser Systems |
| Han's Laser |
| HeatSign |
| TYKMA Electrox |
| Trumpf |
| Trotec Ltd. |
| Mecco |
| Videojet Technologies Inc. |
| Others |
Cost & Logistics Intelligence
UV laser diode substitution for infrared fiber sources is redrawing procurement geography toward Asian captive suppliers while compressing price premiums previously commanded by European precision-engineering houses.
Pricing Analysis
Volume-discount tiering structures separate prototyping labs purchasing single units from electronics contract manufacturers negotiating fleet-scale deployments. Premium positioning rests on ISO 11553 safety certification and galvo-scanning precision, while economy tiers compete on diode cost and assembly labor. Price erosion runs through CO2 platform segments as fiber systems displace metal-marking applications. Small-batch custom merchandisers exhibit acute price sensitivity, whereas medical instrument manufacturers prioritize compliance-grade systems regardless of premium.
Supply Chain Analysis
Strategic stockpile preferences dominate among German automotive tier-one suppliers buffering against diode allocation uncertainty, while just-in-time inventory governs Shenzhen prototyping labs sourcing modular galvo assemblies. Laser diode production concentrates in China, Japan, and Germany. Rare-earth dopants for fiber gain media and precision-machined galvo mirrors constitute critical input dependencies. Single-source vulnerability in high-power diode chips threatens equipment delivery schedules. Distribution runs through manufacturer-direct digital platforms for design studios and field-service-dependent dealer networks for manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Substitution defense against mechanical engraving and inkjet marking systems demands that incumbents harden permanent-traceability value propositions before regulatory mandates commoditize baseline compliance features.
For Market Incumbents: Compound galvo-scanning calibration expertise into captive training academies to lock in precision-engineering talent scarcity. Accelerate backward integration into UV diode production to neutralize Asian cost advantages. Secure KBA and ANSM pre-certification pathways before EU regulatory harmonization closes specification windows.
For New Entrants and Emerging Players: FDA 21 CFR Part 820 quality system certification fast-tracks entry into medical device traceability procurement cycles. White space concentrates in semiconductor research facilities adopting cold-marking platforms. Digital direct-sales platforms collapse distributor margins and enable batch-size-one configuration capture.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed marking-system specialists holding installed-base service contracts. Long-term viability hinges on traceability-mandate durability across medical and aerospace verticals. Acquisition targets should demonstrate CSRD-aligned data-logging architectures. Watch for MIIT enforcement tightening as the signal that Chinese domestic consolidation will accelerate.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Diode Production | Captive UV source supply neutralizes Asian cost advantages for European precision houses. |
| Cloud-Based Job Programming Platform | Stuttgart design studios and Milan jewelry clusters demand manufacturer-direct digital configuration. |
| ISO 11553 Safety Certification Pre-Investment | Anticipatory compliance engineering reduces mid-cycle redesign costs under harmonization pressure. |
| Vision Verification System Integration | German medical tool producers retrofit fastest under EU MDR instrument-marking mandates. |
| Research Facility Cold-Marking Partnership | Gallium arsenide wafer handling in Kanto-region cleanrooms commands premium UV platform positioning. |
Research Approach
Operator-level perspectives from plant engineers, aftermarket service heads, OEM procurement teams, and biomedical equipment managers anchored the qualitative base. Primary fieldwork combined with secondary validation across SEC filings, customs trade records, FDA 510(k) device listings, and EU MDR technical documentation. Bottom-up equipment shipment tracking and top-down industrial laser market sizing were triangulated to constrain variance.
Sensitivity analysis tested forecast robustness across diode price volatility scenarios and regulatory implementation delays. The analytical framework modeled laser type, technology tier, end-use industry, and geographic production cluster across the projection horizon. CAGRs derived from fitted growth curves incorporating electronics contract manufacturer procurement share shifts and medical device traceability mandate compliance timelines.
Decision-makers should treat outputs as directional under sustained REACH compliance tightening and FDA device-traceability enforcement; material deviation would warrant model refresh. Specific risk factors include EU regulatory fragmentation persistence and semiconductor capital expenditure cyclicality. Revision becomes warranted when UV laser adoption rates in research facilities cross threshold inflection points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Fixed Cutter Bits Market
Tools
Europe Power Tools Market
Tools
Handheld Engraving Machine Market
Tools
Construction Nails Market
Tools
Automatic Heat Press Machines Market
Tools
Striking Tools Market
Tools
Adjustable Gripping Hand Tools Market
Tools
Orbital Sanders Market
Tools
Drain Cleaning Equipment Market
Tools
Machine Tools Market
Tools
Gas Cutting Machine Market
Tools
Hydraulic Torque Wrench Market
Tools
Hand Tools Market
Tools
Mechanical Hand Tools Market
Tools
Woodworking CNC Tools Market
Tools
Press Machine Market