
 Press Machine Market | 2026-2036
Press Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Press Machine Market Outlook
German press engineering capacity is rebalancing toward electromechanical and servo systems as automotive OEMs demand tighter stroke control. Schuler leverages its heritage in large-scale mechanical presses to anchor high-volume automotive stamping lines across European plants. AIDA Engineering competes in Asia-Pacific markets with precision servo technology for electric motor lamination. Komatsu sustains dominance in heavy-tonnage forging applications through integrated hydraulic control systems.
A press machine applies controlled force through mechanical, hydraulic, pneumatic, or servo-electric actuation to deform, cut, or join sheet metal and composite materials, typically operating at forces from 20 to 50,000 tons with ram speeds adjustable to 1,000 strokes per minute for progressive die operations. Servo presses capture expanding margin pools as manufacturers replace flywheel-driven mechanical units to achieve programmable slide motion and reduced energy consumption. Hydraulic presses retain structural importance in deep-drawing and forging where sustained force throughout the stroke matters more than speed. Smart technology integration through IoT-enabled condition monitoring is emerging fastest among tier-1 suppliers managing distributed stamping operations.
OSHA machine guarding standards and EU Machinery Directive 2006/42/EC compliance requirements shape product design and retrofit demand across North American and European installed bases. China's GB standards for mechanical safety and the EU F-Gas Regulation on hydraulic fluid emissions create divergent certification burdens for multinational suppliers. Stakeholders must monitor how servo-electric architectures alter aftermarket service models and spare part revenue streams as predictive maintenance replaces scheduled rebuild cycles.
Market Dynamics
Servo-electric actuation is compressing the installed base of flywheel-driven mechanical presses as automotive OEMs retool stamping lines for electric vehicle platforms requiring programmable slide motion and tighter stroke control.
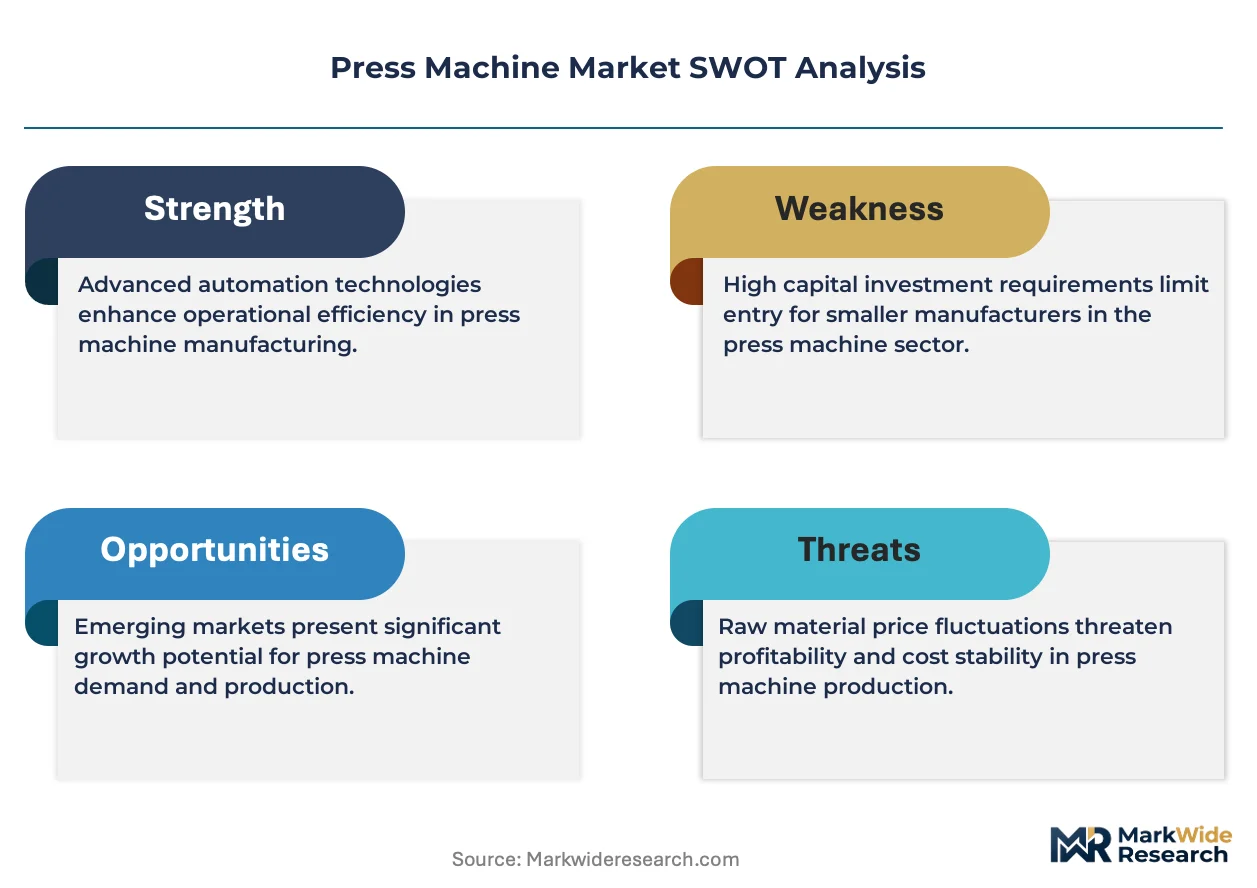
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Tighter safety mandates for electromechanical systems accelerate replacement cycles across European automotive stamping operations.
- Electric vehicle platform retooling:OEMs in Germany, China, and the United States invest in new press capacity for aluminum-intensive body-in-white architectures.
- Servo press technology:Programmable ram motion reduces energy consumption and die wear compared to legacy mechanical systems.
Market Restraints
- Copper and rare-earth magnet costs:Servo motor supply chains face input volatility from concentrated mining operations in Chile and the Democratic Republic of Congo.
- Technical limitation in heavy forging:Hydraulic systems retain structural advantage above 5,000 tons where sustained force throughout the stroke outweighs speed requirements.
- EU F-Gas Regulation:Hydraulic fluid emission standards create certification friction for multinational suppliers serving European forging applications.
Strategic Opportunities
- India metal fabrication:Domestic equipment builders expand capacity under PLI scheme incentives for capital goods manufacturing.
- Battery cell housing stamping:Emerging demand for precision-formed aluminum enclosures in electric vehicle battery pack assembly.
- IoT-enabled condition monitoring:Convergence of sensor hardware and cloud analytics creates aftermarket service revenue streams beyond traditional spare part sales.
Industry Challenges
- Servo drive commissioning expertise:Shortage of technicians trained in electromechanical system integration delays project timelines for tier-2 automotive suppliers.
- Legacy hydraulic infrastructure:Retrofit complexity with existing plant layouts and foundation requirements extends payback periods for brownfield installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Press Machine Market |
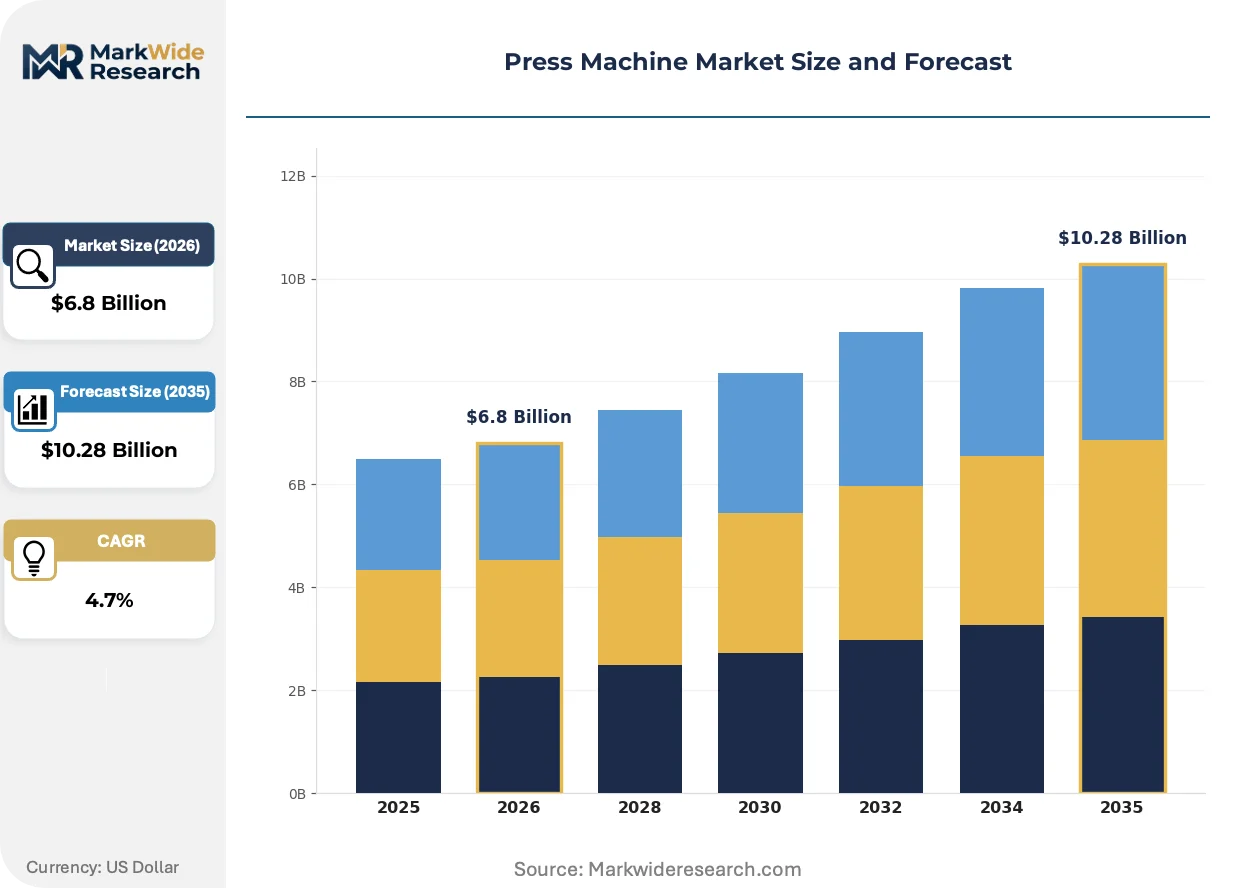
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Presses, Mechanical Presses, Pneumatic Presses, Servo Presses Application: Automotive Manufacturing, Aerospace Components, Metal Fabrication, Plastic Molding End User: Manufacturers, OEMs, Tier-1 Suppliers, Aftermarket Providers Technology: Electromechanical, Hydraulic Control, Automation, Smart Technology |
| Companies Covered | Schuler, Amada, AIDA Engineering, JDM Jingda Machine, LVD, Komatsu, SMS Group, Goodsjack, Tianduan Press, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Press Machine Market Strategic Shifts
Press architecture is fragmenting into configurable subsystems as manufacturers seek production flexibility without full line replacement. Three developments are compressing traditional equipment procurement cycles.
Servo press control systems is modularizing around standardized drive packages and open-architecture software interfaces. Tier-1 automotive stampers in Germany and Japan adopt these platforms to reconfigure stroke profiles without hardware swaps. The approach is compressing capital deployment timelines from 18-month greenfield installations to 6-month line extensions.
REACH substance restrictions and the EU F-Gas Regulation are forcing hydraulic fluid reformulation across European forging operations. Bio-based alternatives face performance validation gaps in high-temperature deep-drawing applications. German press operators are responding with sealed-system designs and accelerated preventive maintenance intervals to minimize emission exposure.
Stamping procurement is consolidating through fleet-management contracts that bundle equipment, maintenance, and consumables under single-vendor agreements. Tier-2 automotive suppliers in China's Yangtze River Delta are shifting from spot purchases to multi-year service partnerships. The model transfers operational risk to OEMs while locking in aftermarket revenue for equipment builders.
Press Machine Market Segmentation
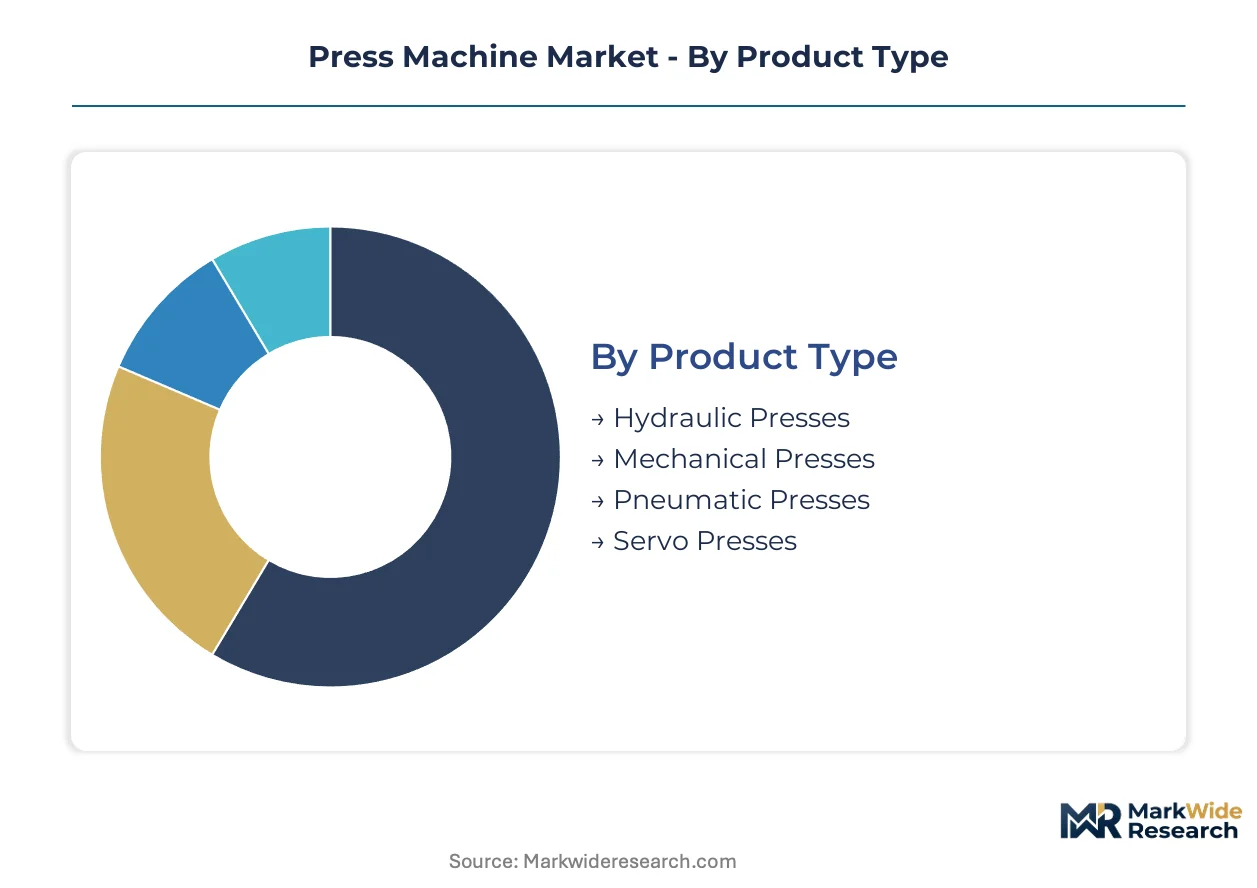
Press machine procurement patterns diverge sharply across buyer types, with automotive OEMs prioritizing programmable motion control while metal fabricators emphasize capital efficiency. Segmentation reveals how technology choice cascades through specification requirements, maintenance models, and supplier relationships.
Product Type:
Buyers in this category separate by force requirements and energy sensitivity, with high-volume stampers favoring precision control and heavy-forming operations tolerating hydraulic inefficiency.
- Servo Presses:Electromechanical actuation with programmable slide motion delivers stroke-specific energy delivery, eliminating flywheel inertia losses. German and Japanese automotive OEMs specify these for aluminum-intensive body panels under EU Machinery Directive compliance timelines. Input volatility in rare-earth magnet supply chains constrains capacity expansion.
- Hydraulic Presses:Fluid-power systems generate sustained force throughout the stroke for deep-drawing and forging above 5,000 tons. Chinese heavy equipment manufacturers and European forging houses maintain installed bases despite F-Gas Regulation compliance costs for hydraulic fluid management.
- Mechanical Presses:Flywheel-driven crank mechanisms dominate legacy installations in cost-sensitive metal fabrication.
- Pneumatic Presses:Compressed-air actuation serves light-duty assembly and blanking in electronics and consumer goods manufacturing.
Volume sits with Hydraulic Presses; growth tilts toward Servo Presses.
Application:
End-use concentration determines specification intensity, with safety-critical applications demanding traceable force control and commodity fabrication tolerating simpler architectures.
- Automotive Manufacturing:Stamping lines for electric vehicle platforms require programmable ram profiles to manage aluminum springback and die wear. OEM retooling cycles in Germany, China, and the United States drive specification of servo-electric systems with integrated condition monitoring.
- Metal Fabrication:Job shops and contract manufacturers prioritize equipment flexibility across material gauges and batch sizes. Indian fabricators under PLI scheme incentives expand servo press adoption for precision components.
- Aerospace Components:Titanium and superalloy forming demands closed-loop force control and heated die systems for airframe and engine applications.
- Plastic Molding:Injection and compression molding applications favor hydraulic clamping force for complex geometries in packaging and medical devices.
Revenue concentrates in Automotive Manufacturing; steepest expansion trajectory appears in Metal Fabrication as developing economies industrialize.
End User:
Procurement authority and technical capability separate buyers, with integrated manufacturers controlling specification and distributors managing spare parts logistics.
- OEMs:Automotive and appliance manufacturers specify complete stamping lines with integrated automation, bundling equipment procurement under fleet-management contracts. German OEMs lead adoption of open-architecture servo control platforms for line reconfiguration flexibility.
- Tier-1 Suppliers:Dedicated stamping operations for single OEM programs face margin pressure from tooling amortization and energy costs. Chinese Yangtze River Delta suppliers shift from spot purchases to multi-year service partnerships transferring operational risk.
- Manufacturers:Captive fabrication shops in heavy machinery and industrial equipment balance make-versus-buy decisions for component supply.
- Aftermarket Providers:Independent rebuild and spare parts distributors serve legacy hydraulic and mechanical installed bases with shorter replacement cycles.
Decision authority rests with OEMs; commercial momentum builds among Tier-1 Suppliers adopting outcome-based service agreements.
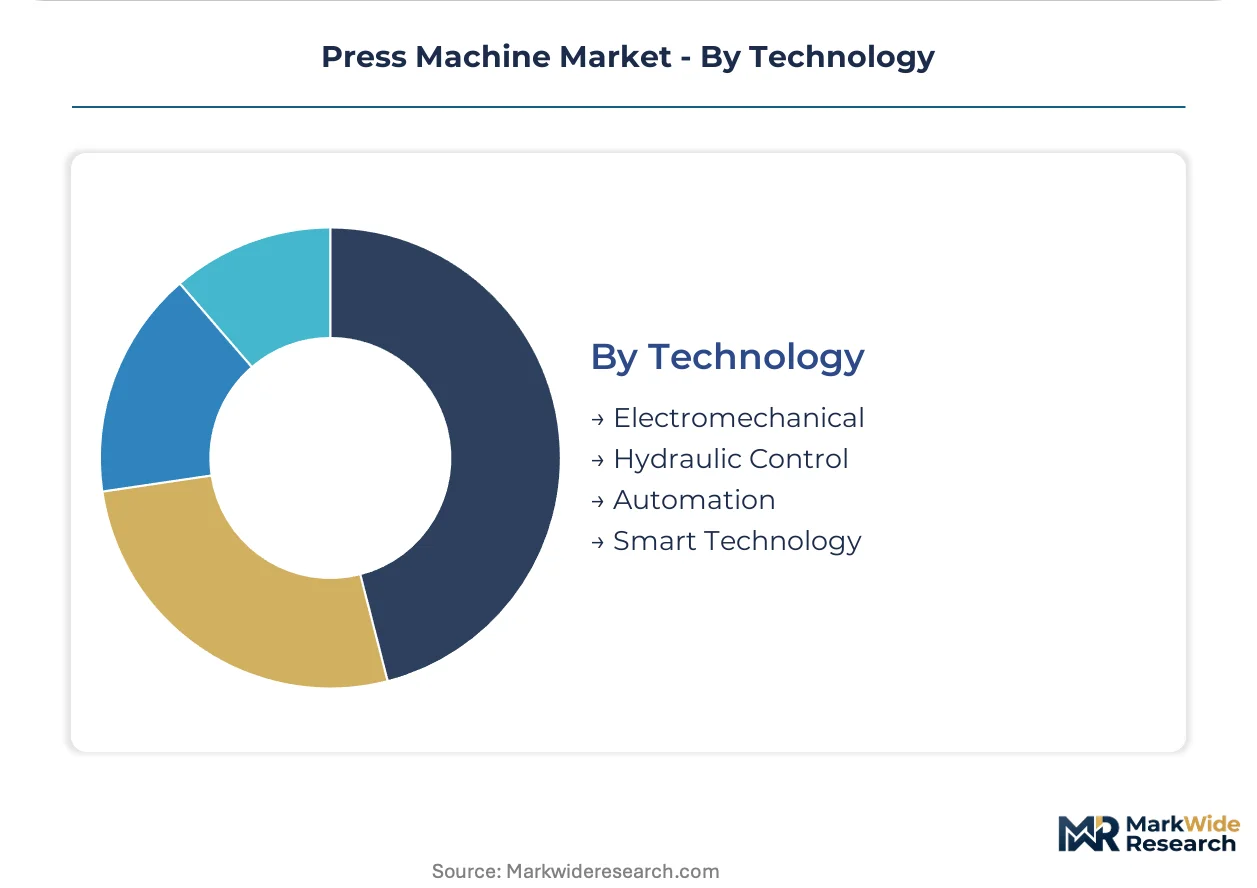
Technology:
Control architecture sophistication determines competitive differentiation, with premium positioning requiring sensor integration and software-enabled optimization.
- Electromechanical:Servo motor and drive systems replace mechanical linkages for programmable motion profiles. Japanese precision motor manufacturers and German drive engineering houses anchor supply chains for automotive lamination and high-speed progressive die operations.
- Smart Technology:IoT-enabled condition monitoring with cloud analytics transforms maintenance from scheduled rebuilds to predictive intervention. Tier-1 suppliers managing distributed stamping operations capture downtime reduction and spare part demand forecasting.
- Hydraulic Control:Proportional valve and closed-loop pressure management retain relevance in heavy forging where force stability outweighs speed.
- Automation:Robotic material handling and die change systems integrate with press controls for unmanned operation in high-volume environments.
Deployment scale favors Electromechanical; capability investment concentrates in Smart Technology as aftermarket revenue models evolve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth magnet deposits in China's Inner Mongolia and Jiangxi provinces anchor the servo press supply chain, concentrating electromechanical component manufacturing in East Asian industrial corridors. Equipment procurement patterns diverge sharply across major manufacturing economies as regulatory frameworks and automotive retooling cycles reshape regional demand.
China
Domestic equipment builders expand capacity for metal fabrication and plastic molding applications under the dual carbon goals and MIIT industrial upgrading directives. GB standards for mechanical safety tighten certification requirements for multinational suppliers. The Yangtze River Delta cluster around Shanghai and Suzhou drives battery cell housing stamping demand for electric vehicle battery pack assembly.
Germany
Automotive OEMs retool stamping lines for aluminum-intensive body-in-white architectures, accelerating servo press adoption under EU Machinery Directive 2006/42/EC compliance timelines. KBA vehicle certification requirements cascade into press equipment specifications. The Stuttgart and Munich industrial corridors concentrate precision stamping operations for premium electric vehicle platforms.
United States
OSHA machine guarding standards and NHTSA vehicle safety mandates shape press equipment retrofit demand across legacy automotive stamping operations. The IRA manufacturing incentives support domestic capital goods production. The Southeast manufacturing belt spanning Tennessee, Kentucky, and Alabama attracts new press capacity for electric vehicle supply chain localization.
Japan
METI industrial competitiveness programs fund servo motor and drive system development for precision lamination applications in electric motor manufacturing. JIS standards govern mechanical safety certification for domestic and export equipment. The Nagoya industrial corridor anchors high-speed progressive die operations for automotive and electronics components.
India
Domestic equipment builders expand metal fabrication capacity under PLI scheme incentives for capital goods manufacturing. BIS certification requirements create entry barriers for imported press systems. The Pune-Nashik corridor in Maharashtra and the Chennai cluster in Tamil Nadu concentrate automotive stamping operations for domestic and export markets.
Press Machine Market Competitive Environment
Global majors compete with regional champions across technology tiers and geographic proximity to end-user clusters. The vendor base separates into consolidated electromechanical specialists, diversified heavy-forging houses, and emerging Asian fabricators. Three archetypes dominate: heritage European engineering houses with automotive lineage, Japanese precision motor-press integrators, and Chinese cost-optimized equipment builders. Competitive moves concentrate on M&A for servo control technology access and strategic partnerships for battery stamping application development.
Within the heritage engineering tier, Schuler and Komatsu occupy positions anchored to large-scale automotive stamping lineage. AIDA Engineering exemplifies the precision servo specialist archetype. Among Asian fabricators, JDM Jingda Machine and Tianduan Press represent regional champions competing on proximity to domestic demand clusters. SMS Group sits within the diversified heavy-industrial equipment category spanning forging and forming applications.
| Leading Market Players |
|---|
| Schuler |
| Amada |
| AIDA Engineering |
| JDM Jingda Machine |
| LVD |
| Komatsu |
| SMS Group |
| Goodsjack |
| Tianduan Press |
| Others |
Value Chain & Pricing Dynamics
Tier-1 automotive stampers in Germany and China's Yangtze River Delta command project-based pricing with multi-year fleet-management contracts bundling equipment, maintenance, and consumables. This procurement concentration shifts pricing power toward OEMs while locking equipment builders into outcome-based service revenue models.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium servo press offerings from unbundled mechanical press transactions. Three-tier pricing structure across premium, standard, and economy levels reflects CE certification grade and servo motor precision tier. Pricing pressure stems from rare-earth magnet cost volatility in concentrated DRC and Chilean mining operations. Tier-2 automotive suppliers in India exhibit highest price sensitivity under PLI scheme capital constraints.
Supply Chain Analysis
CE marking and GB standards qualification gating restricts supplier participation in European and Chinese procurement. Rare-earth magnet production concentrates in China's Inner Mongolia and Jiangxi provinces, with Japanese precision motor manufacturers anchoring drive system supply. Copper winding and high-grade steel feedstock dependencies create input cost exposure. Single-source vulnerability in permanent magnet supply chains threatens servo press capacity expansion. Distribution runs through OEM-direct sales teams and regional equipment distributors serving legacy installed bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Press machine manufacturing is becoming a vertical-integration race as servo motor and drive system capabilities determine competitive positioning. Players are pursuing backward integration into rare-earth magnet supply chains to secure electromechanical component availability.
For Market Incumbents: Lock in aftermarket service contracts with predictive maintenance platforms to defend against IoT-enabled entrants. Secure captive supply agreements for neodymium magnet feedstock from Jiangxi province processors. Expand certified rebuild capacity for legacy hydraulic installed bases facing EU F-Gas Regulation compliance deadlines.
For New Entrants and Emerging Players: Begin with battery cell housing stamping applications in India's Pune-Nashik corridor where domestic PLI incentives reduce import competition. Target precision aluminum forming for electric vehicle battery enclosures with modular servo press architectures. Pursue fleet-management contract structures mirroring German OEM procurement patterns.
For Investors and Strategic Acquirers: The window for entry favors servo control technology specialists with open-architecture software platforms. Long-term viability hinges on electromechanical system integration capabilities replacing legacy mechanical press expertise. Monitor EU Machinery Directive enforcement intensity as inflection indicator for European replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Servo Control Technology Acquisition | Schuler and AIDA Engineering compete for programmable motion expertise in automotive stamping. |
| Rare-Earth Magnet Supply Agreement | Japanese drive manufacturers secure NdFeB magnet offtake from Chinese Jiangxi processors. |
| IoT-Enabled Condition Monitoring Platform | Tier-1 suppliers capture predictive maintenance revenue beyond traditional spare part sales. |
| Battery Cell Housing Stamping Capacity | Yangtze River Delta fabricators serve electric vehicle battery pack assembly demand. |
| EU Machinery Directive Certification Investment | German OEMs mandate electromechanical safety compliance for aluminum-intensive body panels. |
Study Parameters
Multi-period observation of servo press adoption rates and automotive OEM retooling cycles anchored the trend analysis, supplemented by interviews with maintenance directors at Tier-1 stamping operations, plant engineers at German automotive OEMs, procurement leads at Chinese equipment builders, and aftermarket service heads at European distributors. Secondary validation drew from SEC filings of listed press manufacturers, MIIT industrial upgrading directives, EU Machinery Directive implementation guidance, and customs data on electromechanical component trade flows. Bottom-up equipment shipment tallies and top-down automotive capital expenditure estimates were triangulated to establish market sizing.
Segment-weighting across product type, application, end user, and technology dimensions shaped the analytical framework. Servo press, hydraulic press, mechanical press, and pneumatic press categories were modeled separately with force-range and energy-efficiency parameters. Automotive manufacturing, metal fabrication, aerospace components, and plastic molding applications carried distinct specification intensity assumptions. CAGRs were derived from regression analysis against automotive production forecasts and regulatory compliance timelines. Rare-earth magnet supply constraints and EU F-Gas Regulation implementation schedules served as industry-specific forecast inputs.
Underlying measurement precision varies by segment; servo press and electromechnical technology categories carry tighter precision than legacy mechanical press estimates due to concentrated supplier reporting. Forecasts reflect assumptions about electric vehicle platform retooling intensity and rare-earth magnet supply chain stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Parting-Off Blades Market
Tools
Bearing Installation Tool Kit Market
Tools
Mechanical Springs Market
Tools
Forging Press Market
Tools
Automatic Heat Press Machines Market
Tools
Air Hammer Market
Tools
Hand Tools Market
Tools
Painting Tools Market
Tools
Asia Pacific Power Tools & Hand Tools Market
Tools
Global Cordless Power Tools Market
Tools
Rotary Knife Cutters Market
Tools
Global Scarifiers Market
Tools
Wire Cutters Market
Tools
Orbital Sanders Market
Tools
Global Zero Point Clamping System Market
Tools
Rocket Wrench Market