
 Global Cordless Power Tools Market | 2026-2036
Global Cordless Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cordless Power Tools Market Intelligence
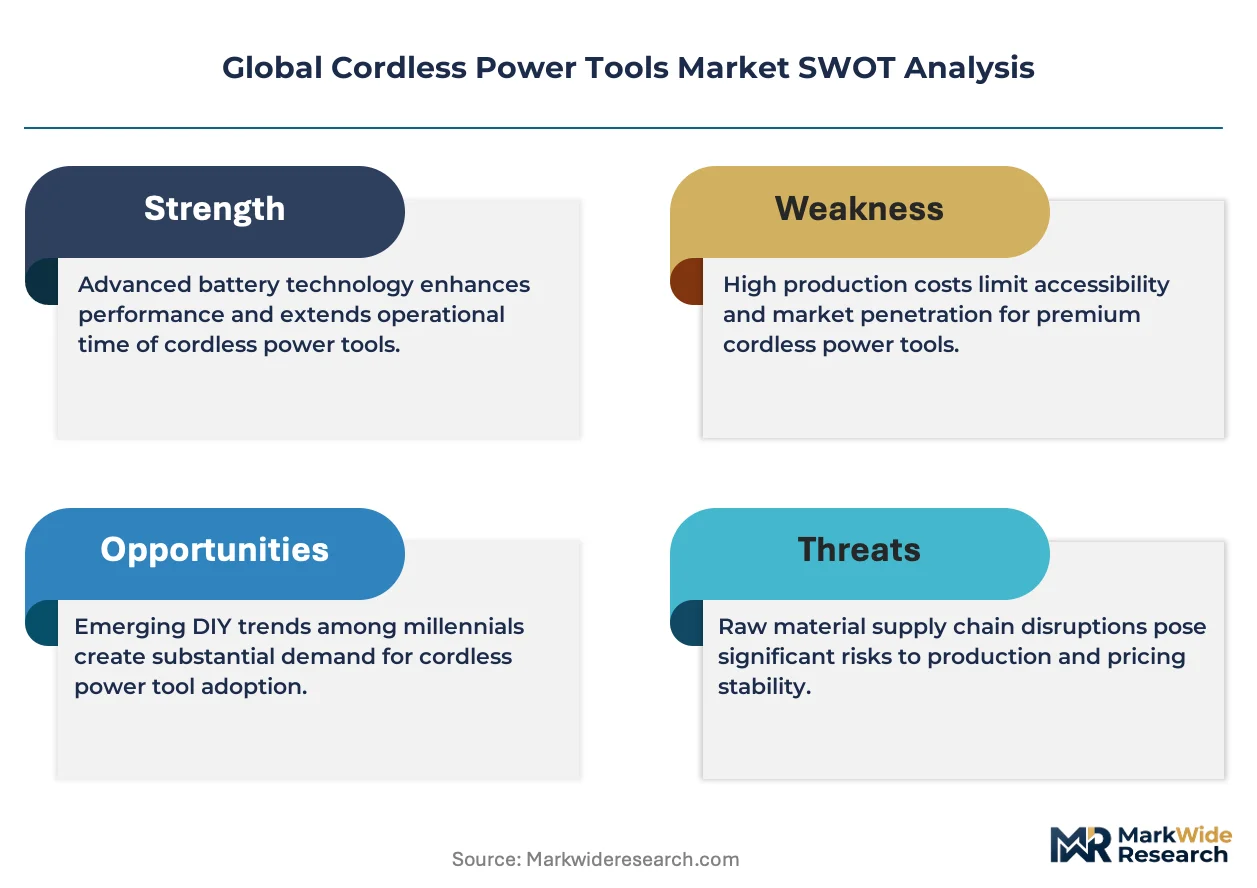
REACH compliance is realigning the cost-of-entry calculus for cordless power tool manufacturers selling into European markets. Stanley Black & Decker leverages its vertical integration into battery cell sourcing to sustain margin stability under these chemical disclosure rules. Robert Bosch dominates the professional-grade segment through German engineering standards that competitors struggle to match at equivalent certification tiers. Makita anchors its competitive position in Asia-Pacific through manufacturing scale and channel control across industrial distribution networks.
Cordless power tools are portable, battery-driven mechanical devices that convert stored electrical energy into rotational or percussive force for cutting, fastening, grinding, or surface finishing operations, typically operating at voltages from 12V to 60V with lithium-ion chemistry as the dominant energy storage medium. Their primary commercial purpose is to deliver pneumatic-equivalent performance without tethered air supply infrastructure, enabling mobility across construction sites, fabrication workshops, and residential renovation environments. Drills and impact drivers together occupy the largest volume position, though brushless motor technology captures the most attractive margin pool as efficiency standards tighten. Lithium-ion battery packs represent the fastest-growing technology segment, displacing nickel-cadmium alternatives as cell energy density improves and recycling infrastructure matures across major manufacturing hubs.
EMA chemical safety standards, EPA hazardous substance rules, and ISO 9001 quality management frameworks collectively shape product design cycles, material selection, and market access timelines for cordless power tool manufacturers. EMA oversight of workplace exposure limits pushes OEMs toward sealed brushless designs that reduce particulate generation during heavy-duty cutting applications. Stakeholders must monitor how battery passport requirements under the EU Battery Regulation will alter supply chain documentation burdens and aftermarket service economics before committing to regional manufacturing footprints.
Market Dynamics
Battery cell supply concentration in China and South Korea is compressing procurement timelines while EU F-Gas Regulation mandates accelerate the displacement of pneumatic systems on European construction sites.
Growth Catalysts
- EU F-Gas Regulation phase-down:Refrigerant restrictions on pneumatic compressors are forcing German and French contractors toward battery-powered alternatives for HVAC installation and metalworking tasks.
- Lithium-ion energy density gains:Cell manufacturers in South Korea and Japan are delivering 300Wh/kg packs that extend runtime for 60V professional-grade rotary hammers without weight penalties.
- Residential electrification mandates:California's Title 24 building codes and parallel ordinances in New York City are eliminating gas-powered equipment from renovation permits, expanding addressable demand for cordless alternatives.
Market Restraints
- Lithium carbonate price volatility:Raw material input swings between Chilean and Australian supply sources are compressing gross margins for pack assemblers lacking long-term offtake agreements.
- Brushless motor controller concentration:Silicon carbide MOSFET fabrication capacity concentrates in Taiwanese foundries, creating single-source vulnerability for high-efficiency drive systems.
- Nickel-cadmium legacy infrastructure:Existing fleet investment in 18V Ni-Cd platforms by US municipal maintenance departments creates switching cost friction against lithium-ion migration.
Strategic Opportunities
- India construction equipment electrification:BIS certification pathways for 36V-54V industrial tools remain underdeveloped, creating first-mover advantage for OEMs establishing local assembly under PLI scheme incentives.
- Battery passport compliance services:EU Battery Regulation documentation requirements will generate recurring revenue streams for third-party traceability platforms serving mid-tier manufacturers.
- Brushless-IoT convergence:Tool telemetry integration with construction management software is enabling usage-based warranty pricing for fleet operators in Australian mining and infrastructure verticals.
Industry Challenges
- Power electronics engineering scarcity:Field-oriented control firmware expertise for sensorless brushless motors concentrates in German and Japanese engineering clusters, constraining product development velocity elsewhere.
- REACH SVHC disclosure complexity:ECHA candidate list expansion for cobalt compounds in battery cathodes is extending European market access timelines by 8-14 months for non-vertically integrated suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cordless Power Tools Market |
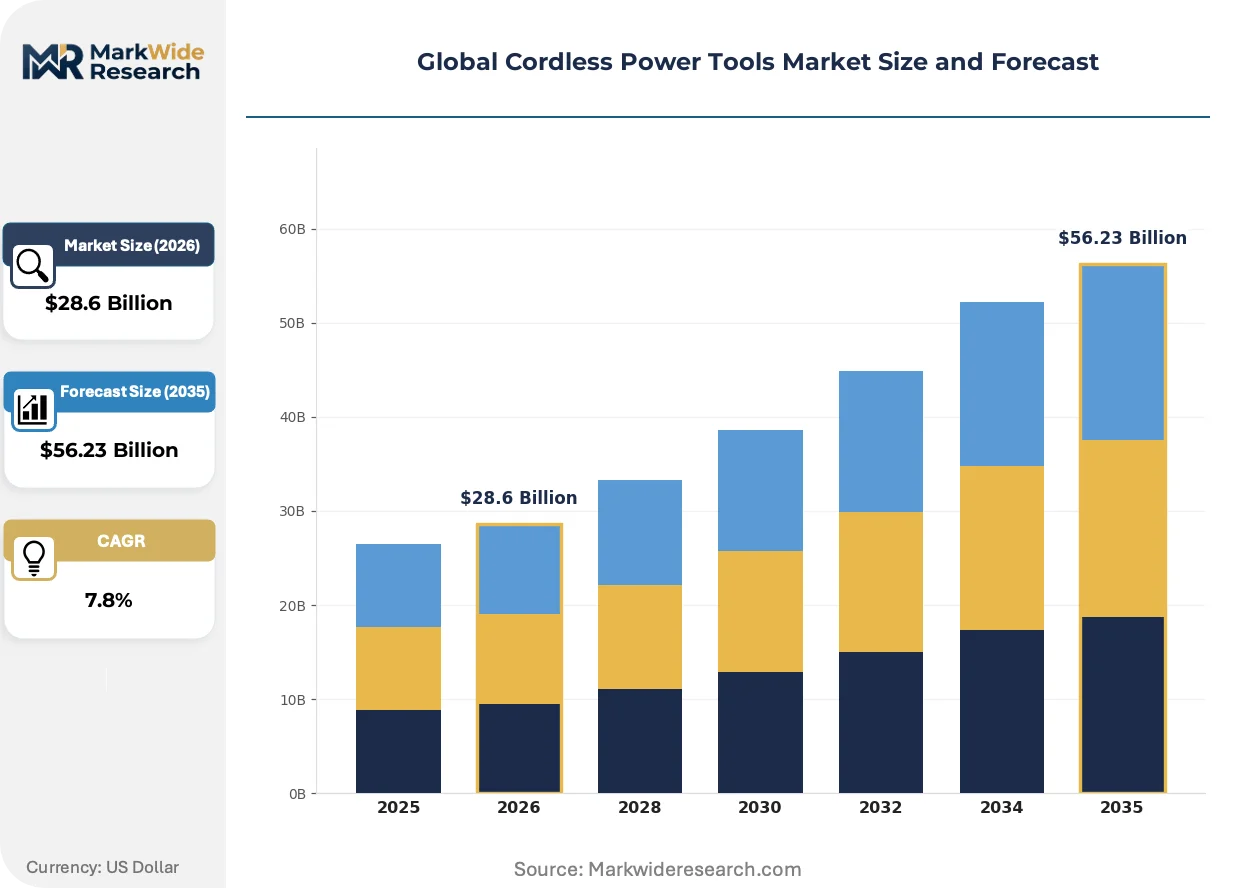
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $56.23 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Impact Drivers, Saws, Sanders, Grinders, Nailers Technology: Brushless Motor, Lithium-Ion Battery, Nickel-Cadmium Battery, Lithium-Polymer Battery, Corded Hybrid Application: Residential Construction, Renovation Projects, Woodworking, Metal Fabrication, Masonry, Outdoor Landscaping End User: DIY Enthusiasts, Home Improvement Contractors, Fabricators, Landscapers, Maintenance Technicians, Assembly Line Workers |
| Companies Covered | Stanley Black & Decker, Robert Bosch, Makita, Techtronic Industries, Hilti, Apex Tool Group, Koki Holdings, Snap-on, Festool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cordless Power Tools Market Strategic Shifts & Innovations
Tool intelligence, energy storage chemistry, and regulatory traceability are converging to redefine competitive differentiation beyond torque specifications and warranty duration.
Brushless motor control is converging with embedded torque sensing to enable automatic stall prevention and bit-breakage mitigation. Commercial contractors in North American residential framing are specifying these smart-drive systems for crew safety liability reduction. The technology is compressing differentiation timelines as sensor fusion becomes standard across premium and mid-tier product lines simultaneously.
REACH substance-of-very-high-concern listings for cobalt and nickel compounds are forcing cathode chemistry pivots toward lithium iron phosphate and high-nickel low-cobalt alternatives. European OEMs with established ECHA compliance infrastructure are absorbing re-certification costs faster than export-dependent competitors. Professional-grade 40V-60V platforms are most affected, with German and Nordic markets showing earliest preference for disclosed supply chain documentation.
Construction fleet managers are consolidating procurement through integrated tool-and-battery subscription models rather than capital purchase programs. Industrial distributors in Japan and South Korea are displacing traditional retail channels with depot-based asset management services. Australian commercial contractors represent the most visible adoption cluster, driven by project-based accounting requirements and cross-site equipment utilization tracking needs.
Global Cordless Power Tools Market Segmentation
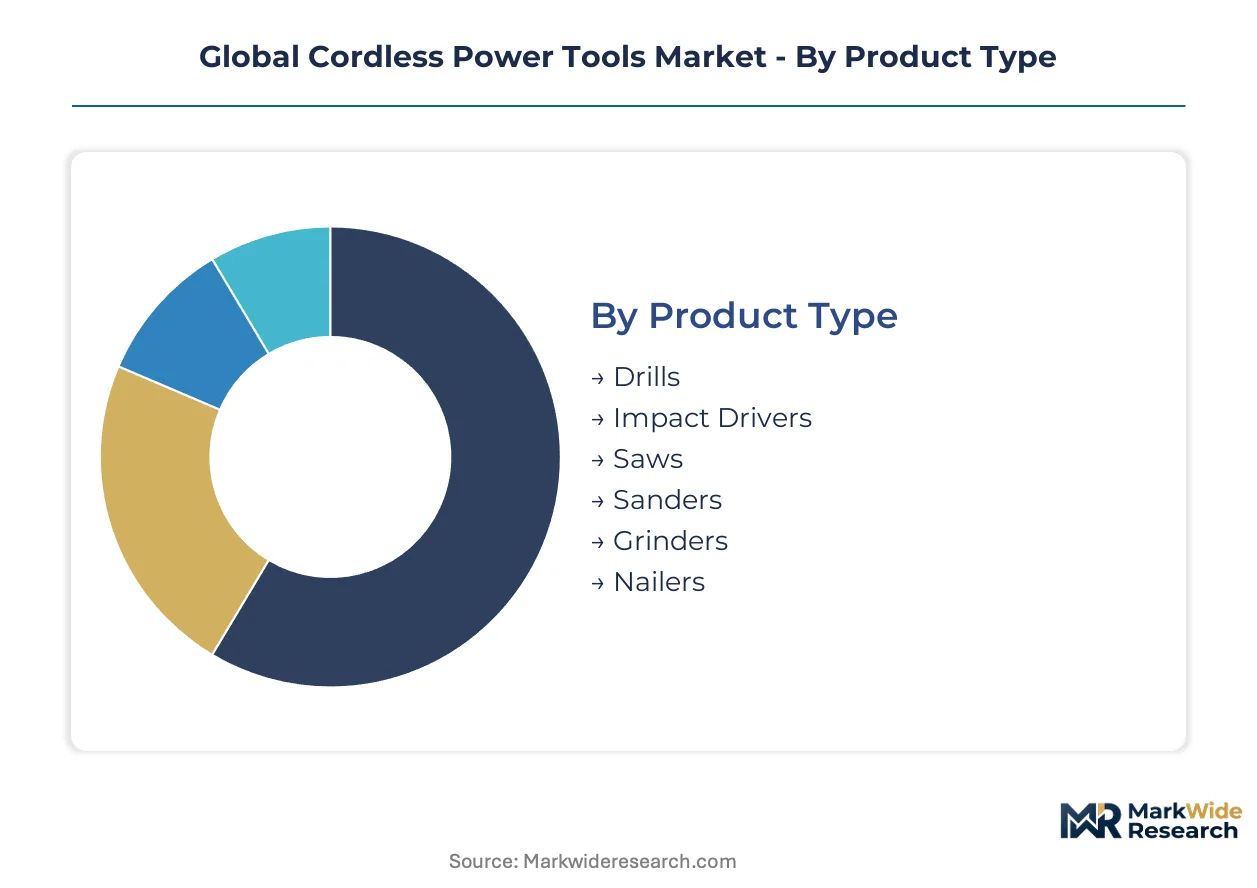
Cordless power tool manufacturers configure product portfolios around torque-band specialization, battery platform compatibility, and duty-cycle intensity. Segmentation discipline separates professional-grade fleet suppliers from retail-channel specialists serving intermittent-use buyers. The analysis below maps how technical specifications, user economics, and regulatory exposure distribute across four structural dimensions.
Product Type:
Standardization dominates high-volume categories where interchangeability drives fleet economics, while specialized attachments command premium positioning in trade-specific applications.
- Drills:Rotary-percussive mechanisms operating at 12V-20V dominate residential installation workflows. German and French electrical contractors are consolidating procurement around 18V brushless platforms to satisfy EU F-Gas phase-down requirements for on-site compressor elimination.
- Impact Drivers:High-torque pulse mechanisms deliver fastening force without reactive torque injury risk. Australian commercial framing crews specify these systems for liability reduction under WorkSafe Victoria guidance, with telemetry-enabled models capturing fleet management contracts.
- Saws:Circular and reciprocating variants serve demolition and rough carpentry with blade-speed optimization.
- Sanders:Orbital and belt configurations address surface finishing with dust extraction integration.
- Grinders:Angle and die grinder formats target metal fabrication with disc-speed control.
- Nailers:Battery-powered framing and finish nailers displace pneumatic units where compressor logistics constrain mobility.
Most installed capacity flows through Drills. Expansion is steepest in Impact Drivers.
Technology:
Cost tier stratification separates mature nickel-cadmium infrastructure from lithium-ion platforms capturing professional-grade replacement cycles.
- Brushless Motor:Sensorless field-oriented control eliminates commutator friction losses, extending runtime 30-50% versus brushed equivalents. Japanese OEMs dominate controller firmware engineering, constraining supply for mid-tier manufacturers seeking 60V professional-grade rotary hammer certification.
- Lithium-Ion Battery:18650 and 21700 cylindrical cell formats at 300Wh/kg energy density enable 40V-60V platforms without weight penalties. South Korean cell manufacturers are prioritizing supply to captive tool brands, compressing procurement access for independent assemblers.
- Nickel-Cadmium Battery:Legacy 18V platforms persist in US municipal maintenance fleets with sunk capital in compatible chargers.
- Lithium-Polymer Battery:Pouch-cell configurations serve compact 12V homeowner tools with form-factor flexibility.
- Corded Hybrid:Dual-power architectures bridge battery runtime constraints for continuous-duty metal fabrication.
Professional-grade volume concentrates in Brushless Motor configurations. Steepest expansion trajectory belongs to Lithium-Ion Battery as nickel-cadmium phase-out accelerates under REACH substance restrictions.
Application:
Customer type differentiation separates project-based contractors from maintenance organizations with predictable utilization patterns.
- Residential Construction:Framing, electrical, and plumbing rough-in tasks demand 18V-20V drill-driver combinations with all-day runtime. California Title 24 electrification mandates are eliminating gas-powered equipment from renovation permits, expanding addressable demand for battery alternatives.
- Renovation Projects:Intermittent-use intensity favors compact 12V platforms with rapid charger compatibility for multi-trade crews.
- Woodworking:Precision routing and joinery applications prioritize variable-speed control and dust extraction integration.
- Metal Fabrication:Continuous-duty grinding and cutting stress thermal management systems in 60V platforms.
- Masonry:Rotary hammer applications require impact energy delivery comparable to pneumatic equivalents.
- Outdoor Landscaping:Seasonal utilization patterns favor battery-platform sharing with handheld construction tools.
Current fleet deployment centers on Residential Construction. Gaining share fastest is Renovation Projects as housing stock turnover accelerates in Germany and Japan.
End User:
Volume scale separates mass-market retail channels from industrial distribution serving fleet procurement with asset-tracking requirements.
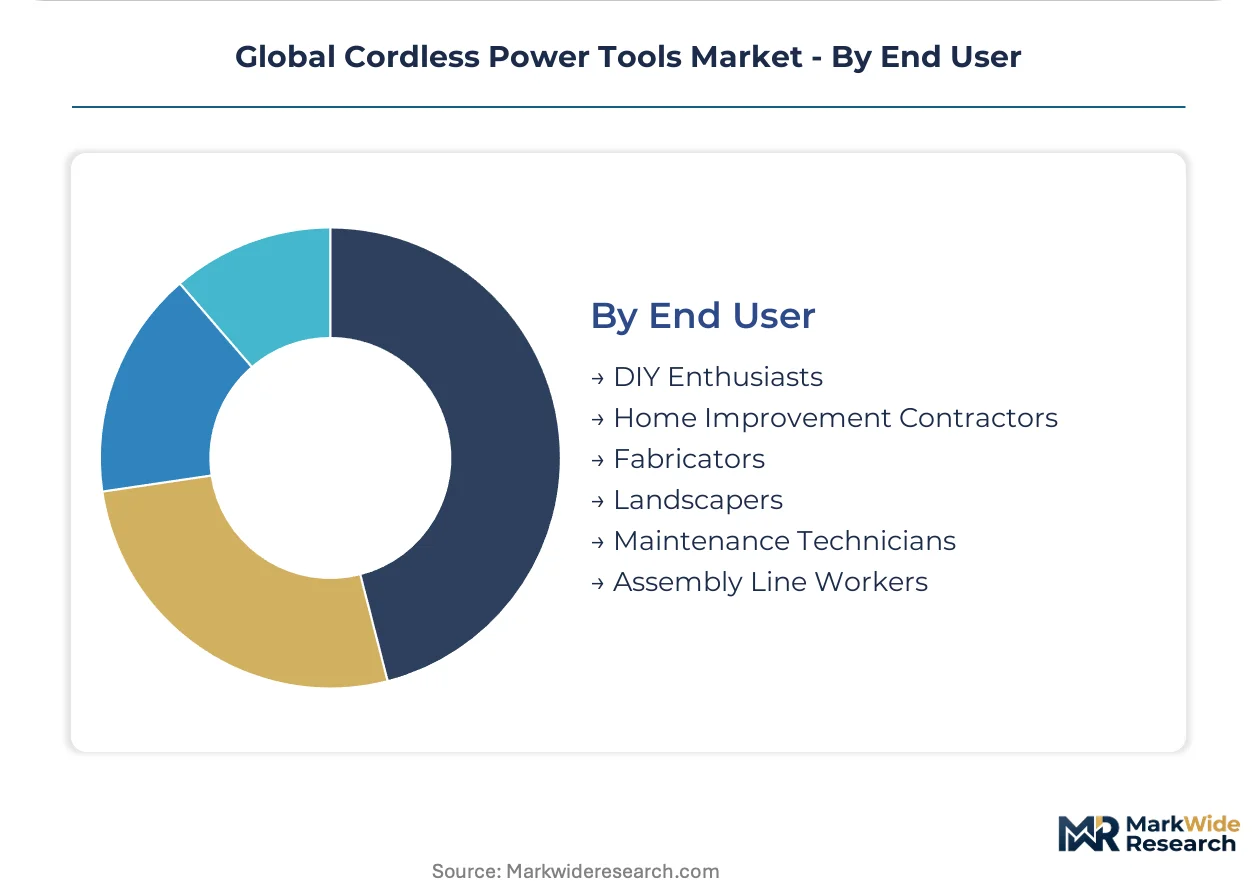
- DIY Enthusiasts:Intermittent-use homeowners prioritize 12V-18V combo kits with charger interoperability across drill, impact, and saw applications. Retail margin compression in this segment is forcing OEMs toward direct-to-consumer battery subscription models.
- Home Improvement Contractors:Small-scale renovation specialists balance tool performance against capital recovery timelines on project-based accounting.
- Fabricators:Metalworking shops specify 60V grinders with thermal overload protection for continuous-duty cycles.
- Landscapers:Seasonal equipment sharing with construction crews drives battery-platform consolidation decisions.
- Maintenance Technicians:Municipal and facility fleets with legacy Ni-Cd infrastructure face switching-cost friction against lithium-ion migration.
- Assembly Line Workers:Manufacturing ergonomics programs specify lightweight 12V-18V tools for repetitive fastening tasks.
Unit volume leadership sits with DIY Enthusiasts. Climbing the fastest is Home Improvement Contractors as residential electrification mandates reshape equipment requirements across US and European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German engineering clusters and Chinese battery manufacturing hubs anchor workforce concentrations that shape regional competitive positioning. Japanese precision motor expertise and South Korean cell chemistry capabilities concentrate specialized talent pools. Australian commercial construction markets demonstrate advanced fleet management adoption patterns.
United States
Residential electrification mandates in California and New York are eliminating gas-powered equipment from renovation permits. EPA refrigerant phase-down rules under Section 608 accelerate pneumatic system displacement. Dallas-Fort Worth metroplex contractors are consolidating procurement around 18V-20V brushless platforms for HVAC installation workflows.
Germany
Professional-grade demand concentrates among electrical and metalworking contractors seeking pneumatic-equivalent performance. EU F-Gas Regulation phase-down restrictions compress compressor deployment on construction sites. Stuttgart engineering corridor OEMs dominate sensorless field-oriented control firmware for 60V rotary hammer certification tiers.
China
Domestic manufacturers scale lithium-ion cell production to serve both local tool makers and export markets. MIIT battery industry standards and dual carbon goals reshape cathode chemistry investment priorities. Suzhou and Shenzhen manufacturing clusters concentrate pack assembly capacity for 21700 cylindrical cell formats.
Japan
Construction fleet managers consolidate procurement through integrated tool-and-battery subscription models rather than capital purchase programs. METI industrial standards govern brushless motor efficiency certification for professional-grade platforms. Nagoya industrial distribution networks displace traditional retail channels with depot-based asset management services.
Australia
Commercial contractors represent the most visible adoption cluster for telemetry-enabled fleet tracking under project-based accounting requirements. WorkSafe Victoria guidance specifies impact driver systems for liability reduction in framing crews. Melbourne and Sydney infrastructure verticals drive usage-based warranty pricing for brushless-IoT convergence platforms.
Global Cordless Power Tools Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across certification-tier stratification. The vendor base organizes around three strategic archetypes: vertically integrated battery cell producers, German engineering-standard bearers, and Asia-Pacific manufacturing scale operators. Consolidation pressure intensifies as REACH compliance costs and EU Battery Regulation documentation requirements favor integrated suppliers over independent assemblers. Dominant competitive moves include backward integration into lithium-ion cell sourcing and strategic partnerships for silicon carbide MOSFET controller procurement.
Among diversified conglomerates with captive battery supply, Stanley Black & Decker exemplifies the vertically integrated archetype through upstream control over cell sourcing. Robert Bosch occupies a position as the German engineering-standard bearer in professional-grade certification tiers. Makita anchors the Asia-Pacific manufacturing scale vector through industrial distribution network control.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Robert Bosch |
| Makita |
| Techtronic Industries |
| Hilti |
| Apex Tool Group |
| Koki Holdings |
| Snap-on |
| Festool |
| Others |
Cost & Logistics Intelligence
Brushless motor controller migration to silicon carbide MOSFETs is simultaneously raising performance thresholds and concentrating procurement leverage among Taiwanese foundries serving premium-tier OEMs. This technology shift forces mid-tier manufacturers to absorb higher unit costs or cede professional-grade segments to vertically integrated competitors with captive controller supply.
Pricing Analysis
Bundled tool-and-battery subscription services are displacing transactional per-unit sales in fleet procurement channels. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered professional platforms from Asian-manufactured mid-tier alternatives and retail-channel homeowner kits. Pricing pressure stems from lithium carbonate volatility compressing pack assembler margins. DIY enthusiasts exhibit highest price sensitivity, while commercial contractors prioritize total-cost-of-ownership metrics including runtime and warranty coverage.
Supply Chain Analysis
India's PLI scheme incentives for domestic cell assembly are reshaping sourcing patterns for OEMs seeking tariff-advantaged access to South Asian construction markets. Battery cell production concentrates in China, South Korea, and Japan, with cylindrical 21700 formats dominating professional-grade platforms. The supply chain draws from cobalt and nickel cathode compounds, silicon carbide wafers, and rare-earth magnet materials. Single-source vulnerability concentrates in Taiwanese controller foundries. Distribution runs through industrial depot networks in developed markets and retail channels in residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between EU F-Gas compliance costs accelerating European pneumatic displacement and China's MIIT battery standards enabling lower-cost export platform development.
For Market Incumbents: Anchor competitive position through backward integration into 21700 cell sourcing to offset REACH SVHC disclosure burdens. Prioritize German engineering-center retention for sensorless field-oriented control firmware development. Defend against emerging pure-play battery specialists by locking long-term offtake agreements with South Korean cathode suppliers before capacity allocation tightens further. For New Entrants and Emerging Players: Industrial distributors in Australia and Japan represent the most accessible channel partners for telemetry-enabled fleet management services. White-space opportunity concentrates in India's BIS certification gap for 36V-54V industrial tools and EU Battery Regulation compliance services for mid-tier manufacturers lacking traceability infrastructure. Target construction fleet operators with usage-based warranty pricing models. For Investors and Strategic Acquirers: Valuations sit cheapest among non-vertically integrated pack assemblers exposed to lithium carbonate volatility without long-term supply contracts. Long-term viability favors OEMs with dual capability in brushless motor engineering and battery platform standardization. Monitor EU Battery Regulation implementation timelines as the critical inflection signal for aftermarket service economics restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Sourcing | Captive lithium-ion supply secures margin stability under REACH cobalt disclosure rules. |
| Silicon Carbide Controller Partnership | Taiwanese foundry alliances reduce single-source vulnerability for 60V platform certification. |
| Battery Passport Compliance Platform | Third-party traceability services generate recurring revenue from EU regulatory mandates. |
| Brushless-IoT Telemetry Integration | Tool intelligence enables usage-based warranty pricing for Australian mining fleet operators. |
| India PLI Scheme Local Assembly | Domestic certification pathways capture first-mover advantage in underdeveloped BIS standards. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's construction equipment procurement clusters. The analytical approach combines structured interviews with fleet managers at commercial contractors, procurement directors at industrial distributors, and engineering leads at OEM platform development teams. Secondary validation draws from EPA refrigerant phase-down filings, EU F-Gas Regulation implementation guidance, MIIT battery industry standards, and customs trade data for lithium-ion cell movements. Bottom-up segment sizing triangulates against top-down macroeconomic construction spending indicators.
Granularity-level modeling disaggregates volume and value across product type, voltage platform, end-user category, and regional regulatory cluster throughout the projection horizon. Segment-specific CAGRs derive from fitted growth curves calibrated to electrification mandate implementation schedules and replacement cycle dynamics for legacy nickel-cadmium fleets. Industry-specific forecast inputs include construction permit data from California Title 24 jurisdictions and EU building renovation wave targets.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to lithium carbonate price trajectories and silicon carbide fabrication capacity expansion timelines. The analytical framework assumes continued regulatory enforcement of F-Gas phase-down schedules and REACH substance restrictions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Total Station Market
Tools
Electric Power Tools Market
Tools
Forging Press Market
Tools
Mallets and Sledgehammers Market
Tools
Gear Honing Machines Market
Tools
Woodworking Tools Market
Tools
Tile Cutter Market
Tools
Hacksaw Blades Market
Tools
Gear Cutting Machines Market
Tools
Welding Products Market
Tools
Oxy-Fuel Torches Market
Tools
Ultra Hard Material Cutting Machines Market
Tools
Hydraulic Tools and Equipment Market
Tools
Coil Fed Punching and Cutting Machines Market
Tools
Pneumatic Tools Market
Tools
Hand Saw Market