
 Grease Gun Market | 2026-2036
Grease Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Grease Gun Market Foresight
Aftermarket service revenue is tilting toward battery-powered and connected tool ecosystems as operators seek to reduce downtime. Milwaukee Tool leverages its REDLITHIUM battery platform to anchor cordless grease gun adoption in heavy-duty workshops. SKF competes through integrated lubrication management systems that extend beyond hardware into condition monitoring services. Lincoln Industrial sustains its position via deep channel control through wholesale distributor networks serving fleet maintenance depots.
A grease gun is a mechanical or powered device designed to deliver lubricating grease under pressure through a coupler to bearings, joints, and fittings, typically operating at pressures ranging from 3,000 to 10,000 PSI depending on the model and application. Its primary industrial purpose is to ensure precise lubricant delivery in maintenance operations, preventing equipment failure and extending machinery life across manufacturing, transportation, and agricultural systems. Battery-powered grease guns are capturing the fastest expansion as workshop electrification reduces pneumatic infrastructure dependency, while manual variants retain dominance in cost-sensitive agricultural settings where capital constraints limit power tool adoption. High-pressure functionality commands premium positioning in mining and construction segments where equipment operates under extreme load conditions.
OSHA workplace safety standards and EPA environmental regulations governing lubricant handling and disposal shape product design requirements and channel compliance burdens for grease gun manufacturers operating in the United States. ISO 4406 cleanliness codes and NLGI consistency standards further define lubrication system compatibility, creating specification barriers for non-certified suppliers. Stakeholders must monitor the pace of cordless platform standardization and the shift toward sealed, contamination-resistant designs as maintenance intervals extend and precision greasing becomes a condition-monitoring input rather than a routine manual task.
Market Dynamics
Workplace electrification mandates and cordless platform standardization are compressing replacement cycles across fleet maintenance operations, forcing distributors to rebalance inventory toward battery-powered systems.
Growth Catalysts
- Predictive maintenance programs:Factory automation investments in automotive assembly plants are embedding grease guns into condition-monitoring workflows, expanding tool procurement budgets for integrated lubrication systems.
- OSHA battery-powered tool standards:Workplace safety requirements for cordless equipment are accelerating pneumatic-to-battery conversions in heavy-duty workshops, creating compliance-driven replacement demand.
- Fleet maintenance outsourcing:Third-party service providers in the United States are consolidating tool purchasing power and standardizing on high-pressure battery platforms to reduce downtime across multi-site operations.
Market Restraints
- Lithium-ion cell cost volatility:Battery pack input costs fluctuate with cobalt and nickel commodity markets, squeezing margins on cordless grease gun production.
- Pneumatic infrastructure lock-in:Legacy compressed air systems in established manufacturing facilities create switching friction that slows electrification timelines.
- NLGI consistency standard fragmentation:Regional lubricant formulation differences force manufacturers to maintain multiple coupler and seal specifications, complicating global product lines.
Strategic Opportunities
- Condition-monitoring convergence:Integration of grease delivery sensors with vibration analysis systems is opening service revenue streams beyond hardware sales.
- Agricultural mechanization:Large-scale farming operations in Brazil are transitioning from manual to powered lubrication tools as equipment uptime becomes critical.
- EU Green Deal lubricant handling rules:Stricter environmental compliance for grease disposal is favoring sealed, contamination-resistant tool designs with closed-loop refill systems.
Industry Challenges
- Cordless platform talent scarcity:Maintenance technicians trained on pneumatic systems require reskilling on battery management and electronic diagnostics, stretching workforce development budgets.
- ISO 4406 certification timelines:Cleanliness code compliance for precision bearings demands extended testing protocols that delay new product launches by months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grease Gun Market |
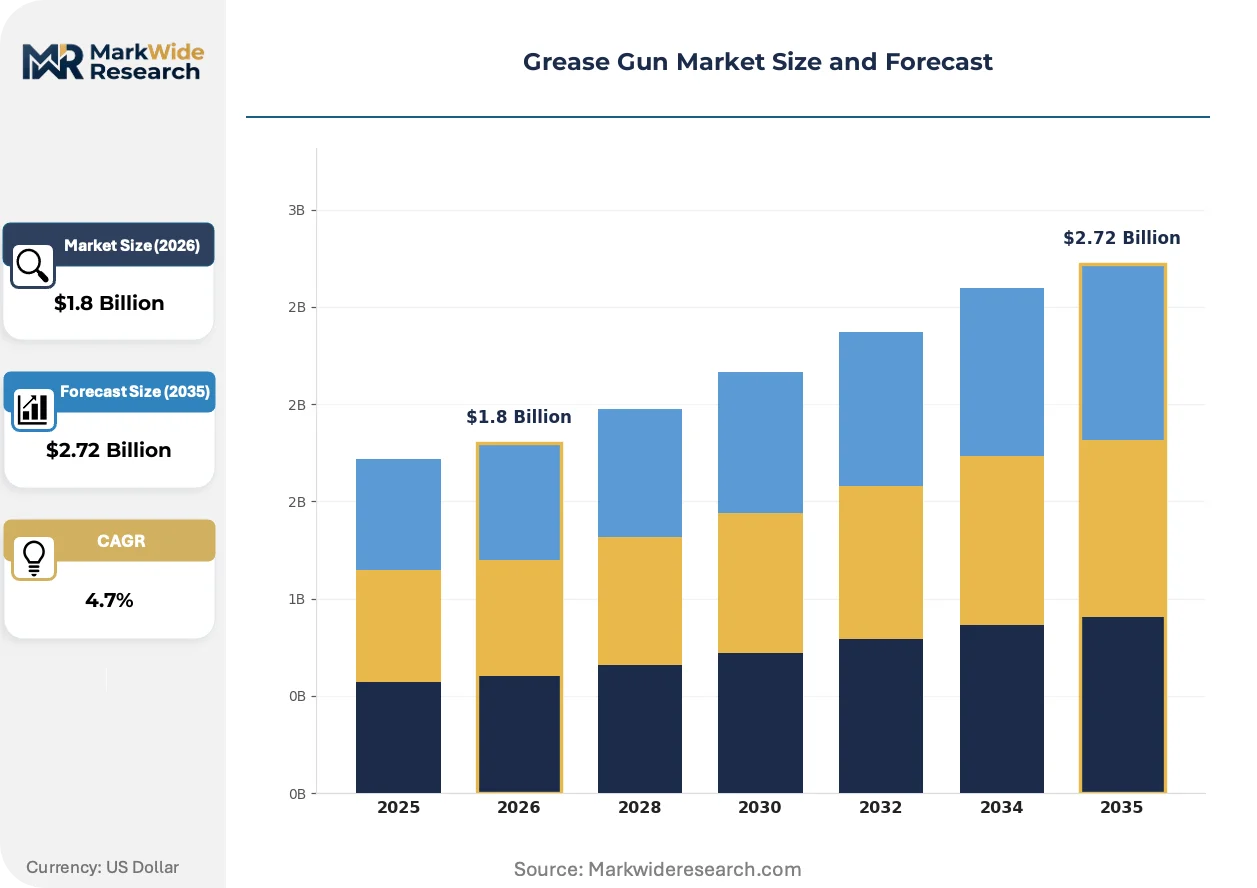
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Grease Guns, Pneumatic Grease Guns, Electric Grease Guns, Battery-powered Grease Guns End User: Automotive Repair Shops, Industrial Applications, Construction, Agriculture Distribution Channel: Online Retailers, Specialty Stores, Wholesale Distributors, Direct Sales Functionality: Standard Greasing, High-pressure Greasing, Automatic Greasing, Precision Greasing |
| Companies Covered | Milwaukee Tool, Ingersoll Rand, SKF, Macnaught, Groz Tools, Lincoln Industrial, Dewalt, Chicago Pneumatic, Alemite, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grease Gun Market Shifts & Advancements
Connected tool ecosystems and sealed lubrication architectures are transforming grease guns from passive hardware into data-generating maintenance nodes. Electrification, regulatory pressure, and procurement centralization are the dominant forces.
Smart grease guns with pressure sensors and Bluetooth connectivity are rendering obsolete manual logging of lubrication intervals. Mining operators in Australia are deploying these units to track bearing health in real time. The shift is compressing maintenance record-keeping from paper-based systems to automated asset management platforms.
EPA environmental regulations governing lubricant handling and disposal are mandating spill-proof designs and closed refill cartridges. Manufacturers serving the United States market are redesigning coupler interfaces to eliminate contamination points. Heavy construction segments face the steepest compliance burdens as job-site environmental liability expands.
Centralized procurement through fleet management companies is disintermediating traditional wholesale distributor relationships. Large logistics operators are negotiating direct supply agreements with manufacturers, bypassing regional tool distributors. This consolidation is most visible in United States trucking and rail maintenance depots where purchasing authority has shifted to corporate headquarters.
Grease Gun Market Segmentation
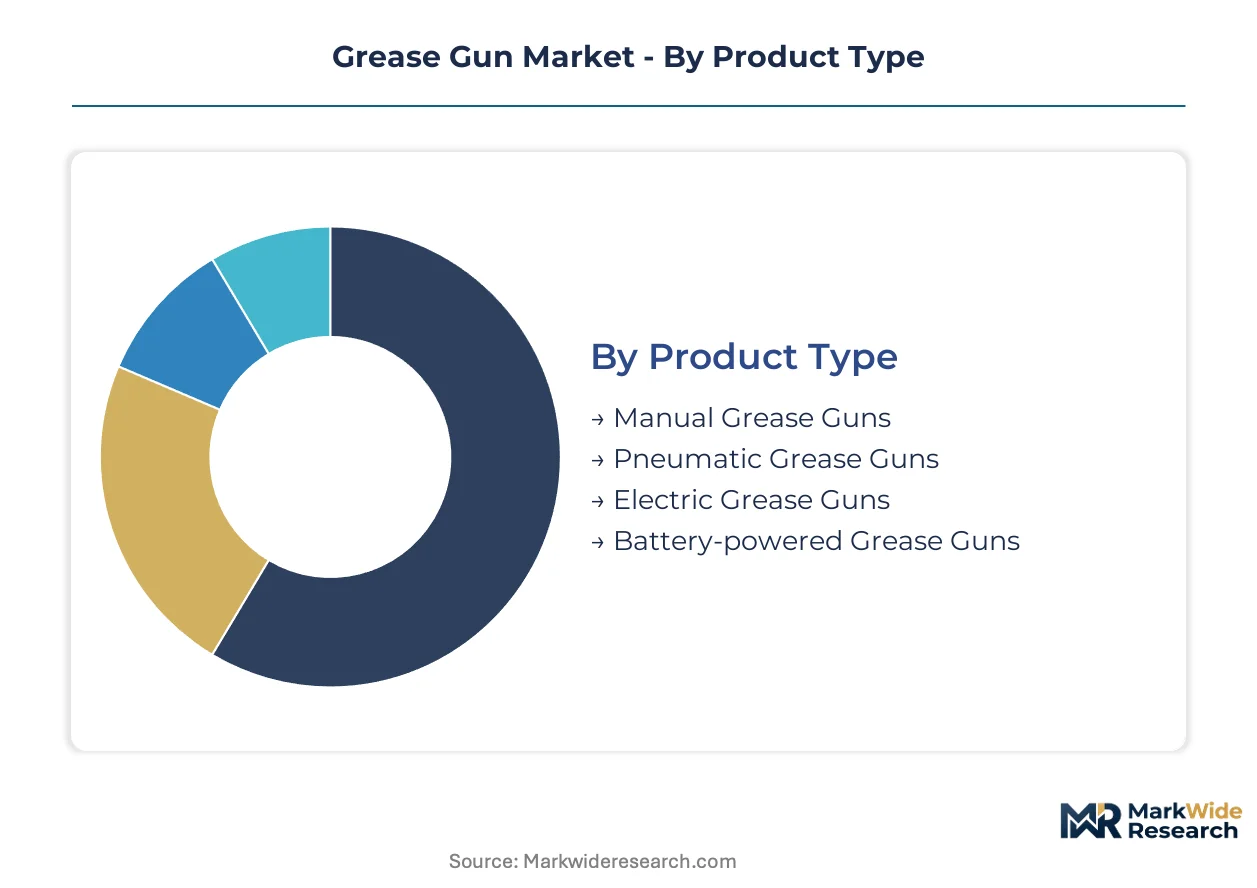
Grease gun segmentation reflects divergent maintenance workflows across electrified workshops and legacy pneumatic environments. Procurement patterns split between standardized fleet purchasing and fragmented agricultural supply chains, while functionality tiers separate routine lubrication from precision bearing management in automated plants.
Product Type:
Use cases span hand-operated field maintenance to high-volume automated lubrication systems in continuous production environments.
- Manual Grease Guns:Hand-powered lever or pistol-grip mechanisms deliver grease at 3,000-5,000 PSI through direct mechanical force. Demand concentrates in Brazilian agricultural operations and developing-market repair shops where capital constraints limit power tool procurement.
- Battery-powered Grease Guns:Cordless lithium-ion systems generate 10,000 PSI with programmable flow control and Bluetooth-enabled cycle tracking. United States fleet maintenance depots are standardizing on Milwaukee Tool REDLITHIUM and DeWalt 20V MAX platforms to eliminate pneumatic infrastructure dependency.
- Pneumatic Grease Guns:Compressed air-driven units maintain installed-base presence in legacy manufacturing facilities with existing shop air infrastructure.
- Electric Grease Guns:Corded AC-powered variants serve fixed-station applications in assembly plants where mobility requirements are limited.
The dominant share belongs to manual grease guns, while battery-powered grease guns are closing the gap fastest.
End User:
Customer sophistication ranges from individual mechanics to corporate procurement offices managing multi-site tool standardization.
- Industrial Applications:Manufacturing plants and processing facilities deploy grease guns within predictive maintenance programs tied to vibration monitoring systems. German automotive assembly plants specify ISO 4406-compliant units with sealed contamination-resistant architectures.
- Automotive Repair Shops:Independent and dealership service bays prioritize cordless platforms for under-vehicle access and reduced trip hazards. OSHA workplace safety standards for battery-powered tools are accelerating pneumatic replacement cycles across United States independent repair networks.
- Construction:Heavy equipment maintenance on job sites demands high-pressure functionality for excavator and loader pivot points exposed to extreme load conditions.
- Agriculture:Large-scale farming operations in Brazil and Argentina are transitioning from manual to powered lubrication as harvester uptime becomes critical to seasonal revenue.
Industrial applications command the largest procurement volumes, though automotive repair shops are expanding fastest through fleet outsourcing consolidation.
Distribution Channel:
Channel structure reflects the tension between centralized corporate purchasing and decentralized field-level replenishment needs.
- Wholesale Distributors:Regional industrial supply houses maintain inventory depth and technical support capabilities for fleet maintenance depots. Lincoln Industrial sustains market position through exclusive channel partnerships with Grainger and Fastenal in the United States.
- Online Retailers:Amazon Business and specialized MRO platforms are capturing specification-grade procurement from small-to-mid-size shops seeking price transparency. SKU proliferation of battery platform accessories complicates digital merchandising.
- Specialty Stores:Local tool retailers serve immediate replacement needs for agricultural and construction operators in remote locations.
- Direct Sales:Manufacturers negotiate enterprise agreements with logistics and rail operators, disintermediating traditional distribution.
Wholesale distributors retain the largest share, while direct sales are expanding most quickly through fleet management company consolidation.
Functionality:
Performance tiers separate commodity lubrication from precision delivery systems integrated into condition-monitoring architectures.
- High-pressure Greasing:10,000 PSI capability serves mining and construction equipment where bearing loads exceed standard specifications. Australian iron ore operators deploy these units with pressure sensors tracking real-time grease acceptance rates as a proxy for bearing health.
- Precision Greasing:Metered delivery systems with digital flow control prevent over-lubrication contamination in wind turbine and semiconductor manufacturing bearings. EU Green Deal lubricant handling rules favor sealed closed-loop refill architectures in this tier.
- Standard Greasing:Unmetered manual or powered delivery for routine maintenance without contamination-critical specifications.
- Automatic Greasing:Centralized pump-to-point systems for continuous lubrication in conveyor and kiln applications.
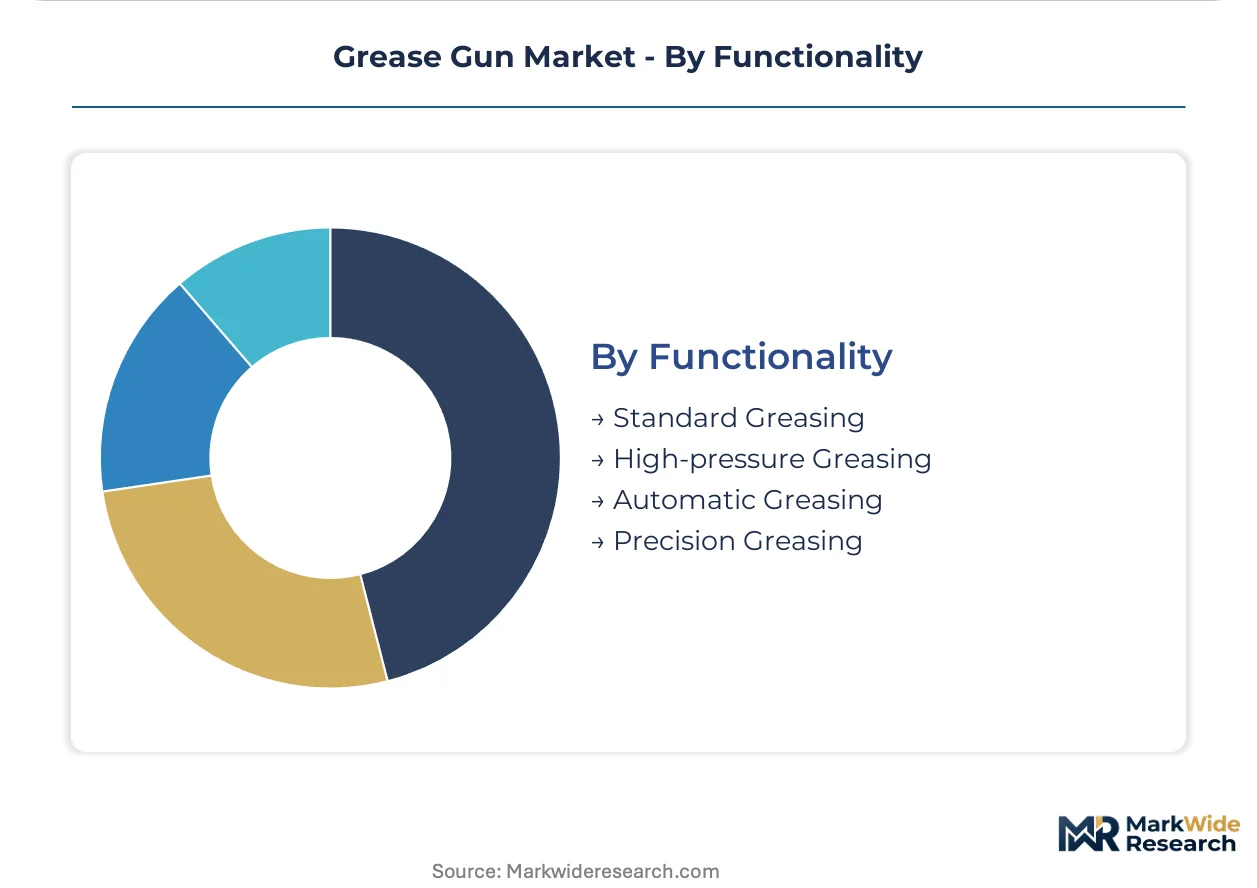
Standard greasing holds the dominant position, yet precision greasing is gaining share fastest through predictive maintenance convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. United States fleet operators absorb premium pricing for battery-powered systems, while Brazilian agricultural buyers remain tethered to manual tools due to capital constraints and seasonal cash flow patterns.
United States
Fleet maintenance outsourcing and factory automation drive replacement cycles for cordless grease gun platforms. OSHA workplace safety standards for battery-powered tools accelerate pneumatic-to-battery conversions in heavy-duty workshops. Chicago and Detroit industrial corridors concentrate procurement authority through corporate headquarters of logistics and rail operators.
Germany
Automotive assembly plants specify ISO 4406-compliant precision greasing systems integrated with condition-monitoring workflows. EU Green Deal lubricant handling rules mandate sealed, contamination-resistant tool designs with closed-loop refill architectures. Stuttgart and Munich manufacturing clusters anchor demand for metered delivery systems in wind turbine and semiconductor bearing applications.
Brazil
Large-scale farming operations in São Paulo and Mato Grosso transition from manual to powered lubrication as harvester uptime becomes critical to seasonal revenue. ANVISA and environmental agencies enforce stricter grease disposal protocols favoring spill-proof designs. Regional agricultural equipment dealers in Campinas serve immediate replacement needs for mechanized soybean and sugarcane operations.
Australia
Mining operators in Western Australia deploy smart grease guns with pressure sensors to track bearing health in real-time across iron ore extraction sites. The country's national workplace safety regulator enforces cordless equipment standards in remote job-site conditions. Perth serves as the procurement hub for fly-in-fly-out maintenance crews serving Pilbara extraction operations.
China
Manufacturing automation investments in Yangtze River Delta assembly plants embed grease guns into predictive maintenance programs. GB standards and MIIT regulations shape product certification requirements for domestic and export markets. Shanghai and Suzhou industrial zones concentrate procurement for integrated lubrication management systems serving automotive and electronics manufacturing.
Grease Gun Market Competitive Landscape
Capability concentration sits with integrated lubrication system specialists; scale advantage sits with cordless power tool platforms leveraging cross-category battery ecosystems. The vendor base separates into three strategic archetypes: battery-platform anchors, precision lubrication integrators, and pneumatic legacy defenders. Dominant competitive moves include exclusive channel partnerships with wholesale distributors and direct enterprise agreements with fleet management companies disintermediating traditional supply chains.
Within the battery-platform tier, Milwaukee Tool and DeWalt exemplify cordless ecosystem dominance through cross-tool battery compatibility. SKF occupies a position among integrated lubrication specialists extending beyond hardware into condition-monitoring services. Lincoln Industrial sits within the legacy pneumatic-to-battery transition space, sustaining market presence through deep channel control. Groz Tools and Macnaught represent regional specialists with concentrated geographic footprints. Ingersoll Rand, Chicago Pneumatic, and Alemite anchor the pneumatic heritage segment facing electrification pressure.
| Leading Market Players |
|---|
| Milwaukee Tool |
| Ingersoll Rand |
| SKF |
| Macnaught |
| Groz Tools |
| Lincoln Industrial |
| Dewalt |
| Chicago Pneumatic |
| Alemite |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese lithium-ion cell manufacturing is compressing battery pack costs and reshaping supplier negotiation leverage across cordless grease gun procurement. This utilization dynamic forces distributors to rebalance inventory toward battery-powered platforms while OEMs absorb margin pressure through volume commitments.
Pricing Analysis
Aftermarket service revenue from battery platform accessories and extended warranty contracts drives lifetime value capture in this market. Three-tier pricing structure across premium, standard, and economy levels separates ISO 4406-certified precision units from workshop-grade cordless systems and manual agricultural variants. Cost compression in battery-powered tiers is intensifying because cobalt and nickel commodity volatility squeezes cell suppliers. Fleet maintenance operators show lowest price sensitivity due to standardization mandates, while Brazilian agricultural buyers remain most price-sensitive due to seasonal cash flow constraints.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for battery-powered grease gun assemblers. Manufacturing concentrates in China, South Korea, and Mexico for lithium-ion cells, precision pumps, and injection-molded housings respectively. Production draws from cobalt cathode chemistries, high-pressure steel alloys, and electronic control modules. Single-source vulnerability in rare earth magnet supply for brushless motors threatens production continuity. Distribution runs through wholesale industrial distributors serving fleet depots alongside direct enterprise agreements with logistics operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Grease gun market expansion sits in early-cycle territory as predictive maintenance programs embed lubrication tools into condition-monitoring workflows. Battery platform standardization across automotive and industrial fleets creates durable replacement demand tailwinds.
For Market Incumbents: Pre-empt cordless platform fragmentation by locking exclusive battery ecosystem partnerships with fleet management companies. Defend against pneumatic-to-battery conversion delays by financing shop air infrastructure removal for strategic accounts. Deepen upstream control over lithium-ion cell supply through long-term offtake agreements with Korean cathode suppliers.
For New Entrants and Emerging Players: Establish a beachhead in Brazilian agricultural mechanization where powered tool penetration remains below industrial benchmarks. White-space exists in precision greasing for wind turbine maintenance where ISO 4406 compliance barriers filter out commodity suppliers. Pursue direct sales to large-scale farming cooperatives bypassing fragmented dealer networks.
For Investors and Strategic Acquirers: Long-term, this sits as a maintenance-intensity play because fleet electrification and automation extend equipment lifecycles while tightening uptime requirements. Acquisition targets should display integrated lubrication management capabilities extending beyond hardware into sensor-enabled service revenue. Monitor cordless platform standardization velocity as the inflection signal—acceleration indicates consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Milwaukee Tool's REDLITHIUM ecosystem anchors cross-tool compatibility reducing fleet inventory complexity. |
| Condition-Monitoring Integration | SKF extends hardware sales into vibration-analysis-linked lubrication services capturing recurring revenue. |
| Backward Integration into Cell Supply | Long-term cathode offtake agreements insulate margins from cobalt-nickel commodity volatility. |
| Direct Enterprise Sales | Logistics operators negotiate supply agreements bypassing Grainger and Fastenal distribution layers. |
| EU Green Deal Compliance Positioning | Sealed closed-loop refill architectures capture premium positioning under stricter lubricant handling rules. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with fleet maintenance directors, plant engineers at automotive assembly facilities, aftermarket service heads, and procurement leads at industrial distributors. Secondary validation drew from OSHA regulatory filings, EPA environmental compliance databases, SEC 10-K disclosures from power tool manufacturers, and customs trade data on lithium-ion cell imports. Bottom-up unit shipment estimates triangulated against top-down market sizing from industrial supply channel audits.
Calibration against historical replacement cycles and technology adoption curves anchored projections across the analysis window. Segmentation dimensions modeled include product type, end-use application, distribution channel, and functionality tier. CAGRs derived from regression analysis of equipment stock growth, maintenance outsourcing penetration, and cordless platform conversion rates. Forecast inputs incorporated fleet standardization timelines and predictive maintenance software adoption curves.
Stress conditions across lithium cost volatility, pneumatic infrastructure retirement rates, and Brazilian agricultural credit availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about battery platform interoperability and regulatory enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Drywall Tool Market
Tools
Thread Milling Machine Market
Tools
Striking Tools Market
Tools
Jade Engraving Machines Market
Tools
Squeegee Market
Tools
Automatic Heat Press Machines Market
Tools
Industrial Plate Bending Machines Market
Tools
Wood Floor Grinding Machine Market
Tools
Global Standard Parts for Tool Making Market
Tools
Theodolite Market
Tools
Spray Painting Machine Market
Tools
Industrial Cleaning Equipment Market
Tools
Global Flange Fasteners Market
Tools
3D Milling Machines Market
Tools
Machining Centers Market
Tools
Dumpy Level Market