
 3D Milling Machines Market | 2026-2036
3D Milling Machines Market Size, Share, and Industry Trends Forecast 2026-2036
3D Milling Machines Market Outlook
Equipment-as-a-service financing is reshaping competitive entry barriers for precision machining. DMG MORI leverages its captive leasing arm to lock in long-term customer relationships across European toolrooms. Yamazaki Mazak anchors its position through deep backward integration into spindle and control system production. Haas Automation competes on standardized platform economics that compress delivery cycles for North American job shops.
3D milling machines execute subtractive material removal across five or more simultaneous axes to achieve tolerances below 5 micrometers on complex geometries. These systems integrate rotary tables, high-speed spindles, and real-time thermal compensation to produce aerospace turbine housings, orthopedic implants, and injection mold cavities. CNC milling machines dominate installed value due to their programmability and repeatability in high-mix production environments. Hybrid technology combining directed energy deposition with milling operations represents the fastest-expanding segment as defense and space contractors pursue near-net-shape processing. Tool and die making remains a mature, margin-dense vertical where shops amortize capital over decade-long replacement cycles.
FDA device manufacturing regulations and ISO 13485 quality mandates shape medical device milling demand by mandating process validation and traceability. Japan's METI promotes smart factory standards that require open-architecture machine tool connectivity, while REACH chemical restrictions affect cutting fluid formulations across European installations. Stakeholders must monitor how dual-use export control expansions affect five-axis system shipments to precision manufacturing clusters.
Market Dynamics
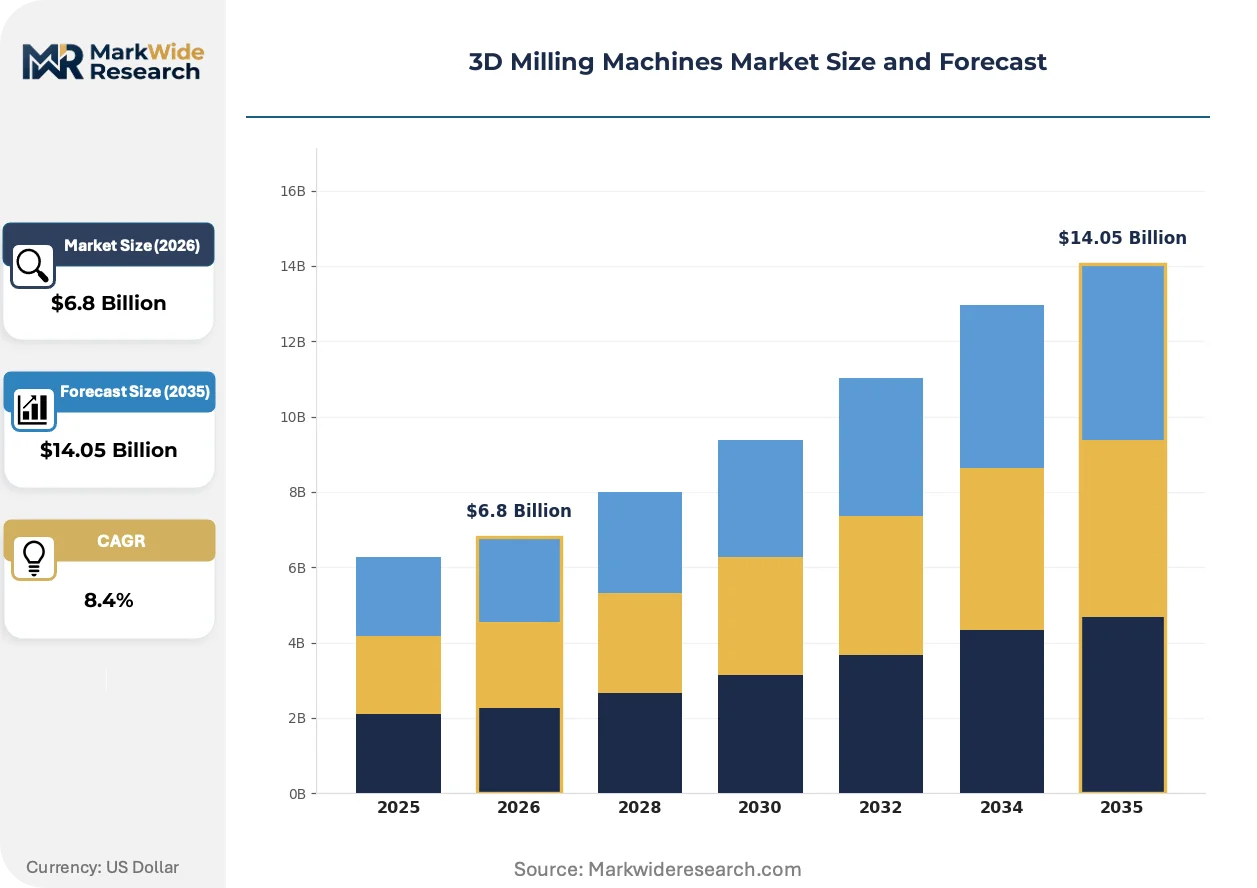
Equipment-as-a-service financing is compressing capital barriers and locking toolrooms into long-term vendor relationships, fundamentally restructuring how precision machining capacity enters production floors.
Growth Catalysts
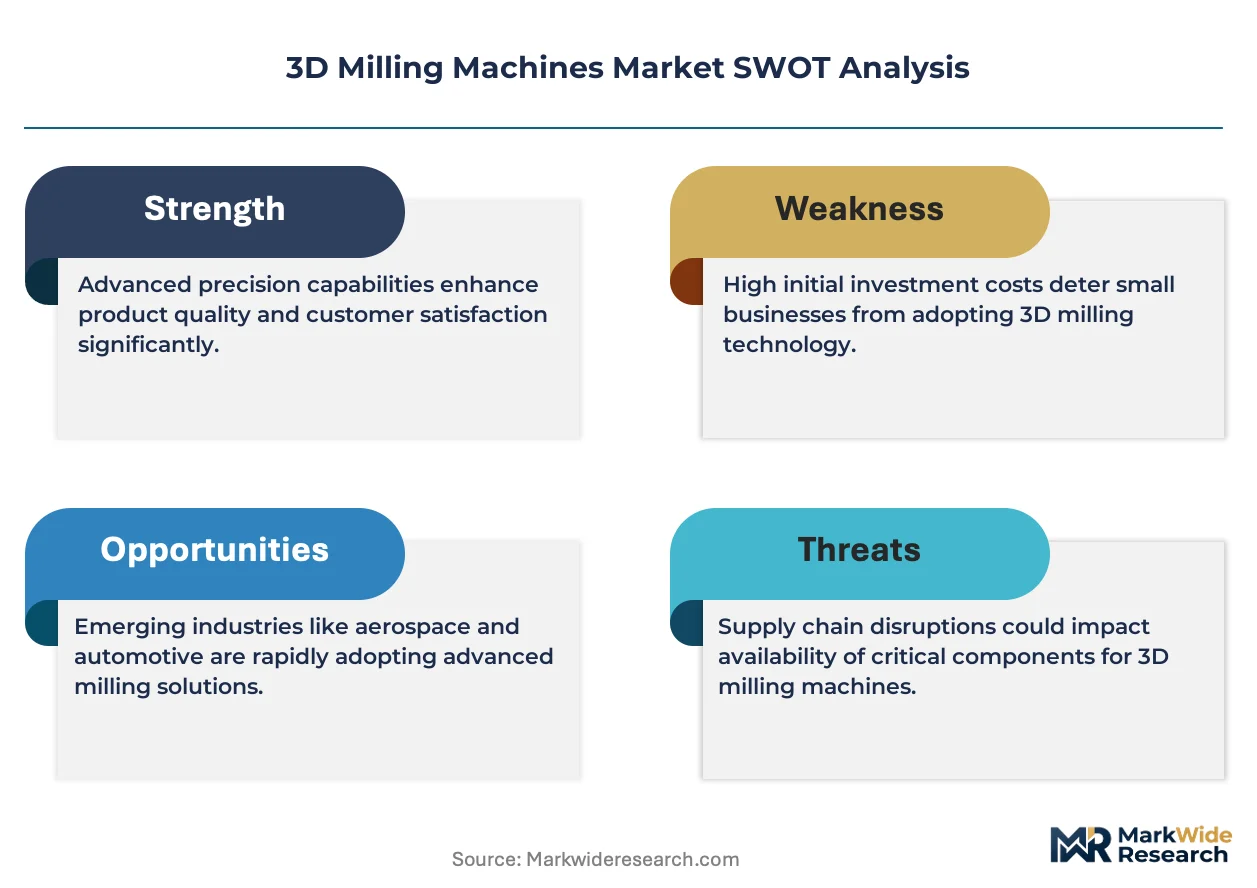
- Aerospace turbine blade mandates:Defense contractors require five-axis simultaneous machining for single-piece integrally bladed rotors, pulling demand from legacy grinding operations.
- FDA process validation requirements:ISO 13485 traceability mandates for orthopedic implants force medical device manufacturers toward CNC-milled production with documented thermal compensation.
- EU Green Deal industrial decarbonization:REACH restrictions on cutting fluid formulations accelerate adoption of minimum-quantity lubrication systems integrated into new machine platforms.
Market Restraints
- High-purity cast iron supply concentration:German and Japanese foundries control 70% of machine bed feedstock, exposing lead times to regional energy price volatility.
- Five-axis calibration complexity:ISO 230-7 volumetric accuracy verification requires specialized laser interferometry equipment scarce outside Stuttgart, Nagoya, and Chicago precision corridors.
- Hybrid system substitution pressure:Directed energy deposition platforms with integrated milling heads threaten standalone five-axis installations in near-net-shape defense applications.
Strategic Opportunities
- Indian PLI scheme manufacturing hubs:Production-linked incentives for precision engineering in Pune and Bangalore create first-mover openings for localized assembly and service networks.
- Space launch vehicle propellant tanks:Cryogenic aluminum-lithium milling for reusable rocket stages represents an emerging application with decade-long procurement cycles.
- Japan METI smart factory mandates:Open-architecture MTConnect and OPC-UA connectivity requirements favor vendors with software-agnostic control platforms.
Industry Challenges
- Multi-axis programming talent scarcity:CAM simulation for collision-free five-axis toolpaths requires specialized operators concentrated in Aachen, Tsukuba, and Detroit technical institutes.
- Capital equipment amortization pressure:Job shops face 7-10 year depreciation schedules against compressed contract durations from automotive tier-one suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Milling Machines Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Milling Machines, Horizontal Milling Machines, CNC Milling Machines, Manual Milling Machines Technology: Subtractive Manufacturing, Additive Manufacturing, Hybrid Technology, Computer-Aided Design End User: Aerospace, Automotive, Medical Devices, Tool and Die Making Application: Prototyping, Production, Customization, Repair |
| Companies Covered | DMG MORI, Haas Automation, Yamazaki Mazak, Okuma Corporation, Makino Milling Machine, Hurco Companies, DN Solutions, FANUC Corporation, GF Machining Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Milling Machines Market Strategic Shifts
Subtractive manufacturing is converging with additive processes while regulatory mandates force open control architectures, reshaping how machine tool vendors capture value beyond hardware sales.
Hybrid manufacturing platforms are hybridizing directed energy deposition with simultaneous five-axis milling to produce near-net-shape aerospace structural components. SpaceX and Blue Origin suppliers are adopting these systems for titanium propellant tank domes. The technology is hybridizing traditional supply chains by collapsing forging, welding, and finishing into single-setup operations that compress lead times from months to days.
EU machinery directives are tightening CE marking requirements for functional safety in autonomous machining cells. The 2023 updates mandate redundant position monitoring for collaborative robot loading systems. German automotive mold shops are responding by retrofitting existing installations with certified safety PLCs rather than purchasing new certified platforms.
Toolroom purchasing is consolidating vendor relationships around captive leasing arms that bundle maintenance, software updates, and consumables into per-hour machining contracts. European job shops are abandoning traditional equipment financing for these full-cost arrangements. The shift is most visible in Stuttgart and Turin manufacturing clusters where DMG MORI and Breton have established dedicated service subsidiaries.
3D Milling Machines Market Segmentation
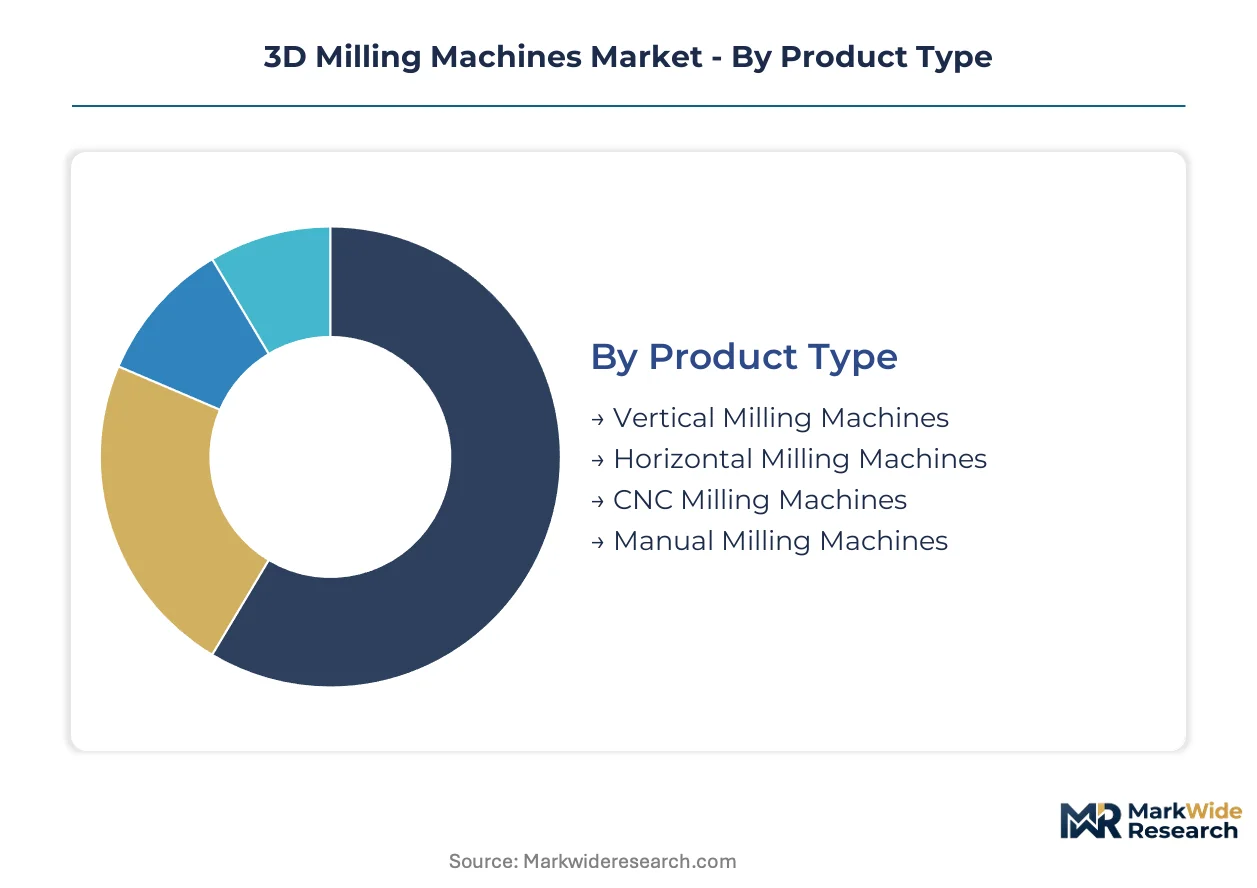
3D milling machine purchasing decisions pivot on axis configuration, control architecture, and thermal stability specifications that vary sharply across aerospace turbine work, medical implant finishing, and mold cavity machining. Segmentation reveals how vendor specialization and end-use certification requirements fragment competitive positioning across hardware categories.
Product Type:
Vertical configurations dominate job shop floors while horizontal platforms anchor high-volume automotive transfer lines.
- Vertical Milling Machines:Spindle orientation perpendicular to the worktable enables gravity-assisted chip evacuation and simplified fixture loading for prototype shops. German toolrooms in Stuttgart and Aachen favor three-axis vertical platforms for quick-change pallet systems in small-batch mold work.
- Horizontal Milling Machines:Tombstone fixturing and pallet pool integration support uninterrupted machining of prismatic automotive components. Japanese automotive tier-one suppliers around Toyota City deploy four-axis horizontal cells for aluminum transmission housing production.
- CNC Milling Machines:Programmable multi-axis motion with real-time thermal compensation dominates aerospace and medical device installations requiring ISO 230-7 volumetric accuracy verification.
- Manual Milling Machines:Hand-cranked positioning persists in maintenance departments and vocational training facilities where capital constraints outweigh throughput requirements.
Established volume favors CNC Milling Machines; emerging adoption favors Horizontal Milling Machines in electric vehicle powertrain machining.
Technology:
Process convergence is blurring traditional boundaries between material removal and deposition methods.
- Subtractive Manufacturing:Rotary cutting tools remove material from solid billets to achieve surface finishes below Ra 0.4 micrometers on hardened tool steels. Aerospace contractors in Nagoya and Seattle rely on five-axis subtractive platforms for titanium structural brackets.
- Hybrid Technology:Directed energy deposition heads integrated into milling spindles enable near-net-shape processing of Inconel propellant tank domes. SpaceX suppliers in Hawthorne and Blue Origin vendors in Kent, Washington, are climbing the fastest with these systems for cryogenic tank production.
- Additive Manufacturing:Powder-bed fusion and directed energy deposition build complex geometries layer-by-layer, competing with milling for low-volume medical implant production.
- Computer-Aided Design:CAD software generates toolpaths and simulates machining sequences, though it functions as an enabler rather than a standalone production technology.
Process validation requirements favor Subtractive Manufacturing; lead time compression favors Hybrid Technology in defense and space applications.
End User:
Regulatory intensity and certification cycles create divergent procurement patterns across customer verticals.
- Aerospace:Single-piece integrally bladed rotors and turbine housings demand five-axis simultaneous machining with spindle speeds exceeding 20,000 RPM. FAA airworthiness directives and defense contractor process specifications mandate full dimensional traceability.
- Medical Devices:FDA 21 CFR Part 820 quality system regulations and ISO 13485 certification requirements force orthopedic implant manufacturers toward validated CNC production with documented thermal compensation.
- Automotive:Powertrain and chassis component machining prioritizes throughput over absolute precision, with electric vehicle battery tray milling emerging as a high-volume application.
- Tool and Die Making:Mold cavity finishing and stamping die production amortize capital equipment over decade-long replacement cycles, favoring premium spindle and control investments.
Certification barriers favor Medical Devices for margin capture; procurement scale favors Automotive for volume concentration.
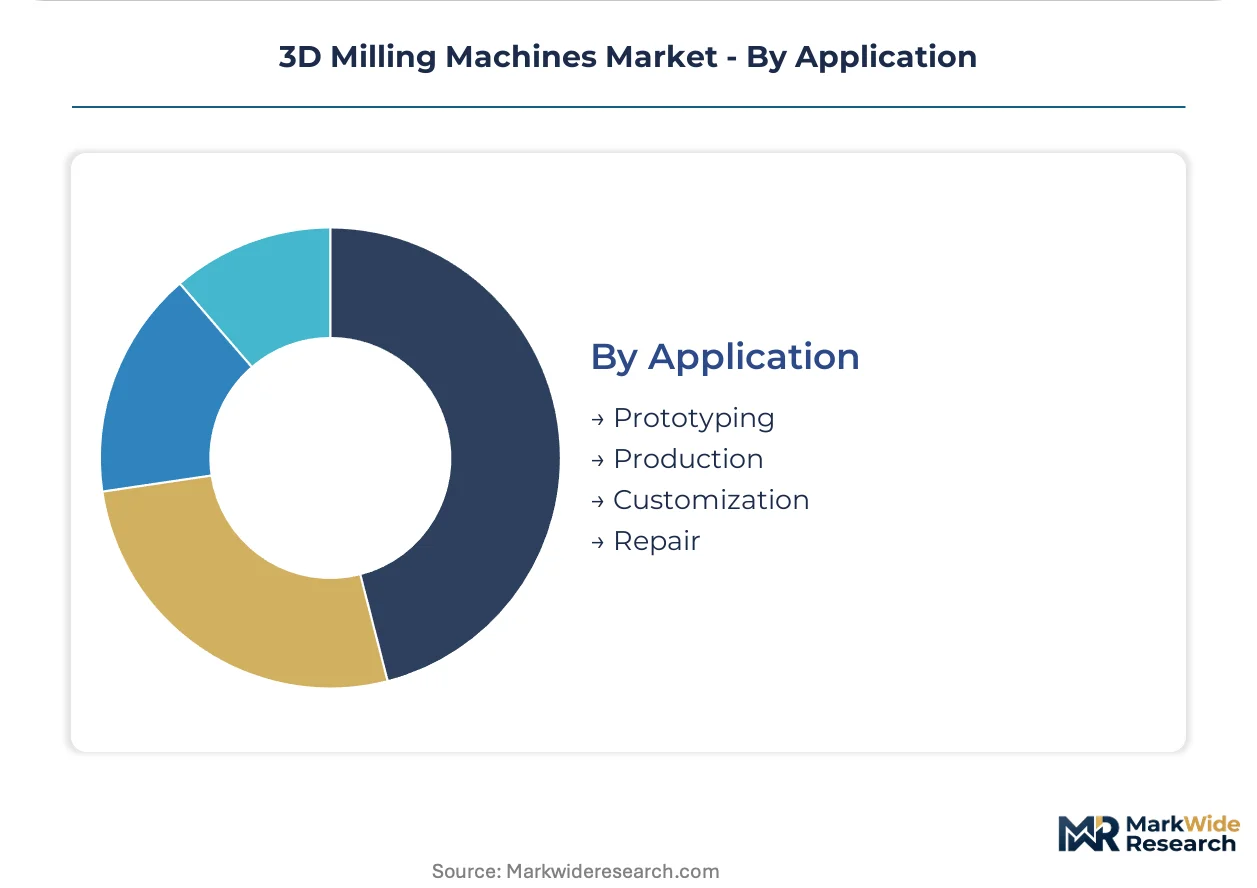
Application:
Workpiece quantity and geometric complexity determine machine configuration and automation level.
- Prototyping:Low-volume validation of design iterations requires rapid setup changeover and multi-material capability. Medical device startups in Boston and Tel Aviv prioritize quick-turn milling for FDA submission samples.
- Production:High-repeatability machining of qualified designs demands pallet automation and in-process probing for lights-out operation.
- Customization:Patient-specific orthopedic implants and aerospace retrofit brackets require adaptive CAM programming and small-lot traceability.
- Repair:Remanufacturing of worn turbine blades and mold surfaces combines cladding deposition with precision finish milling.
Capital efficiency favors Production; margin density favors Customization in medical and defense niche applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for precision engineering is redirecting 3D milling procurement toward domestic assembly networks, while EU machinery directives and Japan's METI smart factory mandates are reshaping equipment standards across major manufacturing corridors.
United States
Defense contractors in Seattle and Hawthorne drive five-axis demand for titanium propellant tank domes and turbine housings. FAA airworthiness directives mandate full dimensional traceability for aerospace components. The Pacific Northwest precision corridor anchors production for SpaceX and Blue Origin suppliers.
Germany
Automotive mold shops in Stuttgart and Aachen prioritize quick-change pallet systems for small-batch production. REACH restrictions on cutting fluid formulations accelerate minimum-quantity lubrication adoption. The Stuttgart precision corridor concentrates ISO 230-7 calibration expertise and captive leasing operations.
Japan
METI smart factory standards require open-architecture MTConnect and OPC-UA connectivity for machine tool installations. Automotive tier-one suppliers around Toyota City deploy four-axis horizontal cells for aluminum transmission housings. The Nagoya precision corridor maintains dense supplier ecosystems for spindle and control system production.
India
Production-linked incentives for precision engineering in Pune and Bangalore create first-mover openings for localized assembly networks. The country's national industrial policy promotes smart factory standards requiring open-architecture connectivity. Pune manufacturing clusters are attracting service network investments from European and Japanese vendors.
China
Dual carbon goals and industrial decarbonization mandates affect energy-intensive machine tool production and foundry operations. The Yangtze River Delta concentrates domestic equipment assembly for aerospace and automotive applications. Shanghai and Suzhou manufacturing hubs are integrating hybrid manufacturing platforms for defense and space contractors.
3D Milling Machines Market Competitive Environment
On the supply side, the industry is consolidating around captive financing arms and backward integration into critical subsystems. Japanese and German incumbents dominate premium five-axis platforms through in-house spindle production. Two strategic archetypes have emerged: integrated solution providers bundling equipment, software, and financing; and standardized platform specialists compressing delivery cycles for price-sensitive job shops. Competitive moves center on equipment-as-a-service contract expansion and geographic localization of assembly networks.
Within the integrated solution tier, DMG MORI and Yamazaki Mazak exemplify archetypes built on captive leasing arms and deep upstream control over spindle and control system production. Haas Automation occupies a position on the standardized platform vector, competing through compressed delivery cycles for North American job shops. These three anchors illustrate how vendor strategies diverge between relationship-locking full-cost arrangements and transactional equipment sales.
| Leading Market Players |
|---|
| DMG MORI |
| Haas Automation |
| Yamazaki Mazak |
| Okuma Corporation |
| Makino Milling Machine |
| Hurco Companies |
| DN Solutions |
| FANUC Corporation |
| GF Machining Solutions |
| Others |
Value Chain & Pricing Dynamics
High-purity cast iron supply concentration in German and Japanese foundries exposes pricing tier spreads to regional energy volatility while compressing procurement options for mid-tier machine builders. This feedstock dependency forces equipment manufacturers to absorb input cost swings or pass them through to buyers, widening the gap between premium five-axis platforms and standardized three-axis alternatives.
Pricing Analysis
Certification level creates the primary spread across ISO 230-7 volumetric accuracy verification tiers, with FDA-grade medical device platforms commanding substantial premiums over CE-marked industrial workhorses. Three-tier pricing structure across premium, standard, and economy levels reflects spindle speed capability, thermal compensation sophistication, and bundled after-sales service intensity. Cost compression in the standard tier is intensifying as Chinese domestic manufacturers expand five-axis offerings. Job shops in North American automotive corridors exhibit highest price sensitivity, while aerospace contractors in Seattle and Hawthorne prioritize performance guarantees over acquisition cost.
Supply Chain Analysis
Contract manufacturing concentration rests with DMG MORI's captive foundry network in Germany, Yamazaki Mazak's integrated spindle facilities in Japan, and emerging assembly partnerships in Pune and Bangalore. Supply chain configuration draws from high-purity cast iron feedstock in Germany and Japan, precision ballscrew production in Taiwan, and motion control electronics from South Korean semiconductor fabs. Single-source vulnerability concentrates in Stuttgart and Nagoya precision corridors where ISO 230-7 calibration expertise remains scarce. Distribution runs through authorized dealer networks that bundle installation, training, and long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of CAM programmers capable of collision-free five-axis toolpath simulation constrains capacity expansion regardless of capital availability. This skills bottleneck favors vendors who can package programming expertise alongside hardware.
For Market Incumbents: Pre-empt hybrid manufacturing substitution by accelerating directed energy deposition integration into existing platform architectures. Defensive consolidation through captive leasing arm expansion in Stuttgart and Turin manufacturing clusters locks in multi-year customer relationships. Backward integration into spindle and control system production preserves margin capture against commoditization pressure from standardized platform competitors. For New Entrants and Emerging Players: Pursue localized assembly and service network establishment in Pune and Bangalore production-linked incentive zones. The most penetrable white space sits in mid-tier five-axis platforms for Indian aerospace subcontracting clusters. A software-agnostic control platform strategy aligns with Japan METI open-architecture mandates while avoiding proprietary ecosystem lock-in. For Investors and Strategic Acquirers: Precision engineering specialists with established ISO 13485 medical device validation capabilities represent the priority acquisition archetype. Long-term viability hinges on defensible calibration expertise and recurring service revenue streams rather than transactional equipment sales. The signal to monitor is equipment-as-a-service contract penetration rates in European toolrooms as an indicator of vendor relationship durability.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Manufacturing Platform Development | Combines directed energy deposition with five-axis milling for SpaceX and Blue Origin suppliers. |
| Equipment-as-a-Service Contract Expansion | Bundles maintenance, software updates, and consumables into per-hour machining arrangements. |
| Localized Assembly Network Establishment | Captures Indian PLI scheme incentives in Pune and Bangalore precision engineering hubs. |
| Open-Architecture Control Platform Investment | Aligns with Japan METI MTConnect and OPC-UA smart factory connectivity mandates. |
| CAM Programming Talent Acquisition | Secures scarce five-axis simulation expertise concentrated in Aachen and Tsukuba institutes. |
Study Parameters
A spread of perspectives from plant engineers at aerospace contractors, procurement leads at medical device OEMs, aftermarket service heads at machine tool distributors, and maintenance directors at automotive tier-one suppliers converged on the working assumptions. Primary interview insights combined with secondary validation from SEC filings of listed equipment manufacturers, customs trade data on machine tool imports, and ISO certification registry databases. Bottom-up demand modeling across end-use verticals triangulated against top-down capacity assessments from foundry and spindle production data.
Demand-supply balance dynamics anchored the analytical framework across the analysis window, with segmentation modeled across axis configuration, control architecture, thermal stability grade, and end-use certification intensity. CAGRs derived from installed base replacement cycles, greenfield capacity announcements, and regulatory mandate implementation timelines. Industry-specific forecast inputs incorporated FAA airworthiness directive compliance schedules and FDA 21 CFR Part 820 process validation requirements.
Sensitivities concentrate around dual-use export control expansions, REACH cutting fluid formulation restrictions, and hybrid system substitution rates in defense applications. Forecasts reflect documented assumptions regarding equipment-as-a-service adoption curves and smart factory connectivity mandate enforcement. Quarterly review of Indian PLI scheme disbursement patterns and space launch vehicle procurement cycles is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Construction Anchors Market
Tools
Manual Cutting Equipment Market
Tools
Digital Cutting Machine Market
Tools
Bi-Metal Band Saw Blade Market
Tools
Turning Tools Market
Tools
Industrial Plate Bending Machines Market
Tools
CNC Metal Cutting Machine Tools Market
Tools
US Chalk Reel and Line Market
Tools
Edge Bending Machine Market
Tools
Sander Market
Tools
Foldable Ladder Market
Tools
Auger Drill Bits Market
Tools
Gear Honing Machines Market
Tools
Woodworking CNC Tools Market
Tools
Industrial Ladder Market
Tools
Broaching Tools Market