
 Screwdriver Market | 2026-2036
Screwdriver Market Size, Share, and Industry Trends Forecast 2026-2036
Screwdriver Market Outlook
Modular bit-set bundling is expanding across retail and professional channels, letting buyers configure single-handle systems with interchangeable heads rather than purchasing discrete tools. Stanley Black & Decker leverages its brand strength and retail shelf presence to anchor the consumer segment. Robert Bosch competes on cordless platform ecosystems that lock users into battery-compatible tool families. Makita specializes in brushless motor integration for extended runtime in professional electric screwdriver lines.
A screwdriver is a hand or power tool designed to insert and remove screws through rotational force, with shaft hardness typically measured on the Rockwell C scale and tip geometry precision-ground to ISO 8764 or comparable tolerances for proper fastener engagement. Electric screwdrivers now dominate volume in automotive and electronics assembly where repetitive torque control reduces defect rates. Precision screwdrivers command disproportionate margin pools in electronics repair and medical device servicing despite lower unit volumes. Manual variants retain structural importance in construction and furniture applications where cost sensitivity and simplicity override powered-tool advantages.
OSHA workplace safety standards in the United States mandate ergonomic tool design and vibration exposure limits that shape electric screwdriver specifications for industrial buyers. The EU's RoHS directive and REACH framework restrict hazardous substances in coatings and plastics, forcing material substitutions across European supply chains. China's GB standards and MIIT manufacturing guidelines set domestic technical baselines that influence export-oriented production. Stakeholders must monitor regulatory divergence between jurisdictions when configuring product portfolios for cross-border distribution.
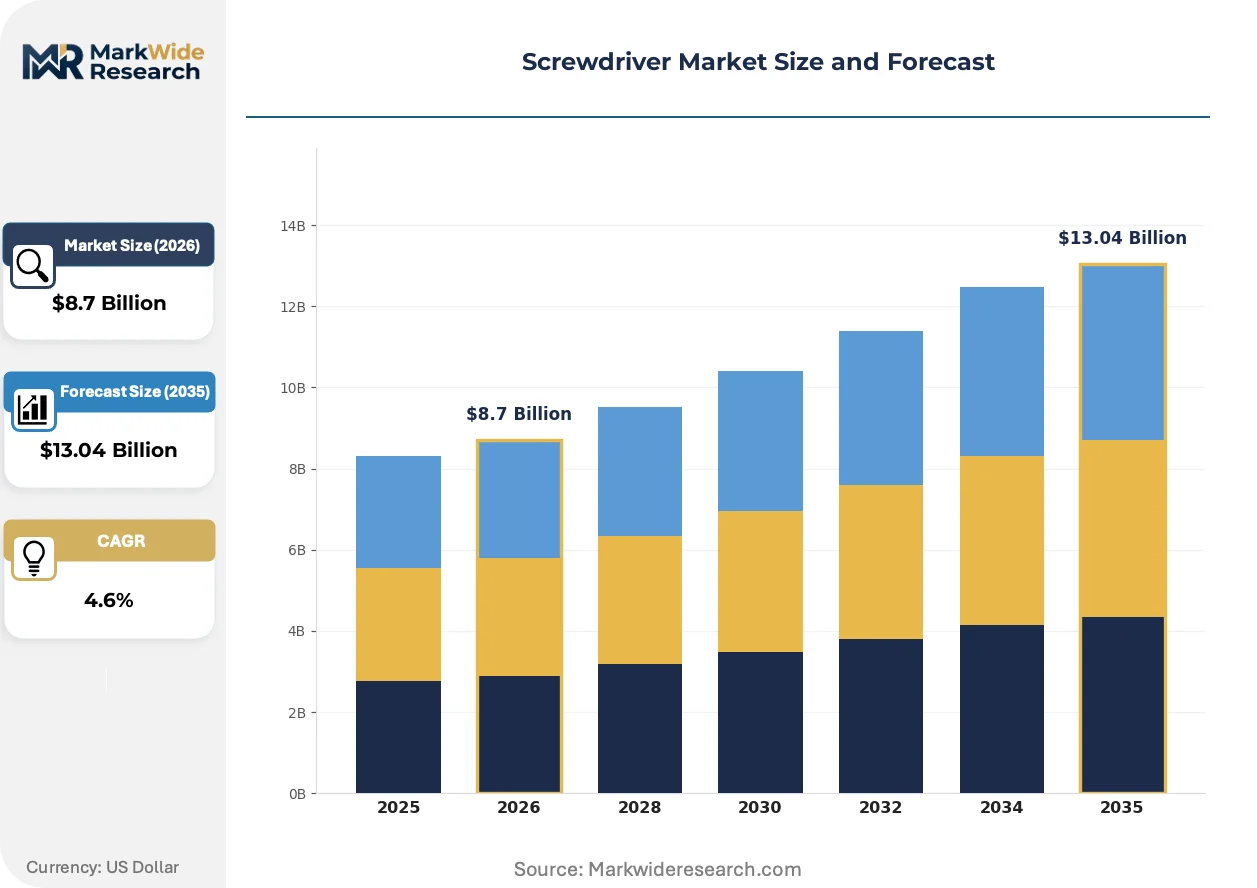
Market Dynamics
Electric screwdriver penetration in automotive and electronics assembly lines is compressing cycle times and forcing manual-tool manufacturers toward precision-specialist niches or exit. This technology shift is redistributing margin pools across the value chain.
Growth Catalysts
- Electronics assembly automation:Surface-mount device production lines in Shenzhen and Seoul are standardizing on torque-calibrated electric screwdrivers to reduce defect rates in smartphone and semiconductor fabrication.
- REACH material compliance:European coating substitution mandates are accelerating R&D into ceramic and titanium-nitride surface treatments that extend bit life and differentiate premium product tiers.
- Medical device servicing expansion:ISO 13485-certified repair facilities are procuring precision screwdriver sets with traceable calibration certificates for surgical instrument maintenance.
Market Restraints
- Raw material cost volatility:Chrome-vanadium and S2 tool steel price swings squeeze mid-tier manufacturers who lack long-term supply agreements with Japanese or German metallurgical suppliers.
- Supply concentration risk:Brushless motor controllers and lithium-ion cell packs concentrate among a handful of East Asian component suppliers, creating single-source vulnerabilities for cordless electric screwdriver assemblers.
- Technical limitation in torque precision:Sub-Nm torque control for microelectronics remains difficult to achieve at consumer price points, capping addressable market expansion in hobbyist repair segments.
Strategic Opportunities
- Underpenetrated aftermarket in India:Mobile phone repair clusters in Delhi and Mumbai lack standardized precision tool distribution, creating whitespace for organized retail and B2B platform entry.
- Regulatory tailwind from EU Green Deal:Circular economy repairability mandates for consumer electronics are mandating accessible disassembly, expanding demand for precision screwdriver kits with standardized bit formats.
- Technology convergence of IoT and torque sensing:Smart screwdrivers with wireless torque logging are integrating into Industry 4.0 quality systems for aerospace fastener documentation.
Industry Challenges
- Certification timeline compression:IEC 60745 safety testing for cordless electric variants requires 8-14 month approval cycles that delay product launches behind faster-moving competitors.
- Skill gap in calibration maintenance:Industrial buyers lack in-house metrology capability to verify screwdriver torque accuracy, creating service dependency on OEM technicians.
- Legacy system integration friction:Smart tool data formats lack standardization with existing MES and ERP platforms, forcing custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Screwdriver Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Tool Type: Manual Screwdrivers, Electric Screwdrivers, Torque Screwdrivers, Precision Screwdrivers Drive Type: Philips, Flathead, Torx, Hex Material: Steel, Stainless Steel, Plastic, Alloy Application: Automotive, Electronics, Construction, Furniture |
| Companies Covered | Stanley Black & Decker, Makita, Robert Bosch, Apex Tool Group, Techtronic Industries, Hilti, Chervon Holdings, FEIN, Snap-on Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Screwdriver Market Strategic Shifts
Tool intelligence and regulatory material bans are converging to reshape product architecture and go-to-market economics. Manufacturers must now engineer for connected functionality and chemical compliance simultaneously.
Brushless DC motor architecture is integrating into professional-grade electric screwdrivers to eliminate carbon brush wear and extend maintenance intervals. Automotive tier-one suppliers and contract electronics manufacturers are adopting these platforms for 24-hour production schedules. This motor transition is integrating predictive maintenance algorithms that flag bearing degradation before catastrophic failure.
REACH Annex XVII restrictions on chromium VI in electroplating are forcing coating reformulation across European-bound production. Toolmakers are shifting to physical vapor deposition and thermal diffusion processes that meet ECHA substance thresholds while maintaining Rockwell C hardness specifications. German and French industrial distributors are now requiring coating compliance documentation as a procurement gate.
Subscription-based tool provisioning is displacing capital purchase models in North American fleet maintenance operations. Airlines and heavy equipment servicers are sourcing screwdriver sets through per-seat monthly arrangements that bundle calibration and bit replacement. This arrangement concentrates most visibly in Texas and California where consolidated MRO providers negotiate enterprise-scale agreements.
Screwdriver Market Segmentation
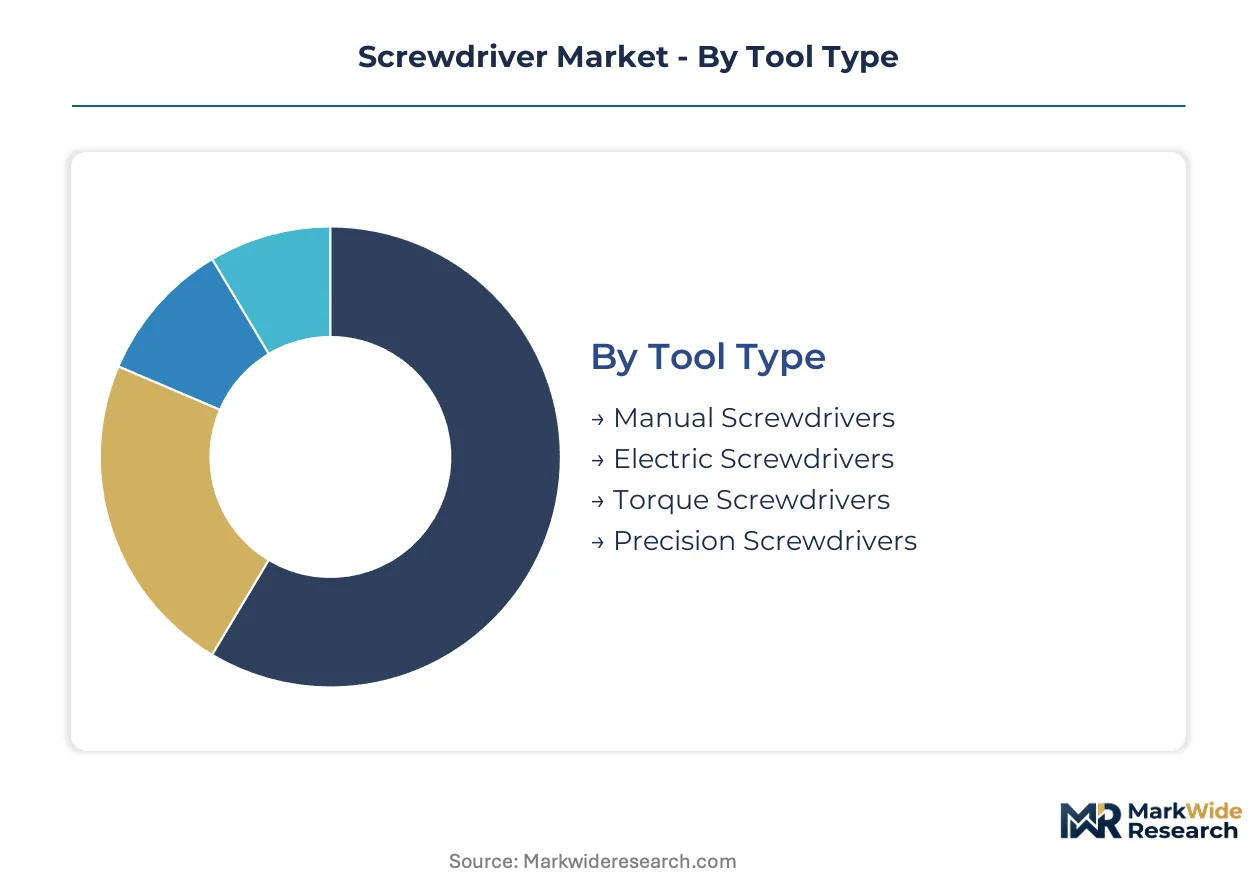
Screwdriver market segmentation reveals divergent capital requirements and margin structures across tool architectures. Understanding these splits allows manufacturers to align R&D spend with segments offering defensible returns rather than commodity exposure.
Tool Type:
Capital intensity varies sharply across this dimension, with electric platforms demanding the heaviest upfront investment in motor controllers, battery integration, and safety certification.
- Manual Screwdrivers:Low-complexity forged shafts with hardened tips dominate volume in construction and furniture assembly. Demand concentrates in China where manufacturing clusters source basic hand tools for export-oriented production and domestic infrastructure builds.
- Electric Screwdrivers:Brushless DC motor systems with lithium-ion power packs and torque-limiting electronics anchor professional procurement in automotive assembly plants. Shenzhen and Seoul electronics manufacturers standardize on these platforms to compress cycle times and reduce repetitive strain injuries.
- Torque Screwdrivers:Calibrated clutch mechanisms enable precise fastener tensioning for aerospace and medical device applications. Calibration traceability requirements limit supplier pools to ISO 17025-certified facilities.
- Precision Screwdrivers:Micro-scale tip geometries for sub-Nm torque control serve smartphone repair and semiconductor handling. Margin concentration here exceeds volume significance due to specialized metallurgy and tight tolerance grinding.
Most installed capacity flows through Manual Screwdrivers. Expansion is steepest in Electric Screwdrivers.
Drive Type:
Application specificity and fastener standardization patterns determine which drive geometries command sustained procurement volumes versus niche positioning.
- Philips:Cross-recess geometry dominates consumer electronics and general industrial assembly where fastener interchangeability reduces inventory complexity. Japanese and South Korean OEMs favor JIS-variant Phillips for tighter tolerances in precision assembly.
- Flathead:Single-slot design retains structural importance in electrical panel work and legacy machinery maintenance where fastener visibility matters. Construction trades in India and Southeast Asia continue standardizing on this lowest-cost drive form.
- Torx:Six-lobe star pattern prevents cam-out in high-torque automotive and appliance assembly. Tamper-resistant pin variants secure public infrastructure and commercial equipment against unauthorized access.
- Hex:Six-sided recess accommodates higher torque transmission in furniture assembly and bicycle maintenance. Allen-key compatibility extends tool utility across multiple fastener sizes.
Philips and Torx together absorb the majority of industrial procurement spend. Hex is gaining share fastest in DIY and compact equipment segments.
Material:
Raw material selection directly determines Rockwell hardness, corrosion resistance, and coating compatibility for target operating environments.
- Steel:Chrome-vanadium and S2 tool steel alloys provide optimal hardness-to-toughness ratios for professional-grade manual and electric screwdriver shafts. Metallurgical supply agreements with Japanese or German mills differentiate tier-one manufacturers from commodity competitors.
- Stainless Steel:Austenitic and martensitic grades eliminate corrosion risk in medical, marine, and food-processing applications where surface integrity is paramount. REACH-compliant European production increasingly specifies stainless over coated carbon steel.
- Plastic:Glass-reinforced nylon and ABS copolymers reduce weight and cost in consumer-grade handles and insulated electric screwdriver housings. Dielectric properties satisfy IEC 60900 standards for live-circuit work.
- Alloy:Titanium-aluminum-vanadium and beryllium-copper alloys serve specialized aerospace and explosive-atmosphere applications where non-magnetic or spark-resistant properties are mandatory.
Steel substrates carry the heaviest installed base. Stainless Steel is climbing the fastest as regulatory corrosion bans expand across European medical and marine procurement.
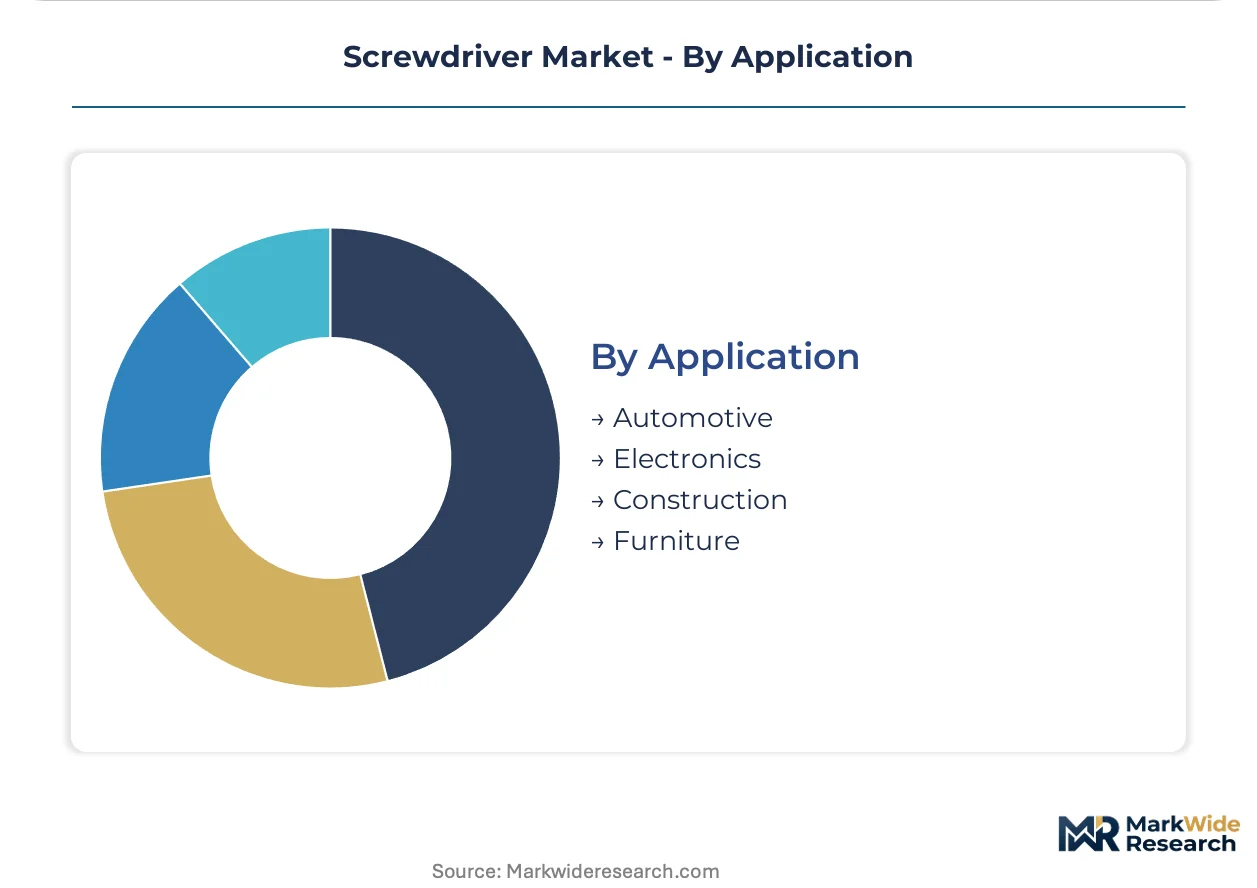
Application:
End-use sector requirements for torque precision, duty cycle, and regulatory compliance fragment demand patterns and viable supplier qualifications.
- Automotive:Assembly line electric screwdrivers with 0.5-50 Nm calibrated torque ranges and wireless data logging integrate into Industry 4.0 quality systems. OEM tier-one suppliers in Germany, Japan, and the United States specify predictive maintenance compatibility.
- Electronics:Surface-mount device production and smartphone repair demand sub-Nm precision with ESD-safe handles. Calibration certificates traceable to national metrology institutes gate entry into ISO 13485 medical device servicing.
- Construction:Manual and cordless impact-rated drivers prioritize durability and cost over precision in residential and commercial building trades. OSHA ergonomic mandates shape handle design for repetitive use.
- Furniture:Medium-torque assembly operations favor interchangeable bit systems and cost-optimized electric platforms. Flat-pack retail distribution in Scandinavia and North America drives seasonal demand spikes.
Automotive and Electronics together concentrate the highest-value procurement. Electronics is expanding most quickly as repairability mandates and semiconductor fabrication capacity multiply addressable demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Solingen valley forged the modern hand-tool industry in the 19th century, establishing metallurgical standards that persist in today's precision screwdriver specifications. Manufacturing clusters in East Asia and North America now rival this heritage with scaled electronics assembly and automotive integration.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg specify torque-calibrated electric screwdrivers with predictive maintenance compatibility. REACH Annex XVII drives coating reformulation toward physical vapor deposition processes. The Solingen-Remscheid tool cluster maintains ISO 17025-certified calibration facilities serving aerospace fastener documentation.
China
Shenzhen electronics manufacturers standardize on brushless DC motor platforms for 24-hour smartphone assembly schedules. MIIT manufacturing guidelines and GB standards set technical baselines for domestic procurement. The Pearl River Delta concentrates precision screwdriver bit production for export-oriented semiconductor fabrication equipment.
United States
Airlines and heavy equipment servicers in Texas and California adopt subscription-based tool provisioning with bundled calibration. OSHA ergonomic mandates shape electric screwdriver handle specifications for industrial buyers. The Midwest automotive corridor integrates wireless torque logging into Industry 4.0 quality systems.
Japan
JIS-variant Phillips drive geometries command premium positioning in precision assembly operations. METI industrial standards influence brushless motor controller specifications for professional-grade platforms. The Nagoya automotive cluster sources calibrated clutch mechanisms for aerospace fastener tensioning.
India
Mobile phone repair clusters in Delhi and Mumbai lack standardized precision tool distribution, creating whitespace for organized retail entry. BIS certification requirements for hand tools tighten quality gates for imported electric variants. Gujarat manufacturing zones expand procurement of interchangeable bit systems for furniture assembly exports.
Screwdriver Market Competitive Environment
Premium-margin players sit above commodity-margin players across motor architecture and calibration traceability tiers. The vendor base stratifies between battery-platform ecosystem builders, precision-specialist machine shops, and mass-market forged-tool forgers. Three archetypes dominate: cordless platform integrators locking users into compatible battery families; precision-calibration houses serving ISO 13485 medical device servicing; and modular bit-system bundlers capturing retail shelf space. Consolidation concentrates in battery-cell supply agreements and calibration laboratory acquisitions.
Within the premium-tier vector, Stanley Black & Decker and Robert Bosch exemplify platform-ecosystem strategies, while Makita occupies a position representing brushless motor integration specialists. These three anchors span distinct geographic origins and corporate structures, collectively illustrating how brand strength, retail presence, and technical specialization carve defensible positions against commodity pressure.
| Leading Market Players |
|---|
| Stanley Black & Decker |
| Makita |
| Robert Bosch |
| Apex Tool Group |
| Techtronic Industries |
| Hilti |
| Chervon Holdings |
| FEIN |
| Snap-on Incorporated |
| Others |
Value Chain & Pricing Dynamics
Captive production of brushless motor controllers and lithium-ion cell packs in East Asian manufacturing clusters anchors both supply security and pricing power for cordless electric screwdriver assemblers. This integration pattern concentrates cost control among platform-ecosystem builders while forcing mid-tier competitors toward commodity manual-tool segments or precision-specialist niches.
Pricing Analysis
Subscription-based provisioning with bundled calibration and bit replacement anchors professional procurement in North American fleet maintenance operations. Price differentiation rests on torque precision certification tiers and predictive maintenance compatibility rather than unit hardware costs. Pricing pressure stems from raw material volatility in chrome-vanadium and S2 tool steel alloys. Construction trades exhibit highest price sensitivity, while aerospace and medical device servicers prioritize calibration traceability over unit economics.
Supply Chain Analysis
Single-source vulnerability sits with brushless motor controllers and lithium-ion cell packs concentrated among East Asian component suppliers. Production gravity centers on China, Japan, and South Korea for precision bit grinding and motor assembly. Raw material flows draw from German and Japanese metallurgical mills for tool steel substrates. Tariff exposure on coated carbon steel imports threatens European-bound production lines. Distribution runs through industrial distributors in Germany, specialized electronics channels in Shenzhen, and consolidated MRO platforms in Texas and California.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in precision-calibration tiers and aftermarket servicing arrangements, driven by REACH-compliant coating substitution costs that premium manufacturers pass through while commodity competitors absorb.
For Market Incumbents: Anchor platform-ecosystem lock-in through battery-compatible tool families that raise switching costs for automotive and electronics assembly buyers. Defend against modular bit-system bundlers by deepening calibration service capabilities and ISO 17025-certified metrology infrastructure. Prioritize ceramic and titanium-nitride coating R&D to capture REACH-driven substitution premiums in European procurement. For New Entrants and Emerging Players: Direct-to-repair-technician platforms offer whitespace entry into India's unstandardized mobile phone repair clusters in Delhi and Mumbai. Target precision screwdriver kits with traceable calibration certificates for ISO 13485 medical device servicing facilities. Leverage EU Green Deal repairability mandates to position standardized bit-format kits for consumer electronics disassembly. For Investors and Strategic Acquirers: Consolidation pressure builds where calibration laboratory capacity scarcity meets expanding aerospace and medical device documentation requirements. Long-term viability favors precision-specialist machine shops with ISO 17025 certification and brushless motor integration capabilities over mass-market forged-tool forgers. Watch for IEC 60745 safety testing timeline compression as an inflection signal for product launch velocity advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Laboratory Acquisition | ISO 17025 certification gates entry into aerospace fastener documentation and medical device servicing contracts. |
| Brushless Motor Platform Standardization | Eliminates carbon brush wear and extends maintenance intervals for 24-hour Shenzhen electronics assembly schedules. |
| REACH-Compliant Coating Transition | Physical vapor deposition processes satisfy ECHA substance thresholds while maintaining Rockwell C hardness specifications. |
| Subscription-Based Tool Provisioning | Per-seat monthly arrangements with bundled calibration concentrate in Texas and California consolidated MRO providers. |
| IoT Torque Sensing Integration | Wireless torque logging integrates into Industry 4.0 quality systems for aerospace fastener documentation compliance. |
Study Parameters
Direct dialogue with procurement managers at automotive tier-one suppliers, calibration technicians at ISO 17025-certified laboratories, electronics assembly line supervisors, and industrial distributors in Germany and China grounded qualitative findings. Secondary validation drew from customs and trade data, SEC filings of listed tool manufacturers, ECHA REACH substance restriction updates, and OSHA ergonomic standard revisions. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity disclosures and end-use procurement patterns.
Bottom-up modeling segmented demand across tool type, drive geometry, material substrate, and application vertical, with electric screwdriver penetration curves calibrated against automotive and electronics assembly automation indices. CAGRs derived from weighted average of historical trajectory and technology substitution elasticity across the projection horizon. Forecast inputs included brushless motor cost decline curves and REACH Annex XVII coating reformulation timelines.
Raw material cost volatility, regulatory divergence between REACH and OSHA jurisdictions, and single-source component concentration are the dominant revision risks to modeled outcomes. Forecasts reflect documented assumptions about technology adoption rates and compliance timeline adherence. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Digital Laser Levels Market
Tools
Metal Cutting Tools Market
Tools
Reamer Market
Tools
Machine Vise Market
Tools
Rivet Busters Market
Tools
US Hitter Based Hand Tools Market
Tools
Europe Paint Spray Guns Market
Tools
Hacksaw Blades Market
Tools
Global Construction Camera Market
Tools
Cordless Impact Wrench Market
Tools
Floor Pads Market
Tools
China Power Tools Market
Tools
Parting-Off Blades Market
Tools
Global Staple Gun Market
Tools
Floor Polishing Machine Market
Tools
Grinding Discs Market