
 Grader Machinery Market | 2026-2036
Grader Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Grader Machinery Market Analytics
Dealer networks and direct-to-contractor digital platforms is reconfiguring how grader machinery reaches end users across mature and emerging economies. Caterpillar leverages its captive financing arm to lock in long-term contractor relationships. Komatsu sustains technical leadership through its integrated machine control and telematics stack. John Deere anchors its position in North American agricultural and rural road maintenance segments.
Grader machinery encompasses self-propelled earthmoving equipment equipped with an adjustable moldboard blade positioned between front and rear axles, engineered to create flat surfaces with precise slope control through hydraulic cylinder articulation. These machines operate at blade widths typically spanning 3.7 to 4.9 meters and deliver grading accuracy within 3 millimeters when paired with GPS-guided control systems, serving primarily in road base preparation, final grade finishing, and mine haul road maintenance. Motor graders occupy the largest installed base due to their versatility across construction and mining workflows, while GPS-Controlled technology commands premium positioning as infrastructure projects mandate tighter tolerance specifications. Hydraulic Graders retain dominance in developing markets where capital constraints favor mechanical simplicity over automated systems.
The US EPA Tier 4 Final and EU Stage V emission frameworks compel engine after-treatment retrofits and drive replacement demand for older non-compliant units in regulated markets. China's MIIT enforces national IV emission standards for non-road mobile machinery, reshaping product portfolios for domestic manufacturers like Sany and XCMG. India's CEA and state public works departments embed BIS-certified equipment specifications into tender documents, creating compliance barriers for uncertified imports. Stakeholders must weigh emission upgrade cycles against hybrid technology readiness when allocating R&D budgets across regional product lines.
Market Dynamics
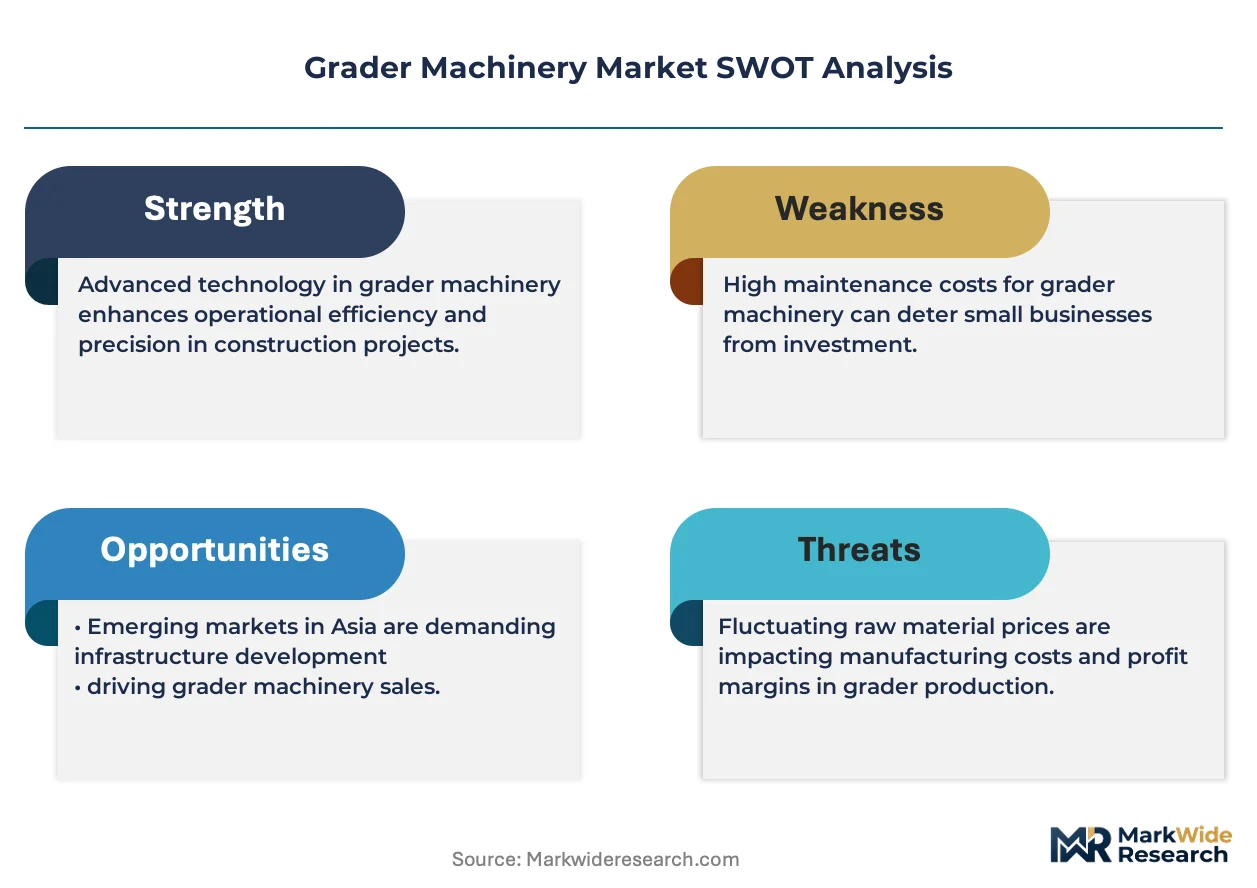
Emission compliance cycles and precision grading mandates are compressing equipment replacement timelines while elevating total cost of ownership calculations for fleet operators across infrastructure and mining verticals.
Growth Catalysts
- India's Bharatmala corridor program:Central and state public works departments are expanding mechanized fleet procurement for national highway expansion, with graders specified for base preparation and shoulder maintenance across 83,000 kilometers of corridor development.
- GPS-guided machine control:Infrastructure agencies in Brazil and Australia now embed 3-millimeter accuracy requirements into tender documents, mandating automated blade control for final grade finishing on federally funded projects.
- EU Stage V retrofit deadlines:German and French rental fleets face compulsory engine after-treatment upgrades or replacement, generating replacement demand for compliant motor graders in Western European markets.
Market Restraints
- High-sulfur diesel price volatility:Off-highway fuel costs in emerging markets consume 35-45% of hourly operating expenses, compressing contractor margins and extending payback periods for new equipment acquisitions.
- Chinese hydraulic component concentration:Cylinder and valve supply for mid-range graders clusters in Jiangsu and Shandong provinces, exposing non-Chinese assemblers to logistics disruptions and input cost spikes.
- Electric powertrain energy density limits:Battery-electric graders cannot sustain full-day operations in high-load mining applications without mid-shift charging, constraining electrification to light-duty municipal maintenance.
Strategic Opportunities
- Indonesia's Trans-Sumatra highway:The 2,700-kilometer corridor lacks established equipment rental infrastructure, creating first-mover advantage for dealers establishing service-backed sales operations in Medan and Palembang.
- Telematics-integrated predictive maintenance:Convergence of IoT sensors and cloud analytics enables outcome-based service contracts, shifting revenue from unit sales to uptime guarantees for municipal fleets.
- US IIJA rural bridge program:Federal funding for county-level infrastructure directs demand toward compact graders suited to constrained access roads and secondary network rehabilitation.
Industry Challenges
- GPS calibration technician scarcity:Machine control integration requires specialized field engineers capable of RTK base station setup and blade sensor alignment, with training pipelines lagging deployment schedules in African and Southeast Asian markets.
- Dual certification complexity:Equipment destined for India must simultaneously satisfy BIS mechanical standards and CEA electrical safety protocols, extending homologation timelines by 8-14 months.
- Legacy fleet interoperability:Contractors operating mixed-age grader pools face data fragmentation as newer telematics-enabled units cannot integrate with 15-20 year old mechanical machines in unified fleet management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Grader Machinery Market |
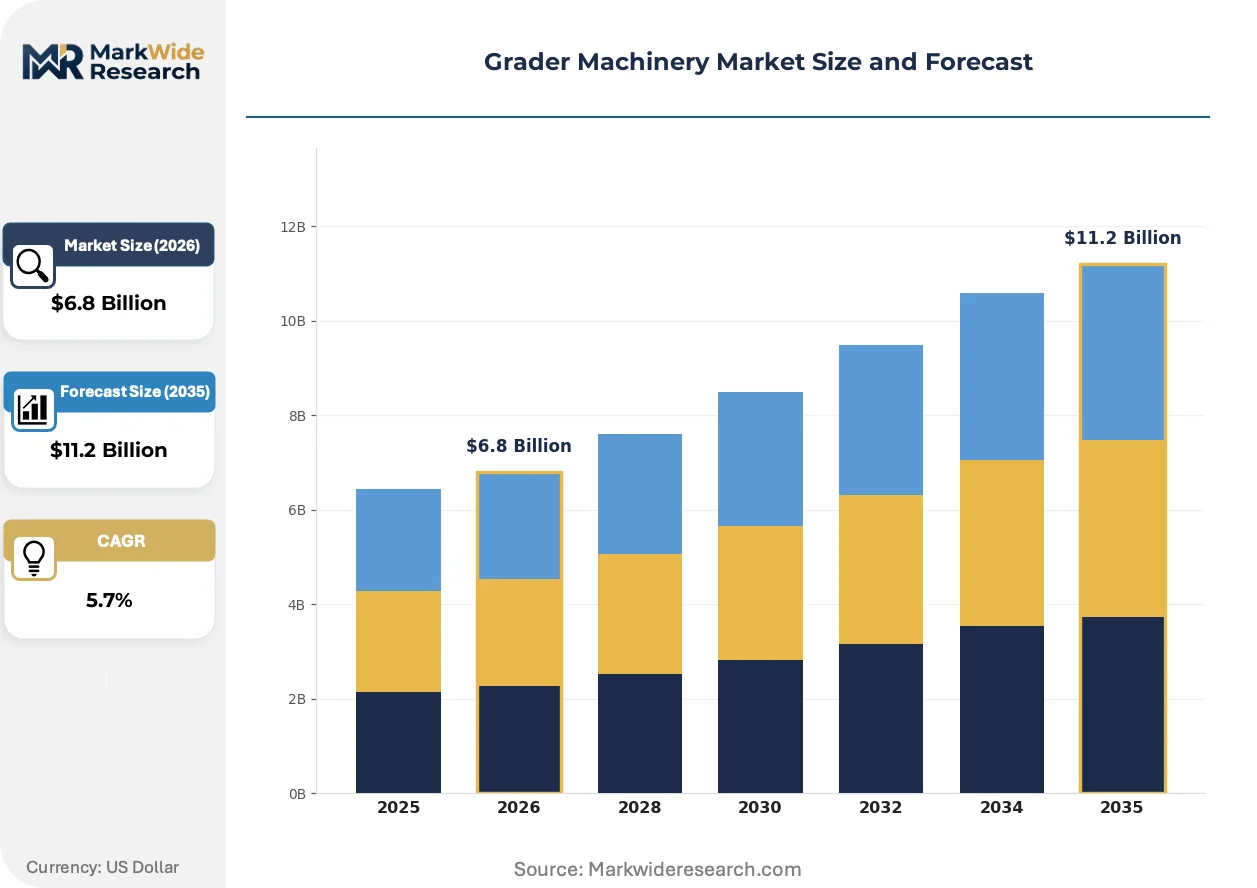
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Graders, Motor Graders, Tracked Graders, Wheeled Graders Application: Construction, Mining, Agriculture, Landscaping End User: Government, Contractors, Farmers, Landscaping Companies Technology: GPS-Controlled, Automated, Manual, Hybrid |
| Companies Covered | Caterpillar, John Deere, Komatsu, Volvo, Case, Sany, XCMG, LiuGong, SDLG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Grader Machinery Market Evolving Landscape
Powertrain diversification and automated blade control are redefining equipment specifications, while procurement digitization is compressing traditional dealer-sales cycles into direct contractor-manufacturer relationships.
Hybrid diesel-electric architectures are hybridizing conventional grader powertrains by capturing braking energy and optimizing engine load cycles. Australian mining contractors are piloting these systems in 24-hour haul road maintenance operations. The technology is hybridizing total cost calculations by reducing fuel consumption 18-25% while extending engine rebuild intervals.
China's MIIT national IV emission standards for non-road mobile machinery are forcing domestic manufacturers to adopt selective catalytic reduction and diesel particulate filters across 150-400 horsepower product lines. Engine suppliers must revalidate power curves and cooling packages, compressing development cycles for Sany and XCMG export configurations. The regulation is accelerating product line consolidation as separate Tier 3 and Tier 4 Final platforms become economically unsustainable.
Rental-with-operator contracts are displacing pure equipment leasing in Brazilian infrastructure corridors, with contractors outsourcing grading operations to fleet owners bearing fuel and maintenance risk. This model concentrates demand among large rental houses with in-house technical capabilities. The shift is most visible in São Paulo state highway concessions, where concessionaire procurement teams now specify performance-based road surface quality metrics rather than machine-hour rates.
Grader Machinery Market Segmentation
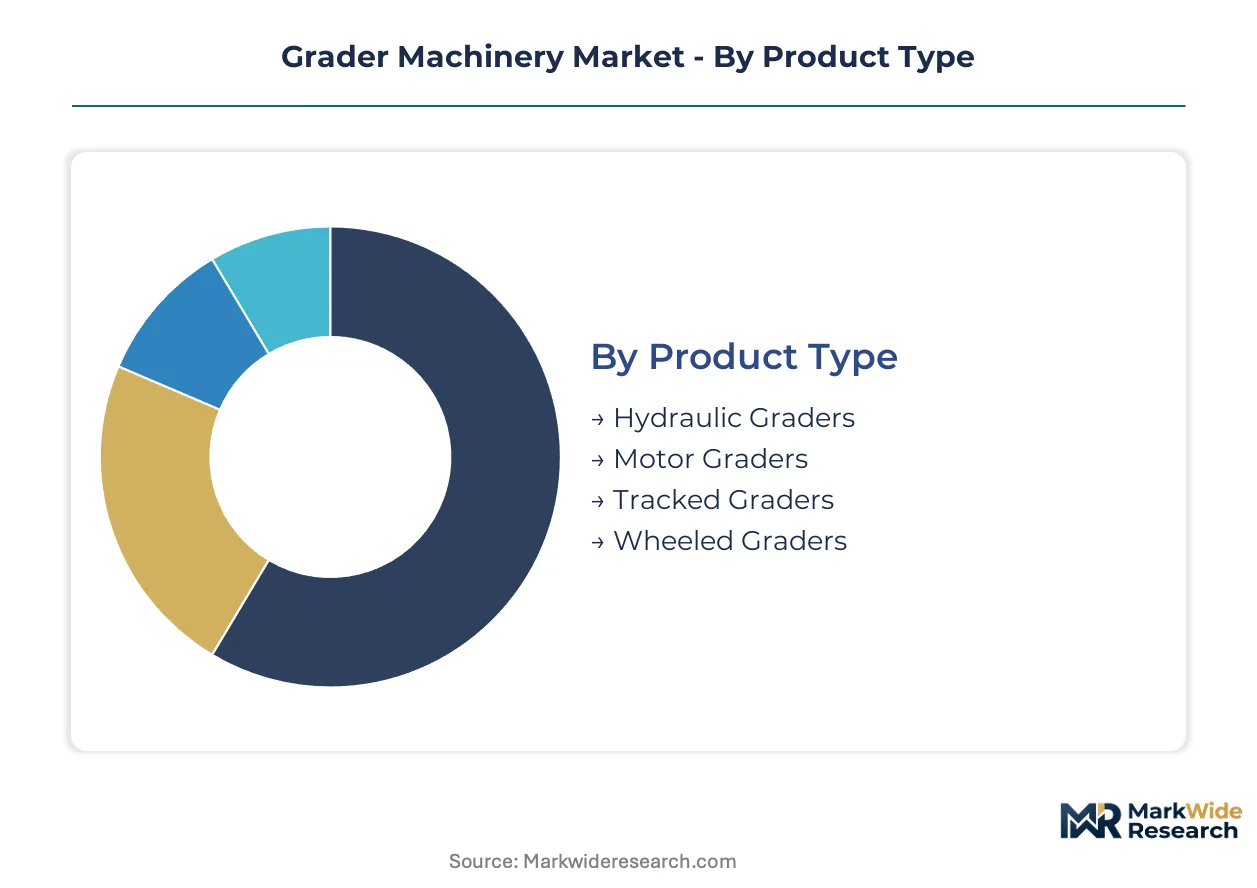
Grader machinery procurement patterns diverge sharply across project scale and precision requirements. Fleet composition decisions hinge on whether operators prioritize capital efficiency or automated accuracy mandates.
Product Type:
Use-case spectrum spans municipal maintenance through precision mining haul roads, with chassis configuration determining terrain access and operating economics.
- Motor Graders:Self-propelled articulated machines with moldboard blades between axles dominate installed bases through versatility across road base preparation and final grading. Brazilian infrastructure corridor projects concentrate demand for 200-300 horsepower units with all-wheel drive.
- Hydraulic Graders:Mechanical simplicity and lower capital outlays sustain dominance in developing markets where GPS integration remains cost-prohibitive. India's state public works departments specify these units for rural road rehabilitation under Bharatmala program tenders.
- Wheeled Graders:Highway-speed mobility suits rapid deployment across dispersed construction sites with established haul networks.
- Tracked Graders:Low ground pressure distributes weight for soft terrain access in mine haul road maintenance and wetland construction.
Established volume favors Motor Graders; emerging adoption favors Tracked Graders in mining verticals.
Application:
Cost tier stratification separates capital-intensive precision work from volume-driven earthmoving operations.
- Construction:Road base preparation and shoulder maintenance consume the largest equipment hours, with GPS-controlled units commanding premium positioning for federally funded projects requiring 3-millimeter tolerance specifications. Australia's tender documents now embed automated blade control mandates.
- Mining:24-hour haul road maintenance operations in Australian iron ore and coal basins drive hybrid powertrain pilots, with fuel consumption reductions of 18-25% justifying technology premiums against diesel price volatility.
- Agriculture:Land leveling and drainage channel construction in North American grain belts favors compact graders suited to field access constraints.
- Landscaping:Precision contouring for golf courses and commercial development requires compact machines with tight turning radii.
Construction absorbs the largest equipment hours; mining generates the steepest expansion trajectory for automated systems.
End User:
Customer type determines procurement modality, with government tenders favoring certified specifications and contractors optimizing total cost of ownership.
- Government:India's central and state public works departments embed BIS-certified equipment specifications into tender documents, creating compliance barriers for uncertified imports while expanding mechanized fleet procurement.
- Contractors:Brazilian highway concessionaire procurement teams now specify performance-based road surface quality metrics rather than machine-hour rates, concentrating demand among rental houses with technical capabilities.
- Farmers:North American agricultural operators anchor John Deere's position in rural road maintenance segments through dealer network relationships.
- Landscaping Companies:Municipal maintenance contracts drive compact grader demand for constrained access roads under US IIJA rural bridge program funding.
Government procurement dominates unit volume; contractor rental-with-operator models are gaining share fastest in emerging markets.
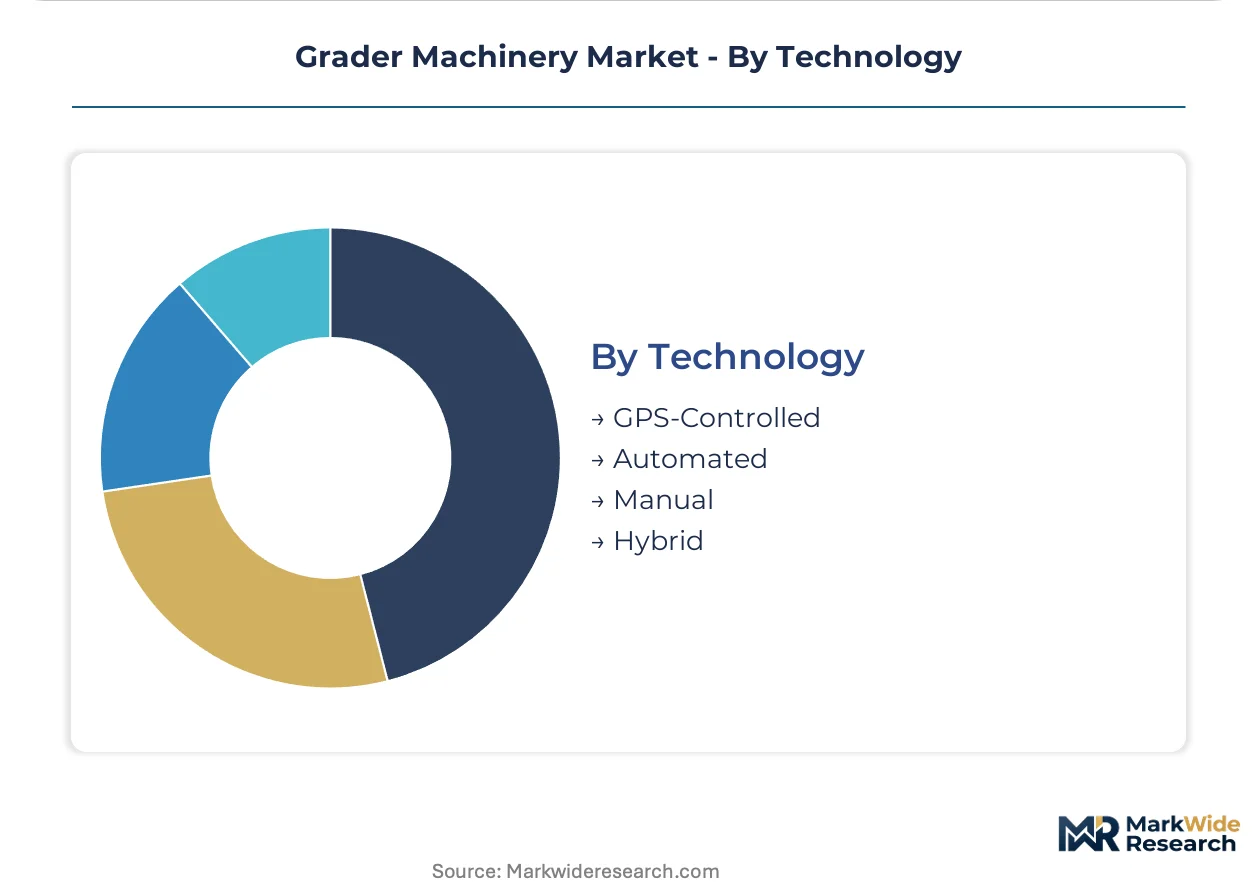
Technology:
Maturity gradients separate proven mechanical systems from emerging powertrain and automation architectures.
- Manual:Mechanical blade control retains installed base dominance where capital constraints override precision requirements, particularly in African and Southeast Asian markets facing GPS calibration technician scarcity.
- GPS-Controlled:RTK base station integration enables 3-millimeter grading accuracy for final grade finishing, with infrastructure agencies in Brazil and Australia embedding requirements into tender documents.
- Automated:Machine control convergence with telematics enables outcome-based service contracts, shifting revenue from unit sales to uptime guarantees for municipal fleets.
- Hybrid:Diesel-electric architectures capturing braking energy face energy density constraints in high-load mining applications, constraining deployment to light-duty municipal maintenance pending battery advances.
Manual systems retain the largest installed base; GPS-Controlled technology commands premium positioning in regulated procurement markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium pricing power concentrates in Australian mining corridors where 24-hour haul road maintenance contracts justify hybrid technology premiums, while Indian state public works departments compress margins through bulk tender mechanisms for Bharatmala corridor equipment.
United States
County-level infrastructure agencies direct IIJA rural bridge program funding toward compact graders suited to constrained access roads. EPA Tier 4 Final emission frameworks compel engine after-treatment retrofits for rental fleets in Texas and California. Equipment demand clusters around Dallas-Fort Worth highway contractors and Pacific Northwest logging road maintenance operators.
China
Domestic manufacturers face compressed development cycles as MIIT national IV emission standards force selective catalytic reduction adoption across 150-400 horsepower product lines. Jiangsu and Shandong provinces concentrate hydraulic cylinder and valve supply for mid-range graders, exposing assemblers to logistics disruptions. XCMG and Sany anchor production in Xuzhou and Changzhou industrial clusters.
India
Central and state public works departments embed BIS-certified equipment specifications into Bharatmala corridor tenders spanning 83,000 kilometers of highway development. CEA electrical safety protocols create dual certification complexity that extends homologation timelines for imported units. Fleet procurement concentrates in Maharashtra and Gujarat contractor pools.
Brazil
Highway concessionaire procurement teams in São Paulo state specify performance-based road surface quality metrics rather than machine-hour rates, concentrating demand among rental houses with technical capabilities. Rental-with-operator contracts displace pure equipment leasing across infrastructure corridors. Equipment deployment focuses on Minas Gerais mining haul roads and Paraná agricultural expansion zones.
Australia
Iron ore and coal basin operators pilot hybrid diesel-electric architectures in 24-hour haul road maintenance operations, with fuel consumption reductions justifying technology premiums against diesel price volatility. Infrastructure agencies embed 3-millimeter GPS-guided accuracy requirements into tender documents for final grade finishing. Demand clusters in Western Australia Pilbara region and Queensland Bowen Basin.
Grader Machinery Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying hydraulic cylinders and valve assemblies to regional assemblers. The vendor base stratifies across three tiers: multinational full-line manufacturers with captive financing arms, domestic champions serving protected procurement markets, and regional fabricators competing on capital efficiency. Strategic archetypes include emission-compliant platform providers, telematics-integrated solution vendors, and cost-optimized mechanical specialists. Competitive moves concentrate on strategic partnerships for machine control integration and geographic expansion through dealer network establishment.
Within the multinational tier, Caterpillar and Komatsu occupy positions defined by integrated technology stacks and captive financing capabilities. John Deere anchors the North American agricultural and rural road maintenance segment through established dealer relationships. Among domestic champions, Sany and XCMG exemplify the Chinese manufacturer archetype navigating MIIT emission standard transitions while consolidating export configurations.
| Leading Market Players |
|---|
| Caterpillar |
| John Deere |
| Komatsu |
| Volvo |
| Case |
| Sany |
| XCMG |
| LiuGong |
| SDLG |
| Others |
Value Network & Pricing Analysis
Chinese hydraulic component concentration in Jiangsu and Shandong provinces determines both the three-tier pricing structure across premium, standard, and economy levels and the geographic clustering of final assembly operations. OEMs exposed to this single-source dependency face compressed margins when logistics disruptions spike input costs, while buyers in regulated markets absorb technology premiums for GPS-integrated platforms.
Pricing Analysis
Configured-to-order spreads separate GPS-controlled motor graders from standard hydraulic units, with customization premiums reflecting RTK base station integration and telematics bundling. Three-tier pricing structure across premium, standard, and economy levels stratifies by emission certification tier and after-sales service depth. Cost compression in mid-range segments is intensifying because Brazilian rental houses consolidate procurement volume. Government tenders in India exhibit highest price sensitivity due to BIS-certified equipment mandates, while Australian mining contractors show lowest sensitivity given fuel consumption reduction justifications.
Supply Chain Analysis
Export-control regimes limiting precision GPS and machine control technology flows constrain component sourcing for non-domestic assemblers serving Chinese and Indian markets. Manufacturing gravity centers on China, Japan, and Germany for hydraulic cylinders, electronic control modules, and precision blade assemblies. Raw material dependencies span high-strength steel plate, engineered hydraulic seals, and rare-earth magnets for electric powertrain prototypes. Single-source vulnerability concentrates in Jiangsu province cylinder suppliers. Distribution runs through captive dealer networks in mature markets and direct-to-contractor digital platforms in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MIIT national IV emission standards for non-road mobile machinery constitute a regulatory inflection accelerating product line consolidation and reshaping competitive positioning. This disruption compresses development cycles while elevating technology premiums for compliant platforms.
For Market Incumbents: Harden emission-compliant platform portfolios through selective catalytic reduction integration across 150-400 horsepower product lines. Deepen upstream control over hydraulic component supply by qualifying secondary cylinder sources outside Jiangsu province. Lock in long-term contractor relationships via captive financing arms and telematics-integrated uptime guarantees.
For New Entrants and Emerging Players: Indonesia's Trans-Sumatra highway corridor represents the most penetrable entry point given absent rental infrastructure and first-mover dealer establishment opportunities. Municipal maintenance fleets in US counties under IIJA rural bridge funding offer compact grader white space with constrained access road specifications. Pursue telematics-integrated predictive maintenance contracts as the go-to-market angle, shifting revenue from unit sales to outcome-based service agreements.
For Investors and Strategic Acquirers: EU Stage V retrofit deadlines reshape the acquisition landscape by generating replacement demand for compliant motor graders in Western European rental fleets. Long-term viability favors platform integrators with machine control integration capabilities and geographic diversification beyond Chinese hydraulic component dependence. Watch GPS calibration technician training pipeline expansion as the inflection indicator for automated system penetration in African and Southeast Asian markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Machine Control Integration Partnership | Komatsu's telematics stack convergence with third-party RTK systems accelerates precision grading adoption in Australian iron ore basins. |
| Emission Platform Consolidation | Sany and XCMG revalidate power curves under MIIT national IV standards, compressing separate Tier 3 and Tier 4 Final product lines. |
| Dealer Network Geographic Expansion | Caterpillar establishes service-backed sales operations in Medan and Palembang ahead of Trans-Sumatra highway equipment deployment. |
| Hybrid Powertrain Pilot Scale-Up | Australian mining contractors extend 24-hour haul road maintenance trials to validate 18-25% fuel consumption reduction claims. |
| Outcome-Based Service Contract Launch | Municipal fleets shift procurement from machine-hour rates to uptime guarantees via IoT sensor and cloud analytics convergence. |
Research Methodology
A spread of perspectives from OEM product managers, rental fleet operators, public works procurement officers, and aftermarket service heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through customs/trade data, SEC 10-K filings, and equipment registration databases. Bottom-up triangulation across contractor fleet composition surveys and top-down reconciliation against national infrastructure budget allocations anchored volume estimates.
Demand-supply balance framing structured the analytical approach across the projection horizon. Segmentation dimensions modeled include product type, application vertical, end-user category, and technology tier alongside regional regulatory cluster differentiation. CAGRs derived from equipment replacement cycle analysis and infrastructure spending trajectory correlation. Industry-specific forecast inputs encompassed Bharatmala corridor mechanization timelines and Brazilian highway concessionaire performance-based procurement shifts.
Macroeconomic conditions sit as an overlay; deviation in diesel price volatility, infrastructure budget execution rates, or emission standard enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding technician training pipeline expansion and battery energy density improvement curves. Material shifts in Chinese hydraulic component export restrictions or GPS guidance technology transfer controls would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Universal Milling Machine Market
Construction Equipment and Machinery
Metal Fabrication Equipment Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Hydraulic Chainsaw Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market