
 Drill Bit Market | 2026-2036
Drill Bit Market Size, Share, and Industry Trends Forecast 2026-2036
Drill Bit Market Intelligence
A transition from single-source contracts to multi-vendor procurement for specialized bits is shifting purchasing power among large industrial firms. Sandvik AB specializes in advanced materials and coatings for hard rock drilling applications. Schlumberger leverages its integrated service model to bundle bits with broader drilling solutions, while Baker Hughes Company competes through its portfolio of application-specific bit technologies that target complex geological formations in the oil and gas sector.
A drill bit is a cutting tool used to remove material and create cylindrical holes. These tools often feature carbide or diamond cutting surfaces bonded to a steel shank, designed for rotational cutting action. Within the market's structure, bits made from Carbide materials command higher value due to durability in demanding applications like mining and construction. High-Speed Steel variants, however, continue to lead in volume for general manufacturing and woodworking tasks performed by contractors and DIY enthusiasts.
Regulatory frameworks globally influence drill bit design and material composition. In the United States, OSHA standards drive innovations that reduce silica dust exposure, while Europe’s REACH and RoHS directives govern chemical content. The imperative to balance higher performance from advanced materials like diamond composites against procurement cost pressures will define the next phase of product development for all end users.
Market Dynamics
The market's central dynamic involves the tension between extreme performance requirements for drilling in hard rock formations and intense procurement cost pressures from end users. This conflict accelerates material science innovation, particularly in advanced composites and industrial diamond technologies.
Growth Catalysts
- Advanced Materials:The development of Polycrystalline Diamond Compact (PDC) cutters enables higher penetration rates and longer bit life in abrasive rock, expanding capabilities in deep oil, gas, and geothermal exploration.
- Critical Mineral Extraction:A global push for energy transition minerals like copper, lithium, and cobalt is intensifying mining activity in geographies such as Chile and the Democratic Republic of Congo, driving equipment demand.
- Infrastructure Investment:Government-led infrastructure programs, including road and tunnel construction projects in India and the United States, stimulate consistent demand for construction-grade rock and concrete drill bits.
Market Restraints
- Input Cost Volatility:Fluctuations in the prices of key raw materials, specifically tungsten carbide and cobalt, create significant cost uncertainty for manufacturers and can lead to price hikes for end users.
- Regulatory Compliance Costs:Adherence to chemical regulations like Europe’s REACH directive adds complexity and expense to manufacturing, particularly for carbide bits that use cobalt as a binder material.
- Substitution by Alternative Methods:In some applications, non-drilling technologies like high-pressure water jet cutting or future laser-based rock boring present a long-term substitution threat for conventional mechanical drilling.
Strategic Opportunities
- Geothermal Energy Drilling:The expansion of geothermal energy projects creates a niche for highly durable bits capable of withstanding the high temperatures and abrasive crystalline rock unique to these applications.
- Sensor Integration:Embedding sensors directly into drill bits for real-time data collection on vibration, temperature, and rock properties offers a path to creating "smart drilling" systems that optimize performance.
- New Exploration Frontiers:Under-explored regions in Africa and Southeast Asia offer significant growth potential for suppliers of specialized mining and exploration bits as new resource deposits are developed.
Industry Challenges
- Specialized Talent Shortages:A lack of trained operators who can effectively use advanced drilling systems and interpret data from sensor-equipped bits limits the full realization of technological benefits on-site.
- Divergent Safety Standards:Manufacturers must design products that comply with varying regional health and safety mandates, such as OSHA's specific rules on silica dust control in the US versus different standards elsewhere.
- Intellectual Property Protection:Safeguarding proprietary designs for cutter geometry, coating formulations, and material compositions is a constant challenge, especially for high-value PDC and diamond-impregnated bits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Drill Bit Market |
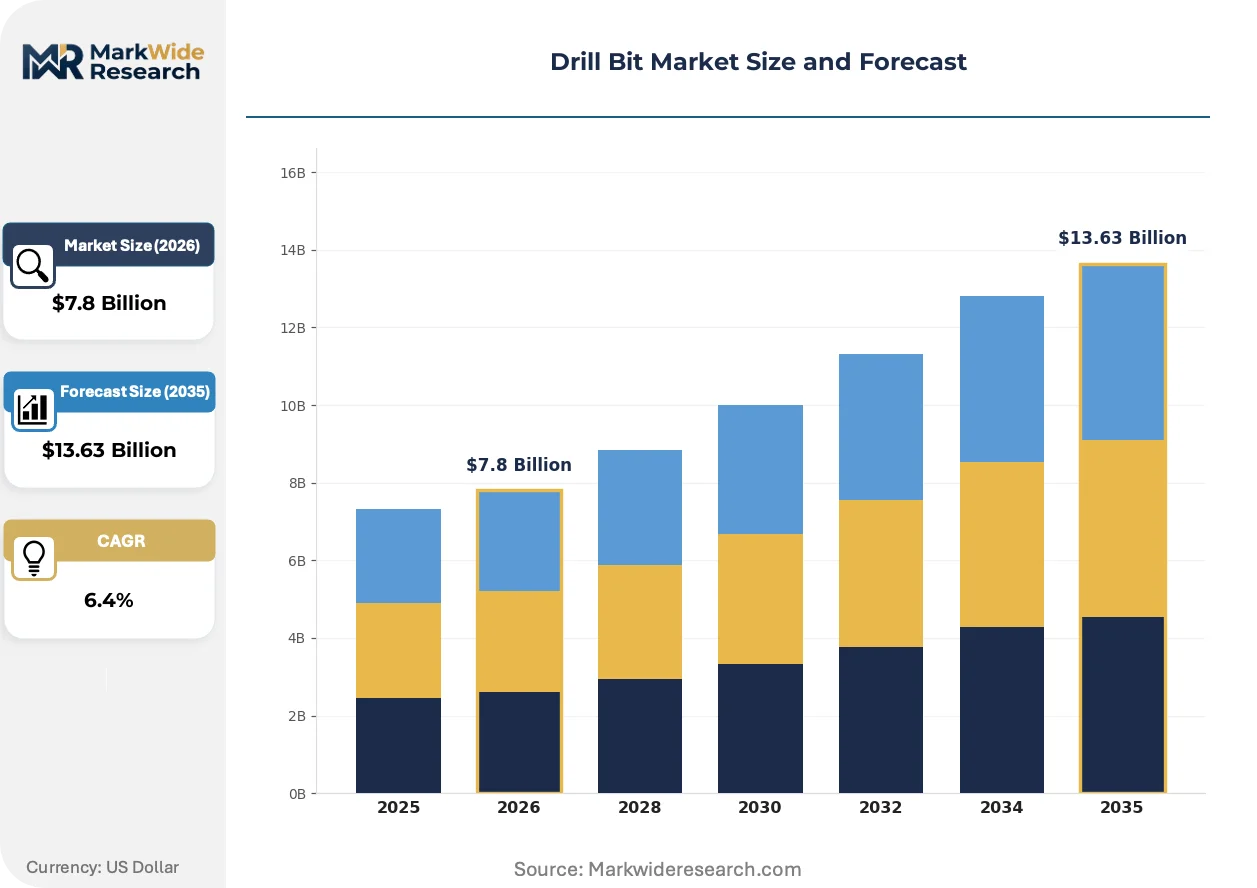
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Twist, Core, Spade, Hole Saw Material: High-Speed Steel, Carbide, Cobalt, Diamond Application: Construction, Manufacturing, Mining, Woodworking End User: Contractors, OEMs, DIY Enthusiasts, Industrial Firms |
| Companies Covered | Schlumberger (SLB), Baker Hughes Company, Halliburton Company, National Oilwell Varco (NOV), Atlas Copco, Sandvik AB, Epiroc AB, Varel International, Ulterra Drilling Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Drill Bit Market Strategic Shifts & Innovations
Application-specific engineering and digital integration are defining the next generation of drill bits. The focus is on tailoring cutter technology and material science to specific geological challenges, which improves operational efficiency and site safety for end users in mining and energy.
PDC cutter technology utilizes a layer of synthetic diamond bonded to a carbide substrate to shear rock with high efficiency. Oil and gas operators and mining companies are adopting these bits to achieve faster drilling speeds. This advanced technology is consolidating its position in the high-performance segment, pushing older bit materials into less demanding or more cost-sensitive applications.
Europe’s REACH directive regulates the use of certain chemicals, including cobalt, a common binder in tungsten carbide tools. This regulation compels manufacturers to invest in R&D for alternative binder materials or navigate extensive compliance documentation. The hard rock drilling segment, which depends on carbide performance, feels the most immediate impact from these material restrictions.
A behavioral change toward multi-vendor procurement for specialized bits allows large firms to source the optimal tool for each distinct geological challenge. This model disrupts traditional sole-supplier relationships by favoring niche technology specialists over generalist providers. This practice is most visible within major resource extraction zones like Australia's Pilbara region and the Permian Basin in the United States.
Drill Bit Market Segmentation
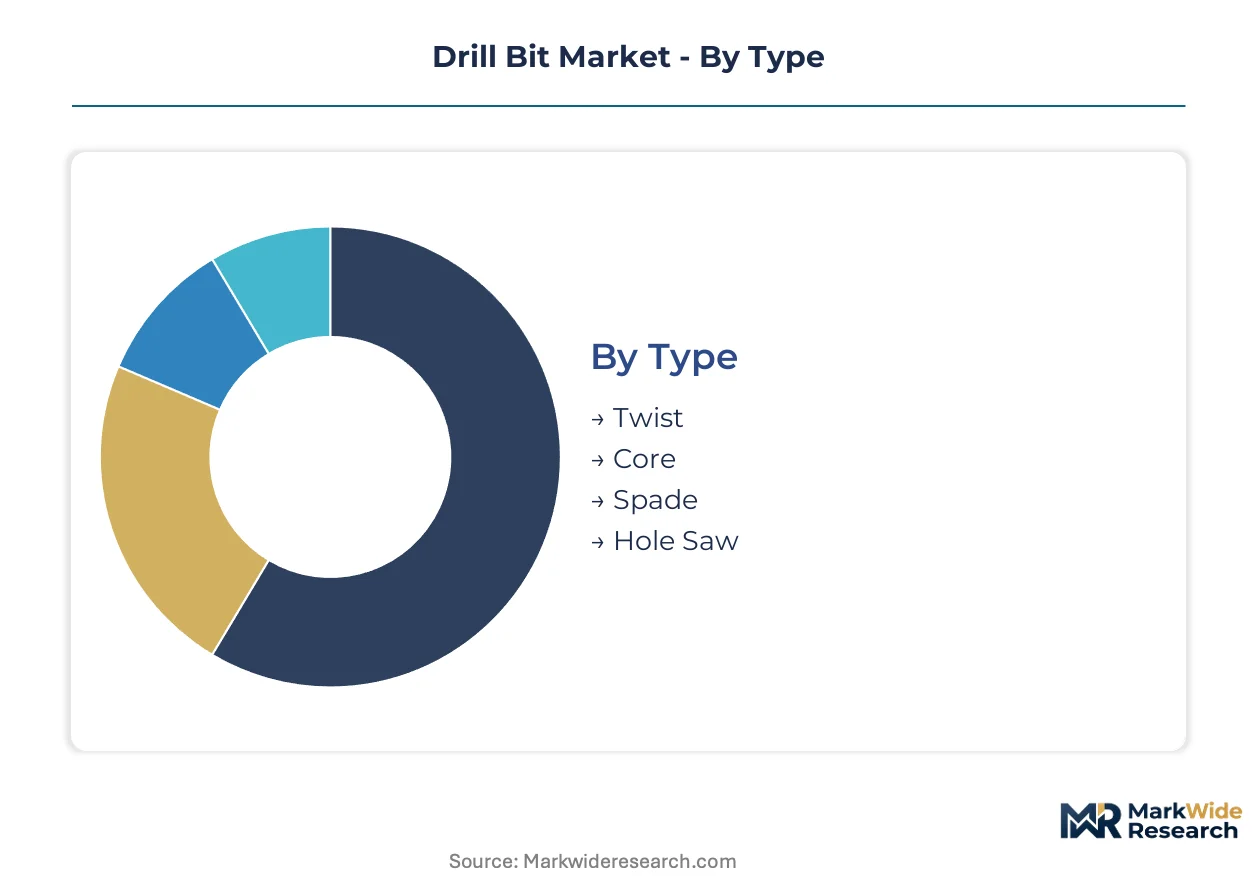
The drill bit market categorizes products by type, material, application, and end-user, reflecting diverse performance requirements across industries. Each segment addresses specific geological challenges and operational demands, influencing product design and material science investments. Understanding these distinctions helps suppliers align offerings with precise customer needs and procurement strategies.
Type:
Supply concentration for drill bit types often reflects manufacturing complexity and specialized application demand. Advanced production techniques are necessary for high-performance bits, leading to fewer specialized suppliers dominating those niches.
- Twist:These bits feature helical flutes for chip removal and are typically made from High-Speed Steel or carbide. Demand concentrates in general manufacturing and woodworking applications across the United States, driven by versatility and cost-effectiveness.
- Core:Designed to cut an annular ring and extract a cylindrical sample, core bits often incorporate diamond segments for abrasive materials. Infrastructure projects in India, particularly for road and tunnel construction, drive demand for these specialized bits for concrete and rock sampling.
- Spade:Characterized by a flat, paddle-shaped head, spade bits are primarily used for drilling large holes in wood. Contractors and DIY enthusiasts widely use these bits for basic construction and home improvement tasks.
- Hole Saw:These bits cut large diameter holes by forming a circular kerf, leaving the core intact. They are common in electrical, plumbing, and HVAC installations.
Today's leader: Twist. Tomorrow's challenger: Core.
Material:
The performance characteristics and durability of drill bits are fundamentally determined by their material composition, impacting their cost and application suitability.
- Carbide:These bits feature tungsten carbide cutting edges, offering superior hardness and heat resistance for demanding applications. Mining operations in Western Australia's Pilbara region heavily demand carbide bits due to their durability in hard rock formations.
- Diamond:Utilizing Polycrystalline Diamond Compact (PDC) or diamond impregnation, these bits deliver exceptional wear resistance and penetration rates in extreme conditions. Deep oil and gas exploration in the Permian Basin drives demand for diamond bits, enabling faster and more efficient drilling.
- High-Speed Steel:Known for its toughness and resistance to abrasion, High-Speed Steel (HSS) is a common material for general-purpose drilling. Manufacturing facilities across Germany utilize HSS bits for machining various metals.
- Cobalt:HSS bits with a cobalt alloy addition offer enhanced heat resistance and hardness, suitable for drilling harder metals. Aerospace component manufacturers in France frequently use cobalt bits for precision work on tough alloys.
The shift towards advanced material composites like diamond is accelerating, displacing traditional materials in high-performance segments.
Application:
Different applications impose distinct requirements on drill bit design, influencing cutter geometry, material selection, and overall bit robustness.
- Mining:This segment requires extremely durable bits capable of penetrating hard rock formations and abrasive ores over long operational cycles. Critical mineral extraction projects in Chile, targeting copper deposits, represent a significant demand driver for high-performance mining bits.
- Construction:Drill bits for construction must handle diverse materials like concrete, asphalt, and various rock types, often prioritizing speed and dust control. Government-led infrastructure programs in the United States stimulate consistent demand for construction-grade rock and concrete drill bits.
- Manufacturing:This application involves precision drilling in metals, plastics, and composites, often requiring high-speed and accurate hole creation. Automotive production lines in Japan rely on specialized manufacturing bits for assembly processes.
- Woodworking:Bits for woodworking are designed for efficient chip removal and clean hole finishes in various wood types. Furniture producers in Vietnam utilize woodworking bits for their production needs.
The mining sector is expanding most quickly, driven by global energy transition demands.
End User:
End-user segments categorize demand based on purchasing power, technical expertise, and specific operational contexts, influencing product features and distribution channels.
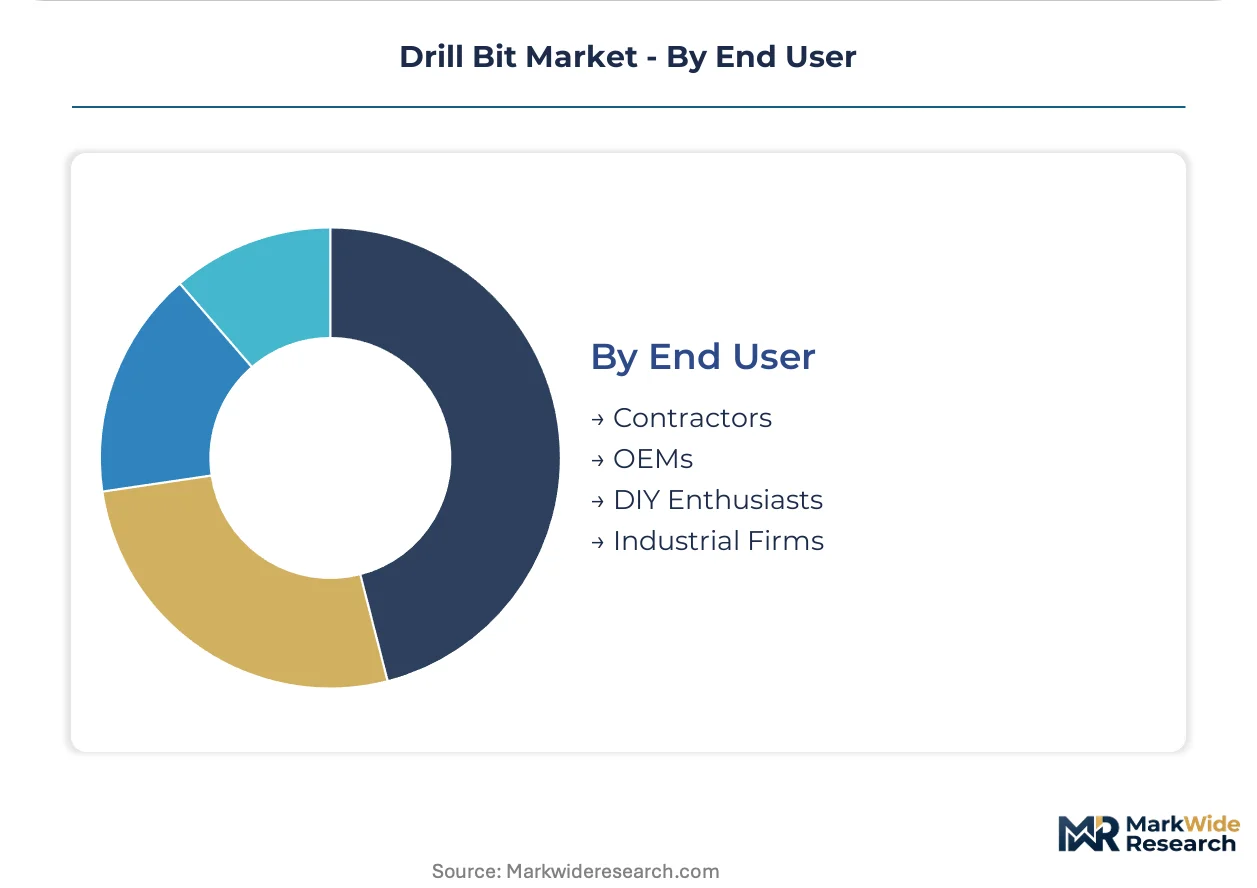
- Industrial Firms:These large enterprises, including oil and gas companies and major mining corporations, prioritize advanced performance, long bit life, and integrated drilling solutions. Their procurement patterns favor multi-vendor sourcing for specialized bits.
- Contractors:Professional contractors in construction and specialized trades require reliable, durable bits that offer good value and performance across various job sites. Demand from contractors for construction-grade bits is strong in urban development projects in the United Kingdom.
- OEMs:Original Equipment Manufacturers integrate drill bits into their machinery or tools, requiring consistent quality and specific technical specifications. Machine tool builders in South Korea procure bits tailored for their equipment.
- DIY Enthusiasts:This segment comprises individual consumers who purchase bits for home improvement and hobby projects, valuing affordability and ease of use. Retail channels in Canada serve DIY enthusiasts with a range of general-purpose drill bits.
Industrial firms dominate the high-value segment, while DIY enthusiasts drive volume in the consumer market.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks globally create a complex landscape for drill bit manufacturing, influencing material choices and production locations. The imperative to balance stringent environmental and safety standards with cost-effective production often drives strategic shifts in supply chains. Manufacturers sometimes re-evaluate their operational footprints to optimize compliance costs across different jurisdictions.
United States
Deep oil and gas exploration in the Permian Basin drives demand for advanced diamond bits. OSHA standards significantly influence drill bit design to mitigate silica dust exposure during construction. Major drilling operations across Texas and Oklahoma concentrate on high-performance bit technologies for complex geological formations.
Australia
Mining operations in Western Australia's Pilbara region heavily demand durable carbide bits for hard rock formations. The nation's push for critical mineral extraction for battery materials accelerates equipment turnover. Specialized suppliers in Perth support the mining industry with tailored drilling solutions and maintenance services.
Chile
Critical mineral extraction projects targeting copper deposits represent a significant demand driver for high-performance mining bits. The Chilean government's investment in sustainable mining practices encourages the use of efficient, long-lasting tools. Mining clusters in the Atacama Desert require robust drill bits capable of withstanding extreme abrasive conditions.
Germany
Manufacturing facilities across Germany utilize High-Speed Steel bits for precision machining of various metals. Europe’s REACH directive compels manufacturers to invest in alternative binder materials for carbide tools. Industrial hubs in Bavaria specialize in producing high-quality drill bits for the automotive and machinery sectors.
India
Government-led infrastructure programs, including road and tunnel construction, stimulate consistent demand for construction-grade rock and concrete drill bits. The Bureau of Indian Standards (BIS) sets quality benchmarks for drilling tools used in large-scale projects. Major construction activity in states like Maharashtra and Uttar Pradesh requires a steady supply of core and twist bits.
Drill Bit Market Key Industry Players
Established producers occupy the standard tier, focusing on high-volume, general-purpose drill bits; emerging entrants pursue niche applications in advanced materials and smart drilling systems. The market exhibits a tiered structure, with a few large integrated service providers and numerous specialized manufacturers. Key strategic archetypes include integrated solution providers, material science innovators, and application-specific specialists. Companies frequently engage in strategic partnerships for technology co-development and geographic expansion into new resource frontiers.
Integrated solution providers like Schlumberger and Baker Hughes Company exemplify the strategy of bundling drill bits with broader drilling solutions. These firms leverage extensive service networks to offer comprehensive packages to oil and gas operators, particularly in complex deep exploration. Sandvik AB, a Swedish industrial group, occupies a position as a material science innovator, specializing in advanced materials and coatings for hard rock drilling applications. These companies anchor different segments of the market, from high-value services to specialized material-driven performance tools.
| Leading Market Players |
|---|
| Schlumberger (SLB) |
| Baker Hughes Company |
| Halliburton Company |
| National Oilwell Varco (NOV) |
| Atlas Copco |
| Sandvik AB |
| Epiroc AB |
| Varel International |
| Ulterra Drilling Technologies |
| Others |
Cost & Logistics Intelligence
Multi-vendor procurement for specialized bits shifts purchasing power, compelling suppliers to differentiate on performance, which in turn influences pricing structures. This demand-side pressure favors niche technology specialists over generalist providers.
Pricing Analysis
Fluctuations in tungsten carbide and cobalt prices directly impact manufacturing costs, leading to price adjustments for end users. Transactional, project-based pricing dominates for high-performance bits in mining and oil and gas. Performance in specific geological formations and after-sales technical support drive price differentiation. Pricing pressure stems from end-user demand for higher performance at lower operational cost. DIY enthusiasts exhibit the highest price sensitivity, while industrial firms prioritize performance over initial cost.
Supply Chain Analysis
Specialized talent shortages in Germany and the United States for advanced manufacturing limit production capacity for complex drill bit components. Production concentrates in Germany, the United States, and Sweden for high-value bits. The supply chain relies on tungsten carbide, cobalt, and industrial diamonds. Regulatory compliance costs, particularly Europe’s REACH directive, present a structural risk. Distribution runs through specialized industrial distributors and direct sales channels to large industrial firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drill bit market presents a geographic-arbitrage opportunity, as manufacturing in regions with lower regulatory compliance costs, like parts of Asia, can offset higher R&D investments required by Europe’s REACH directive. This dynamic influences strategic production decisions.
For Market Incumbents: Lock in long-term supply contracts for critical raw materials like tungsten carbide to mitigate input cost volatility. Invest in advanced material R&D to counter substitution threats from non-drilling technologies. Expand integrated service models, bundling bits with broader drilling solutions, to defend against niche technology specialists. This strategy leverages existing customer relationships and protects against competitive erosion.
For New Entrants and Emerging Players: OSHA standards in the United States open a window for new entrants offering silica dust-reducing bit designs. Target the construction segment within government-led infrastructure programs in India. Partner with local distributors to offer application-specific bits for concrete and rock drilling. Focus on high-performance core bits, where material science innovation creates differentiation.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized material science innovators focusing on diamond composites. The long-term viability of these firms is tied to the global push for critical mineral extraction and geothermal energy development over the next decade. Seek out mid-cap companies with proprietary PDC cutter technology or sensor integration capabilities. Monitor the rate of adoption of "smart drilling" systems in major oil and gas basins.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in advanced PDC cutter R&D | Enhances bit life and penetration rates for deep oil and gas exploration. |
| Expand integrated drilling solutions | Bundles drill bits with services, increasing customer value for industrial firms. |
| Develop alternative binder materials | Mitigates regulatory compliance risks from Europe’s REACH directive. |
| Acquire sensor technology specialists | Enables real-time data collection for "smart drilling" optimization. |
| Target critical mineral extraction regions | Captures demand in Chile and Australia driven by global energy transition. |
Research Approach
Bottom-up end-user modeling reconciled against top-down manufacturer tracking forms the analytical core for this drill bit market study. Primary interviews with drilling engineers, procurement managers, R&D directors, and field operators provided qualitative insights. Secondary validation utilized industry reports, company financial statements, patent databases, and trade association publications. This approach ensures robust data triangulation across multiple sources.
Historical trendline analysis informed the projection of market trajectories over the forecast period. Segmentation dimensions modeled include bit type, material composition, application area, and end-user archetype. Compound annual growth rates were derived from regression analysis of historical market performance. Key forecast inputs included critical mineral demand forecasts and global infrastructure spending plans.
Forecast precision tightens around the base case; tail outcomes carry wider variance under significant geopolitical shifts or unforeseen material supply disruptions. Forecasts reflect assumptions regarding technological advancements and regulatory stability. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
L Allen Wrench Market
Tools
Yard Scraper Market
Tools
Machine Tools Market
Tools
Foam Engraving Machines Market
Tools
Cordless Trim Routers Market
Tools
Global Sandblasting Media Market
Tools
Wood-Sanding Machine Market
Tools
Grease Gun Market
Tools
Overload Protection Tools Market
Tools
Cold and Hot Tool Steel Market
Tools
Spray Painting Machine Market
Tools
Global Swaging Machine Market
Tools
Workholding Tools Market
Tools
Sand Control Tools Market
Tools
Riveting Tools Market
Tools
Diamond Hole Saw Market