
 Virtual Pipeline Market | 2026-2036
Virtual Pipeline Market Size, Share, and Industry Trends Forecast 2026-2036
Virtual Pipeline Market Analysis
Industrial off-grid energy buyers is rotating toward virtual pipeline solutions as pipeline-constrained regions expand manufacturing capacity. Hexagon Agility dominates high-pressure composite cylinder manufacturing for CNG transport modules. Chart Industries anchors cryogenic equipment supply for LNG virtual pipeline networks across North American shale plays. Galileo Technologies specializes in modular compression and regasification systems that enable rapid deployment.
A virtual pipeline constitutes a non-stationary natural gas delivery system employing tube trailers, ISO containers, or cryogenic tankers to transport compressed or liquefied gas from source to consumption point without fixed pipeline infrastructure. These systems operate at pressures ranging from 3,000 to 3,600 psi for CNG or maintain cryogenic temperatures near minus 162 degrees Celsius for LNG, serving industrial facilities, power generation sites, and transportation fueling stations lacking physical pipeline connections. Compressed natural gas holds the largest volume share among product types due to lower liquefaction costs and simpler handling requirements, while renewable natural gas represents the fastest-expanding segment as landfill and agricultural biogas projects seek pipeline-independent offtake pathways. Pipeline monitoring technology commands premium pricing as operators deploy IoT-enabled pressure and leak detection systems to satisfy tightening safety protocols.
The EPA enforces New Source Performance Standards under the Clean Air Act that limit methane venting from compression and transfer operations, directly influencing virtual pipeline equipment specifications and maintenance intervals. DOT Pipeline and Hazardous Materials Safety Administration regulations govern cylinder requalification cycles and transport routing, creating compliance barriers for new market entrants lacking certified fleet assets. Stakeholders must monitor evolving state-level low-carbon fuel standards that could reclassify renewable natural gas delivered via virtual pipeline as a compliance credit generator, altering project economics and infrastructure investment priorities.
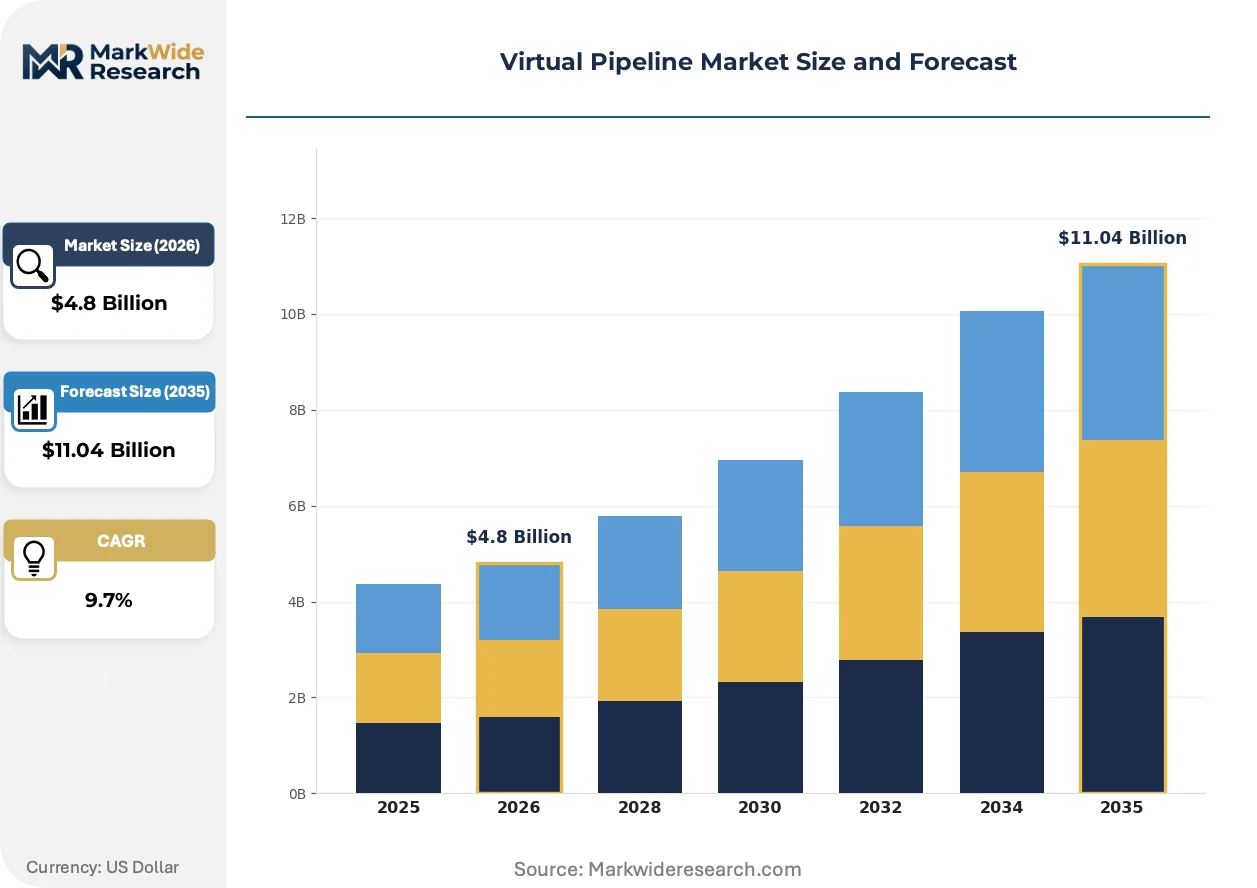
Market Dynamics
Pipeline takeaway capacity constraints in the Permian and Bakken shale formations are forcing industrial off-takers toward mobile gas delivery systems, compressing deployment timelines from years to months.
Growth Catalysts
- EPA Methane Emissions Standards:The EPA's New Source Performance Standards under the Clean Air Act mandate leak detection and repair protocols that favor newer virtual pipeline equipment with IoT-enabled monitoring over aging fixed infrastructure.
- Renewable Fuel Standards:State-level low-carbon fuel standards in California and Oregon create compliance credit pathways for renewable natural gas delivered via tube trailer networks, stimulating landfill and dairy biogas project development.
- Shale Production Bottlenecks:Associated gas flaring restrictions in Texas and North Dakota push producers toward virtual pipeline offtake agreements as pipeline buildouts lag behind drilling activity.
Market Restraints
- DOT Cylinder Requalification Cycles:The Department of Transportation mandates 5-year hydrostatic testing for high-pressure composite cylinders, creating fleet downtime and compliance costs that barrier new entrants lacking certified maintenance networks.
- Cryogenic Equipment Concentration:LNG virtual pipeline systems depend on a concentrated supplier base for vacuum-insulated tankers, exposing operators to lead time volatility and spare parts scarcity.
- Fixed Pipeline Substitution Economics:Large-scale industrial users in the Marcellus and Utica shales face persistent pressure to switch to permanent pipeline connections once takeaway capacity expands, threatening contract renewal rates.
Strategic Opportunities
- Power Generation Microgrids:Remote mining operations and data centers in Wyoming and Colorado present untapped demand for containerized LNG regasification systems that bypass transmission interconnection queues.
- Renewable Natural Gas Aggregation:Agricultural digesters in the Midwest lack pipeline interconnection, creating white space for mobile compression and tube trailer consolidation services that aggregate distributed biogas supply.
- Transportation Fueling Corridors:Heavy-duty trucking fleets along I-10 and I-80 corridors require CNG and LNG fueling infrastructure that virtual pipeline operators can deploy faster than permanent station buildouts.
Industry Challenges
- ASME Certification Timelines:Pressure vessel and piping system approvals under ASME Boiler and Pressure Vessel Code Section VIII extend equipment commissioning cycles by 6-12 months, compressing project returns.
- Specialized Technician Scarcity:Cryogenic system maintenance and high-pressure compression operations require certified personnel that existing vocational pipelines fail to produce at sufficient scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Virtual Pipeline Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Natural Gas, Liquefied Natural Gas, Hydrogen, Renewable Natural Gas Technology: Pipeline Monitoring, Compression Systems, Metering Solutions, Control Systems End User: Utilities, Industrial Sector, Commercial Sector, Transportation Application: Transportation Fuel, Power Generation, Heating, Industrial Processes |
| Companies Covered | Xpress Natural Gas, Hexagon Agility, Chart Industries, NG Advantage, Stabilis Solutions, Galileo Technologies, Kinder Morgan, CERTARUS Ltd, Air Products and Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Virtual Pipeline Market Emerging Trajectories
Equipment manufacturers are converging on modular, skid-mounted designs that slash field assembly requirements. Composite materials and digital monitoring systems are compressing weight profiles and enabling predictive maintenance protocols.
Carbon fiber-reinforced polymer cylinders from Hexagon Agility and Worthington Industries are displacing traditional steel pressure vessels in CNG transport modules. Fleet operators in the Permian Basin are retrofitting existing trailers with Type IV composite tanks to extend range and payload capacity. This displacement is compressing the total cost of ownership differential between virtual pipeline delivery and fixed pipeline connections for industrial users within 150 miles of supply sources.
The EPA's supplemental proposal to strengthen methane emissions standards for the oil and natural gas sector tightens monitoring frequency and repair timelines for compression equipment. Virtual pipeline operators must deploy continuous emissions monitoring systems and optical gas imaging protocols across transfer stations and storage facilities. Small and mid-size operators lacking capital for sensor networks face consolidation pressure or operational restrictions in Pennsylvania and Texas production zones.
Industrial buyers are unbundling fuel supply contracts from equipment provision, forcing virtual pipeline operators to compete on molecule price rather than integrated service packages. Chemical manufacturers and food processors in the Gulf Coast region now source gas through third-party commodity traders while leasing transport equipment from independent fleet operators. This bifurcation is most visible in Louisiana and Texas, where spot market liquidity and trailer leasing platforms have matured.
Virtual Pipeline Market Segmentation
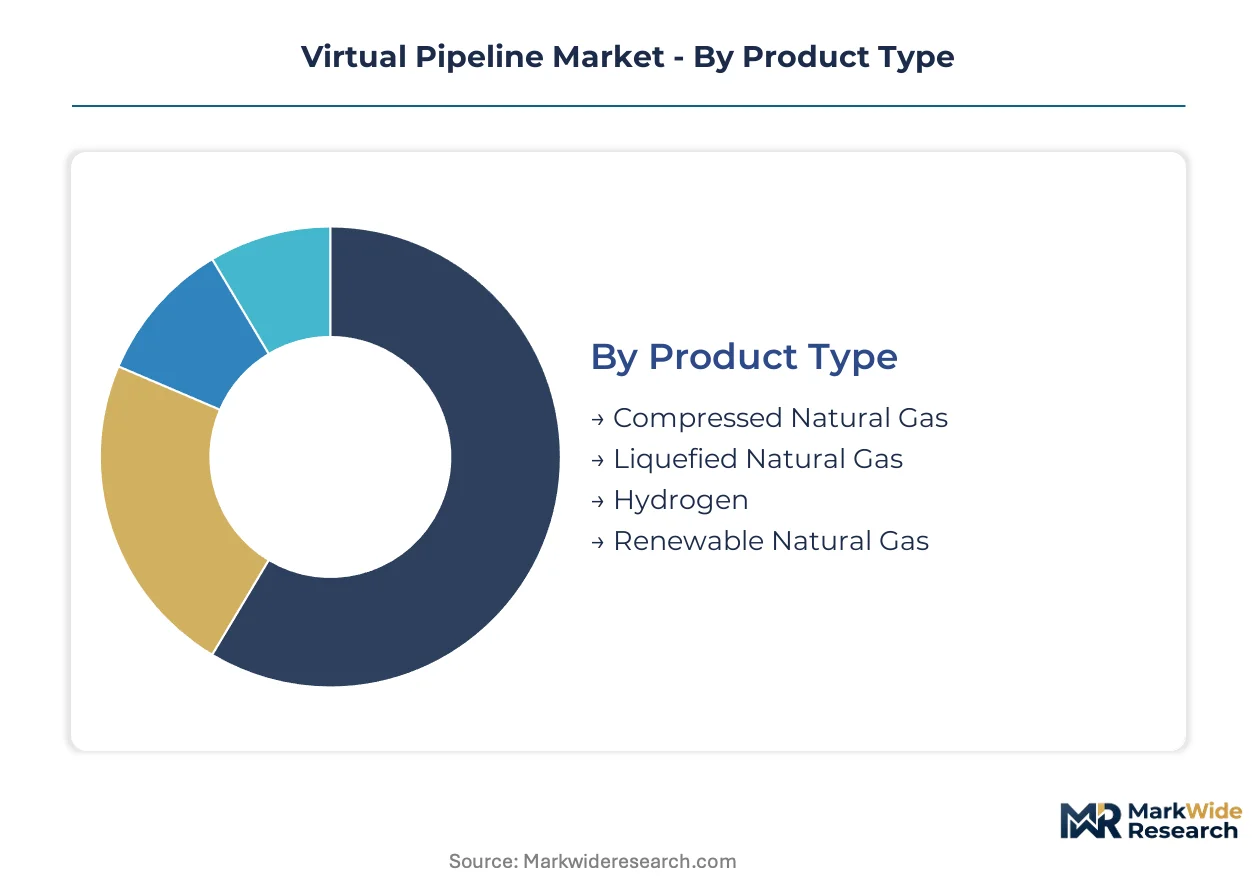
Virtual pipeline operators configure equipment specifications and service models around distinct regulatory thresholds, end-use thermal requirements, and transport distance economics. Segmentation reveals where compliance costs concentrate and which technology combinations unlock profitable deployment in pipeline-constrained geographies.
Product Type:
EPA methane performance standards and state renewable fuel credits create divergent compliance burdens across gas compositions, altering equipment selection and maintenance protocols.
- Compressed Natural Gas:Stored in high-pressure composite cylinders at 3,000 to 3,600 psi, CNG dominates short-haul industrial delivery within 150 miles of supply sources. Demand concentrates in Texas and Pennsylvania shale plays where flaring restrictions push producers toward mobile offtake agreements.
- Liquefied Natural Gas:Maintained at cryogenic temperatures near minus 162 degrees Celsius, LNG enables long-distance transport and high-volume delivery to remote power generation and marine bunkering sites. Industrial microgrids in Wyoming and Colorado mining corridors favor LNG for energy density and storage duration.
- Hydrogen:Emerging transport applications leverage existing CNG infrastructure with modified compression and cylinder materials; pilot deployments focus on California heavy-duty trucking corridors seeking zero-emission fuel alternatives.
- Renewable Natural Gas:Pipeline-quality biomethane from landfill and agricultural digesters qualifies for low-carbon fuel standard credits in Oregon and California, stimulating dairy and waste sector project development.
Established volume favors compressed natural gas; emerging adoption favors renewable natural gas.
Technology:
Capital intensity and operational criticality separate technologies into core infrastructure versus monitoring overlay investments.
- Pipeline Monitoring:IoT-enabled pressure sensors and optical gas imaging systems command premium pricing as operators deploy continuous emissions monitoring to satisfy EPA leak detection and repair protocols.
- Compression Systems:Modular skid-mounted units from specialized manufacturers enable rapid field deployment; Permian Basin operators prioritize units with integrated methane capture to meet venting restrictions.
- Metering Solutions:Custody transfer accuracy requirements drive specification for Coriolis and ultrasonic flow meters at virtual pipeline interconnection points.
- Control Systems:Distributed automation platforms manage pressure regulation and safety shutdowns across trailer fleets and regasification terminals.
Compression systems anchor capital deployment; pipeline monitoring is climbing the fastest as regulatory enforcement tightens.
End User:
Contract duration and volume predictability vary sharply across customer categories, shaping fleet utilization and financing structures.
- Industrial Sector:Chemical manufacturers and food processors in the Gulf Coast region unbundle fuel supply from equipment provision, sourcing molecules through commodity traders while leasing transport assets.
- Utilities:Municipal gas distribution companies deploy virtual pipelines as seasonal peak shaving and emergency backup, requiring rapid-response fleet availability.
- Commercial Sector:Hotels, hospitals, and institutional facilities lacking pipeline access represent fragmented, price-sensitive demand with shorter contract terms.
- Transportation:Heavy-duty trucking fleets along I-10 and I-80 corridors require dedicated CNG and LNG fueling infrastructure with high station throughput.
Industrial offtakers provide contract stability; transportation fueling delivers the steepest expansion trajectory.
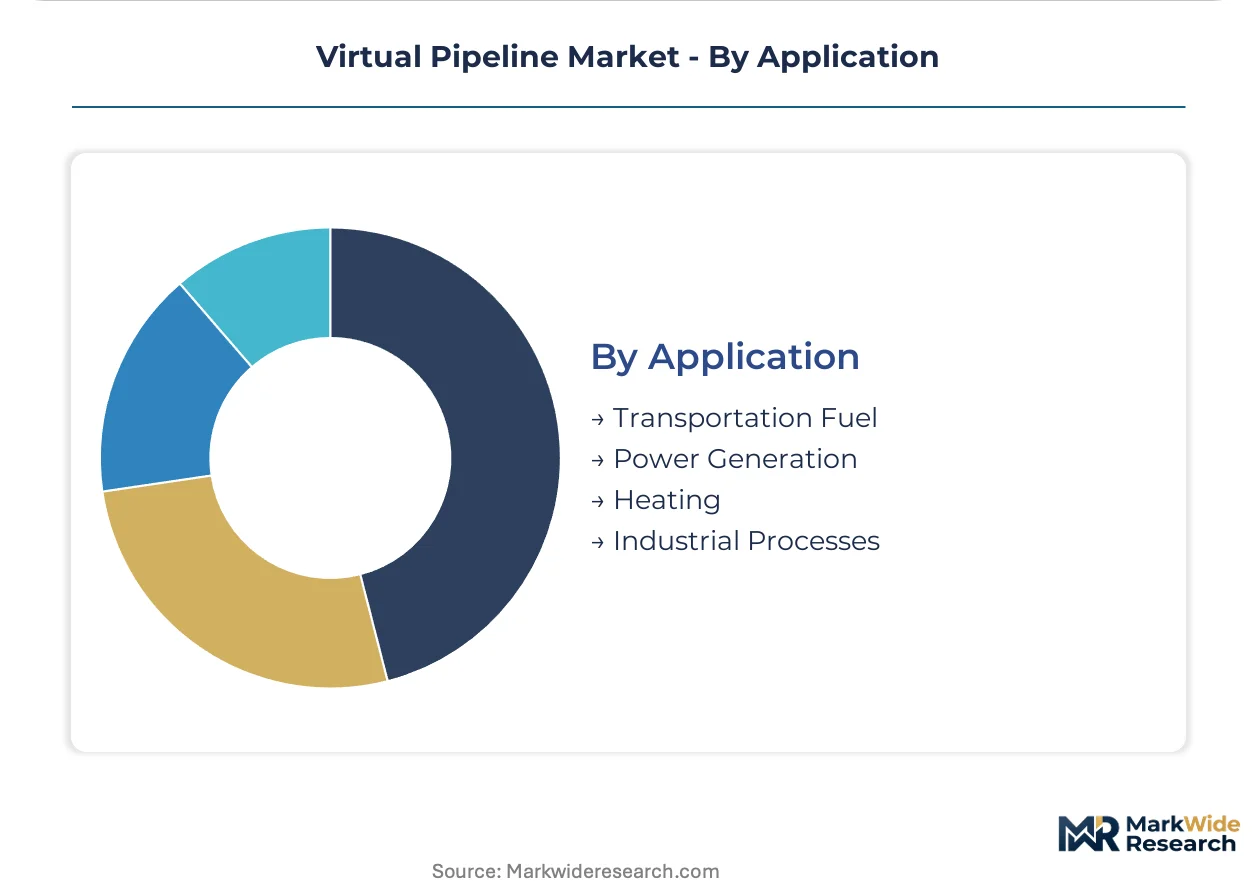
Application:
Thermal load profiles and emissions constraints determine gas quality specifications and delivery reliability requirements.
- Industrial Processes:High-heat manufacturing applications in cement, glass, and metals production require consistent pressure and calorific value, favoring LNG for thermal stability.
- Power Generation:Remote mining operations and data centers bypass transmission interconnection queues using containerized LNG regasification for baseload or backup power.
- Transportation Fuel:Fleet operators prioritize fast-fill CNG and LNG dispensing capacity, driving investment in high-flow compression and cryogenic pumping systems.
- Heating:Seasonal demand from commercial and institutional buildings concentrates in winter months, creating fleet utilization challenges for operators without diversified contract portfolios.
Industrial processes anchor equipment specifications; power generation microgrids are gaining share fastest as interconnection delays persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Virtual pipeline equipment and services flow primarily from United States manufacturers to pipeline-constrained industrial zones across North America, with shale production bottlenecks in Texas and North Dakota driving cross-border equipment deployment into Canadian mining corridors and Mexican manufacturing clusters.
United States
Permian Basin flaring restrictions and Bakken shale takeaway constraints sustain demand for mobile CNG and LNG delivery systems. The EPA's New Source Performance Standards mandate leak detection protocols that favor newer compression equipment with integrated monitoring. Industrial facilities in Texas, Pennsylvania, and North Dakota represent the densest concentration of virtual pipeline contracts.
Canada
Remote mining operations in Alberta and British Columbia bypass grid interconnection queues through containerized LNG regasification for power generation. Environment and Climate Change Canada methane regulations align with EPA stringency, creating equipment specification overlap with United States suppliers. The oil sands region around Fort McMurray deploys virtual pipelines for process heat and worker camp power.
Mexico
Manufacturing expansion in Nuevo León and Tamaulipas outpaces fixed pipeline buildout, creating demand for tube trailer-delivered natural gas. Comisión Reguladora de Energía permitting delays for permanent infrastructure compress deployment timelines for mobile alternatives. Monterrey industrial parks represent the fastest-growing contract concentration for cross-border equipment lessors.
Germany
Industrial gas buyers in Bavaria and North Rhine-Westphalia seek pipeline-independent supply security amid geopolitical supply restructuring. The EU F-Gas Regulation and national methane reduction targets pressure operators toward low-emission compression technologies. Chemical clusters around Ludwigshafen and Leverkusen pilot renewable natural gas delivery via virtual pipeline to meet corporate decarbonization commitments.
Australia
Remote mining and mineral processing operations in Western Australia and Queensland rely on LNG virtual pipelines for off-grid power and process heat. The Clean Energy Regulator's Safeguard Mechanism creates compliance incentives for lower-emission fuel switching. Pilbara iron ore operations represent high-volume demand for cryogenic transport and regasification systems.
Virtual Pipeline Market Vendor Landscape
Player mix skews toward integrated equipment manufacturers with captive cylinder production and specialized compression technology licensors. Market structure concentrates around three strategic tiers: composite pressure vessel specialists, cryogenic system fabricators, and modular compression packagers. Competitive dynamics center on ASME certification speed and fleet scale economics, with dominant moves including backward integration into cylinder manufacturing and geographic expansion through equipment leasing platforms.
Within the integrated equipment tier, Hexagon Agility and Chart Industries occupy anchor positions, the former representing composite cylinder manufacturing depth and the latter exemplifying cryogenic system integration capabilities. Galileo Technologies sits within the modular compression specialization vector. These three entities collectively illustrate the technology segmentation that defines competitive positioning: pressure containment expertise, thermal management systems, and skid-mounted process equipment.
| Leading Market Players |
|---|
| Xpress Natural Gas |
| Hexagon Agility |
| Chart Industries |
| NG Advantage |
| Stabilis Solutions |
| Galileo Technologies |
| Kinder Morgan |
| CERTARUS Ltd |
| Air Products and Chemicals |
| Others |
Supply Flow & Price Mechanics
Fleet scale economies at 500+ tube trailer units compress per-mile delivery costs and erect price floors that smaller operators cannot match, concentrating supply-side power among certified fleet aggregators while pressuring marginal players toward equipment leasing or exit.
Pricing Analysis
Next-generation Type IV composite cylinders command 15-20% premiums over legacy steel pressure vessels, while prior-generation Type II metal-lined cylinders face accelerated depreciation. Three-tier pricing structure across premium ASME-certified, standard DOT-compliant, and economy refurbished equipment levels dominates equipment procurement. Price differentiation hinges on EPA methane monitoring integration and cylinder requalification cycle length, with industrial buyers in Texas and Pennsylvania showing highest sensitivity to per-MMBtu delivery spreads. Cost compression in standard-tier compression systems is intensifying because modular skid-packagers are eroding field-assembly premiums.
Supply Chain Analysis
The United States anchors composite pressure vessel fabrication through Hexagon Agility and Worthington Industries facilities, while Germany and China concentrate cryogenic tanker production for LNG virtual pipeline networks. Raw material flows draw from carbon fiber pre-preg suppliers in Japan, high-strength aluminum forging in Russia, and vacuum insulation panel manufacturers in South Korea. Single-source vulnerability concentrates in ASME-certified forging capacity for high-pressure cylinder neck rings. Distribution runs through equipment leasing platforms and captive fleet operators serving Permian Basin and Bakken shale corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat: DOT cylinder certification networks and EPA emissions compliance protocols create switching costs that cement incumbent positions while raising new entrant capital thresholds.
For Market Incumbents: Shield market position by accelerating backward integration into composite cylinder manufacturing to capture margin compression from steel-to-composite displacement, and harden defensive moats through ASME certification speed investments that extend lead times for challenger equipment approvals. Emerging modular compression packagers threaten service contract erosion in the Permian Basin. For New Entrants and Emerging Players: DOT fast-track certification programs for high-pressure composite cylinders unlock white-space entry in agricultural biogas aggregation across Midwest dairy corridors, where pipeline interconnection gaps exceed 200 miles. Target containerized LNG regasification for remote data center microgrids in Wyoming and Colorado as the most penetrable application, deploying lease-to-own equipment financing to bypass incumbent fleet scale advantages. For Investors and Strategic Acquirers: Mid-size fleet operators with captive maintenance networks and multi-state DOT certifications represent the highest-conviction acquisition archetype for rollup strategies. Long-term viability hinges on renewable natural gas credit monetization durability under evolving state low-carbon fuel standards. Watch California LCFS credit price volatility as the inflection signal for RNG project development momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cylinder Manufacturing | Captures margin from Type IV composite displacement and secures supply continuity against carbon fiber pre-preg allocation constraints. |
| EPA Continuous Emissions Monitoring Deployment | Satisfies supplemental methane performance standards and differentiates fleet assets for penalty-averse industrial buyers in Texas. |
| Renewable Natural Gas Aggregation Partnerships | Locks landfill and dairy digester offtake streams to generate California and Oregon LCFS compliance credits. |
| Modular Compression Skid Standardization | Compresses field commissioning timelines from 6-12 months to 8-12 weeks for rapid Permian Basin deployment. |
| Cryogenic Equipment Leasing Platform Expansion | Addresses LNG virtual pipeline demand from remote mining operations in Wyoming, Colorado, and Western Australia. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with virtual pipeline fleet operators, compression equipment procurement managers, and EPA compliance officers; and secondary validation through DOT cylinder requalification databases, FERC interstate gas transport filings, and state-level renewable fuel standard credit registries. Bottom-up equipment deployment counts triangulated against top-down shale production and flaring volume estimates from EIA data.
Across the analysis window, the forecast framework modeled segmentation by product type, technology tier, end-user contract structure, and regional regulatory stringency cluster. CAGRs were derived from equipment replacement cycles, pipeline takeaway capacity expansion lag times, and renewable natural gas project development pipelines. Key inputs included EPA methane rule implementation timelines and state LCFS credit bank balances.
Decision-makers should treat outputs as directional under assumptions of sustained shale production growth and stable renewable fuel credit pricing; material deviation in pipeline buildout completion rates or federal methane regulation rollback would warrant model refresh. Recalibration cycles align with material shifts in EPA enforcement posture and state-level low-carbon fuel standard amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Global Oil Storage Fee Rental Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Natural Gas Refueling Infrastructure Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market