
 Southeast Asia Power Transmission and Distribution Market | 2026-2036
Southeast Asia Power Transmission and Distribution Market Size, Share, and Industry Trends Forecast 2026-2036
Southeast Asia Power Transmission and Distribution Market Analytics
Copper-aluminum hybrid conductor designs is consolidating cost advantages across long-haul transmission projects in archipelagic geographies. Hitachi Energy leverages its HVDC technology leadership to anchor submarine cable interconnection bids between Indonesian islands. Siemens AG competes through localized manufacturing partnerships that sustain delivery timelines for 500 kV transformer contracts.
Southeast Asia power transmission and distribution encompasses the infrastructure, equipment, and services that move electricity from generation sources through high-voltage networks to distribution endpoints serving industrial, commercial, and residential consumers, typically operating at voltages from 66 kV to 800 kV for transmission and 11 kV to 33 kV for primary distribution. Transformers dominate product procurement volumes as aging oil-immersed units face replacement pressure under stricter fire-safety codes, while smart grid technology captures the fastest growth trajectory as utilities deploy SCADA-enabled monitoring to manage renewable intermittency from solar and wind farms. Service-type revenue pools tilt toward upgrades and maintenance as state-owned operators defer greenfield capital in favor of extending existing asset life.
Indonesia's CEA and Vietnam's EVN technical standards shape equipment certification requirements across the region, while ASEAN Power Grid coordination protocols influence cross-border transmission investment sequencing. Thailand's ERC and the Philippines' ERC both enforce reliability indices that mandate automation upgrades in urban distribution networks. Stakeholders must monitor which national regulators accelerate renewable integration timelines versus those prioritizing baseload stability, as this divergence determines transformer specification and smart-grid deployment speed.
Market Dynamics
Data center load growth across Singapore, Indonesia, and Vietnam is pulling high-voltage infrastructure investment faster than grid operators can deploy capital, compressing procurement cycles for 500 kV transformers and submarine cable systems.
Growth Catalysts
- ASEAN Power Grid coordination protocols:Cross-border transmission investment sequencing is unlocking interconnection projects between Thailand, Malaysia, and Singapore, creating pooled procurement opportunities for HVDC equipment.
- Indonesia's Java-Bali interconnection upgrades:State-owned PLN is accelerating transformer replacement cycles under stricter fire-safety codes, generating demand for dry-type and gas-insulated alternatives.
- Vietnam's north-south transmission corridor expansion:EVN's 500 kV backbone reinforcement is absorbing switchgear and conductor volumes as renewable integration mandates tighten grid stability requirements.
Market Restraints
- Copper price volatility:Raw material swings compress transformer manufacturer margins and destabilize long-term contract pricing for utilities.
- Specialized high-voltage cable supply concentration:Submarine interconnector fabrication capacity clusters in European and Northeast Asian facilities, extending delivery timelines for Indonesian archipelago projects.
- Land acquisition friction under Vietnam's Land Law:Transmission right-of-way approvals delay corridor construction and inflate project development costs.
Strategic Opportunities
- Philippines' offshore wind pipeline:The country's 35 GW seabed lease program requires export cable systems and offshore substation platforms that domestic suppliers cannot yet deliver.
- Digital twin convergence with SCADA:Real-time grid modeling layered atop existing monitoring infrastructure is creating upgrade revenue streams without full asset replacement.
- Thailand's smart city mandates:Bangkok Metropolitan Authority's distribution automation requirements are opening urban secondary substation retrofit contracts.
Industry Challenges
- HVDC commissioning engineer scarcity:Specialized skills for converter station energization are concentrated among aging European and Japanese technician pools, constraining project ramp rates.
- CEA-EVN certification divergence:Indonesia and Vietnam maintain non-harmonized type-test requirements, forcing manufacturers to duplicate validation protocols for adjacent markets.
- Legacy oil-immersed transformer integration:Fire-code retrofits demand thermal modeling expertise that local utilities lack, slowing replacement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Southeast Asia Power Transmission and Distribution Market |
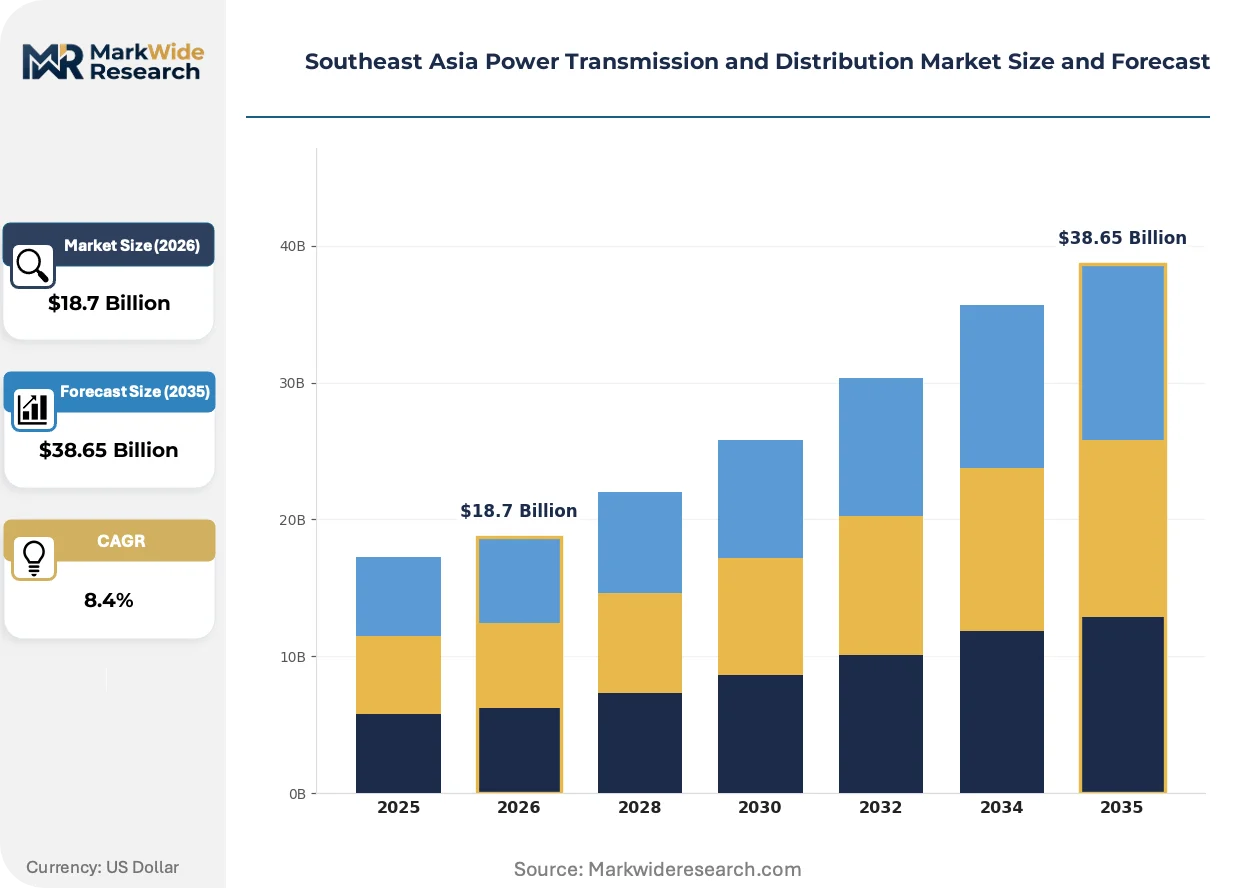
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Transformers, Switchgear, Circuit Breakers, Conductors Service Type: Installation, Maintenance, Consulting, Upgrades End User: Utilities, Industrial Sector, Commercial Sector, Residential Users Technology: Smart Grid, Renewable Integration, SCADA Systems, Conventional Systems |
| Companies Covered | Hitachi Energy, Toshiba Corporation, Mitsubishi Electric Corporation, LS Electric, CG Power and Industrial Solutions Limited, General Electric Company, Schneider Electric SE, Hyosung Heavy Industries, Siemens AG, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Southeast Asia Power Transmission and Distribution Market Evolving Landscape
Grid digitalization and conductor material substitution are compressing traditional equipment procurement patterns while opening service-based revenue pools for technology providers.
Gas-insulated switchgear is expanding into urban distribution substations across Bangkok, Jakarta, and Ho Chi Minh City as land scarcity forces footprint reduction. PLN, EVN, and Meralco are specifying 145 kV GIS for new underground substations at triple the rate of air-insulated alternatives. This technology is expanding into secondary distribution networks previously reserved for conventional switchgear, compressing equipment procurement cycles by eliminating civil works.
Thailand's ERC reliability index enforcement is mandating distribution automation upgrades in metropolitan networks. The regulation requires SAIDI and SAIFI improvements that force SCADA deployment down to 22 kV feeders. Urban utilities are responding by unbundling automation packages from primary equipment contracts, creating discrete procurement categories for sensors and control systems.
Data center operators in Singapore and Johor are contracting directly with transmission developers for dedicated substations, bypassing traditional utility intermediation. Hyperscale buyers are specifying 230 kV delivery points with redundant feeds, displacing standard industrial connection protocols. This pattern is most visible in Singapore's Tuas and Indonesia's Batam corridor, where load growth outstocks distribution network capacity.
Southeast Asia Power Transmission and Distribution Market Segmentation
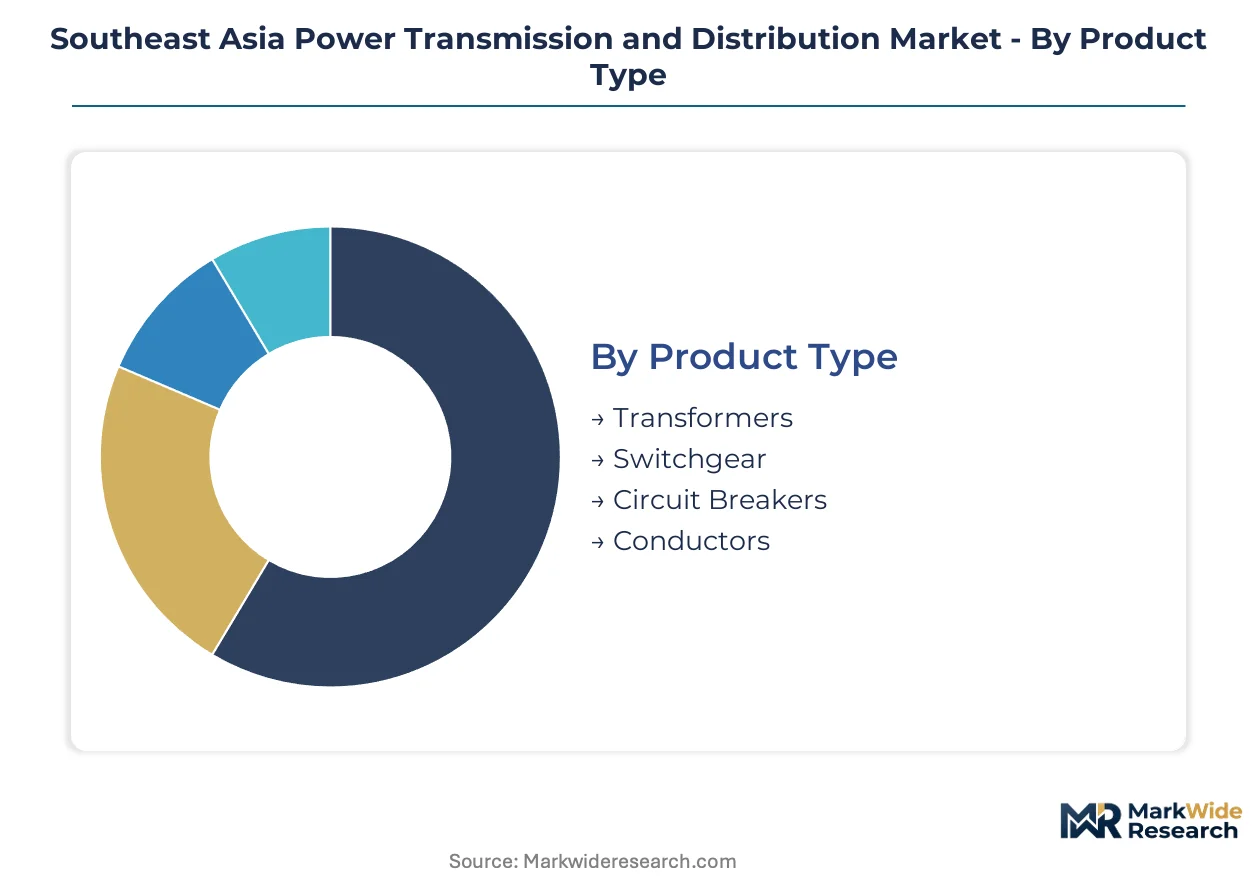
Power transmission and distribution equipment procurement in Southeast Asia fragments across voltage tiers, service lifecycles, and grid modernization priorities. Understanding these segment boundaries reveals where capital concentrates versus where operational expenditure dominates.
Product Type:
Voltage ratings and insulation mediums differentiate procurement specifications across transmission corridors and distribution substations.
- Transformers:Oil-immersed units face replacement pressure under Indonesia's stricter fire-safety codes, while dry-type and gas-insulated alternatives gain specification share in urban underground substations across Jakarta and Bangkok. PLN's Java-Bali interconnection upgrades and EVN's 500 kV backbone reinforcement are absorbing large power transformer volumes at voltage classes from 230 kV to 500 kV.
- Switchgear:Gas-insulated switchgear specifications are expanding into metropolitan distribution networks previously reserved for air-insulated alternatives, driven by land scarcity in Bangkok, Jakarta, and Ho Chi Minh City. PLN, EVN, and Meralco are specifying 145 kV GIS for new underground substations at triple the rate of conventional options.
- Circuit Breakers:High-voltage vacuum and SF6 interruption technologies serve 500 kV transmission corridors in Vietnam and Indonesia's island interconnection projects.
- Conductors:Copper-aluminum hybrid designs consolidate cost advantages across long-haul archipelagic transmission routes.
Mature deployment sits with oil-immersed transformers and air-insulated switchgear. Newer deployment is concentrated in gas-insulated switchgear and dry-type transformer alternatives.
Service Type:
Procurement patterns tilt toward lifecycle extension as state-owned operators defer greenfield capital in favor of asset optimization.
- Installation:Greenfield substation construction concentrates in Vietnam's north-south corridor and Indonesia's island interconnectors, though project timelines extend due to specialized HVDC commissioning engineer scarcity.
- Maintenance:Aging transformer fleets across Thailand's metropolitan networks and the Philippines' distribution zones generate recurring revenue pools as utilities prioritize reliability index compliance.
- Consulting:Thermal modeling expertise for fire-code retrofits and grid stability analysis supports renewable integration mandates in Indonesia and Vietnam.
- Upgrades:SCADA-enabled monitoring deployment and digital twin convergence create upgrade revenue streams without full asset replacement, particularly in Thailand's ERC-mandated distribution automation programs.
Installation revenue clusters in Vietnam and Indonesia's transmission expansion zones. Upgrades are expanding most quickly across Thailand and Singapore's smart grid mandates.
End User:
Load growth velocity and grid access protocols determine equipment specification priorities across customer categories.
- Utilities:State-owned PLN, EVN, and Meralco dominate procurement volumes, driven by ASEAN Power Grid coordination protocols and national renewable energy targets shaping transformer and switchgear replacement cycles.
- Industrial Sector:Data center operators in Singapore's Tuas and Indonesia's Batam corridor are contracting directly for dedicated 230 kV substations with redundant feeds, bypassing standard industrial connection protocols.
- Commercial Sector:Urban load centers in Bangkok, Jakarta, and Ho Chi Minh City drive distribution automation requirements as ERC reliability indices mandate SAIDI and SAIFI improvements.
- Residential Users:Rural electrification programs in Indonesia's outer islands and Vietnam's mountainous regions sustain demand for medium-voltage distribution infrastructure.
Utility procurement anchors volume. Industrial direct contracting is gaining share fastest in Singapore and Johor's data center corridors.
Technology:
Control layer sophistication separates capital expenditure profiles across grid modernization trajectories.
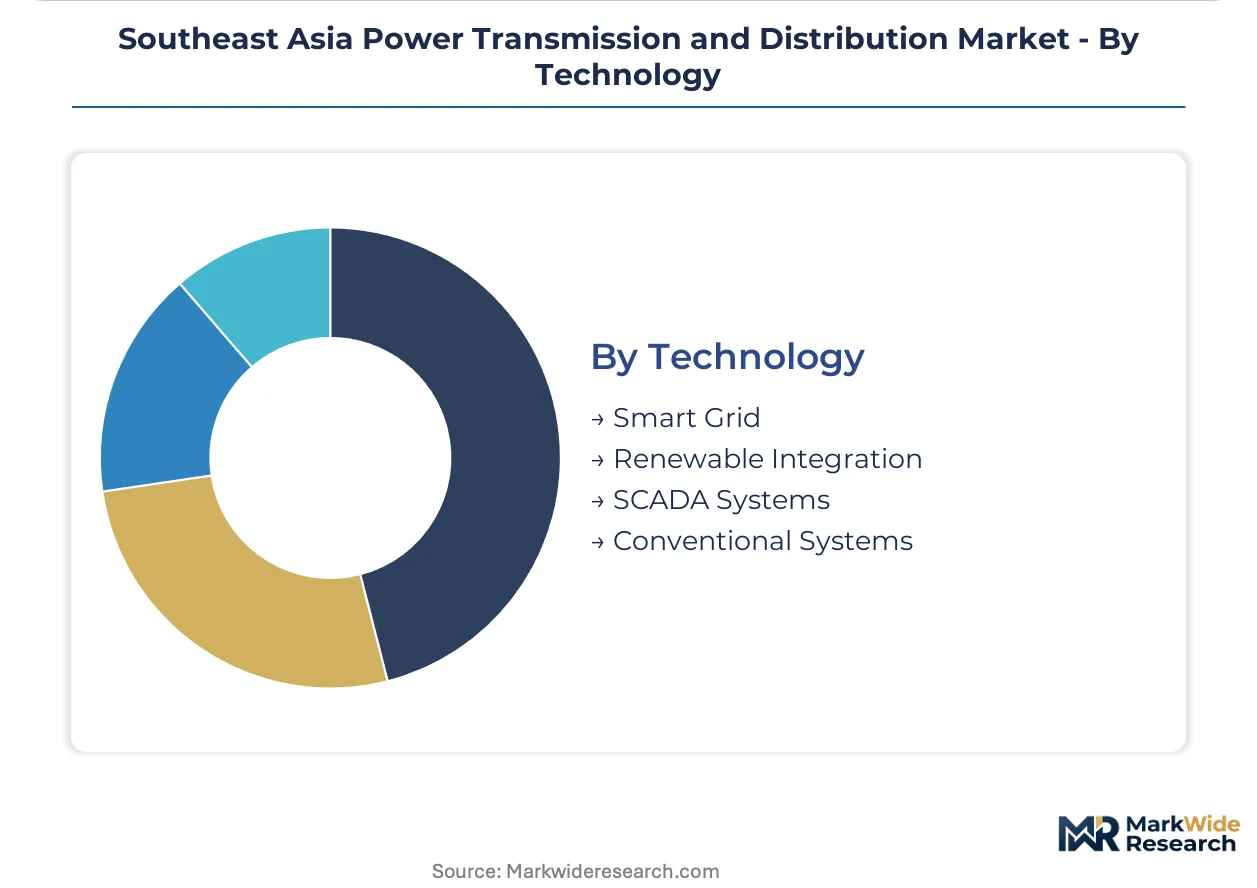
- Smart Grid:Distribution automation packages are unbundling from primary equipment contracts in Thailand's metropolitan networks, creating discrete procurement categories for sensors and control systems that manage renewable intermittency.
- Renewable Integration:Grid stability requirements from solar and wind farm connections are tightening specifications for power quality equipment and energy storage interfaces in Vietnam's central highlands and Indonesia's Java grid.
- SCADA Systems:Real-time monitoring deployment down to 22 kV feeders satisfies Thailand's ERC reliability enforcement, with digital twin convergence layering atop existing infrastructure.
- Conventional Systems:Electromechanical protection and manual switching equipment persists in Indonesia's outer island networks where capital constraints limit automation deployment.
Conventional systems retain share in Indonesia's peripheral islands. Smart grid and SCADA deployment is concentrating in Thailand, Singapore, and Vietnam's urban load centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Batam's free trade zone and Batamindo Industrial Park concentrate data center load growth that pulls dedicated 230 kV substation investment from transmission developers. This corridor exemplifies how special economic zones reshape power infrastructure deployment across the region.
Indonesia
Java-Bali interconnection upgrades and PLN's transformer replacement programs under stricter fire-safety codes absorb large power transformer volumes. The country's CEA technical standards shape equipment certification requirements that force manufacturers into duplicate validation protocols. Batam's data center corridor and Jakarta's underground substation expansions are specifying gas-insulated switchgear at triple the rate of conventional alternatives.
Vietnam
EVN's north-south 500 kV backbone reinforcement and renewable integration mandates tighten grid stability requirements for switchgear and conductor procurement. The country's Land Law generates transmission right-of-way friction that delays corridor construction and inflates project costs. Northern industrial provinces and the central highlands wind zones are absorbing SCADA-enabled monitoring deployment to manage solar and wind intermittency.
Singapore
Tuas data center clusters and Johor cross-border load growth compress procurement cycles for dedicated high-voltage delivery points with redundant feeds. The Energy Market Authority's reliability frameworks mandate distribution automation upgrades that unbundle sensor packages from primary equipment contracts. Urban substation retrofit contracts concentrate in the western industrial corridor where hyperscale buyers bypass traditional utility intermediation.
Thailand
Bangkok Metropolitan Authority's smart city mandates and ERC reliability index enforcement drive distribution automation requirements down to 22 kV feeders. The regulation's SAIDI and SAIFI improvement targets force SCADA deployment and digital twin convergence atop existing infrastructure. Metropolitan secondary substation retrofits and provincial renewable integration zones are creating upgrade revenue streams without full asset replacement.
Philippines
Meralco's urban distribution networks and the 35 GW offshore wind pipeline generate demand for export cable systems and offshore substation platforms. The ERC's reliability indices mandate automation upgrades that domestic suppliers cannot yet fully deliver. Luzon's transmission backbone and Visayas interconnection projects are absorbing maintenance revenue from aging transformer fleets as utilities prioritize reliability compliance over greenfield capital.
Southeast Asia Power Transmission and Distribution Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology leaders anchoring HVDC and GIS procurement while localized fabricators capture transformer delivery timelines. The vendor base concentrates around three strategic archetypes: Japanese and Korean conglomerates with integrated heavy electrical divisions, European specialists leveraging HVDC technology leadership, and emerging Asian challengers scaling through manufacturing partnerships. Competitive positioning hardens through M&A activity targeting automation software capabilities and strategic partnerships securing localized production capacity for 500 kV equipment.
Among Japanese electrical conglomerates, Hitachi Energy, Toshiba Corporation, and Mitsubishi Electric Corporation exemplify the integrated heavy electrical archetype that dominates high-voltage infrastructure bidding. These companies occupy positions where technology leadership in converter stations and gas-insulated switchgear intersects with long-standing utility relationships across Indonesia, Vietnam, and Thailand. Their geographic origin and corporate structure signal deep vertical integration into core component manufacturing that sustains delivery reliability for archipelagic interconnection projects.
| Leading Market Players |
|---|
| Hitachi Energy |
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| LS Electric |
| CG Power and Industrial Solutions Limited |
| General Electric Company |
| Schneider Electric SE |
| Hyosung Heavy Industries |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Data center operators in Singapore and Johor contracting directly for dedicated 230 kV substations are compressing procurement timelines and forcing suppliers to absorb expedited delivery premiums, reshaping how transformer manufacturers structure contract pricing across the region.
Pricing Analysis
Premium pricing for compressed lead times dominates contract structures, with utilities paying surcharges for 500 kV transformer delivery acceleration while spot inventory of standard-rated units trades at modest discounts. Price differentiation separates IEC-certified equipment for Vietnam's EVN from CEA-validated alternatives for Indonesia's PLN, with dual-certification SKUs commanding modest premiums. Cost compression in copper-intensive conductor bundles is intensifying because raw material volatility destabilizes long-term offtake agreements. State-owned utilities exhibit lowest price sensitivity due to mandated reliability targets, while independent power producers in the Philippines' offshore wind pipeline drive hardest bargain on export cable systems.
Supply Chain Analysis
Specialized HVDC commissioning engineer pools concentrated in Germany, Japan, and South Korea constrain converter station ramp rates and extend project timelines for Indonesian archipelago interconnectors. Manufacturing draws from copper cathode supplies in Chile and Indonesia, electrical steel from Japan and South Korea, and SF6 gas from Chinese chemical processors. Single-source vulnerability sits with submarine cable fabrication capacity clustering in European and Northeast Asian facilities. Distribution runs through state-owned utility procurement frameworks in Indonesia, Vietnam, and Thailand, with secondary channels serving direct industrial contracting in Singapore's Tuas corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around technology leaders with captive HVDC and GIS capabilities, as copper price volatility and certification divergence force smaller transformer fabricators into margin compression or exit.
For Market Incumbents: Deepen backward integration into electrical steel and copper processing to insulate margins from raw material swings, while accelerating CEA-EVN harmonization lobbying to reduce duplicate validation costs. Anchor defensive positioning through long-term service contracts for aging transformer fleets across Thailand's metropolitan networks, locking out emerging competitors from recurring revenue pools. For New Entrants and Emerging Players: Local EPC contractors in Vietnam's north-south corridor and Indonesia's outer island electrification zones represent the most penetrable channel for equipment supply partnerships. Target white-space in digital twin software layered atop existing SCADA infrastructure, and in dry-type transformer retrofits for Jakarta's underground substation expansions where fire-code compliance creates specification openings. For Investors and Strategic Acquirers: The window for entry favors automation software specialists with grid modeling capabilities that incumbent heavy electrical conglomerates lack. Mid-term viability hinges on ASEAN Power Grid coordination accelerating cross-border transmission investment sequencing. Watch for PLN or EVN publishing unified type-test protocols as the inflection signal for reduced market fragmentation.| Strategic Initiative | Industry Significance |
|---|---|
| HVDC Technology Licensing | Enables European specialists to monetize converter station expertise across Indonesian island interconnections. |
| Localized Manufacturing Partnership | Sustains delivery timelines for 500 kV transformer contracts under Indonesia's CEA certification requirements. |
| Digital Twin Platform Integration | Creates upgrade revenue streams without full asset replacement in Thailand's ERC-mandated automation programs. |
| Submarine Cable Supply Agreement | Secures fabrication capacity for Philippines' 35 GW offshore wind pipeline export cable demand. |
| Fire-Safety Certification Program | Accelerates dry-type and gas-insulated transformer specification share under Indonesia's stricter codes. |
Research Methodology
Multi-period observation of utility capital expenditure disclosures, transformer procurement contract awards, and renewable integration milestone timelines anchored the trend analysis, supplemented by interviews with grid planning officers at PLN and EVN, EPC contractors active in Vietnam's north-south corridor, HVDC commissioning specialists, and distribution automation vendors. Secondary validation drew from ASEAN Power Grid coordination protocol documents, national renewable energy target filings, and equipment certification databases maintained by Indonesia's CEA and Vietnam's EVN. Bottom-up equipment shipment tracking and top-down utility investment forecasting were triangulated against cross-border transmission project announcements.
Segment-weighting applied voltage tier, insulation medium, and service lifecycle dimensions across the projection horizon, with technology deployment trajectories modeled separately for smart grid, SCADA, and conventional electromechanical systems. CAGRs were derived from equipment procurement cycle compression analysis and renewable intermittency management requirements. Grid stability modeling inputs and data center load growth velocity in Singapore, Indonesia, and Vietnam shaped demand-side assumptions.
Several conditions sit outside the modeled scope, including unannounced ASEAN Power Grid treaty revisions, abrupt copper price shocks exceeding historical volatility bands, and regulatory acceleration of offshore wind leasing beyond published seabed programs. Forecasts reflect documented assumptions about transmission right-of-way approval timelines and HVDC engineer availability. Material deviation in utility privatization timelines or CEA-EVN certification harmonization progress warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
High Temperature Overhead Conductor Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market