
 Germany DC Distribution Network Market | 2026-2036
Germany DC Distribution Network Market Size, Share, and Industry Trends Forecast 2026-2036
Germany DC Distribution Network Market Foresight
German electrical infrastructure manufacturers is recalibrating production schedules to match accelerating DC distribution orders from hyperscale data center builders. Siemens AG leverages its domestic manufacturing base to supply converter systems for industrial microgrids across Baden-Württemberg. ABB Ltd anchors its position through specialized distribution boards designed for renewable integration projects in northern Germany. Schneider Electric differentiates via monitoring solutions that comply with stringent national efficiency protocols.
A DC distribution network routes direct current power from generation or conversion points to end-use equipment through switchgear, busbars, and protection devices operating typically at 380V, 750V, or 1500V DC. These systems eliminate AC-DC conversion losses in data centers, electric vehicle charging stations, and photovoltaic installations where native DC sources predominate. Converter systems command the largest technology segment due to their role in voltage transformation and power quality management. Data centers represent the fastest-growing end user category as Frankfurt's cloud computing cluster demands higher energy density with lower thermal overhead. Energy storage integration is emerging as a margin-rich application segment, driven by grid stabilization requirements in renewable-heavy regions.
Germany's Federal Network Agency enforces grid connection standards that favor DC-compatible architectures in new industrial installations. The EU Ecodesign Directive and national implementation rules under the Bundesministerium für Wirtschaft und Klimaschutz mandate minimum efficiency thresholds for power conversion equipment. VDE certification requirements create compliance barriers for non-European suppliers while protecting domestic manufacturers. Stakeholders must track evolving F-Gas Regulation impacts on cooling-integrated DC systems and anticipate how the EU AI Act's infrastructure requirements will reshape power density specifications for edge computing deployments.
Market Dynamics
The Bundesministerium für Wirtschaft und Klimaschutz is tightening conversion efficiency mandates under Germany's Ecodesign Directive implementation, forcing industrial power infrastructure toward native DC architectures and eliminating legacy AC-DC conversion stages in new Bavarian and Baden-Württemberg installations.
Growth Catalysts
- EU Ecodesign Directive:Minimum efficiency thresholds for power conversion equipment mandate higher-performance DC architectures in new industrial builds across Germany's automotive corridor.
- Data center energy density requirements:Frankfurt's hyperscale cloud computing cluster demands thermal overhead reduction through elimination of AC-DC conversion losses.
- Photovoltaic proliferation:Native DC generation from rooftop solar in northern Germany creates pull for compatible distribution infrastructure without inversion stages.
Market Restraints
- Copper and rare earth input volatility:Converter system manufacturing faces raw material cost pressure from magnet and winding supply concentration in Asian processing centers.
- VDE certification barriers:Non-European suppliers encounter extended compliance timelines and testing costs that protect domestic incumbent manufacturers.
- Legacy AC infrastructure substitution:Existing industrial electrical systems in Germany's Mittelstand manufacturing base create high switching costs for DC retrofit.
Strategic Opportunities
- Energy storage integration:Grid stabilization requirements in renewable-heavy regions of northern Germany create margin-rich demand for battery-coupled DC distribution systems.
- Edge computing infrastructure:The EU AI Act's power density specifications for distributed computing nodes favor compact DC microgrids in urban edge locations.
- Electric vehicle charging corridors:Autobahn-adjacent industrial zones require high-capacity 750V and 1500V DC distribution for fleet charging infrastructure.
Industry Challenges
- Power electronics engineering scarcity:German technical universities produce insufficient specialists in wide-bandgap semiconductor applications for DC converter design.
- F-Gas Regulation compliance:Cooling-integrated DC systems face refrigerant phase-out timelines that complicate thermal management architecture decisions.
- Multi-vendor interoperability:Absence of unified communication protocols between Schneider, ABB, and Siemens control systems creates integration friction in mixed-facility deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany DC Distribution Network Market |
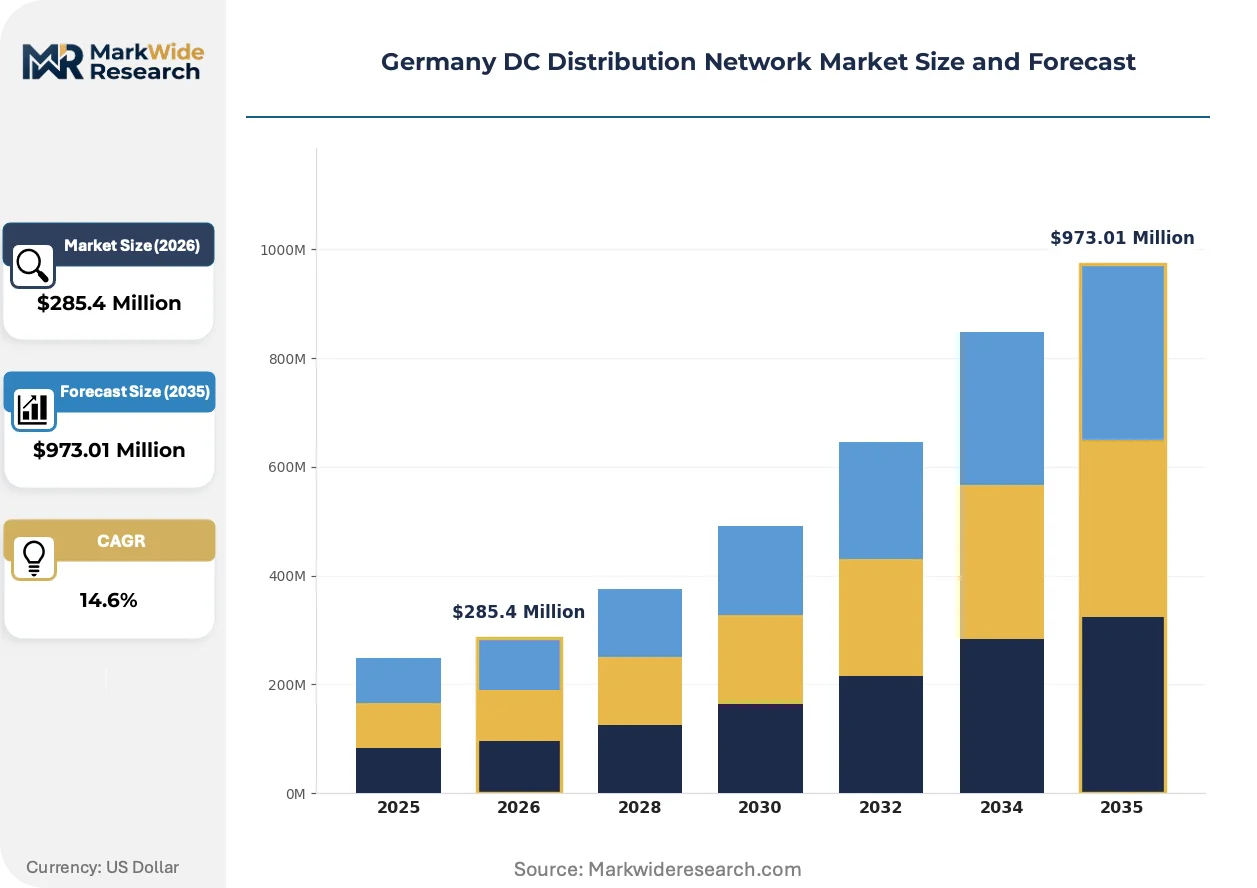
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $973.01 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Direct Current Supply, Technical Support, Maintenance, Consultation End User: Telecommunications, Data Centers, Industrial Facilities, Commercial Buildings Technology: Converter Systems, Distribution Boards, Energy Storage, Monitoring Solutions Application: Renewable Integration, Backup Power, Electric Vehicles, Power Distribution |
| Companies Covered | Vertiv Group Corp, Secheron SA, Siemens AG, Pareto Energy, Nextek Power Systems, ABB Ltd, Johnson Controls, Schneider Electric, Eaton Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany DC Distribution Network Market Shifts & Advancements
Solid-state power conversion and intelligent monitoring systems are compressing the technical and economic case for DC distribution in German industrial settings. Three developments are actively restructuring competitive positioning and procurement patterns.
Silicon carbide (SiC) and gallium nitride (GaN) semiconductor technology enables higher switching frequencies and reduced thermal losses in DC-DC converter stages. Automotive suppliers in Stuttgart's industrial zone are piloting 1500V SiC-based distribution for electric vehicle test facilities. This technology is expanding into data center power distribution units, compressing footprint requirements and enabling higher rack densities in Frankfurt facilities.
Germany's Federal Network Agency is enforcing grid connection standards under the Energiewende framework that favor DC-compatible architectures in new industrial installations. The Bundesnetzagentur's technical connection rules create compliance pathways bypassing traditional AC synchronization requirements for large-scale renewable coupling. Northern German wind-to-hydrogen projects are most affected, responding with direct DC coupling of electrolyzer stacks to offshore transmission infrastructure.
Hyperscale operators are consolidating vendor relationships and demanding integrated performance guarantees spanning conversion, distribution, and thermal management. Traditional equipment specification through separate electrical and mechanical contractors is yielding to single-source accountability contracts in Munich's emerging data center cluster. This concentration is most visible in Bavaria, where Microsoft and Google facility investments specify turnkey DC microgrid delivery with fifteen-year efficiency warranties.
Germany DC Distribution Network Market Segmentation
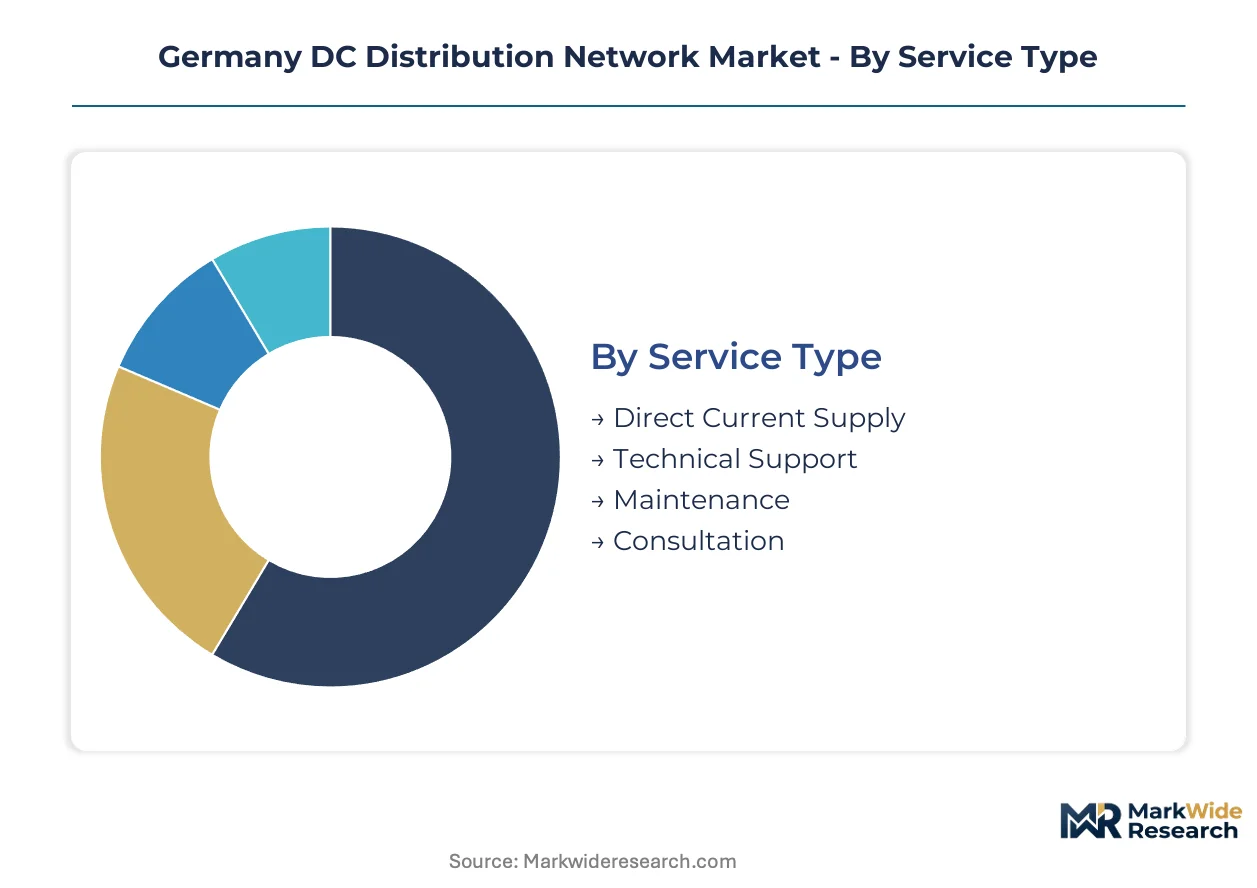
Segmentation reveals how DC distribution infrastructure aligns with distinct operational requirements across German industry. Each dimension exposes different procurement priorities, from technical service dependencies to end-use thermal constraints.
Service Type:
Standalone service engagements dominate large industrial retrofits, while embedded support packages accompany new hyperscale data center construction in Frankfurt and Munich.
- Direct Current Supply:Utility-scale power procurement agreements deliver 380V to 1500V DC feedstock for industrial microgrids. Bavarian automotive plants source dedicated DC supply contracts to bypass grid conversion losses.
- Technical Support:Engineering services cover converter commissioning, protection coordination, and arc flash mitigation. Frankfurt's cloud computing cluster drives 24/7 remote monitoring contracts with guaranteed response times.
- Maintenance:Predictive service programs using thermal imaging and contact resistance testing prevent busbar failures in semiconductor fabs. Baden-Württemberg industrial zones show highest contract penetration.
- Consultation:Front-end engineering studies address Ecodesign Directive compliance and VDE certification pathways. Northern Germany's renewable integration projects require specialized DC grid code advisory.
Volume placements concentrate in Direct Current Supply; the faster expansion belongs to Technical Support.
End User:
Cost tier segmentation separates mission-critical facilities willing to pay efficiency premiums from price-sensitive commercial installations.
- Data Centers:Hyperscale operators in Frankfurt's cloud corridor demand 750V rack-level distribution to eliminate AC-DC conversion stages. Microsoft's Bavarian facilities specify native DC architectures with fifteen-year efficiency warranties.
- Industrial Facilities:Stuttgart's automotive test centers and Wolfsburg manufacturing plants deploy 1500V SiC-based distribution for electric vehicle production lines. Process continuity requirements justify premium converter investments.
- Telecommunications:Edge computing nodes for 5G infrastructure use compact 380V DC microgrids. Urban deployment constraints favor modular, containerized systems.
- Commercial Buildings:Office and retail installations show slower DC adoption due to legacy AC lease structures and split incentive problems between landlords and tenants.
Revenue concentration sits with Data Centers; Industrial Facilities are climbing the fastest as automotive electrification accelerates.
Technology:
Margin structure varies sharply between commodity distribution hardware and software-integrated monitoring platforms.
- Converter Systems:Silicon carbide and gallium nitride semiconductor platforms enable 98%+ efficiency in DC-DC transformation stages. Siemens AG's domestic manufacturing base supplies Bavarian industrial microgrids with specialized units.
- Monitoring Solutions:Intelligent power management software with VDE-compliant efficiency reporting commands premium pricing. Schneider Electric differentiates through integrated analytics that track conversion losses across facility zones.
- Distribution Boards:Busbar and protection assemblies for 750V and 1500V installations require arc containment engineering. ABB Ltd anchors position through marine-certified units adapted for northern Germany's offshore wind coupling.
- Energy Storage:Battery-coupled DC distribution addresses grid stabilization in renewable-heavy regions. Northern German wind-to-hydrogen projects drive direct coupling of electrolyzer stacks to storage infrastructure.
Shipments concentrate in Converter Systems; Energy Storage is gaining share fastest on grid stabilization demand.
Application:
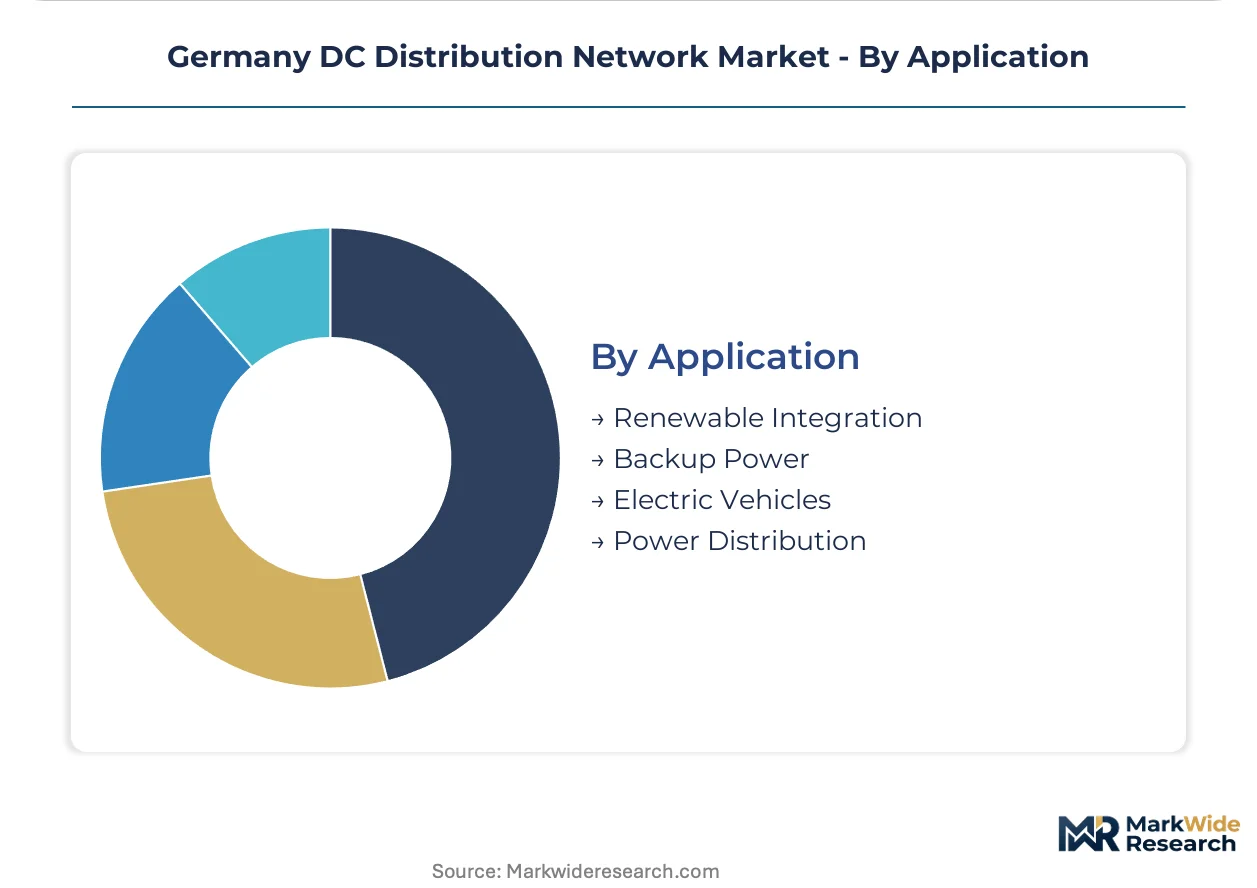
Application segmentation tracks how DC distribution embeds into broader energy system architectures versus standalone deployment.
- Renewable Integration:Direct coupling of photovoltaic arrays and offshore wind to DC distribution eliminates inversion losses. Northern Germany's wind-to-hydrogen clusters bypass AC synchronization through native DC architectures.
- Electric Vehicles:Fleet charging corridors along Autobahn-adjacent industrial zones require 750V and 1500V high-capacity distribution. Stuttgart's automotive suppliers pilot test facility electrification with dedicated DC feeders.
- Backup Power:Battery energy storage systems provide ride-through capability for semiconductor fabs and data centers. Bavarian installations specify sub-10ms transfer times for process continuity.
- Power Distribution:General industrial electrification using DC bus architectures remains nascent outside automotive and cloud computing verticals. Mittelstand manufacturers show retrofit hesitation due to switching costs.
Deployment volumes concentrate in Renewable Integration; Electric Vehicles shows the steepest expansion trajectory on charging infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare earth processing concentration in China's Inner Mongolia and Jiangxi provinces anchors converter magnet supply chains serving German DC distribution manufacturers. Frankfurt's hyperscale data center cluster and Stuttgart's automotive electrification corridor generate concentrated domestic demand.
Bavaria
Microsoft and Google facility investments specify turnkey DC microgrid delivery with fifteen-year efficiency warranties. The Bundesministerium für Wirtschaft und Klimaschutz enforces Ecodesign Directive implementation tightening conversion efficiency mandates. Munich's emerging data center cluster consolidates vendor relationships and demands integrated performance guarantees spanning conversion, distribution, and thermal management.
Baden-Württemberg
Automotive suppliers in Stuttgart's industrial zone pilot 1500V SiC-based distribution for electric vehicle test facilities. VDE certification requirements create compliance barriers protecting domestic manufacturers from non-European competition. Stuttgart's automotive test centers and Wolfsburg manufacturing plants deploy premium converter investments justified by process continuity requirements.
North Rhine-Westphalia
Industrial microgrid deployments concentrate in the Ruhr region's legacy manufacturing transformation. The Federal Network Agency enforces grid connection standards favoring DC-compatible architectures in new industrial installations. Düsseldorf and Cologne host engineering consultancies specializing in Ecodesign Directive compliance and VDE certification pathways.
Lower Saxony
Wind-to-hydrogen projects respond with direct DC coupling of electrolyzer stacks to offshore transmission infrastructure. The Energiewende framework's technical connection rules create compliance pathways bypassing traditional AC synchronization requirements. Northern German offshore wind clusters drive battery-coupled DC distribution for grid stabilization.
Hesse
Frankfurt's cloud computing cluster demands higher energy density with lower thermal overhead through native DC architectures. Hyperscale operators specify 750V rack-level distribution to eliminate AC-DC conversion stages. The Rhine-Main metropolitan area concentrates 24/7 remote monitoring contracts with guaranteed response times.
Germany DC Distribution Network Market Competitive Landscape
Global majors compete with regional champions across certification and efficiency warranty dimensions. Domestic incumbents leverage VDE certification timelines and testing cost structures that disadvantage non-European suppliers. Three archetypes dominate: integrated industrial conglomerates with captive converter manufacturing, specialized power electronics engineering houses, and energy infrastructure multinationals with monitoring software platforms. Competitive moves concentrate on strategic partnerships for turnkey microgrid delivery and portfolio diversification into energy storage integration.
Among Germany-based industrial conglomerates, Siemens AG exemplifies the integrated archetype with domestic manufacturing supplying Bavarian industrial microgrids. ABB Ltd and Schneider Electric represent multinational infrastructure specialists; ABB anchors position through marine-certified distribution units while Schneider differentiates via VDE-compliant efficiency reporting platforms. Secheron SA occupies a position within the specialized engineering tier focused on high-voltage DC protection systems.
| Leading Market Players |
|---|
| Vertiv Group Corp |
| Secheron SA |
| Siemens AG |
| Pareto Energy |
| Nextek Power Systems |
| ABB Ltd |
| Johnson Controls |
| Schneider Electric |
| Eaton Corporation |
| Others |
Supply & Pricing Matrix
Hyperscale operators' fifteen-year efficiency warranty demands are forcing converter manufacturers to absorb long-term performance risk, compressing upfront pricing while embedding predictive maintenance costs into bundled contracts. This procurement shift favors vertically integrated suppliers capable of warranting complete microgrid performance rather than component-only vendors.
Pricing Analysis
Warranty bundling separates turnkey DC microgrid providers from component-only suppliers, with the former capturing 40-60% service attach rates over fifteen-year terms. Price differentiation hinges on VDE certification tier and SiC semiconductor integration grade, with premium-tier converters commanding substantial efficiency guarantees. Cost compression in standard-grade distribution boards is intensifying due to Chinese converter competition in sub-750V segments. Mittelstand manufacturers show highest price sensitivity, while Frankfurt hyperscale operators prioritize efficiency warranties over unit economics.
Supply Chain Analysis
End-of-life converter refurbishment flows are emerging as a secondary supply channel, with ABB and Siemens operating dedicated remanufacturing facilities for busbar assemblies and protection modules. Magnet and winding production concentrates in China's Inner Mongolia and Jiangxi provinces, with German manufacturers drawing from Taiwanese semiconductor packaging for SiC devices. Single-source vulnerability in rare earth processing creates exposure to export restriction shocks. Distribution runs through authorized system integrators for industrial microgrids and direct OEM relationships for hyperscale data center projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race, with control over SiC semiconductor sourcing and captive converter manufacturing determining margin sustainability. Players are pursuing backward integration into wide-bandgap semiconductor supply to secure efficiency leadership.
For Market Incumbents: Acquire SiC wafer fabrication capacity or binding offtake agreements with Taiwanese foundries to defend against emerging Chinese converter entrants. Secure exclusive distribution partnerships with Frankfurt and Munich hyperscale developers before single-source accountability contracts lock out multi-vendor procurement. VDE certification investment remains essential for domestic market protection. For New Entrants and Emerging Players: The premium-to-economy tier price gap in 380V commercial building applications offers entry opportunity, as legacy AC lease structures delay DC adoption and incumbent attention concentrates on high-voltage industrial segments. Target edge computing nodes in urban 5G infrastructure, where compact modular systems face less entrenched competition. Pursue partnership-based go-to-market with German engineering consultancies holding Ecodesign Directive advisory relationships. For Investors and Strategic Acquirers: The window for entry favors specialized power electronics engineering houses with SiC converter design capabilities and existing VDE certification pathways. Long-term viability rests on regulatory tailwinds from EU efficiency mandates rather than cyclical infrastructure spending. Monitor F-Gas Regulation phase-out timelines as inflection indicator for cooling-integrated DC system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into SiC Semiconductor Supply | Captive wafer sourcing insulates converter margins from Chinese rare earth export volatility. |
| Turnkey Microgrid Performance Contracting | Fifteen-year efficiency warranties lock out component-only competitors from Frankfurt hyperscale procurement. |
| VDE Certification Acceleration Program | Fast-track compliance creates procurement advantage in Ecodesign Directive-mandated Bavarian industrial builds. |
| Energy Storage Integration Partnership | Battery-coupled DC distribution addresses grid stabilization demand in northern German wind-to-hydrogen clusters. |
| Predictive Maintenance Platform Deployment | Remote thermal monitoring and contact resistance analytics extend service revenue attach rates across Baden-Württemberg semiconductor fabs. |
Research Methodology
Trade association filings, Bundesnetzagentur grid connection rulemakings, and VDE certification registries formed the secondary backbone for market sizing and regulatory trajectory assessment. Primary interviews with data center engineering directors, industrial plant managers, converter system procurement leads, and power electronics R&D heads at German technical universities were combined with customs data on SiC semiconductor imports and bottom-up facility installation tracking across Frankfurt, Munich, and Stuttgart clusters. Triangulation across these sources validated segment-level demand assumptions.
Bottom-up modeling of individual hyperscale data center and automotive test facility DC microgrid deployments was cross-checked against top-down analysis of national Ecodesign Directive compliance spending and industrial efficiency investment trends. Segmentation dimensions included service type, end user vertical, converter technology tier, and application architecture. CAGRs were derived from facility pipeline analysis and regulatory mandate implementation schedules. Forecast inputs incorporated Energiewende grid connection rule evolution and EU AI Act power density specifications for distributed computing infrastructure.
Underlying measurement precision varies by segment; data center and automotive facility deployments carry tighter precision than commercial building retrofits due to disclosed procurement volumes. Forecasts reflect assumptions on Ecodesign Directive enforcement intensity and SiC semiconductor cost curves. Material deviation in F-Gas Regulation phase-out timelines or rare earth export restriction severity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Australia High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
High Temperature Overhead Conductor Market