
 Solar Containers Market | 2026-2036
Solar Containers Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Containers Market Analytics
Aftermarket service revenue is rewriting profit expectations across the solar containers sector. BoxPower Inc. leverages its rural electrification footprint to capture recurring maintenance contracts in off-grid territories. Trina Solar Limited anchors containerized module supply through its integrated photovoltaic manufacturing chain. Yangzhou CIMC New Energy Equipment Co., Ltd. dominates steel-hybrid enclosure fabrication with port-adjacent production assets.
Solar containers are standardized shipping-frame structures retrofitted with photovoltaic arrays, integrated inverters, and battery storage compartments, typically rated between 20 kilowatts and 2 megawatts for rapid site deployment. Their primary purpose is to deliver plug-and-play renewable generation without permanent civil works, serving mines, disaster zones, and grid-constrained industrial parks. Modular units command the widest addressable market because buyers scale capacity in 20-foot increments rather than committing to fixed megawatt blocks. Photovoltaic systems still occupy the largest technology share, though integrated battery storage is capturing margin expansion as lithium-ion costs compress and dispatchability premiums widen.
FDA equipment safety guidelines for field-deployed electrical enclosures intersect with EPA site remediation rules to shape product certification pathways in the United States. The EU Green Deal and CE marking requirements for machinery directive compliance are tightening material traceability and end-of-life recycling obligations for European deployments. Stakeholders must weigh regulatory divergence against platform standardization when configuring container fleets for cross-border mobility.
Market Dynamics
The EU Green Deal's embedded carbon thresholds are redirecting procurement toward containerized renewable systems that ship pre-certified, compressing traditional site-built solar timelines from months to days.
Growth Catalysts
- Mining Electrification:Remote extraction operators in sub-Saharan Africa and Latin America are deploying solar containers to displace diesel gensets where grid extension is economically unviable.
- CE Marking Pre-Certification:Machinery directive compliance allows European port-to-project logistics to bypass repetitive national approvals, accelerating cross-border fleet mobility.
- Lithium-Ion Cost Compression:Battery storage integration is capturing margin expansion as cell prices decline and dispatchability premiums widen in industrial parks.
Market Restraints
- Steel Price Volatility:Container chassis fabrication depends on hot-rolled coil input costs that fluctuate with Chinese export tariffs and scrap metal arbitrage.
- Port Concentration Risk:Hamburg and Rotterdam handle the majority of European solar container throughput, creating single-point-of-failure exposure for just-in-time project schedules.
- Fixed Megawatt Substitution:Traditional ground-mount arrays retain cost advantages for permanent installations where civil works timelines are acceptable.
Strategic Opportunities
- Disaster Response Contracts:FEMA and equivalent national emergency agencies are formalizing rapid-deployment renewable procurement frameworks for grid restoration scenarios.
- Industrial Retrofit Mandates:Germany's building energy efficiency regulations are forcing manufacturing parks to source plug-and-play generation without structural modification permits.
- Battery-Photovoltaic Convergence:Integrated DC-coupled architectures are eliminating AC conversion losses and reducing balance-of-system component counts.
Industry Challenges
- Multinational Certification Timelines:UL 1741-SA and IEC 61427-2 testing sequences for field-deployed electrical enclosures extend product launch windows by 8-14 months.
- Legacy Grid Integration Protocols:Distribution network operators in conservative jurisdictions demand customized protection settings that fragment firmware standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Containers Market |
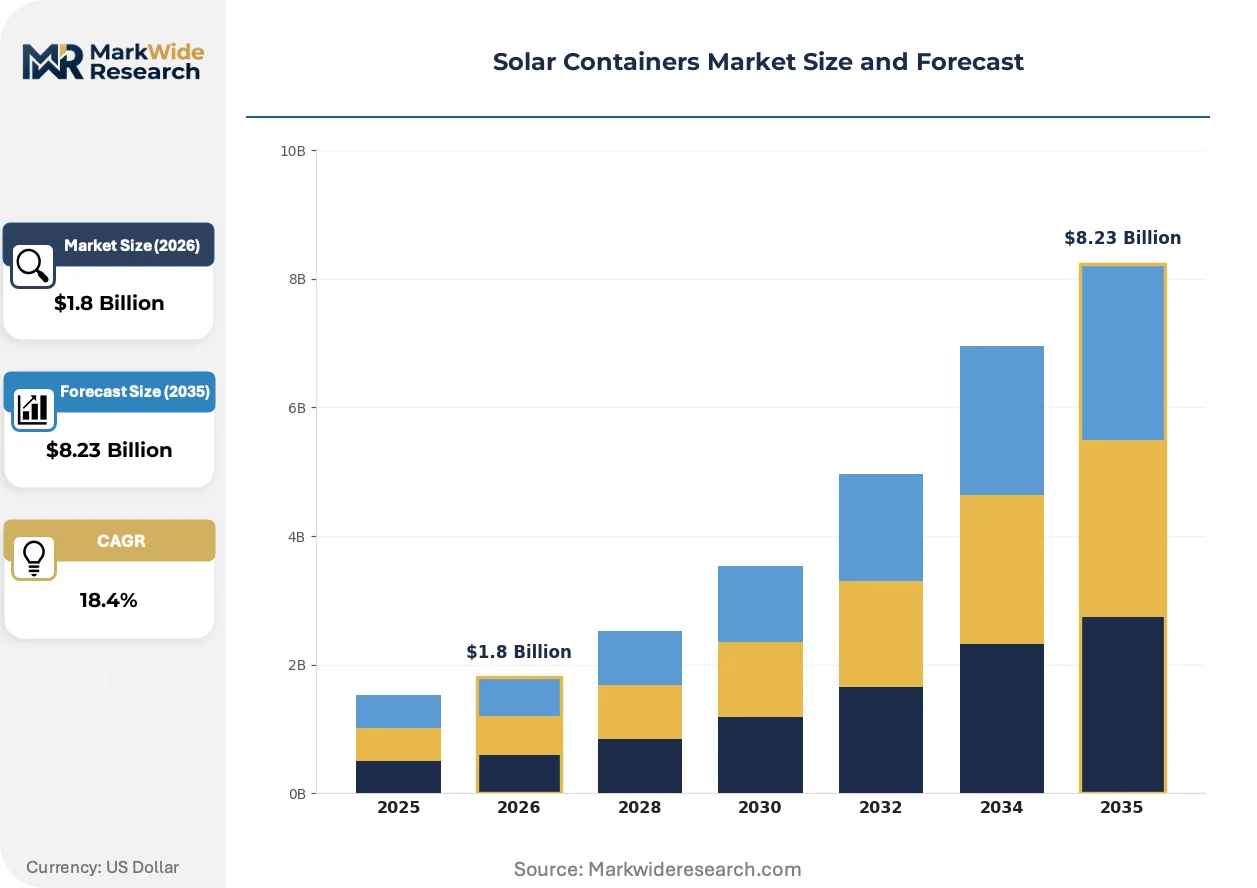
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.23 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Containers, Modular Units, Custom Containers, Mobile Containers Application: Commercial Use, Residential Use, Emergency Response, Off-Grid Solutions Technology: Photovoltaic Systems, Integrated Battery Storage, Hybrid Systems, Innovative Tracking End User: Government Agencies, NGOs, Construction Firms, Academic Institutions |
| Companies Covered | BoxPower Inc., Trina Solar Limited, Yangzhou CIMC New Energy Equipment Co., Ltd., Canadian Solar Inc., JinkoSolar Holding Co., Ltd., Ecosun Innovations, Hacon Containers, LONGi Green Energy Technology Co., Ltd., Faber Infrastructure GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Containers Market Evolving Landscape
Modular architecture is compressing project finance risk profiles by enabling phased capacity commitment rather than upfront megawatt-scale capital deployment.
Silicon carbide power electronics are replacing traditional IGBT inverters in high-temperature container environments. Mining operators in Western Australia are adopting these units for their reduced cooling loads and higher switching frequencies. This semiconductor transition is rendering obsolete air-cooled string inverter configurations that dominate legacy deployments.
REACH substance restrictions on flame-retardant additives are forcing enclosure manufacturers to reformulate insulation materials for European deployments. The industrial consequence is a bifurcation in bill-of-materials between EU-bound and export-oriented production lines. German steel-hybrid fabricators are responding with port-adjacent segregated assembly bays to maintain CE marking integrity.
Leasing structures are displacing outright purchase for solar container fleets in cash-constrained end-uses. Equipment finance providers are bundling maintenance and performance guarantees into power-purchase-equivalent contracts. This capital-light model is most visible in African off-grid mining camps where currency volatility discourages dollar-denominated asset ownership.
Solar Containers Market Segmentation
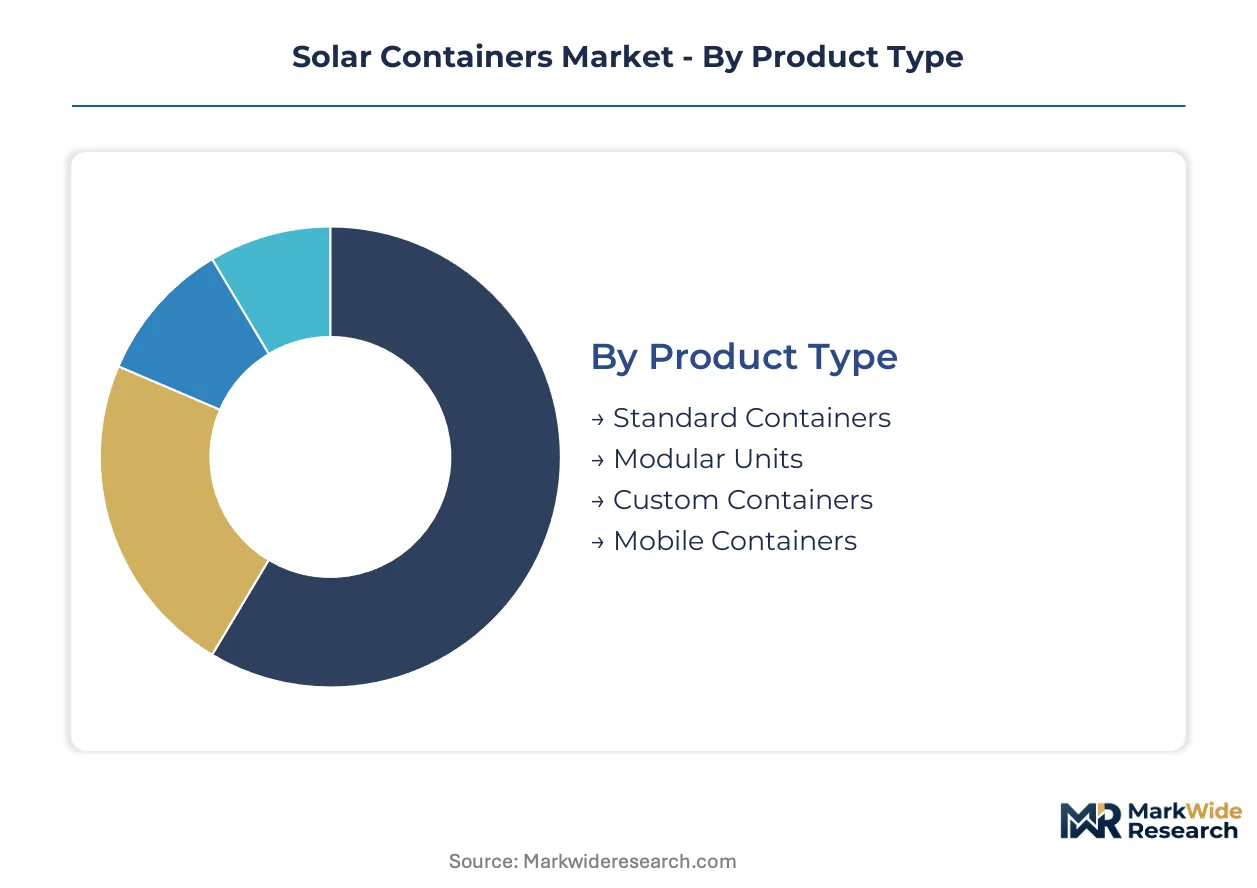
Solar container segmentation reveals divergent deployment velocities across product architectures and buyer categories. Cycle times range from same-day emergency mobilization to multi-month custom fabrication, compressing or extending capital recovery horizons accordingly.
Product Type:
Cycle times separate standardized offerings from engineered-to-order variants, with port inventory depth determining which segments turn fastest.
- Standard Containers:Pre-certified 20-foot and 40-foot units ship from Hamburg and Rotterdam stockyards within 72 hours. Mining operators in Western Australia and Chile favor these for diesel displacement projects where grid extension timelines are unacceptable.
- Modular Units:Scalable 20-kilowatt building blocks snap together without civil works, enabling phased capacity commitment. German manufacturing parks under building energy efficiency retrofit mandates source these to bypass structural modification permits.
- Custom Containers:Site-specific engineering extends lead times to 12-16 weeks for non-standard dimensions or climate ratings.
- Mobile Containers:Trailer-mounted configurations serve FEMA-style rapid deployment frameworks with highway-legal transport profiles.
Standard containers anchor the volume base while modular units gain share at the steepest rate.
Application:
Revenue concentration clusters where procurement bypasses traditional grid interconnection queues and permanent infrastructure approvals.
- Commercial Use:Industrial parks and mine sites deploy containerized generation to meet Scope 2 emissions targets without construction permits. EU Green Deal embedded carbon thresholds accelerate procurement for pre-certified systems that ship port-to-project.
- Emergency Response:FEMA and equivalent national agencies formalize renewable procurement frameworks for grid restoration, with silicon carbide inverter variants reducing cooling loads in high-temperature field conditions.
- Residential Use:Limited adoption due to rooftop solar cost advantages and zoning restrictions on ground-mounted container placement.
- Off-Grid Solutions:African mining camps and Latin American extraction sites displace diesel gensets where currency volatility favors leasing over dollar-denominated asset ownership.
Commercial use dominates current revenue while emergency response contracts expand most quickly as disaster agencies institutionalize rapid-deployment protocols.
Technology:
Margin profiles diverge sharply between commodity photovoltaic supply and integrated storage architectures capturing dispatchability premiums.
- Photovoltaic Systems:Containerized module arrays without storage remain the lowest-cost configuration. Trina Solar and integrated manufacturers anchor supply through captive cell production, though price compression limits margin expansion.
- Integrated Battery Storage:DC-coupled lithium-ion architectures eliminate AC conversion losses and reduce balance-of-system component counts. Lithium-ion cost compression widens dispatchability premiums in industrial parks with time-of-use rate structures.
- Hybrid Systems:Diesel-solar container combinations serve transitional electrification in remote extraction sites.
- Innovative Tracking:Single-axis and dual-axis tracking mechanisms increase yield density for space-constrained deployments.
Photovoltaic systems retain the widest installed base while integrated battery storage climbs the fastest as cell economics improve and grid services monetize.
End User:
Procurement sophistication varies from performance-guaranteed power purchase structures to grant-dependent deployment schedules.
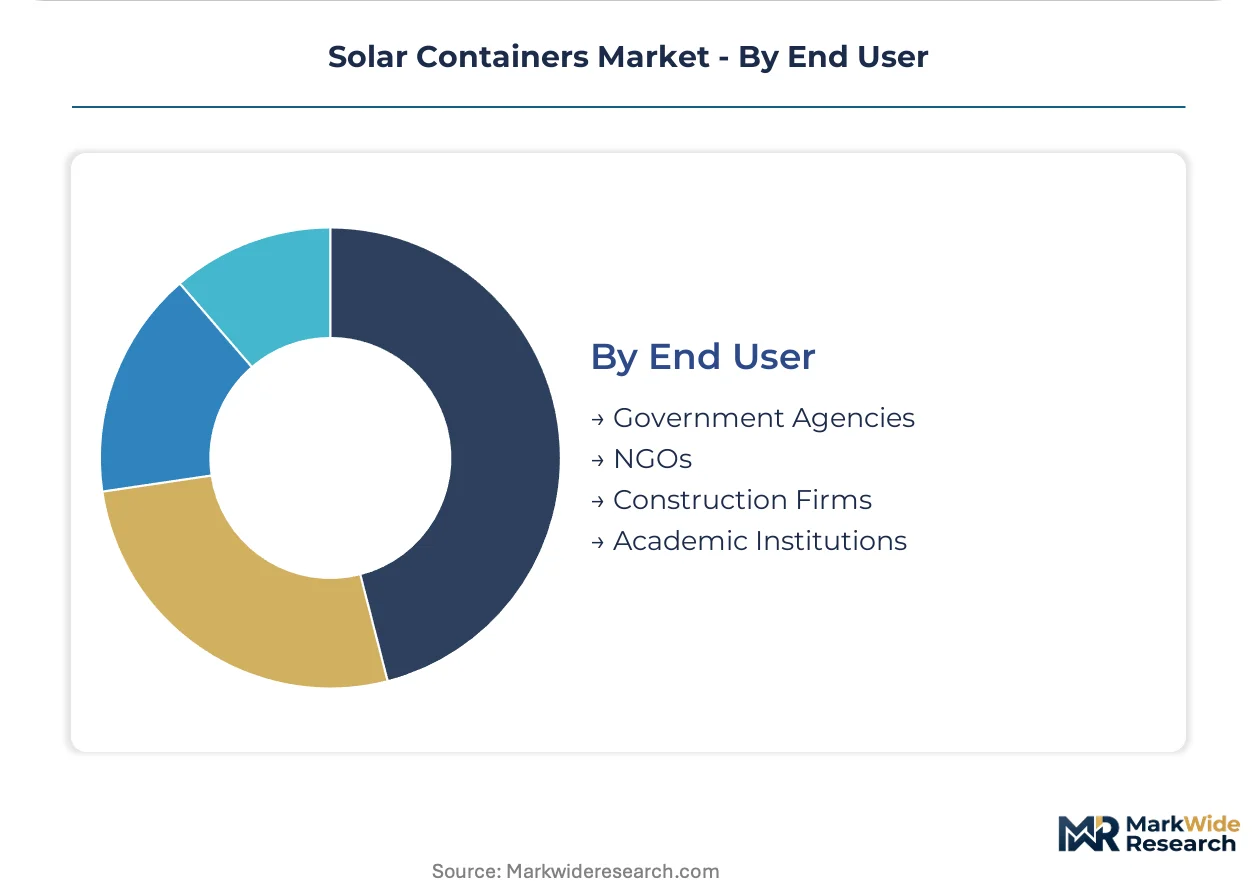
- Government Agencies:Defense and civilian emergency management departments specify MIL-STD or equivalent ruggedization with multi-year maintenance contracts. CE marking pre-certification enables European cross-border fleet mobility without repetitive national approvals.
- Construction Firms:Temporary power for remote infrastructure projects drives rental-heavy demand with 6-18 month deployment horizons.
- NGOs:Rural electrification programs in sub-Saharan Africa and island nations depend on development finance timelines with extended procurement cycles.
- Academic Institutions:Research and demonstration projects generate small-batch orders with customized monitoring and data acquisition requirements.
Government agencies anchor procurement volume while construction firms represent the most rapidly expanding buyer category as infrastructure investment accelerates in resource extraction corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and the Netherlands absorb premium pricing for CE-marked pre-certification, while African mining camps and Latin American extraction sites prioritize lease-based structures to dodge currency volatility.
Germany
Industrial retrofit mandates under the Building Energy Act are forcing manufacturing parks toward plug-and-play generation without structural modification permits. The EU Green Deal's embedded carbon thresholds accelerate port-to-project procurement of pre-certified systems. Hamburg anchors European throughput with stockyards shipping standardized units within 72 hours.
United States
FEMA and defense agencies are formalizing rapid-deployment renewable procurement frameworks for grid restoration scenarios. FDA equipment safety guidelines for field-deployed electrical enclosures intersect with EPA site remediation rules to shape certification pathways. Silicon carbide inverter adoption concentrates in Western Australian mining camps serving US equipment suppliers.
Chile
Remote copper and lithium extraction operators deploy solar containers to displace diesel gensets where grid extension timelines are unacceptable. The national mining regulator's decarbonization protocols favor pre-certified equipment imports over site-built alternatives. Antofagasta and the Atacama Desert host the densest concentration of diesel displacement projects.
Australia
Western Australian iron ore and gold mining corridors represent the fastest-expanding buyer segment for deployable solar infrastructure. The country's Clean Energy Regulator administers carbon credit frameworks that improve project finance viability for off-grid deployments. Perth serves as the logistics hub for sub-Saharan African and Southeast Asian re-export.
South Africa
Platinum and manganese extraction sites in the Northern Cape and Limpopo provinces lease containerized systems to avoid dollar-denominated asset ownership amid rand volatility. The national energy regulator's embedded generation licensing reforms compress approval timelines for sub-10-megawatt installations. Richards Bay and Durban handle the majority of import throughput for southern African redistribution.
Solar Containers Market Competitive Landscape
Integrated photovoltaic manufacturers and steel-hybrid enclosure fabricators split the market between module supply dominance and port-adjacent production assets. The vendor base organizes around three strategic archetypes: captive cell producers leveraging backward integration into wafer supply, port-proximate fabricators optimizing logistics velocity, and rural electrification specialists capturing recurring maintenance contracts. Competitive moves concentrate on CE marking pre-certification for European fleet mobility and lithium-ion cost compression for dispatchability premium capture.
Among integrated manufacturers, Trina Solar Limited and LONGi Green Energy Technology Co., Ltd. exemplify the captive-production archetype with in-house cell fabrication. Yangzhou CIMC New Energy Equipment Co., Ltd. occupies a position within the port-proximate fabrication tier. BoxPower Inc. represents the service-anchored model with its rural electrification footprint. These three company structures illustrate how competitive positioning diverges between upstream supply control, logistics optimization, and aftermarket service capture.
| Leading Market Players |
|---|
| BoxPower Inc. |
| Trina Solar Limited |
| Yangzhou CIMC New Energy Equipment Co., Ltd. |
| Canadian Solar Inc. |
| JinkoSolar Holding Co., Ltd. |
| Ecosun Innovations |
| Hacon Containers |
| LONGi Green Energy Technology Co., Ltd. |
| Faber Infrastructure GmbH |
| Others |
Value Network & Pricing Analysis
Chinese hot-rolled coil export tariff exposure determines both tier spreads between CE-marked and uncertified units and the geographic shape of container chassis sourcing. Steel price volatility feeds directly into fabrication cost structures, compressing margins for port-adjacent fabricators while rewarding backward-integrated producers with captive metallurgical supply.
Pricing Analysis
Aftermarket service revenue tiers—spanning parts replacement, preventive maintenance, and performance-guaranteed power contracts—drive lifetime value capture for fleet operators. Three-tier pricing structure across premium CE-marked, standard pre-certified, and economy export-oriented levels separates buyers by certification grade and bundled service depth. Cost compression in battery-integrated configurations is intensifying because lithium-ion cell economics improve faster than module price declines. Mining operators in currency-volatile jurisdictions exhibit highest price sensitivity, while German industrial parks under retrofit mandates show lowest sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Extended payment terms from equipment finance providers and supply-chain finance facilities are reshaping working capital requirements for port-proximate fabricators. Manufacturing gravity centers on China for steel-hybrid enclosures, Germany for CE-marked final assembly, and South Korea for silicon carbide power electronics. Raw material dependencies draw from Australian iron ore, Chilean copper, and Chinese processed lithium. Single-source vulnerability concentrates in Hamburg and Rotterdam port throughput for European distribution. Distribution runs through EPC contractors for mining deployments and direct manufacturer relationships for emergency response agencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Solar containers represent a high-growth infrastructure disruption as EU Green Deal embedded carbon thresholds eliminate site-built solar timelines. The regulatory inflection compresses procurement cycles from months to days for pre-certified systems.
For Market Incumbents: Insulate margin position by deepening backward integration into wafer supply and securing dedicated port-adjacent assembly bays for CE marking integrity. Steel price volatility and emerging silicon carbide inverter specialists threaten traditional air-cooled string configurations. Certification investment in UL 1741-SA and IEC 61427-2 parallel testing sequences defends against multinational launch delays.
For New Entrants and Emerging Players: Sub-Saharan African mining corridors beyond South Africa's established channels offer the most penetrable white-space for lease-based fleet deployment. Latin American extraction sites in Peru and Brazil lack established solar container maintenance networks. Target disaster response procurement frameworks as the go-to-market angle, leveraging highway-legal mobile configurations for FEMA-style rapid deployment protocols.
For Investors and Strategic Acquirers: EU Green Deal enforcement milestones reshape the acquisition landscape toward port-proximate fabricators with segregated CE-marking assembly capabilities. Long-term viability hinges on lithium-ion cost compression sustaining dispatchability premium capture across industrial park time-of-use structures. Target steel-hybrid enclosure specialists with integrated photovoltaic module relationships. The signal to watch is embedded carbon threshold tightening accelerating pre-certified procurement share.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pre-Certification Investment | Enables Hamburg and Rotterdam stockyards to ship standardized units within 72 hours. |
| Backward Integration into Silicon Carbide Supply | Reduces cooling loads for Western Australian mining camps adopting high-temperature inverters. |
| Leasing Structure Development | Bundles maintenance contracts for African mining camps avoiding dollar-denominated asset ownership. |
| Port-Adjacent Segregated Assembly Expansion | Maintains CE marking integrity under REACH substance restrictions on flame-retardant additives. |
| Disaster Response Framework Partnership | Positions mobile container fleets for FEMA and equivalent national emergency agency procurement. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with solar container manufacturers, EPC contractors, mining procurement officers, and port logistics operators; and secondary validation against customs trade records, EU Green Deal implementation directives, and IEA distributed generation databases. Bottom-up triangulation across project deployment databases and top-down reconciliation against steel-hybrid enclosure production capacity anchored volume estimates.
Forecast inputs considered module cost trajectories, lithium-ion cell price compression rates, and CE marking adoption velocity across the projection horizon. Segmentation dimensions modeled include product architecture, application category, technology integration level, and end-user procurement sophistication. CAGRs derived from weighted capacity deployment curves and replacement cycle assumptions for diesel genset displacement in remote extraction sites.
Practitioners should monitor Chinese hot-rolled coil tariff adjustments and REACH substance restriction expansions for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
China Electric Vehicle Battery Separator Market
Battery Infrastructure
Advance Battery Technologies Market
Battery Infrastructure
Automatic Battery Manufacturing Equipment Market
Battery Infrastructure
North America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Global Battery Technology Market
Battery Infrastructure
United States Battery Manufacturing Equipment Market
Battery Infrastructure
United States Electric Vehicle Battery Separator Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Substation Battery Market
Battery Infrastructure
China Battery Manufacturing Equipment Market