
 Africa High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market Outlook
Direct procurement channels between utilities and original equipment manufacturers is narrowing as African power pools consolidate tendering through regional bodies. Siemens AG leverages its converter technology leadership to anchor projects in the Horn of Africa, while Hitachi Energy Ltd competes on modular Voltage Source Converter platforms suited to variable renewable integration. Prysmian SpA specializes in submarine and underground cable systems that sustain interconnector reliability across challenging terrain.
Africa High-Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity across long distances with lower losses than alternating current alternatives, typically operating at voltages exceeding 100 kV and utilizing thyristor or insulated-gate bipolar transistor switching technologies. These systems primarily serve to interconnect asynchronous grids, integrate remote renewable generation, and stabilize weak networks across vast continental geography. Voltage Source Converter technology leads new installations due to superior black-start capability and compact footprint, while Line Commutated Converter systems retain cost advantages in ultra-high-capacity bulk transmission corridors where mature thyristor designs suffice. Multi-Terminal System configurations represent the fastest-growing architecture as regional power pools in East and Southern Africa pursue meshed HVDC networks enabling bidirectional power flows between multiple injection points.
South Africa's National Energy Regulator, Ethiopia's Ethiopian Energy Authority, and Kenya's Energy and Petroleum Regulatory Authority each enforce grid codes and connection standards that determine converter station specifications and interconnection protocols for cross-border projects. Compliance with these national frameworks shapes vendor qualification requirements and extends project development timelines. Stakeholders must monitor how harmonization of technical standards across the Eastern Africa Power Pool and Southern African Power Pool reshapes procurement rules and equipment certification pathways.
Market Dynamics
Voltage Source Converter technology is compressing project timelines across East African power pools, enabling utilities to integrate variable renewable generation without synchronous inertia requirements that constrain traditional Line Commutated Converter architectures.
Growth Catalysts
- Ethiopia's renewable export strategy:The Ethiopian Energy Authority fast-tracks cross-border transmission permits to monetize surplus hydropower through the Eastern Africa Power Pool, creating immediate demand for bidirectional converter stations.
- IRP grid modernization mandates:South Africa's Integrated Resource Plan mandates transmission expansion corridors that prioritize HVDC backbones for long-distance bulk transfer from northern solar zones to industrial load centers in Gauteng.
- Lake Turkana Wind Power integration:Kenya's 310 MW wind corridor requires HVDC collection systems to stabilize frequency excursions across the 428-kilometer route to Nairobi, driving procurement of compact modular converter platforms.
Market Restraints
- Converter station capital intensity:Voltage Source Converter valve halls require insulated-gate bipolar transistor stacks that cost 40-60% more per megawatt than mature thyristor assemblies, constraining utility budgets in fiscally constrained markets.
- Specialized labor scarcity:Commissioning engineers capable of tuning phase-locked loop controls for weak-grid connections concentrate in European and East Asian supplier hubs, extending mobilization timelines for African projects.
- Spare parts supply concentration:Critical power semiconductor modules ship from fabrication facilities in Germany and Japan, exposing projects to extended lead times and currency volatility that disrupt construction schedules.
Strategic Opportunities
- Meshed multi-terminal architectures:The Southern African Power Pool is advancing technical studies for three-node HVDC networks connecting South Africa, Mozambique, and Zimbabwe that would enable dynamic power routing based on real-time marginal costs.
- Submarine cable corridors:Prysmian and Nexans are pre-qualifying 525 kV extruded insulation systems for subsea interconnectors across the Mozambique Channel that would link Southern and Eastern African power pools.
- Green hydrogen export hubs:Namibia and Morocco are designing dedicated HVDC feeders to supply 24/7 renewable power to electrolyzer complexes, creating anchor demand for high-capacity transmission corridors with guaranteed offtake.
Industry Challenges
- Grid code harmonization delays:Divergent fault-ride-through requirements between Kenya's Energy and Petroleum Regulatory Authority and South Africa's National Energy Regulator force vendors to engineer country-specific control software, duplicating validation costs.
- Converter transformer lead times:Core-type transformers with DC bias mitigation require specialized magnetic steel grades that face 18-24 month delivery schedules, synchronizing poorly with renewable generation commissioning targets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa High-Voltage Direct Current (HVDC) Transmission Systems Market |
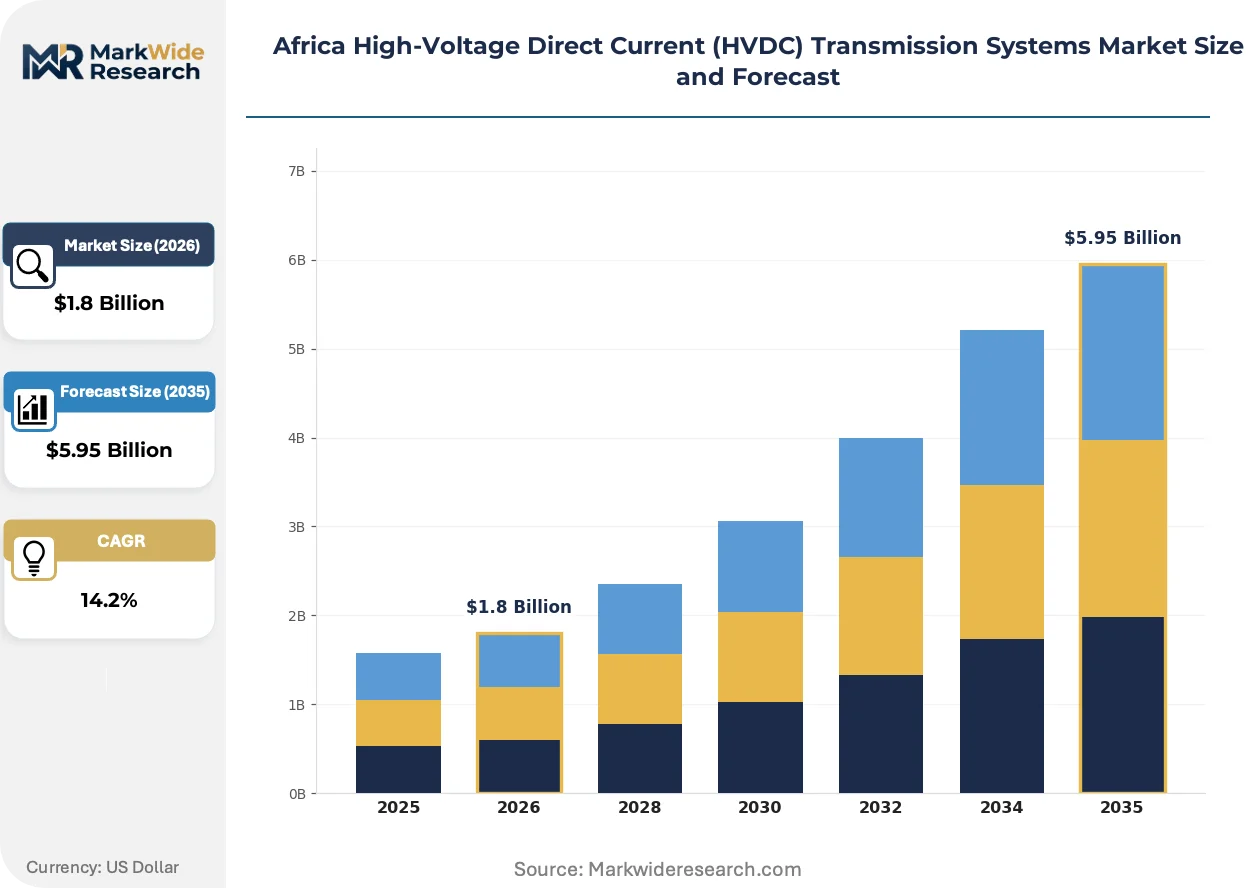
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Line Commutated Converter, Voltage Source Converter, Hybrid Converter, Multi-Terminal System Application: Renewable Integration, Bulk Power Transmission, Interconnection, Offshore Wind End User: Utilities, Independent Power Producers, Industrial Consumers, Government Entities Installation Type: Onshore, Offshore, Underground, Embedded |
| Companies Covered | Toshiba Corporation, Prysmian SpA, ABB Ltd, LS Industrial Systems Co Ltd, Hitachi Energy Ltd, Siemens AG, Mitsubishi Electric Corporation, Schneider Electric SE, General Electric Company, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market Strategic Shifts
Modular converter platforms are compressing the minimum efficient scale for HVDC deployment, allowing utilities to stage investments in 200-400 MW increments rather than committing to multi-gigawatt corridors upfront.
Hybrid HVDC-AC substation designs are hybridizing at Ethiopia's Grand Renaissance Dam export terminals, where Voltage Source Converter stations share site infrastructure with conventional 500 kV AC switchyards to reduce land acquisition costs and accelerate permitting. Ethiopian Electric Power is adopting this architecture for the 2,000 MW Sudan export corridor. The approach is compressing total installed cost per megawatt by 12-15% compared to greenfield AC-DC conversion sites.
Kenya's Energy and Petroleum Regulatory Authority revised interconnection standards in 2023 to mandate black-start capability for all cross-border converter stations, effectively disqualifying Line Commutated Converter bids from new tenders. The rule change is accelerating Voltage Source Converter adoption across the Eastern Africa Power Pool. Developers in Tanzania and Uganda are now specifying full-formerless converter transformers to meet the same standard preemptively.
Regional power pools are consolidating tendering through centralized procurement bodies rather than bilateral utility negotiations, concentrating buyer power and compressing supplier margins. The Eastern Africa Power Pool's single-window tender system for the Ethiopia-Kenya interconnector extension eliminated duplicate feasibility studies and synchronized environmental approvals across both jurisdictions. This model is displacing the fragmented procurement patterns that previously delayed the Lake Turkana corridor by four years.
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
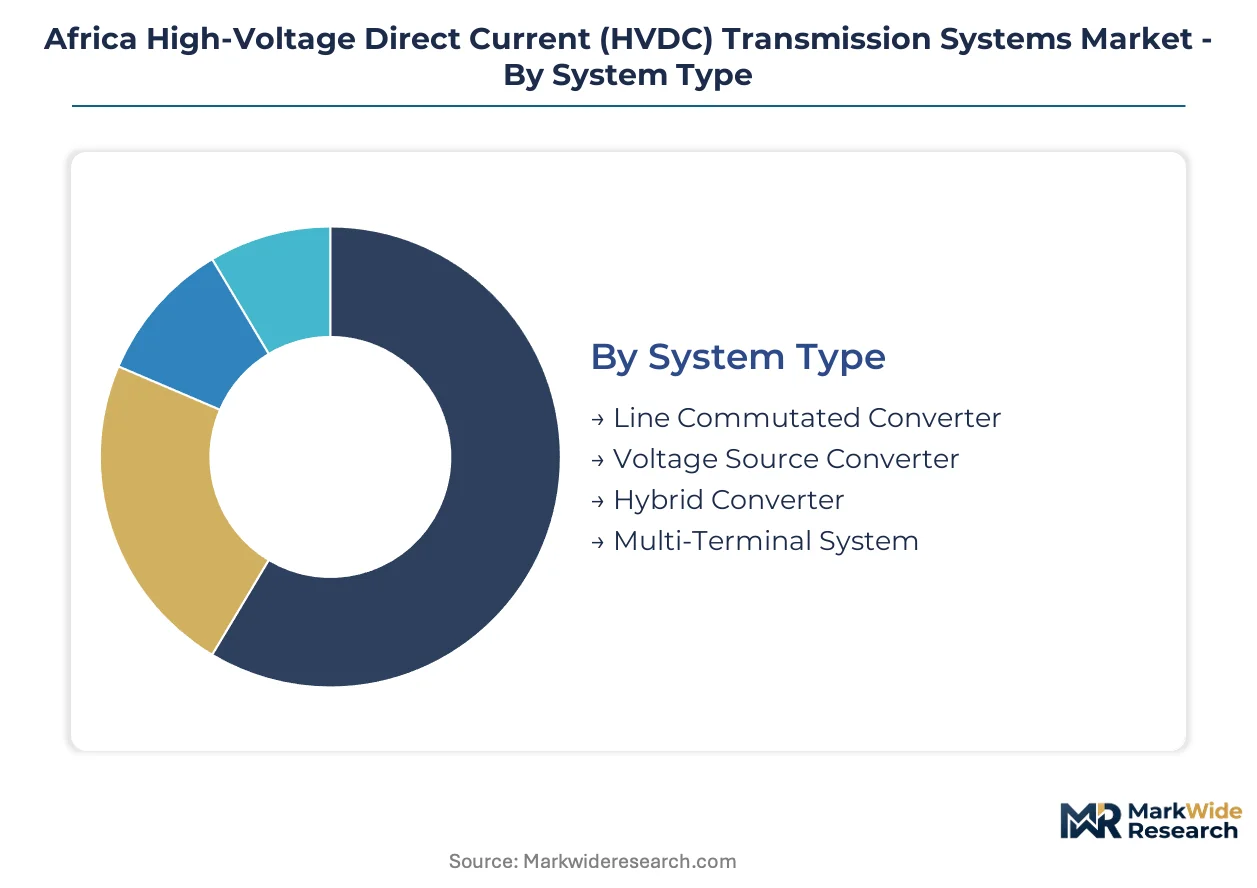
HVDC procurement across Africa fragments across converter technologies, grid applications, and installation environments. Each segment carries distinct capital cycles, technical requirements, and regulatory compliance pathways that shape vendor selection and project economics.
System Type:
Voltage Source Converter platforms turn over fastest as utilities prioritize black-start capability and compact footprints, while Line Commutated Converter systems persist in mature bulk corridors with longer replacement cycles.
- Voltage Source Converter:Insulated-gate bipolar transistor switching enables independent reactive power control and weak-grid stability without synchronous inertia. Kenya's Energy and Petroleum Regulatory Authority mandates this technology for all cross-border stations, concentrating procurement around modular 200-400 MW platforms.
- Line Commutated Converter:Thyristor-based designs deliver cost efficiency in ultra-high-capacity corridors exceeding 1,000 MW where grid strength is assured. Ethiopia's Grand Renaissance Dam export terminals to Sudan deploy mature thyristor assemblies for their proven reliability in high-inertia transmission.
- Hybrid Converter:Combines thyristor economy with IGBT flexibility for corridors transitioning between strong and weak grid zones.
- Multi-Terminal System:Meshed architectures enabling three-node networks across the Southern African Power Pool.
Line Commutated Converter anchors the volume base while Voltage Source Converter gains share at the steepest rate.
Application:
Application segmentation maps directly to Africa's generation geography—remote renewable zones, industrial load centers, and asynchronous national grids each demand tailored converter specifications.
- Renewable Integration:Frequency stabilization for variable wind and solar injection across weak rural networks. Lake Turkana Wind Power's 310 MW corridor requires dedicated HVDC collection to manage voltage excursions over 428 kilometers of transmission.
- Bulk Power Transmission:Long-distance transfer from generation basins to demand centers with minimal losses. South Africa's Integrated Resource Plan prioritizes northern solar zones feeding Gauteng industrial complexes through dedicated HVDC spines.
- Interconnection:Cross-border asynchronous grid linking between national utilities under power pool frameworks.
- Offshore Wind:Submarine cable systems for coastal generation not yet deployed at scale in African waters.
Bulk Power Transmission carries the heaviest capital deployment while Renewable Integration expands most quickly as wind and solar procurement accelerates.
End User:
End user categories reflect divergent risk appetites and financing capacities—utilities dominate sovereign-guaranteed projects while independent producers seek merchant transmission structures.
- Utilities:State-owned transmission operators with preferential access to multilateral development financing. Ethiopian Electric Power and Kenya Electricity Transmission Company anchor regional procurement through Eastern Africa Power Pool consolidated tendering.
- Independent Power Producers:Renewable developers requiring dedicated export corridors with guaranteed transmission access rights.
- Industrial Consumers:Mining and smelting operations negotiating private offtake agreements for remote generation.
- Government Entities:Direct infrastructure investment for strategic energy security objectives.
Utilities command the installed base while Independent Power Producers drive the steepest procurement expansion through renewable auction programs.
Installation Type:
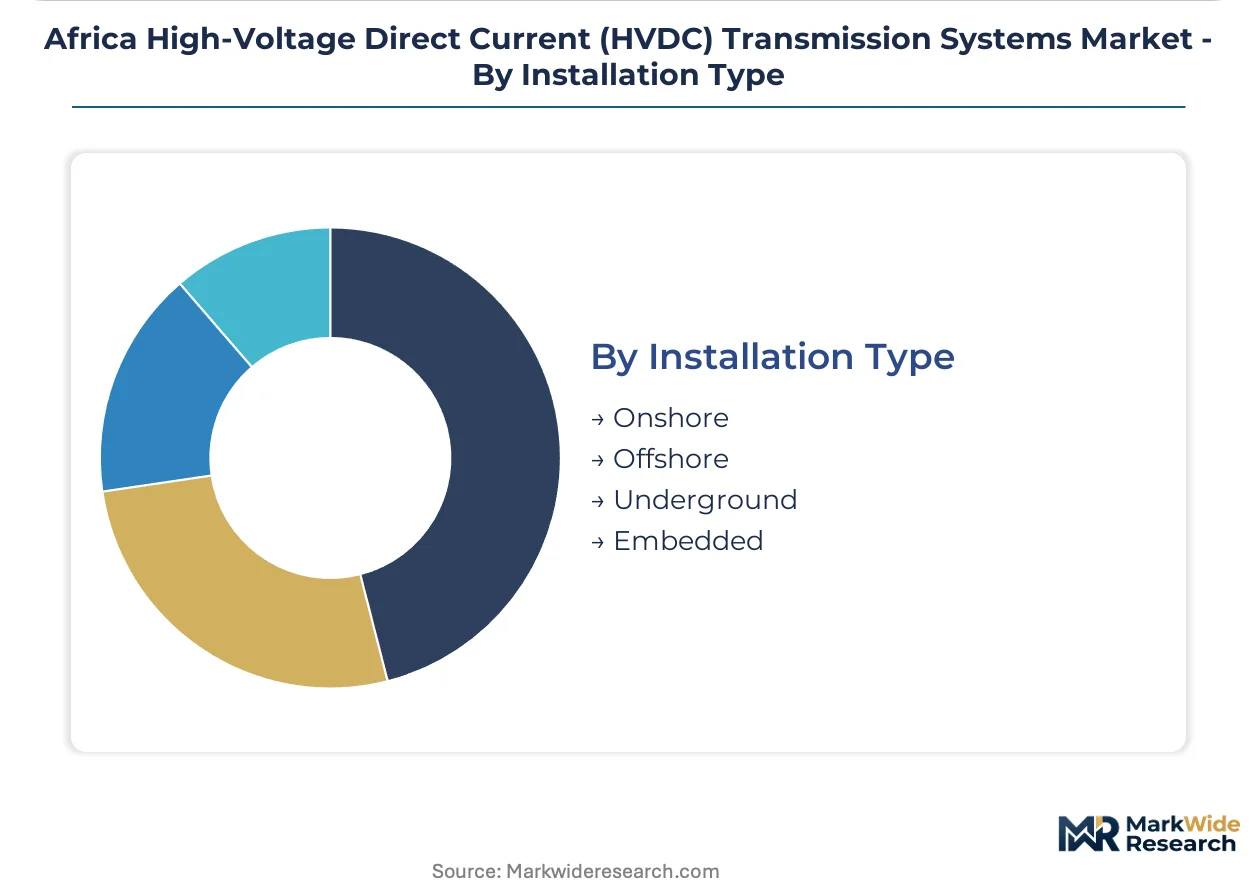
Installation environments determine cable technology selection and civil engineering intensity—onshore corridors dominate current deployment while offshore and underground options expand route flexibility.
- Onshore:Overhead line corridors across savanna and semi-arid terrain with minimal vegetation clearance requirements. Ethiopia-Kenya interconnector extensions traverse Rift Valley topography with standard lattice tower construction.
- Underground:Urban ingress routes and environmentally sensitive passages requiring extruded insulation systems. Nairobi load center connections specify 525 kV underground segments to bypass dense settlement zones.
- Offshore:Submarine cable corridors across the Mozambique Channel linking Southern and Eastern African power pools.
- Embedded:Converter stations integrated within existing substation infrastructure to reduce land acquisition.
Onshore installations anchor the volume base while Underground gains share at the steepest rate as urban congestion and environmental permitting tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Ethiopian converter station procurement while Kenyan utilities absorb technology premiums for black-start compliant systems. South Africa leverages domestic manufacturing scale to compress supplier margins on large-scale projects. Regional procurement consolidation through power pools is compressing margins for vendors serving smaller national markets.
Ethiopia
Grand Renaissance Dam export terminals drive demand for ultra-high-capacity thyristor assemblies in the Sudan corridor. The Ethiopian Energy Authority fast-tracks cross-border transmission permits to monetize surplus hydropower through the Eastern Africa Power Pool. The Renaissance Dam complex anchors procurement concentration for 2,000 MW export infrastructure.
South Africa
Northern solar zones feeding Gauteng industrial complexes require dedicated HVDC spines under Integrated Resource Plan mandates. The National Energy Regulator enforces grid codes that determine converter station specifications for cross-border projects. Eskom's transmission division concentrates procurement activity around the industrial load centers of Johannesburg and Pretoria.
Kenya
Lake Turkana Wind Power's 310 MW corridor requires dedicated HVDC collection systems to manage voltage excursions over 428 kilometers. The Energy and Petroleum Regulatory Authority revised interconnection standards in 2023 to mandate black-start capability for all cross-border converter stations. Nairobi load center connections specify 525 kV underground segments to bypass dense settlement zones.
Tanzania
Developers are specifying full-formerless converter transformers to meet Kenyan black-start standards preemptively for future interconnector projects. The country's national energy regulator harmonizes technical standards with the Eastern Africa Power Pool framework. Dar es Salaam serves as the coordination hub for regional grid integration studies.
Mozambique
Submarine cable corridors across the Mozambique Channel would link Southern and Eastern African power pools through 525 kV extruded insulation systems. The national electricity utility participates in Southern African Power Pool technical studies for three-node HVDC networks. Maputo functions as the strategic coordination point for cross-channel interconnector planning.
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Environment
Converter technology specialists and integrated electrical equipment conglomerates split the market based on project scale and technical complexity. The vendor base concentrates around firms with proven valve hall commissioning experience in weak-grid environments. Technology licensing partnerships and modular platform standardization represent the dominant competitive moves as procurement timelines compress.
Among European-based integrated electrical groups, Siemens AG and ABB Ltd occupy positions as anchor suppliers for large-scale East African corridors. Prysmian SpA exemplifies the cable systems specialization archetype, focusing on submarine and underground extruded insulation technologies. Hitachi Energy Ltd represents the modular converter platform segment, competing on compact Voltage Source Converter architectures suited to variable renewable integration. These three firms anchor distinct competitive vectors within the regional procurement landscape.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Prysmian SpA |
| ABB Ltd |
| LS Industrial Systems Co Ltd |
| Hitachi Energy Ltd |
| Siemens AG |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| General Electric Company |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency on insulated-gate bipolar transistor modules from German and Japanese fabrication facilities determines both pricing tier spreads and supply chain shape across African HVDC procurement. Currency volatility exposure and extended lead times compress margins for fiscally constrained utilities while concentrating negotiating leverage with original equipment manufacturers who control valve hall assembly.
Pricing Analysis
Configured-to-order pricing for Voltage Source Converter stations commands substantial premiums over standard Line Commutated Converter assemblies due to black-start capability requirements. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and customization depth. Cost compression in the standard tier is intensifying because regional power pools consolidate tendering through single-window procurement systems. State-owned utilities exhibit highest price sensitivity due to sovereign budget constraints, while green hydrogen export developers absorb premiums for guaranteed 24/7 renewable power delivery.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from European export credit agencies enable African utilities to bridge the capital intensity gap for converter station procurement. Geographic supply concentration centers on Germany for power semiconductor modules, Japan for specialized magnetic steel grades, and Italy for extruded submarine cable systems. Raw material dependencies draw from rare earth elements for IGBT doping, high-purity copper for conductor systems, and transformer-grade grain-oriented electrical steel. Single-source vulnerability persists for phase-locked loop control tuning expertise concentrated in European supplier hubs. Distribution runs through regional power pool consolidated procurement bodies rather than bilateral utility negotiations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC incumbents face substitution pressure from modular battery storage and distributed generation architectures that could bypass long-distance transmission investment in remote renewable zones.
For Market Incumbents: Build switching cost moats through captive spare parts warehousing in Nairobi, Addis Ababa, and Johannesburg to compress mobilization timelines for weak-grid commissioning. Anchor long-term service contracts with Ethiopian Electric Power and Kenya Electricity Transmission Company to preempt modular converter platform competitors. Deepen backward integration into converter transformer core manufacturing to mitigate 18-24 month delivery schedules for specialized magnetic steel grades. For New Entrants and Emerging Players: Build out full-formerless converter transformer capabilities to capture procurement from Tanzania and Uganda developers preemptively aligning with Kenyan black-start standards. Target the Lake Turkana Wind Power corridor extension and Namibia green hydrogen export feeder segments where incumbent relationships remain unsettled. Pursue technology licensing partnerships with established valve hall specialists to bypass the specialized labor scarcity barrier in weak-grid commissioning. For Investors and Strategic Acquirers: The market sits at an infrastructure buildout phase that favors integrated electrical equipment conglomerates with proven African project execution. Five-to-ten-year viability hinges on successful meshed multi-terminal network deployment across the Southern African Power Pool. Acquisition targets should demonstrate valve hall commissioning experience in weak-grid environments with existing relationships to Eastern Africa Power Pool procurement bodies. Monitor harmonization progress between Kenya's Energy and Petroleum Regulatory Authority and South Africa's National Energy Regulator as the inflection signal for scaled regional procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing Partnership | Enables new entrants to access proven IGBT valve hall designs without captive R&D investment. |
| Regional Spare Parts Warehousing | Compresses mobilization timelines for Ethiopian and Kenyan converter station maintenance cycles. |
| Power Purchase Agreement Structuring | Secures guaranteed offtake for Namibia and Morocco green hydrogen export hub transmission feeders. |
| Backward Integration into Magnetic Steel | Mitigates 18-24 month converter transformer lead times that disrupt renewable commissioning targets. |
| Submarine Cable Pre-qualification | Positions Prysmian and Nexans for Mozambique Channel interconnector awards linking regional power pools. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across the Eastern Africa Power Pool and Southern African Power Pool; and secondary validation through IEA transmission investment databases, FERC-equivalent regulatory filings from Ethiopia's Ethiopian Energy Authority and Kenya's Energy and Petroleum Regulatory Authority, and project development tracking from multilateral development finance institutions. Bottom-up unit economics for converter station deployments were triangulated against top-down power pool procurement pipeline aggregates.
Forecast inputs considered Voltage Source Converter versus Line Commutated Converter technology mix shifts, meshed multi-terminal network adoption curves, and submarine versus overhead installation type evolution across the analysis window. Segmentation dimensions modeled include converter technology type, application category spanning renewable integration through interconnection, end-user archetype from state-owned utilities to independent power producers, and installation environment. CAGRs were derived from project pipeline aggregation and announced procurement timelines without year-specific anchoring.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by modular converter platform specialists or accelerated grid code harmonization across regional power pools would shift outcomes. Macroeconomic volatility affecting multilateral development finance availability, regulatory deviation from black-start capability mandates, or breakthrough advances in solid-state transformer technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Electrical Substation Management Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Europe Active Network Management Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Fuse Rails Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market