
 Oil Well Cement Market | 2026-2036
Oil Well Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Well Cement Market Intelligence
Deepwater exploration is realigning demand patterns across the Oil Well Cement Market as drilling contractors prioritize sulfate-resistant formulations for high-pressure, high-temperature wells. LafargeHolcim Ltd. leverages its integrated supply chain across the Middle East and North America to secure long-term drilling contracts. HeidelbergCement AG anchors its position through specialized production of API-compliant cements tailored to North Sea conditions. CEMEX S.A.B. de C.V. competes aggressively in Latin American offshore markets with regionally optimized logistics networks.
Oil well cement is a hydraulic binder formulated from Portland cement clinker with controlled mineral additives, designed to set and harden under downhole conditions ranging from ambient to over 350°F while maintaining zonal isolation integrity. Its primary function is to seal annular spaces between casing and formation, preventing fluid migration and protecting groundwater aquifers throughout a well's productive life. Class G and Class H cements dominate volume demand due to their versatility across standard and deep well applications, while foamed cement technology commands premium positioning in low-density wellbore applications where lost circulation risks constrain conventional slurry designs. Zonal isolation applications concentrate margin pools as operators face escalating liability exposure from sustained casing pressure and gas migration incidents.
API Specification 10A and ISO 10426-1 establish mandatory testing protocols for thickening time, compressive strength, and free fluid content that determine market access for all suppliers. EPA Underground Injection Control regulations and BSEE well integrity standards in the US Gulf of Mexico impose additional barriers through mechanical integrity testing and cement evaluation logging requirements. Stakeholders must monitor the divergence between API baseline standards and operator-specific technical specifications, as supermajor procurement contracts increasingly embed performance guarantees beyond standardized certification thresholds.
Market Dynamics
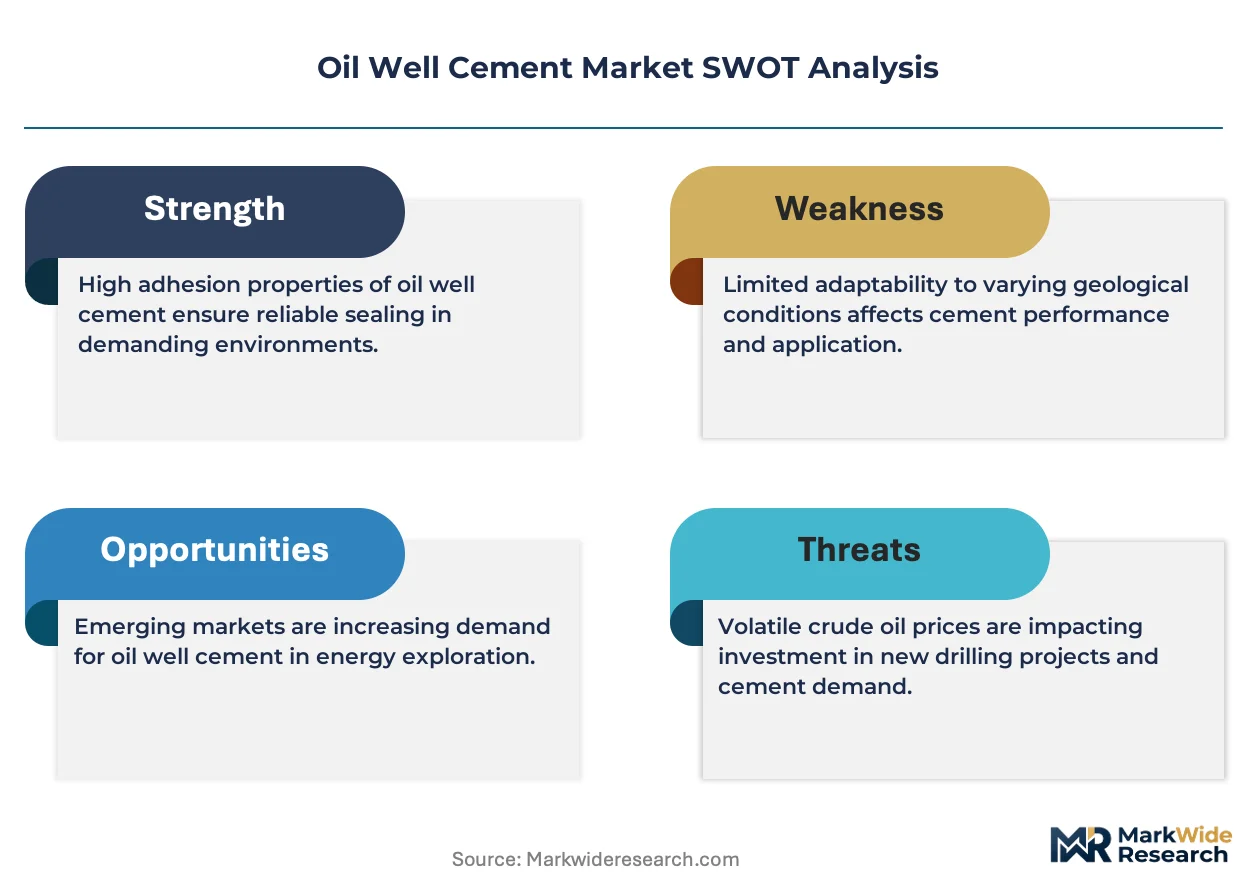
Deepwater exploration off Brazil and West Africa is compressing thickening time requirements for cement slurries, forcing suppliers to reformulate Class G and Class H systems for high-pressure, high-temperature wells while API Specification 10A compliance costs escalate.
Growth Catalysts
- Extended-reach drilling:Permian Basin operators require specialized cement systems for lateral sections exceeding 15,000 feet, expanding demand for engineered particle-size distributions.
- EPA Underground Injection Control:Mechanical integrity testing mandates in the US Gulf of Mexico are accelerating replacement cycles for aging wellbore cement.
- Foamed cement technology:Low-density formulations are penetrating low-fracture-gradient formations where lost circulation risks previously blocked conventional slurry deployment.
Market Restraints
- Clinker input volatility:Energy-intensive cement production faces natural gas price swings that compress margins on API-compliant formulations.
- Supply concentration:Gulf Coast production clusters concentrate manufacturing capacity, exposing procurement channels to hurricane-related disruption.
- Geopolymer substitution:Alternative binder systems threaten displacement in geothermal applications where Portland chemistry degrades.
Strategic Opportunities
- Offshore West Africa:Ghana and Senegal licensing rounds are opening procurement channels for sulfate-resistant formulations in pre-salt analog plays.
- Carbon capture utilization:CO2-enhanced oil recovery projects create demand for carbonation-resistant cement systems in mature Permian fields.
- Real-time monitoring integration:Distributed fiber-optic sensing is converging with cement placement operations to enable zonal isolation verification.
Industry Challenges
- Rheology modeling expertise:Computational fluid dynamics specialization gaps constrain slurry design for ultra-deepwater wells.
- ISO 10426-1 certification timelines:Extended laboratory testing protocols delay product commercialization for emerging well conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Well Cement Market |
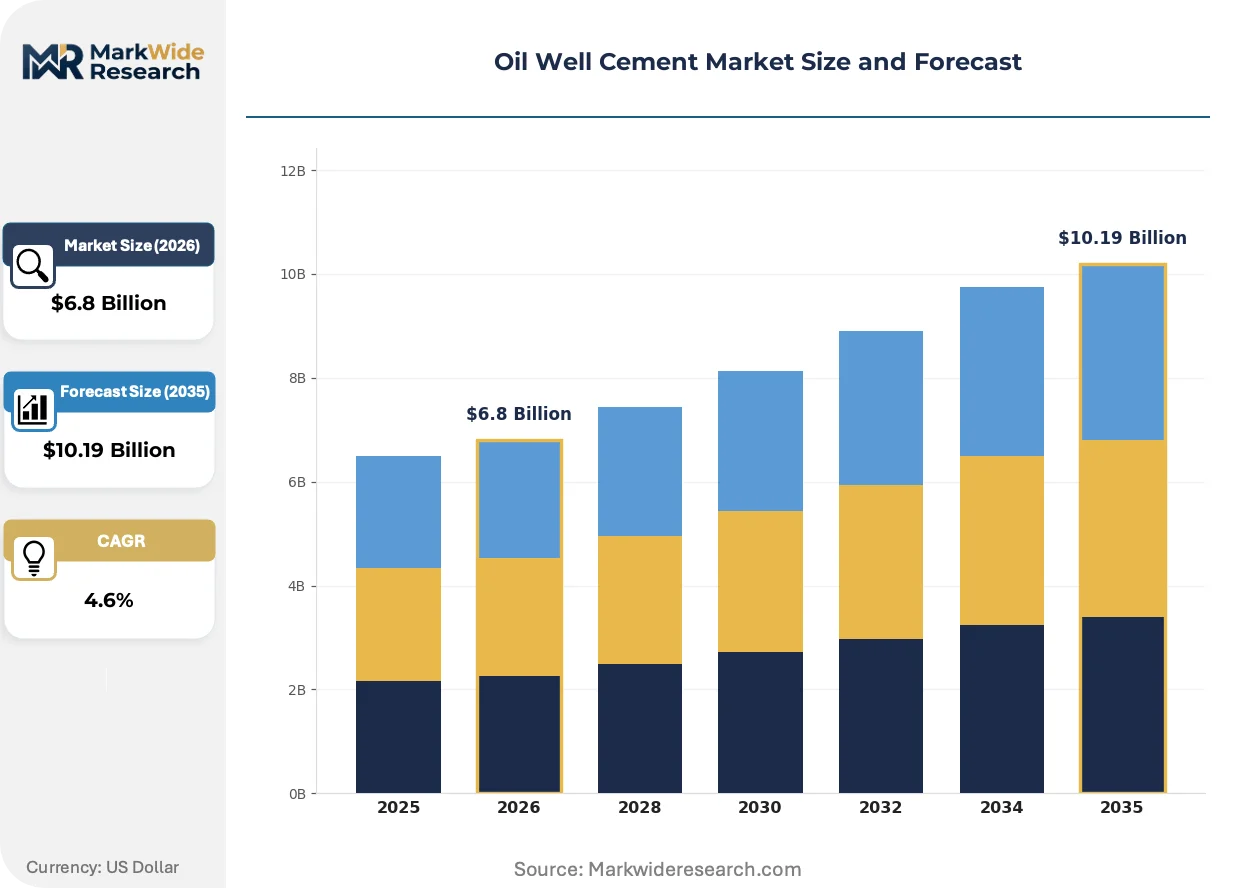
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Class A, Class B, Class C, Class G, Class H Application: Wellbore Cementing, Zonal Isolation, Lost Circulation Control, Hydraulic Fracturing Technology: Foamed Cement, Lightweight Cement, High-Pressure Cement, Flexible Cement End User: Exploration Companies, Drilling Contractors, Well Service Providers, Drilling Equipment Manufacturers |
| Companies Covered | LafargeHolcim Ltd., HeidelbergCement AG, CEMEX S.A.B. de C.V., Buzzi Unicem SpA, Colacem SpA, Raysut Cement Co., Oman Cement Company, TPI Polene Public, Karmen Cement, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Well Cement Market Strategic Shifts & Innovations
Nanomaterial additives and digital twin technologies are restructuring how cement systems are designed, tested, and deployed across conventional and unconventional reservoirs.
Nano-silica dispersions are enhancing compressive strength development in lightweight slurries without density increases. Offshore contractors in the US Gulf of Mexico are specifying these formulations for subsea tieback projects. The technology is converging with automated mixing systems to reduce surface equipment footprint on offshore platforms.
EU Green Deal carbon border adjustments are pressuring cement imports into European offshore markets. BSEE well integrity standards in the US Gulf and evolving ISO frameworks are tightening documentation requirements for sulfate-resistant grades. North Sea operators are responding by embedding lifecycle carbon data into procurement specifications.
Integrated service contracts are bundling cementing operations with logging and evaluation services, displacing standalone product supply arrangements. Supermajor operators in Brazil's pre-salt concessions are consolidating vendors under multi-well framework agreements. This consolidation is most visible in deepwater Brazil where Petrobras procurement reforms favor bundled technical service providers over material-only suppliers.
Oil Well Cement Market Segmentation
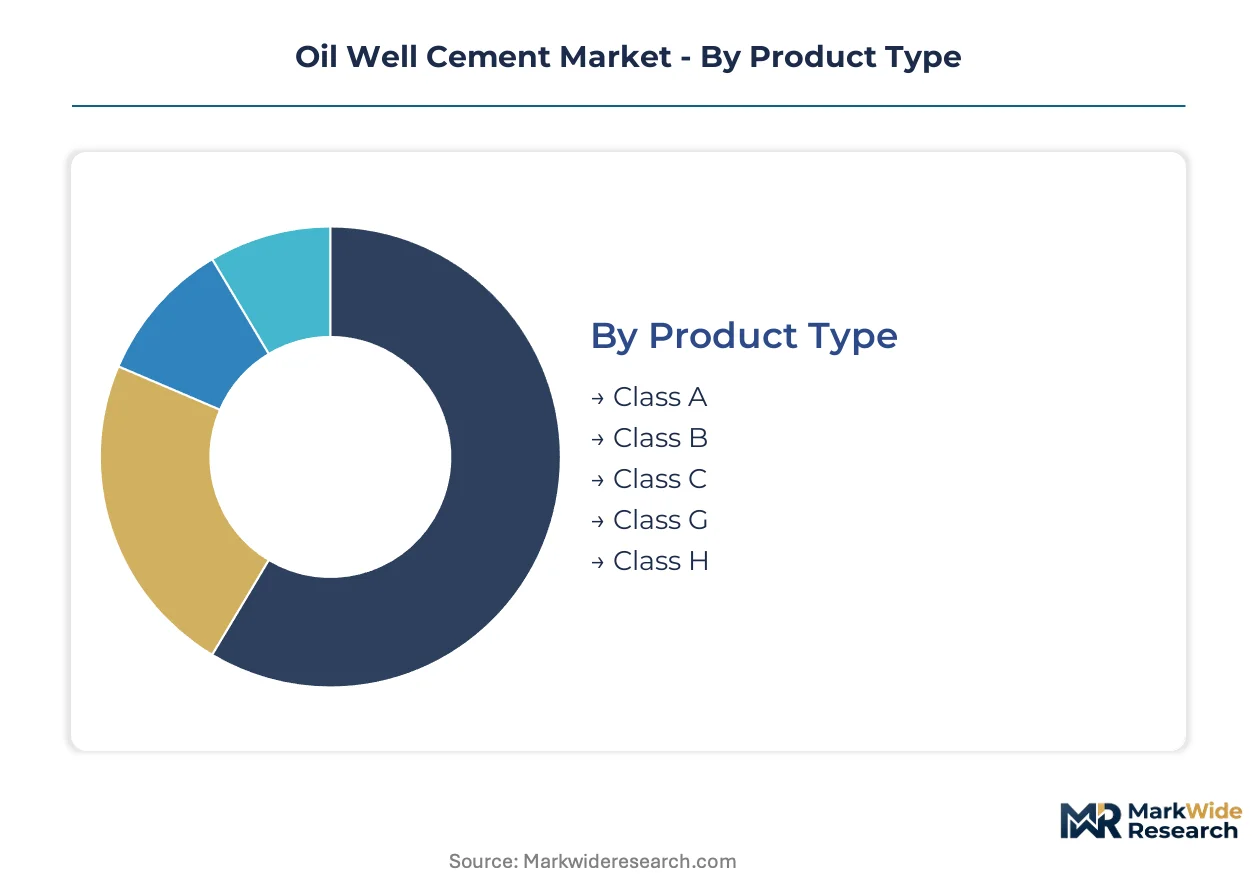
Oil well cement segmentation tracks the divergence between high-volume commodity grades and engineered systems commanding technical premiums. Procurement patterns split between standardized API-compliant products and application-specific formulations tailored to downhole chemistry and pressure regimes.
Product Type:
Volume concentrates in basic API grades while premium accrues to deepwell-specialized formulations with extended performance envelopes.
- Class G:Portland cement base with moderate sulfate resistance serves as the workhorse for wells up to 8,000 feet. Permian Basin operators specify this grade for extended-reach laterals where cost efficiency dominates procurement decisions.
- Class H:Coarser grind and retarded set chemistry enable deployment in high-temperature formations exceeding 230°F. Deepwater Brazil pre-salt drilling contracts specify Class H as the baseline for HPHT well architecture.
- Class A:Basic Portland formulation for surface casing and shallow well construction where sulfate exposure remains minimal.
- Class B:Moderate sulfate-resistant variant targeting intermediate depths with moderate formation pressures.
- Class C:Early-strength formulation for remedial cementing and squeeze operations requiring rapid compressive development.
Today's leader: Class G. Tomorrow's challenger: Class H.
Application:
Margin pools concentrate where zonal integrity failures trigger regulatory enforcement and liability exposure.
- Zonal Isolation:Annular sealing between casing and formation prevents fluid migration and protects groundwater aquifers throughout productive life. EPA Underground Injection Control enforcement in the US Gulf of Mexico accelerates replacement demand for aging cement sheaths.
- Wellbore Cementing:Primary cementing of production and intermediate casings constitutes the largest volume application. Standard API grades dominate this segment with limited differentiation beyond logistics reliability.
- Lost Circulation Control:Foamed and thixotropic systems address fractured formations where conventional slurries disappear into thief zones.
- Hydraulic Fracturing:Plug-and-perf operations in unconventional reservoirs consume specialized cements for stage isolation and temporary wellbore abandonment.
Regulatory pressure on zonal isolation is climbing fastest, while wellbore cementing retains volume dominance.
Technology:
Density reduction and mechanical flexibility command technical premiums in complex well architectures.
- Foamed Cement:Nitrogen-injected slurries achieve densities below 10 ppg for formations with fracture gradients below 0.7 psi/ft. US Gulf of Mexico subsea tieback projects specify these systems to prevent lost circulation in depleted sands.
- Flexible Cement:Polymer-modified systems accommodate casing expansion and contraction in thermal recovery wells. Steam-assisted gravity drainage operations in Alberta oil sands deploy flexible formulations to prevent microannulus formation.
- Lightweight Cement:Hollow glass microsphere or ceramic bead additives reduce density without nitrogen injection equipment.
- High-Pressure Cement:Dense slurries exceeding 18 ppg for well control situations and kick containment in HPHT environments.
Foamed systems anchor current premium positioning. Flexible cement is gaining share fastest in thermal applications.
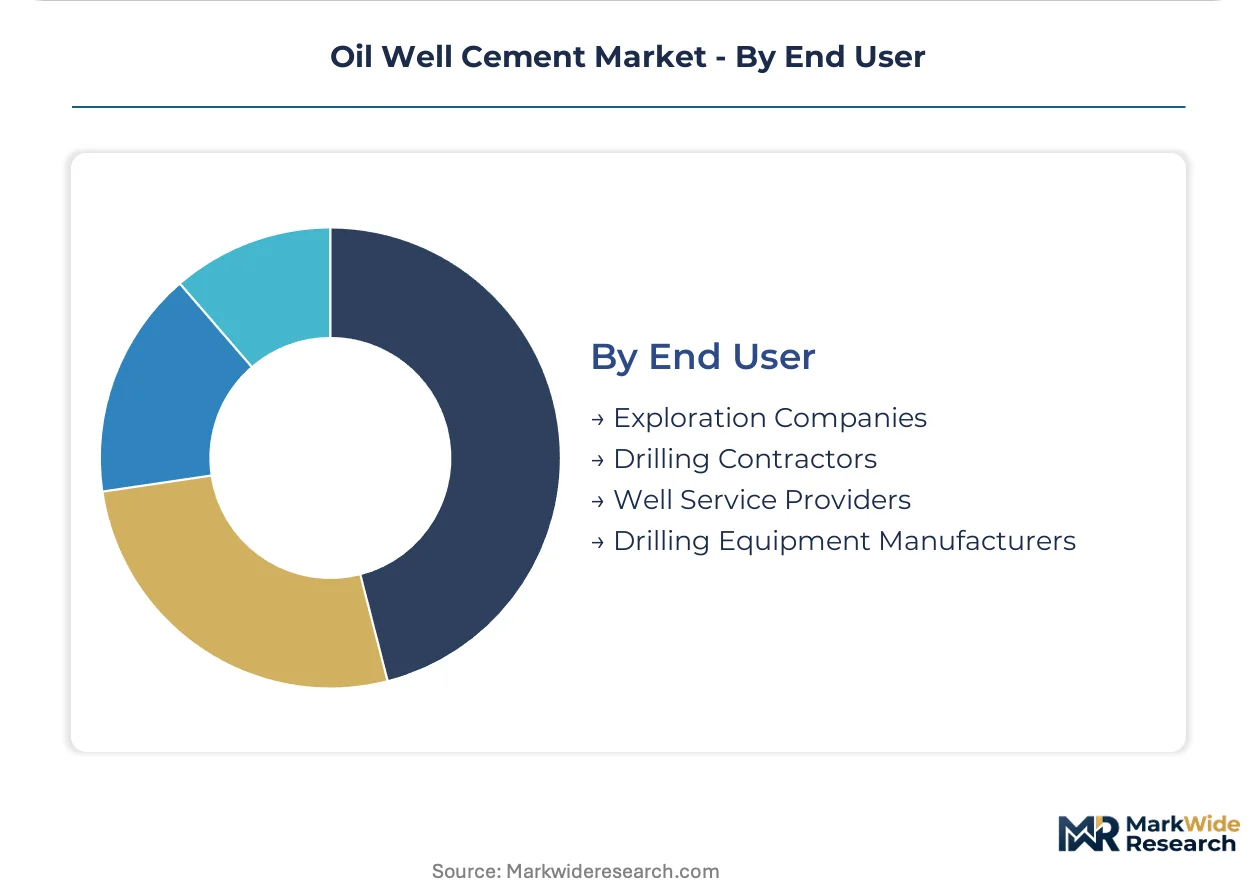
End User:
Procurement authority is consolidating under integrated drilling contractors with multi-well framework agreements.
- Drilling Contractors:Nabors, Helmerich & Payne, and Precision Drilling specify cement systems through integrated service contracts bundling placement, logging, and evaluation. Brazil's pre-salt concessions favor this procurement model.
- Exploration Companies:Independent operators in the Permian Basin and Bakken formation purchase cement through spot markets and regional distributors with limited technical service integration.
- Well Service Providers:Halliburton and Schlumberger cementing divisions procure bulk materials for bundled pumping and evaluation services.
- Drilling Equipment Manufacturers:OEMs specify cement systems for casing hardware compatibility testing and qualification protocols.
Drilling contractors control today's procurement volume. Exploration companies represent the challenger segment as supermajors restructure vendor relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing manufacturing capacity toward jurisdictions with lower compliance burdens for API Specification 10A certification, while deepwater drilling economics pull demand toward Brazil and West Africa. Producers are optimizing plant locations to balance sulfur-resistant formulation costs against proximity to offshore logistics hubs.
United States
Permian Basin extended-reach drilling and Gulf of Mexico deepwater activity anchor North American demand. EPA Underground Injection Control enforcement accelerates replacement cycles for aging wellbore cement in mature fields. Houston-Galveston corridor suppliers concentrate production capacity to serve offshore contractors with rapid-response logistics.
Brazil
Pre-salt deepwater exploration off the Santos Basin compresses thickening time requirements for HPHT cement systems. ANVISA environmental licensing and Petrobras procurement reforms favor bundled technical service providers over material-only suppliers. Macaé logistics cluster serves as the primary staging point for offshore cementing operations.
Norway
North Sea well integrity standards and mature field abandonment programs sustain demand for sulfate-resistant Class H formulations. Norwegian Petroleum Directorate regulations mandate cement evaluation logging for all subsea completions. Stavanger-based suppliers specialize in Arctic-grade systems for Barents Sea high-pressure conditions.
Saudi Arabia
Gas drilling in the Jafurah Basin and offshore Red Sea exploration expand procurement for high-temperature cement systems. SAMR technical regulations and Aramco supplier qualification protocols create entry barriers for non-API-compliant materials. Eastern Province manufacturing clusters leverage captive clinker supply for Gulf regional export.
United Arab Emirates
ADNOC offshore expansion and sour gas development in the Hail and Ghasha fields drive demand for corrosion-resistant cement chemistry. MOHAP industrial standards and UAE carbon reduction targets pressure producers toward lower-emission kiln operations. Jebel Ali port infrastructure enables re-export positioning for East African and South Asian markets.
Oil Well Cement Market Key Industry Players
Capacity expansion dominates the current landscape as regional producers add sulfate-resistant grinding capacity to capture deepwater drilling contracts. The market structures around three tiers: multinational building materials conglomerates with integrated oilfield divisions, regional cement specialists with API-certified product lines, and national champions serving captive domestic drilling programs. Strategic archetypes include logistics-integrated suppliers bundling placement services, and technology-focused formulators engineering particle-size distributions for extended-reach applications. M&A activity and strategic partnerships represent the dominant competitive vectors as operators consolidate vendor relationships under multi-well framework agreements.
Among European-based building materials conglomerates, LafargeHolcim Ltd. and HeidelbergCement AG exemplify the integrated multinational archetype with cross-regional supply chain footprints. CEMEX S.A.B. de C.V. represents the Americas-focused regional champion with logistics networks optimized for Latin American offshore markets. These three entities occupy positions that span commodity-grade volume supply through specialized deepwell formulation capabilities, reflecting the market's bifurcation between standardized API compliance and engineered performance premiums.
| Leading Market Players |
|---|
| LafargeHolcim Ltd. |
| HeidelbergCement AG |
| CEMEX S.A.B. de C.V. |
| Buzzi Unicem SpA |
| Colacem SpA |
| Raysut Cement Co. |
| Oman Cement Company |
| TPI Polene Public |
| Karmen Cement |
| Others |
Cost & Logistics Intelligence
Petrobras procurement reforms mandating bundled technical service contracts are compressing material-only supplier margins and forcing cement manufacturers to absorb placement service costs or surrender Gulf of Mexico and pre-salt market access.
Pricing Analysis
Distributor markups on API-certified bulk cement range from 8-15% above ex-works pricing, with direct-to-driller contracts commanding 12-20% discounts for multi-well framework commitments. Three-tier pricing structure separates premium sulfate-resistant deepwell formulations from standard Class G bulk deliveries and economy-grade spot market volumes. Pricing pressure stems from clinker input volatility and natural gas price swings that compress margins on energy-intensive kiln operations. Independent Permian Basin operators exhibit highest price sensitivity, while supermajor drilling contractors prioritize technical performance guarantees over unit cost.
Supply Chain Analysis
Dual-sourcing qualification requirements from BSEE and ANVISA mandate that drilling contractors maintain approved supplier lists spanning at least two manufacturing jurisdictions, preventing single-source dependency in Gulf of Mexico and Brazilian offshore markets. Production gravity centers on the United States, Saudi Arabia, and Brazil, with captive clinker supply in the Eastern Province anchoring Gulf regional export capacity. Raw material dependencies span high-purity limestone, gypsum, and specialized mineral additives for sulfate resistance. Single-source vulnerability concentrates around Gulf Coast manufacturing clusters exposed to hurricane-related disruption. Distribution runs through Houston-Galveston and Macaé logistics corridors serving offshore contractors with rapid-response bulk delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EPA Underground Injection Control enforcement and BSEE well integrity standards continuously refresh replacement demand for aging cement sheaths.
For Market Incumbents: Deepen backward integration into captive clinker supply to insulate margin structures from energy input volatility, while accelerating ISO 10426-1 certification timelines to preempt geopolymer substitution threats in geothermal applications. Prioritize multi-well framework agreements with integrated drilling contractors in Brazil's pre-salt concessions to lock out material-only competitors. For New Entrants and Emerging Players: Enter via carbonation-resistant cement formulations targeting CO2-enhanced oil recovery projects in mature Permian fields, where incumbent portfolios remain underdeveloped. Ghana and Senegal licensing rounds offer the most penetrable procurement channels for sulfate-resistant pre-salt analog plays. Lead with real-time monitoring integration partnerships to differentiate against commodity-grade suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with regional cement specialists possessing API-certified production lines and established logistics networks in West African offshore markets. Long-term viability hinges on positioning for abandonment-driven replacement cycles in mature North Sea fields. Watch distributed fiber-optic sensing convergence with cement placement operations as the inflection signal for premium technology capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Clinker Supply | Captive limestone quarries in Saudi Arabia's Eastern Province shield margin structures from energy price volatility. |
| ISO 10426-1 Certification Acceleration | Extended laboratory testing protocols for HPHT formulations delay commercialization and erect barriers against geopolymer substitutes. |
| Multi-Well Framework Agreements | Petrobras procurement reforms in Brazil's pre-salt concessions favor bundled technical service providers over standalone material suppliers. |
| Carbonation-Resistant Formulation Development | CO2-enhanced oil recovery projects in mature Permian fields create demand pockets where incumbent portfolios remain underdeveloped. |
| Real-Time Monitoring Integration | Distributed fiber-optic sensing partnerships with Halliburton and Schlumberger cementing divisions enable zonal isolation verification premiums. |
Research Approach
Bottom-up drilling contractor procurement modeling reconciled against top-down cement production capacity tracking forms the analytical core of this study. Primary interviews with drilling engineers, cementing service managers, procurement leads at integrated contractors, and regulatory compliance officers at BSEE and ANVISA were validated against secondary sources including API Specification 10A documentation, EPA Underground Injection Control enforcement records, SEC filings from building materials conglomerates, and customs trade data for clinker and finished cement movements. Triangulation between demand-side contract awards and supply-side kiln utilization rates ensures cross-verification of volume estimates.
Input-output matrices map clinker grinding capacity, sulfur-resistant formulation capabilities, and logistics infrastructure against well permit filings, rig count trajectories, and abandonment program schedules across the projection horizon. Segmentation dimensions include cement class tier, application type, technology category, and end-user procurement authority. CAGRs were derived from regression analysis of historical well completion intensity against cement consumption per wellbore, incorporating assumptions for extended-reach drilling penetration and deepwater exploration ramp rates.
Inputs from drilling contractor procurement databases and regulatory filing systems were available through the study window; gaps in real-time inventory positioning at offshore logistics hubs introduce uncertainty bands around short-term demand spikes. Deviation in EPA enforcement intensity or Petrobras capital allocation priorities would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Data Management Market
Oil & Gas
Delayed Coker Unit Market
Oil & Gas
Modular Refinery Market
Oil & Gas
Crude Oil Desalter Market
Oil & Gas
Well Cementing Market
Oil & Gas
Operational Digital Oilfield Solution Market
Oil & Gas
Subsea Boosting Systems Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Seismic Survey Equipment Market
Oil & Gas
Middle-East Oil and Gas Line Pipe Market
Oil & Gas
Pipeline Pigging Services Market
Oil & Gas
Crown Block Market
Oil & Gas
Libya Oil and Gas Midstream Market
Oil & Gas
Oriented Perforating System Market
Oil & Gas
Process Simulation Software in Oil and Gas Market
Oil & Gas
Oil and Gas Processing Seals Market