
 Cryogenic Vaporizer Market | 2026-2036
Cryogenic Vaporizer Market Size, Share, and Industry Trends Forecast 2026-2036
Cryogenic Vaporizer Market Insights
ASME-certified high-pressure specifications is collapsing the gap between legacy industrial equipment and next-generation LNG infrastructure requirements. Chart Industries leverages vertical integration across heat exchanger manufacturing to sustain cost leadership in ambient vaporizer systems. Nikkiso Co., Ltd. anchors its position through specialized aluminum-fin production for cryogenic heat transfer. Linde plc dominates project-scale deployments by controlling engineering procurement construction channels for integrated LNG facilities.
Cryogenic vaporizers are heat exchange devices that convert liquefied gases—nitrogen, oxygen, argon, LNG—back to gaseous phase through ambient air, forced convection, or direct-fired thermal energy transfer, typically operating at pressures from 10 bar to 350 bar and temperatures approaching minus 196 degrees Celsius. Their primary purpose centers on delivering consistent gas supply to industrial processes, medical oxygen networks, and LNG regasification terminals where pipeline pressure and flow stability determine operational continuity. Ambient vaporizers occupy the largest installed base due to zero energy consumption and minimal maintenance, while forced convection units capture expanding margin pools in high-throughput LNG applications where atmospheric humidity and temperature swings constrain passive systems. Industrial gases applications sustain the deepest replacement cycle demand, whereas LNG plants represent the fastest-growing deployment category as export terminal capacity additions accelerate across multiple continents.
EPA emission standards and China's GB pressure vessel codes are reshaping material selection and welding certification requirements for cryogenic equipment manufacturers seeking cross-border market access. The EU F-Gas Regulation and REACH compliance frameworks impose additional documentation burdens on European-deployed systems, favoring suppliers with established certification portfolios. ISO cryogenic testing protocols serve as the baseline quality benchmark for international project tenders, effectively filtering out uncertified regional fabricators. Stakeholders must monitor evolving carbon border adjustment mechanisms and their potential to restructure sourcing geography for aluminum fin stock and stainless steel pressure envelopes.
Market Dynamics
ASME-certified high-pressure specifications are collapsing the gap between legacy industrial equipment and next-generation LNG infrastructure requirements. The EPA's methane emission regulations and China's dual carbon goals are tightening equipment efficiency standards across manufacturing footprints.
Growth Catalysts
- Qatar's North Field expansion:Mega-scale LNG trains require high-capacity ambient and forced convection vaporizer systems. This concentration of project demand pulls specialized fabrication capacity toward the Gulf region.
- EPA methane regulations:Tighter emission standards force LNG plant operators in the United States to upgrade vaporizer fleets. Equipment replacement cycles compress as compliance deadlines approach.
- Aluminum-fin heat transfer technology:Advances in cryogenic-grade fin production improve thermal efficiency in ambient vaporizer systems. Industrial gas networks deploy these units to reduce energy consumption in medical oxygen and nitrogen supply chains.
Market Restraints
- Stainless steel price volatility:Pressure envelope fabrication depends on nickel-alloy steel inputs. Cost swings compress margins for ASME-certified fabricators serving project-scale deployments.
- Aluminum fin stock supply concentration:Specialized cryogenic-grade aluminum sourcing clusters among limited primary producers. Geographic concentration in East Asian smelting capacity exposes downstream fabricators to trade policy friction.
- Forced convection energy intensity:High-throughput LNG applications require auxiliary power for fan-driven systems. Ambient vaporizer zero-energy advantage constrains forced convection penetration in cost-sensitive industrial gas segments.
Strategic Opportunities
- India's industrial gas infrastructure:Cryogenic vaporizer penetration remains shallow outside major metropolitan medical oxygen networks. PLI scheme incentives for domestic manufacturing attract equipment suppliers to establish local assembly.
- EU F-Gas Regulation compliance:REACH documentation burdens favor suppliers with established certification portfolios. European-deployed systems command premium positioning through verified carbon footprint transparency.
- Digital twin integration with predictive maintenance:IoT sensor networks converge with vaporizer thermal performance modeling. LNG terminal operators adopt these systems to minimize unplanned downtime during peak regasification demand.
Industry Challenges
- ASME Section VIII welding certification scarcity:Qualified pressure vessel welders for cryogenic service remain concentrated among aging specialist workforces. Training pipeline gaps constrain fabrication capacity expansion.
- ISO cryogenic testing protocol timelines:International project tenders require extensive documentation of low-temperature material performance. Certification delays extend order-to-delivery cycles for custom-engineered units.
- Legacy system integration complexity:Existing LNG regasification terminals operate vaporizer banks installed under prior design codes. Retrofit projects must reconcile new equipment with established piping and control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cryogenic Vaporizer Market |
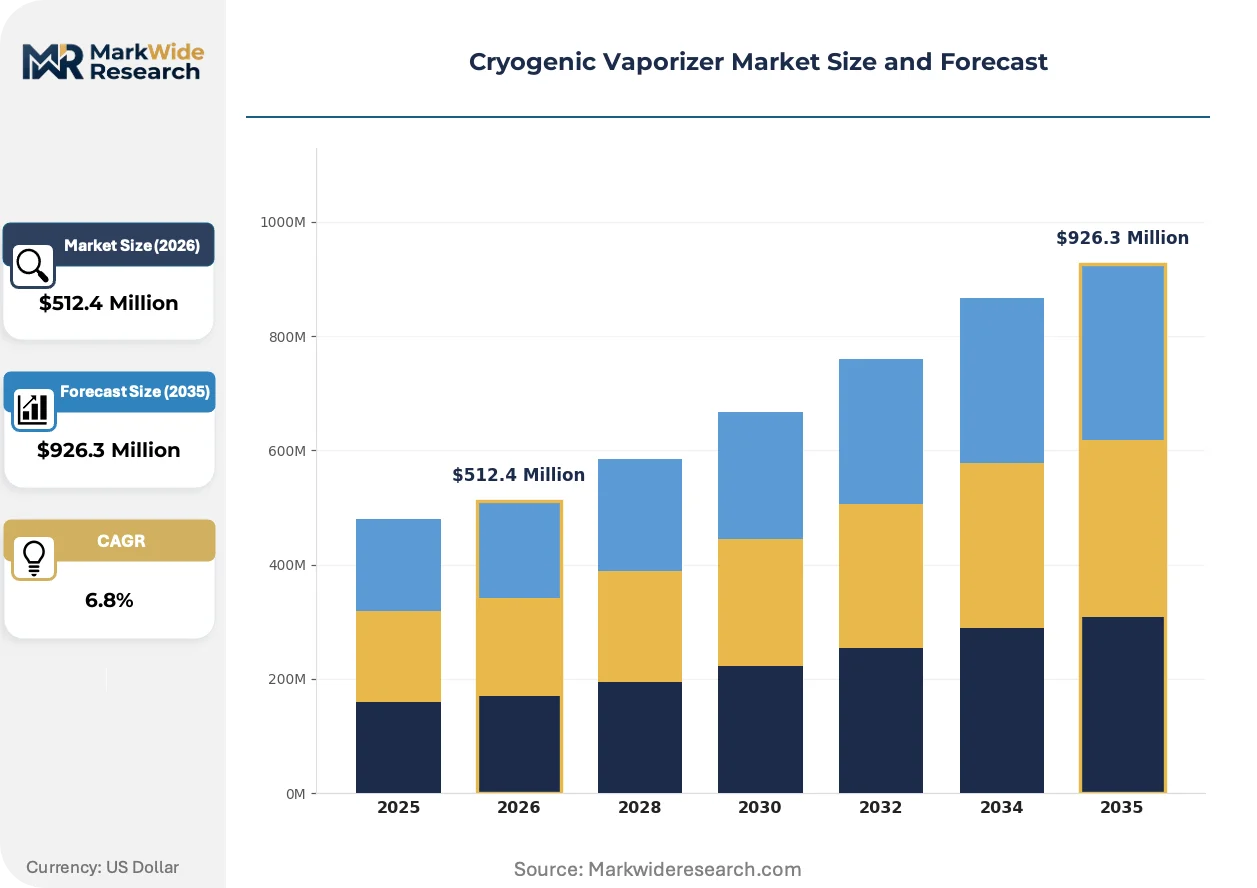
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $926.3 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flow Vaporizer, Pressure Vaporizer, Ambient Vaporizer, Forced Convection Vaporizer Application: LNG Plants, Chemical Processing, Medical Applications, Industrial Gases End User: Oil & Gas, Healthcare, Food & Beverage, Energy Installation: Fixed, Portable, Skid-Mounted, Pipeline |
| Companies Covered | Chart Industries, Nikkiso Co., Ltd., Linde plc, Air Liquide, Cryostar, INOX India Limited, Kobe Steel, Ltd., Taylor-Wharton, Cryolor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cryogenic Vaporizer Market Trends and Innovations
Equipment manufacturers are embedding sensor networks and advanced materials into vaporizer designs to capture efficiency gains and predictive capabilities. Three developments are restructuring competitive positioning across ambient, forced convection, and direct-fired system categories.
Aluminum-fin ambient vaporizer technology is supplanting traditional stainless-steel tube bundles in moderate-climate industrial gas applications. Medical oxygen network operators in Germany and Japan are adopting these units to eliminate fan energy consumption. The shift compresses maintenance requirements while expanding addressable market share in cost-sensitive hospital supply chains.
China's GB pressure vessel codes and dual carbon goals are mandating material traceability and welding documentation for cross-border equipment sales. Domestic fabricators must upgrade quality systems to meet these standards. LNG project developers in the United States and Qatar increasingly specify GB-compliant units to preserve sourcing flexibility.
Service unbundling is separating vaporizer hardware from long-term maintenance contracts. Industrial gas distributors are internalizing predictive maintenance capabilities rather than relying on OEM service agreements. This pattern concentrates most visibly in North American medical oxygen networks where uptime guarantees determine contract awards.
Cryogenic Vaporizer Market Segmentation
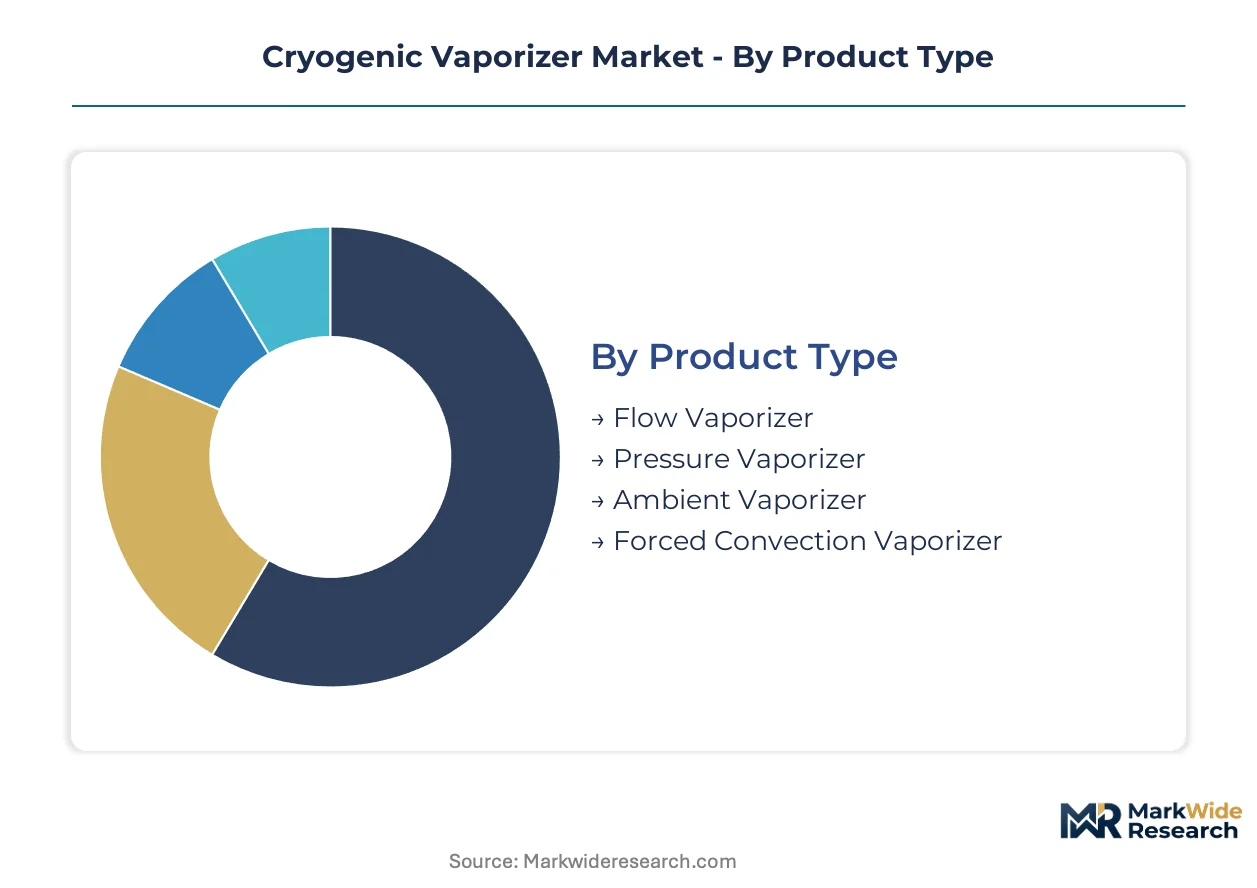
Cryogenic vaporizer procurement decisions diverge sharply across operating pressure, thermal duty, and mobility requirements. Segment-specific certification burdens and energy intensity trade-offs determine supplier selection criteria in LNG infrastructure versus medical gas networks.
Product Type:
ASME Section VIII and GB pressure vessel codes create divergent compliance pathways for each thermal transfer architecture, filtering fabricator participation by certification scope.
- Ambient Vaporizer:Aluminum-fin heat exchange surfaces exploit atmospheric temperature differentials to vaporize cryogenic fluids without auxiliary power. Qatar's North Field expansion corridor and German medical oxygen networks deploy these units where climate conditions permit passive operation and zero energy consumption secures operational cost advantages.
- Forced Convection Vaporizer:Motor-driven fan arrays accelerate air movement across extended fin surfaces to overcome humidity and temperature constraints that limit passive systems. High-throughput LNG regasification terminals in the United States specify these units despite energy intensity, as throughput guarantees override operating cost considerations in peak demand scenarios.
- Flow Vaporizer:Compact inline designs integrate directly into distribution piping for continuous process gas supply. Chemical processing facilities in Japan and South Korea favor these configurations for nitrogen blanketing operations where space constraints dominate equipment selection.
- Pressure Vaporizer:High-pressure envelope construction accommodates discharge pressures exceeding 100 bar for direct pipeline injection. CNG vehicle fueling stations and industrial gas cylinder filling operations specify these units where compression stage elimination yields capital cost savings.
Established volume favors Ambient Vaporizer; emerging adoption favors Forced Convection Vaporizer.
Application:
End-use thermal duty profiles and purity requirements segment fabrication capabilities between industrial-scale and precision-medical supply chains.
- LNG Plants:Mega-scale regasification terminals demand vaporizer banks exceeding 200 tonnes per hour capacity per unit. Project developers in Qatar, the United States, and China specify these systems under lump-sum turnkey contracts where engineering procurement construction integration determines vendor selection.
- Industrial Gases:Merchant gas supply networks require vaporizer fleets distributed across production plants and customer sites. Nitrogen and argon applications in semiconductor fabrication and metal processing sustain replacement cycle demand as installed base ages beyond design life.
- Chemical Processing:Cryogenic reaction cooling and inert atmosphere maintenance consume vaporized nitrogen at varying flow rates. Petrochemical complexes in India and Saudi Arabia deploy skid-mounted systems for flexibility across batch and continuous process operations.
- Medical Applications:Oxygen supply networks for hospitals and home healthcare demand vaporizers meeting pharmacopeia purity standards. India's metropolitan hospital infrastructure and Japan's aging care facilities drive specification of contamination-resistant aluminum-fin designs.
Replacement cycles concentrate in Industrial Gases; capacity additions concentrate in LNG Plants.
End User:
Capital deployment cycles and operating expenditure sensitivity diverge across energy infrastructure versus consumables supply chains.
- Oil & Gas:Upstream production facilities and midstream terminals specify vaporizers for wellhead gas processing and LNG export. QatarEnergy and US Gulf Coast operators dominate procurement volume through project-scale fleet acquisitions tied to liquefaction train commissioning schedules.
- Energy:Power generation utilities deploy vaporized natural gas for peak shaving and grid stabilization. Japanese and South Korean electric utilities maintain strategic LNG inventories requiring rapid regasification capability during supply disruptions.
- Healthcare:Hospital systems and home medical equipment suppliers prioritize vaporizer reliability over capital cost minimization. German and Japanese oxygen network operators specify redundant vaporizer configurations to guarantee continuous patient supply.
- Food & Beverage:Modified atmosphere packaging and cryogenic freezing applications consume vaporized nitrogen and carbon dioxide. Food processing clusters in the United States and Brazil deploy portable vaporizer units for seasonal production flexibility.
Project concentration favors Oil & Gas; contract stability favors Healthcare.
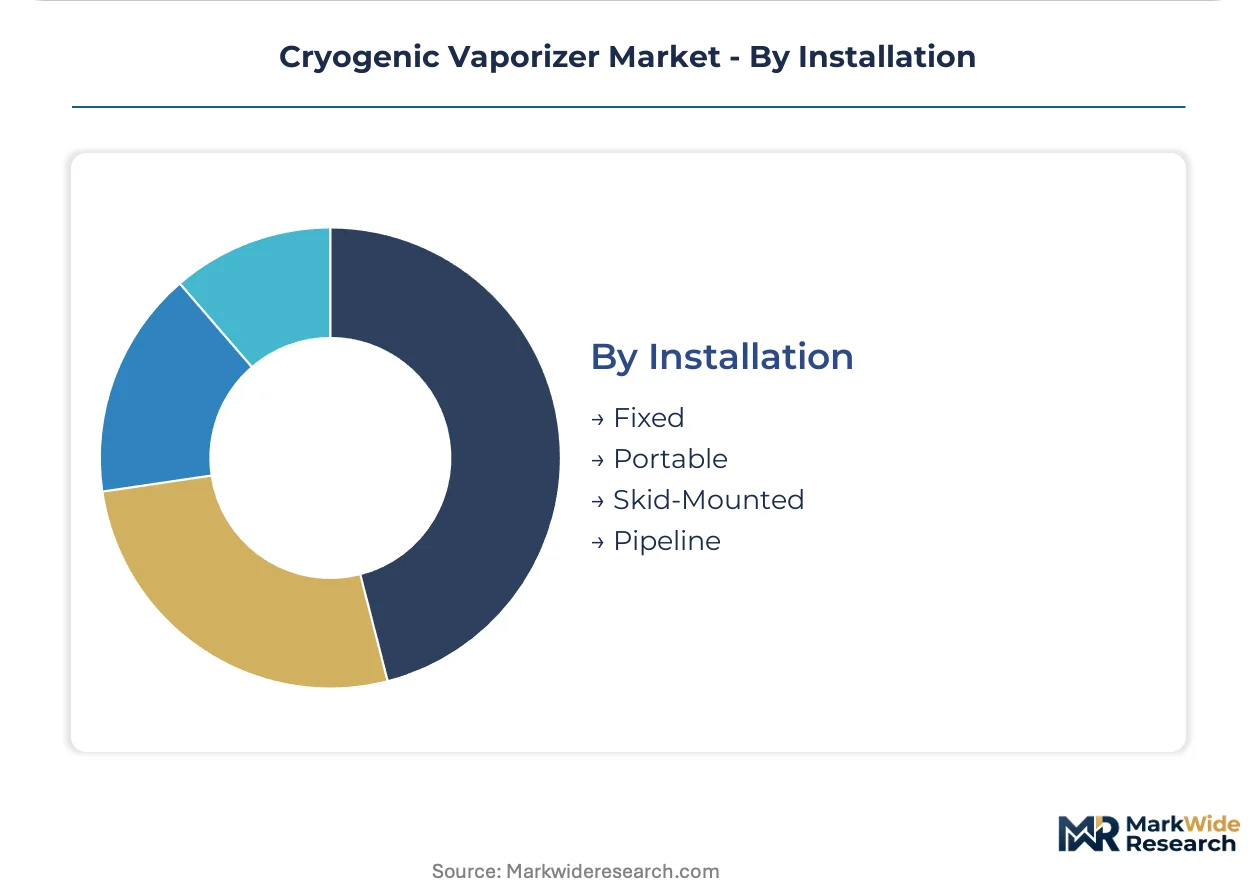
Installation:
Mobility requirements and site preparation constraints determine fabrication location and logistics cost structure.
- Fixed:Permanent concrete foundation installations dominate LNG terminal and industrial gas plant deployments. These configurations minimize footprint and piping complexity in greenfield projects where civil works proceed in parallel with equipment delivery.
- Skid-Mounted:Pre-assembled packages on structural steel frames enable rapid site installation and future relocation. Modular LNG solutions and remote oilfield operations favor this approach where construction labor scarcity drives factory completion preference.
- Portable:Trailer-transportable vaporizers serve temporary industrial gas supply and emergency medical oxygen deployment. Rental fleet operators in North America and Europe maintain these units for short-term customer contracts.
- Pipeline:Direct burial or aboveground integration into distribution networks eliminates intermediate storage. Russian and Central Asian gas transmission systems specify these configurations for minimal pressure drop and thermal loss.
Greenfield deployment favors Fixed; operational flexibility favors Skid-Mounted.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized cryogenic-grade aluminum smelting capacity clusters in East Asian industrial corridors, concentrating fin stock supply for vaporizer fabricators worldwide. QatarEnergy and US Gulf Coast operators pull fabrication capacity toward LNG export terminals through project-scale procurement.
United States
EPA methane regulations compress replacement cycles for LNG plant operators upgrading vaporizer fleets. The Inflation Reduction Act channels investment toward low-emission regasification infrastructure. Gulf Coast terminal clusters in Texas and Louisiana commission high-capacity forced convection systems for peak export demand.
Qatar
North Field mega-train expansion concentrates global demand for ambient and forced convection vaporizers exceeding 200 tonnes per hour. QatarEnergy mandates ASME-certified fabrication for cross-border sourcing flexibility. Ras Laffan Industrial City anchors specialized welding capacity serving liquefaction project timelines.
China
Dual carbon goals and GB pressure vessel codes tighten material traceability requirements for domestic fabricators. MIIT standards accelerate aluminum-fin technology deployment in medical oxygen networks. Yangtze River Delta manufacturing bases upgrade quality systems for export qualification.
Germany
EU F-Gas Regulation and REACH compliance frameworks impose documentation burdens favoring certified European suppliers. Medical oxygen network operators specify redundant aluminum-fin ambient configurations. Ruhr industrial clusters and Bavarian chemical corridors sustain replacement demand for nitrogen blanketing systems.
India
PLI scheme incentives attract equipment suppliers to establish local assembly for shallow-penetration industrial gas markets. CEA guidelines shape hospital infrastructure oxygen supply standards. Maharashtra and Gujarat pharmaceutical clusters deploy contamination-resistant vaporizer designs for metropolitan medical networks.
Cryogenic Vaporizer Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the vaporizer supply base. ASME-certified fabricators with captive heat exchanger manufacturing command premium positioning in LNG project tenders. The market structures around three strategic archetypes: integrated industrial gas conglomerates controlling EPC channels, specialized cryogenic equipment fabricators with aluminum-fin expertise, and regional pressure vessel shops serving replacement cycles. Dominant competitive moves include backward integration into fin stock supply and strategic partnerships with LNG terminal developers for long-term service contracts.
Among US-based industrial equipment specialists, Chart Industries exemplifies the integrated archetype through captive manufacturing capabilities. Japanese fabricators including Nikkiso Co., Ltd. and Kobe Steel, Ltd. occupy positions anchored in precision aluminum-fin production for cryogenic heat transfer applications. These companies represent distinct competitive vectors—scale-driven project execution versus specialized thermal engineering expertise—without overlapping segment focus.
| Leading Market Players |
|---|
| Chart Industries |
| Nikkiso Co., Ltd. |
| Linde plc |
| Air Liquide |
| Cryostar |
| INOX India Limited |
| Kobe Steel, Ltd. |
| Taylor-Wharton |
| Cryolor |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between LNG terminal developers and vaporizer fabricators lock in aluminum-fin supply allocations and compress price volatility for ASME-certified units across the Qatar North Field expansion corridor. These contracts bundle engineering procurement construction milestones with material cost pass-through mechanisms, giving buyers visibility into landed equipment costs while constraining supplier margin flexibility.
Pricing Analysis
EPA methane emission standards dictate the pricing tier structure across the cryogenic vaporizer market. Three-tier pricing separates ASME-certified premium systems from GB-compliant mid-tier units and uncertified economy fabrications. Price differentiation centers on welding certification grade and captive heat exchanger manufacturing depth. Cost compression in standard-tier ambient vaporizers is intensifying because East Asian aluminum smelters face carbon border adjustment exposure. Industrial gas distributors in India exhibit the highest price sensitivity, while QatarEnergy maintains lowest sensitivity due to lump-sum turnkey contract structures.
Supply Chain Analysis
Strait of Hormuz transit underwrites aluminum-fin delivery schedules to Ras Laffan Industrial City fabrication yards. Cryogenic-grade aluminum sourcing draws from Chinese Yangtze River Delta smelters, South Korean POSCO metallurgical facilities, and Russian Rusal primary production. Nickel-alloy stainless steel for pressure envelopes rests on Finnish Outokumpu and Japanese Nippon Steel capacity. Single-source vulnerability concentrates in ASME Section VIII welding certification, where aging specialist workforces constrain fabrication expansion. Distribution runs through engineering procurement construction channels controlled by integrated industrial gas conglomerates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cryogenic vaporizer deployment sits in early-cycle expansion as LNG export terminal commissioning accelerates across multiple continents. Qatar's North Field mega-train timeline pulls specialized fabrication capacity toward the Gulf region faster than supply can respond.
For Market Incumbents: Secure captive aluminum-fin production through backward integration into East Asian smelter partnerships or long-term offtake agreements with Rusal and POSCO. Defend project-scale positioning by embedding digital twin capabilities into forced convection systems before emerging IoT specialists capture LNG terminal maintenance contracts. ASME welding certification scarcity represents the critical chokepoint for capacity expansion. For New Entrants and Emerging Players: Lead with India's PLI scheme incentives to establish local assembly for shallow-penetration medical oxygen networks outside metropolitan hospital infrastructure. Target contamination-resistant aluminum-fin ambient vaporizers for Maharashtra pharmaceutical clusters where German and Japanese incumbents lack service density. Partner with domestic industrial gas distributors to bypass EPC channel control by integrated conglomerates. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap fabricators with GB-ASME dual certification scope and established QatarEnergy supplier status. Long-term viability hinges on positioning for carbon border adjustment mechanism compliance across European-deployed systems. Watch for aluminum-fin technology licensing agreements between Japanese specialists and Chinese Yangtze River Delta manufacturers as inflection signal for competitive repositioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum-Fin Supply | Captive cryogenic-grade fin production insulates Chart Industries and Nikkiso from East Asian smelter concentration risk. |
| Digital Twin Integration with Predictive Maintenance | IoT-enabled thermal performance modeling allows LNG terminal operators to minimize unplanned downtime during peak Qatar regasification demand. |
| GB-ASME Dual Certification Investment | Dual code compliance preserves sourcing flexibility for US Gulf Coast developers seeking to qualify Chinese fabricators for project-scale deployment. |
| PLI Scheme Local Assembly in India | Domestic manufacturing incentives attract equipment suppliers to Maharashtra and Gujarat where metropolitan medical oxygen penetration remains incomplete. |
| Long-Term Service Contract Unbundling | Separating vaporizer hardware from maintenance agreements concentrates value capture in North American medical oxygen networks where uptime guarantees determine contract awards. |
Research Methodology
The analysis maps ambient vaporizer, forced convection vaporizer, flow vaporizer, and pressure vaporizer sub-sectors, each validated through maintenance directors at LNG terminals, plant engineers at industrial gas facilities, OEM procurement teams at Chart Industries and Linde plc, and aftermarket service heads at regional pressure vessel shops. Primary interview findings triangulate against customs and trade data for cryogenic equipment imports, ASME certification registry filings, SEC 10-K disclosures from listed industrial gas conglomerates, and project development databases tracking Qatar North Field expansion timelines. Bottom-up unit economics and top-down sector sizing converge through iterative reconciliation.
Volume and value outputs were validated against external benchmarks including EIA LNG export terminal capacity announcements, IEA natural gas trade flow projections, and FERC filing data for US Gulf Coast regasification infrastructure. The analytical framework models thermal transfer architecture, operating pressure envelope, end-use application, and geographic regulatory cluster across the projection horizon. CAGRs derive from segment-level demand elasticity analysis calibrated to LNG train commissioning schedules and industrial gas replacement cycle data. Forecast inputs include aluminum LME price trajectories and ASME welding certification pipeline constraints.
The analysis sits within stated boundaries; outcomes outside sustained LNG trade volume expansion, stable East Asian aluminum smelter output, and continued EPA methane regulation enforcement would require recalibration. Forecasts reflect documented assumptions regarding QatarEnergy project timelines, China dual carbon goal implementation pace, and India PLI scheme incentive continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Mobile Energy Storage Systems Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Hydrogen Liquefaction System Market
Energy Storage
Behind-The-Meter Stationary Battery Storage Market
Energy Storage
Solar Storage Inverter Market
Energy Storage
Asia-Pacific Energy Storage Systems Market
Energy Storage
Supercapacitor Market
Energy Storage
Energy Storage Software Market
Energy Storage
Global Data Center Energy Storage Market
Energy Storage
United Kingdom Energy Storage Systems Market
Energy Storage
High Capacity Power Banks Market
Energy Storage
Long-Duration Energy Storage Market
Energy Storage
Grid Scale Battery Storage Sales Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Natural Gas Storage Market