
 Overhead Line Fault Passage Indicator Market | 2026-2036
Overhead Line Fault Passage Indicator Market Size, Share, and Industry Trends Forecast 2026-2036
Overhead Line Fault Passage Indicator Market Insights
IEC 61850 certification-grade hardware is reorganizing supplier hierarchies in the Overhead Line Fault Passage Indicator space. Schneider Electric leverages its substation automation ecosystem to extend indicator compatibility with digital relay platforms. Siemens anchors European utility procurement through its SICAM product architecture and localized manufacturing footprint. Horstmann GmbH specializes in compact magnetic-field sensing configurations for dense urban distribution networks.
An overhead line fault passage indicator is a sensor-mounted device installed on medium-voltage conductors to detect and signal fault current passage, typically rated for 6-36 kV systems with response thresholds between 50 A and 800 A. Its primary purpose is to accelerate fault location and reduce patrol-based restoration time in radial distribution feeders. Current monitoring indicators lead unit shipments due to their lower cost and compatibility with legacy recloser schemes, while communication system variants represent the fastest-expanding margin pool as utilities prioritize SCADA integration. Remote fault indicator demand concentrates in renewable energy end-user segments, where intermittent generation profiles complicate traditional fault detection logic.
Grid operators in Germany must comply with VDE-AR-N 4110 technical connection rules, which mandate fault location capabilities for distributed generation interfaces. India's Central Electricity Authority enforces distribution system standards that require fault indicators on rural feeders above 11 kV. Stakeholders must weigh cellular-versus-fiber communication commitments before procurement lock-in, as retrofit costs for protocol migration exceed initial hardware expenditure.
Market Dynamics
Utilities are replacing electromechanical fault indicators with IEC 61850-certified digital units that stream real-time current signatures to SCADA systems, compressing restoration windows from hours to minutes.
Growth Catalysts
- IEC 61850 Protocol Adoption:European grid operators under ENTSO-E guidelines mandate interoperable communication interfaces, forcing wholesale replacement of legacy indicators lacking digital relay compatibility.
- Rural Electrification Mandates:India's CEA distribution standards require fault passage indicators on all 11 kV and above rural feeders, creating sustained procurement volume through 2035.
- Magnetic-Field Sensing Arrays:Dense urban networks in Tokyo and Seoul deploy compact non-contact sensors that eliminate line loading interruptions during installation.
Market Restraints
- Cellular Module Cost Volatility:NB-IoT and LTE-M radio components from concentrated semiconductor fabs in Taiwan inflate bill-of-materials unpredictability.
- Single-Source Firmware Dependencies:Proprietary communication stacks from dominant European automation vendors create vendor lock-in and protocol migration friction.
- Technical Limitation in High-Impedance Faults:Ground fault detection below 50 A remains unreliable in compensated neutral networks, limiting deployment on certain 20 kV systems.
Strategic Opportunities
- Underpenetrated Brazilian Distribution:ANEEL's regulatory targets for SAIDI reduction have not yet translated to mandatory fault indicator procurement, leaving first-mover positioning open.
- Solar Farm Integration:Utility-scale photovoltaic clusters require directional fault indicators that distinguish inverter-fed faults from grid-side disturbances.
- Edge Computing Convergence:On-device machine learning inference enables localized fault classification without continuous backhaul to control centers.
Industry Challenges
- SCADA Integration Complexity:Legacy DMS platforms from 1990s-era deployments lack native DNP3 or IEC 61850 client capabilities, requiring expensive middleware development.
- Field Calibration Skill Scarcity:Proper threshold setting for current-reset indicators demands trained relay technicians, a workforce category shrinking across US cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Overhead Line Fault Passage Indicator Market |
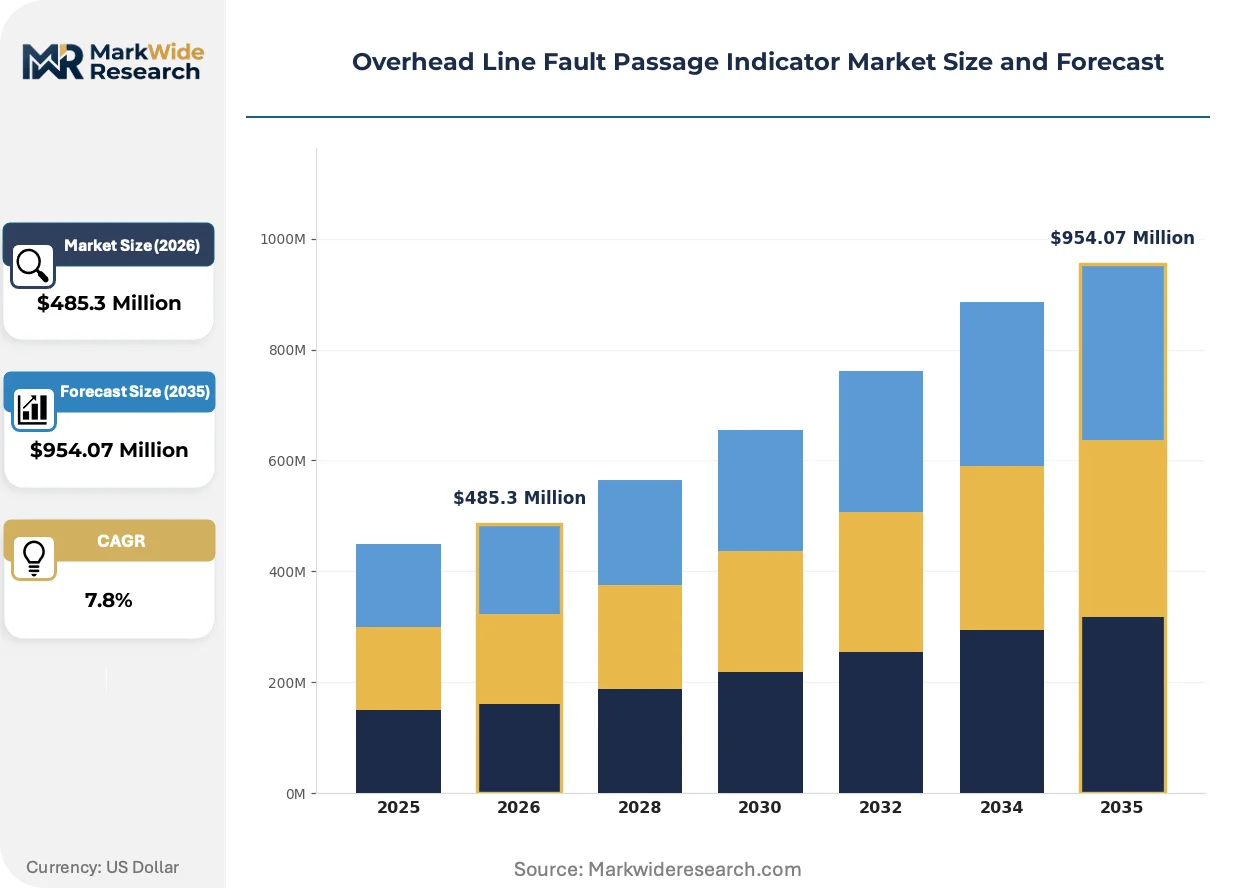
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $954.07 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Voltage Detection, Current Monitoring, Communication System, Remote Fault Indicator Technology: Optical Fiber, Magnetic Field, Sensor Technology, Hybrid Systems End User: Utilities, Infrastructure Operators, Industrial Plants, Renewable Energy Installation: Overhead Lines, Underground Lines, Substations, Distribution Networks |
| Companies Covered | Schneider Electric, Siemens AG, ABB Ltd., Eaton Corporation, Schweitzer Engineering Laboratories, Horstmann GmbH, Nortroll AS, S&C Electric Company, Cooper Power Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Overhead Line Fault Passage Indicator Market Trends and Innovations
Digitalization of medium-voltage distribution infrastructure is collapsing the distinction between standalone indicators and fully instrumented line sensors, reshaping how utilities budget for fault management hardware.
Self-powered harvesting from line current is fragmenting the auxiliary supply market for fault indicators. Units drawing operating power from 10 A minimum load currents eliminate battery maintenance cycles. German municipal utilities and Korean KEPCO subsidiaries are standardizing on these designs for remote mountain feeders. The technology is fragmenting supplier hierarchies as battery-dependent incumbents lose specification slots.
EU CSRD sustainability reporting requirements now capture embodied carbon in distribution hardware procurement. French Enedis and Italian Terna have added lifecycle assessment scoring to tender evaluations, favoring aluminum-housing indicators over resin-cast alternatives. Indicator manufacturers with ISO 14064-certified production facilities are securing multi-year framework agreements.
Asset-as-a-service contracting is displacing capital purchase models for fault indicator fleets. Nordic distribution system operators now lease indicator hardware with bundled cellular data and cloud analytics, transferring obsolescence risk to vendors. This restructuring concentrates most visibly in Denmark and Norway, where state-owned grid companies prioritize operational expenditure flexibility over balance-sheet ownership.
Overhead Line Fault Passage Indicator Market Segmentation
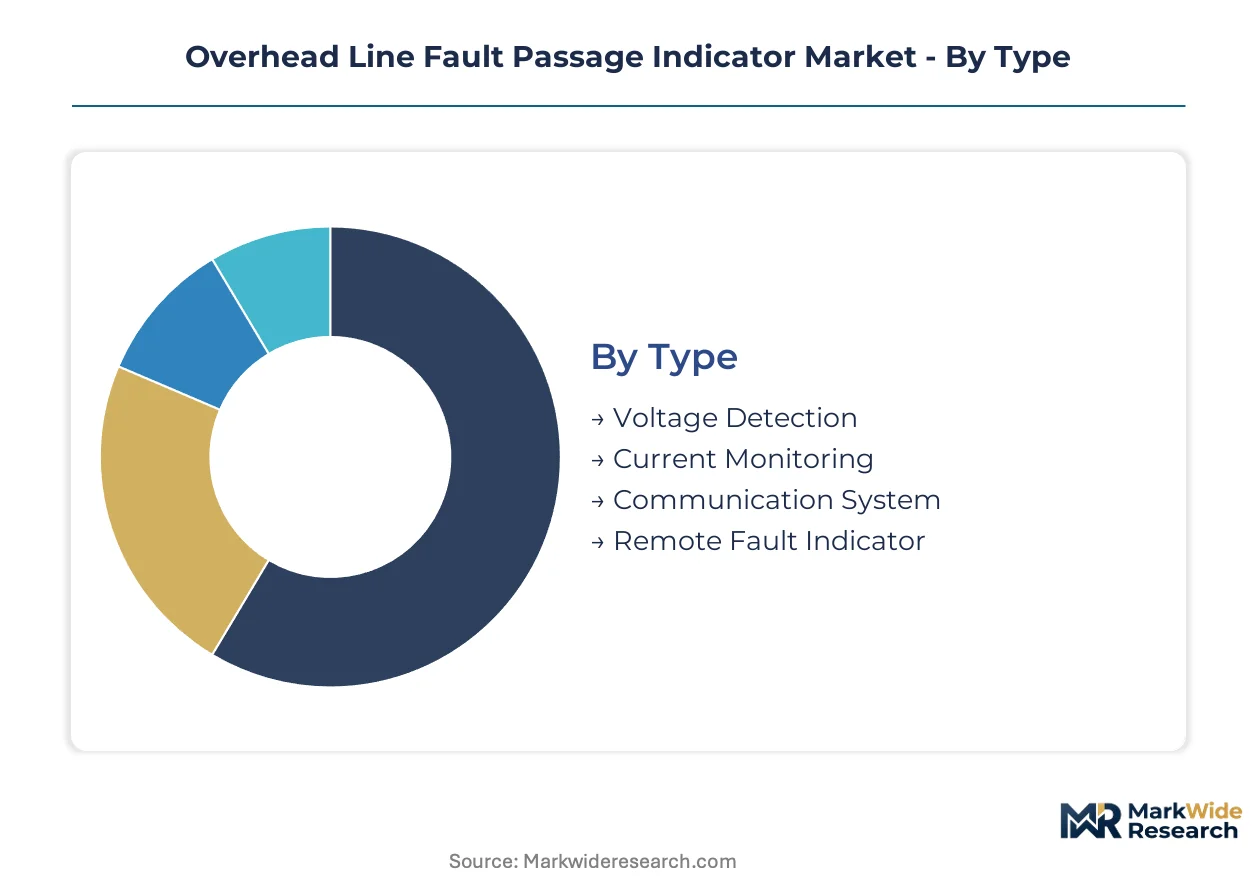
Fault passage indicator procurement splits across technical specifications, communication protocols, and deployment contexts. Each segmentation axis carries distinct regulatory implications and supplier qualification requirements that shape competitive positioning.
Type:
CEA distribution standards in India mandate specific detection thresholds for rural 11 kV feeders, while ENTSO-E guidelines in Europe prioritize SCADA interoperability over standalone functionality.
- Current Monitoring:Electromechanical and digital units detect fault current magnitude between 50 A and 800 A through direct conductor coupling. India's rural electrification programs specify these for cost-sensitive 11 kV feeder deployment where cellular backhaul remains uneven.
- Communication System:IEC 61850-certified digital indicators stream real-time current signatures with DNP3 or MMS protocol support. German municipal utilities under VDE-AR-N 4110 rules specify these for distributed generation interface points where inverter-fed faults complicate detection logic.
- Voltage Detection:Units sense electric field collapse during fault events without direct current transformer installation.
- Remote Fault Indicator:Battery or harvesting-powered devices with integrated NB-IoT/LTE-M radios for unmanned feeder segments.
Current Monitoring handles the majority of throughput; Communication System is the fastest mover on share.
Technology:
Cost tiers separate premium magnetic-field arrays from economy optical-fiber alternatives, with hybrid configurations occupying the mid-market specification band.
- Magnetic Field:Non-contact sensors measure induced magnetic flux from conductor current without line loading interruption. Tokyo and Seoul distribution operators specify Horstmann-style compact arrays for dense urban 22 kV networks where outage windows are measured in minutes.
- Hybrid Systems:Combined magnetic-field and voltage-sensing architectures enable directional fault classification for renewable integration. Utility-scale solar clusters in Gujarat and Rajasthan deploy these to distinguish inverter-fed faults from grid-side disturbances under CEA technical standards.
- Optical Fiber:Fiber-optic current sensors immune to electromagnetic interference for substation exit points.
- Sensor Technology:MEMS-based or Rogowski coil configurations for specialized measurement ranges.
Magnetic Field dominates unit economics; Hybrid Systems are expanding most quickly in specification slots.
End User:
Application context determines communication protocol requirements and maintenance cycle expectations across customer categories.
- Utilities:State and private distribution companies with SCADA integration mandates and multi-year framework procurement. Nordic operators in Denmark and Norway are shifting toward asset-as-a-service leasing models with bundled analytics.
- Renewable Energy:Solar and wind farm developers requiring directional fault indicators for point-of-interconnection compliance. Germany's VDE-AR-N 4110 technical connection rules mandate fault location capabilities that drive specification of communication-enabled units.
- Infrastructure Operators:Railway and highway electrification authorities with specialized reliability requirements.
- Industrial Plants:Captive power facilities with internal medium-voltage distribution prioritizing rapid fault isolation.
Utilities absorb the largest procurement volume; Renewable Energy is climbing the fastest on specification intensity.
Installation:
Physical deployment environment dictates housing specifications, auxiliary power options, and accessibility for calibration maintenance.
- Overhead Lines:Clamp-mounted or hot-stick installable units on bare or covered conductors. German and Korean operators standardize on self-powered harvesting designs for remote mountain feeders where battery replacement costs exceed hardware depreciation.
- Substations:Rack-mounted or panel-integrated indicators with direct CT/VT inputs for busbar and transformer protection zones.
- Underground Lines:Jacket-mounted or manhole-accessible sensors for cable fault location in urban trench networks.
- Distribution Networks:Pole-mounted or pad-mounted configurations for mixed overhead-underground feeders.
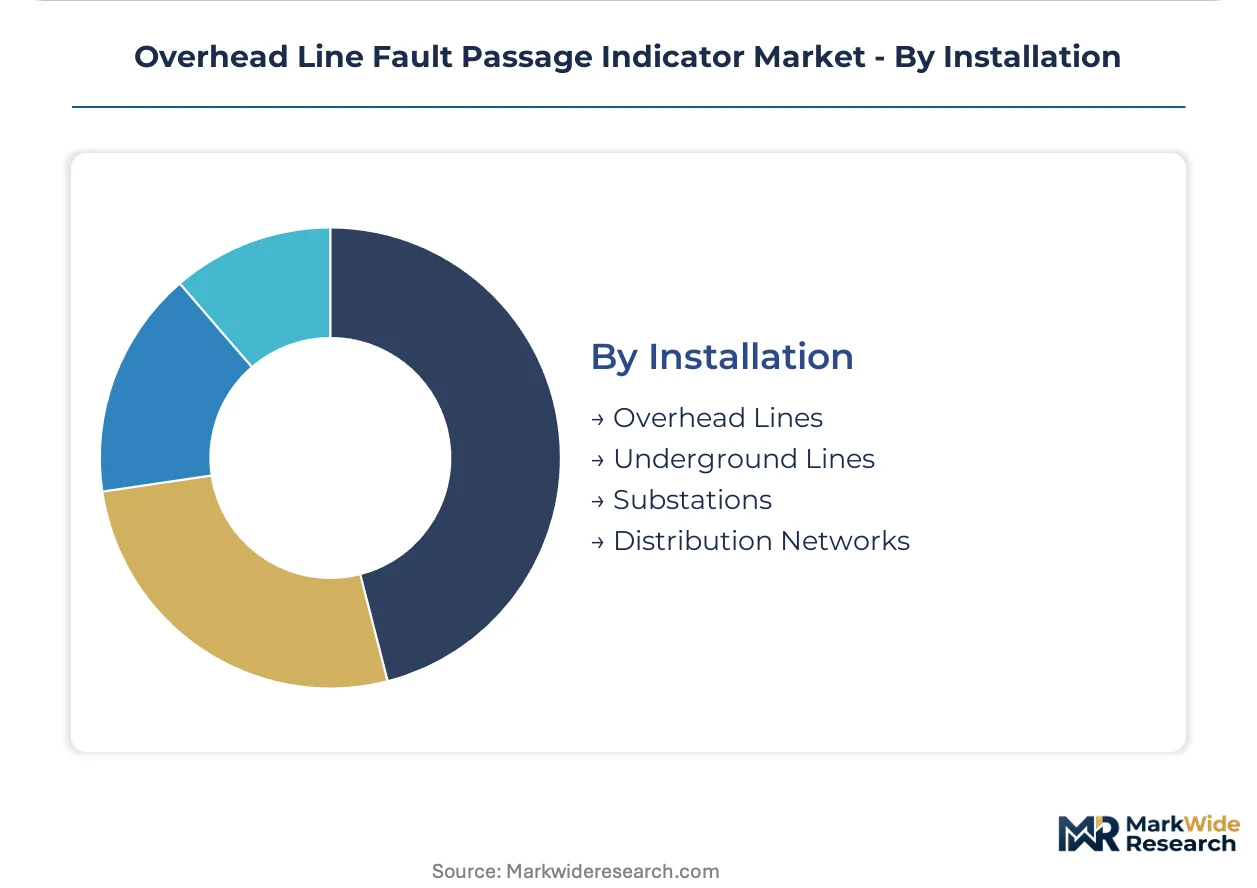
Overhead Lines carries the bulk of unit shipments; Substations command the steepest expansion trajectory on digitization investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Indian rural electrification programs prioritize cost-minimized current-monitoring units, while German utilities under VDE-AR-N 4110 rules absorb premium pricing for IEC 61850-certified communication systems.
India
Rural electrification mandates and distribution automation investments drive sustained procurement volume. The Central Electricity Authority enforces standards requiring fault indicators on all 11 kV and above rural feeders. Gujarat and Rajasthan host utility-scale solar clusters deploying directional fault indicators to distinguish inverter-fed faults from grid-side disturbances.
Germany
Distributed generation interfaces and municipal utility digitization programs accelerate technology replacement cycles. VDE-AR-N 4110 technical connection rules mandate fault location capabilities for renewable integration points. Municipal utilities in Bavaria and Baden-Württemberg standardize on self-powered harvesting designs for remote mountain feeders.
United States
Cooperative utility infrastructure modernization and wildfire risk mitigation programs expand specification slots. FERC Order 2222 and state-level reliability incentives push SCADA integration requirements. Pacific Northwest cooperatives face field calibration skill scarcity as trained relay technician workforces shrink.
Brazil
ANEEL regulatory targets for SAIDI reduction create first-mover positioning opportunities before mandatory procurement rules crystallize. Transmission and distribution concession renewals incorporate reliability performance clauses. São Paulo and Minas Gerais distribution operators pilot cellular-communicating indicator fleets on critical feeders.
Japan
Tokyo and Osaka dense urban networks demand compact non-contact sensor configurations minimizing outage windows during installation. METI grid resilience initiatives fund distribution automation upgrades. Kanto region operators deploy magnetic-field sensing arrays on 22 kV underground-overhead transition points.
Overhead Line Fault Passage Indicator Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the supplier base. European automation conglomerates anchor premium-tier positioning through substation ecosystem integration, while Asian fabricators compete on unit economics for price-sensitive emerging market procurement. Three archetypes dominate: integrated automation platforms, compact sensor specialists, and regional component fabricators. Strategic moves concentrate on protocol certification racing and cellular module supply partnerships.
Among European integrated platforms, Schneider Electric and Siemens AG exemplify ecosystem-extension strategies leveraging existing substation automation footprints. Horstmann GmbH occupies a specialist position within the compact sensor tier. These three anchors illustrate divergent competitive vectors: platform breadth versus application-specific miniaturization versus regional manufacturing proximity.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens AG |
| ABB Ltd. |
| Eaton Corporation |
| Schweitzer Engineering Laboratories |
| Horstmann GmbH |
| Nortroll AS |
| S&C Electric Company |
| Cooper Power Systems |
| Others |
Pricing and Supply Chain Analysis
Self-powered harvesting modules replacing battery-dependent architectures are simultaneously shifting procurement geography toward German and Korean municipal utilities and compressing after-sales service revenue pools that previously sustained margins. This substitution dynamic restructures supplier economics as maintenance-light designs eliminate recurring battery replacement contracts while rewarding manufacturers with ISO 14064-certified production facilities under EU CSRD sustainability reporting requirements.
Pricing Analysis
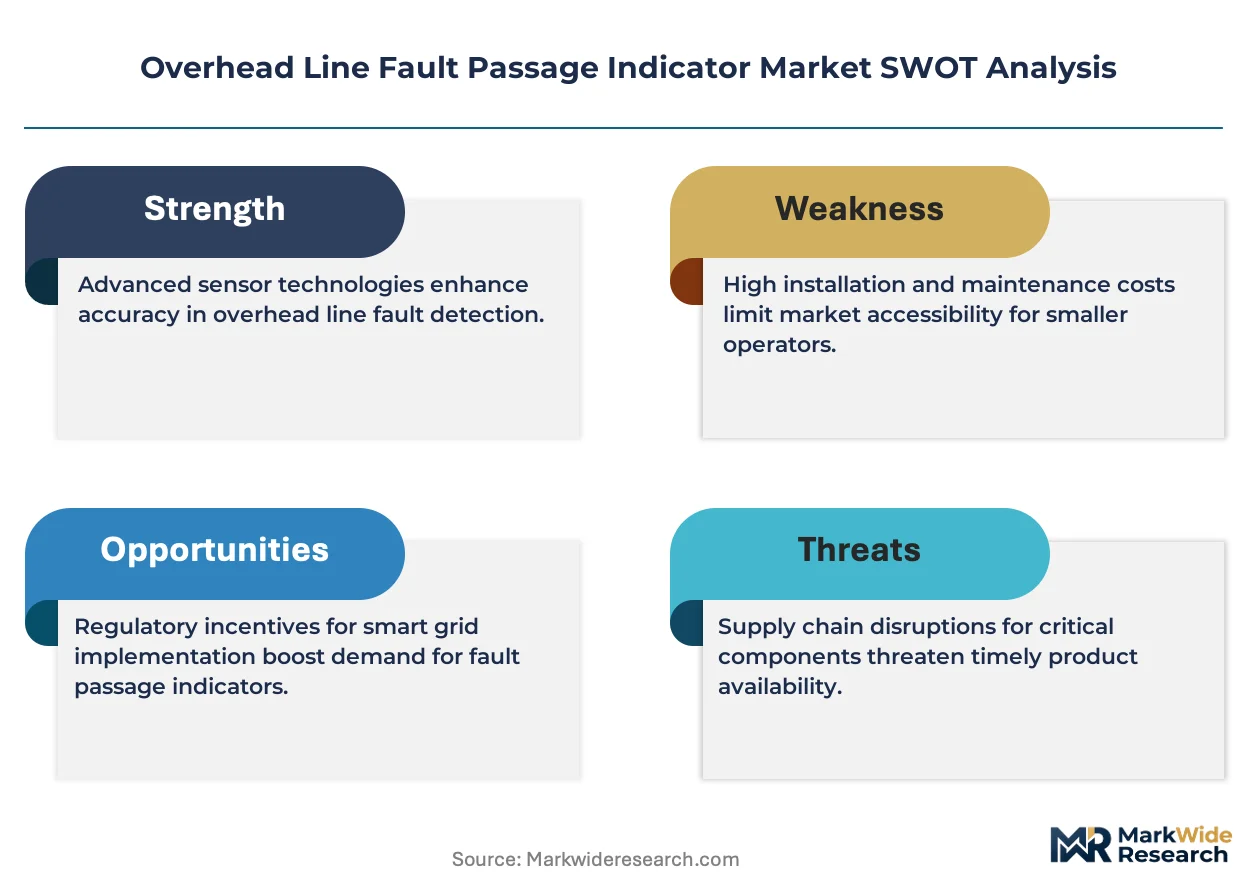
After-sales service contracts and extended warranty tiers now drive lifetime value differentiation as hardware margins compress on standardized IEC 61850-certified units. Three-tier pricing structure across premium communication-enabled systems, standard current-monitoring indicators, and economy electromechanical alternatives reflects certification grade and SCADA integration depth. Cost compression in the economy tier intensifies as Indian rural electrification programs consolidate procurement volume around bare-bones 11 kV specifications. Distribution cooperatives exhibit highest price sensitivity, while German municipal utilities under VDE-AR-N 4110 mandates absorb premium positioning for distributed generation interface compliance.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for NB-IoT and LTE-M radio components sourced from Taiwan semiconductor fabs. Manufacturing concentrates in Germany, China, and India, with magnetic-field sensor arrays and cellular communication modules representing critical input dependencies. Single-source vulnerability in proprietary firmware stacks from European automation vendors creates protocol migration friction and vendor lock-in exposure. Distribution runs through utility framework agreements and direct OEM procurement channels, with Nordic asset-as-a-service leasing models transferring hardware ownership risk to vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as IEC 61850 protocol mandates force wholesale replacement of legacy indicators lacking digital relay compatibility, creating sustained replacement demand through 2035.
For Market Incumbents: Shield specification slots by accelerating certification investment for IEC 61850-9-2LE process bus compatibility and securing captive supply of self-powered harvesting components through backward integration into magnetic sensor manufacturing. Vertically integrated European automation platforms face emerging entrant pressure from Asian fabricators competing on unit economics for Indian rural electrification procurement. For New Entrants and Emerging Players: Cloud analytics and predictive maintenance service layers represent underexploited white space where incumbents under-serve Nordic distribution operators shifting toward operational expenditure models. Brazil's ANEEL regulatory targets for SAIDI reduction offer the most penetrable geography before mandatory procurement rules crystallize. Partner with cellular module suppliers to bundle connectivity and hardware in subscription-based offerings. For Investors and Strategic Acquirers: India's CEA distribution standards reshapes the acquisition landscape by mandating fault indicators on all 11 kV and above rural feeders, creating predictable procurement volume visibility. Target compact sensor specialists with magnetic-field array expertise and established relationships with Tokyo or Seoul distribution operators. Monitor IEC 61850 certification completion rates as the signal for technology replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Self-Powered Harvesting Technology Migration | Eliminates battery maintenance cycles for German and Korean mountain feeder deployments. |
| IEC 61850-9-2LE Process Bus Certification | Secures interoperability with Schneider and Siemens digital relay platforms. |
| Asset-as-a-Service Contracting Model | Captures Nordic operational expenditure shift away from capital purchase frameworks. |
| ISO 14064 Production Facility Certification | Qualifies suppliers for French Enedis and Italian Terna lifecycle assessment scoring. |
| Edge Computing Convergence Development | Enables localized fault classification without continuous SCADA backhaul dependency. |
Research Methodology
The analysis maps current monitoring, communication system, voltage detection, and remote fault indicator sub-sectors, each validated through utility planning officers, distribution automation engineers, OEM procurement teams, and aftermarket service heads. Primary interviews with grid operators across German municipal utilities, Indian state distribution companies, and Nordic system operators combined with secondary validation from CEA distribution standards documentation, ENTSO-E interoperability guidelines, VDE-AR-N 4110 technical connection rules, and IEC 61850 certification registries. Bottom-up unit shipment estimates triangulated against top-down infrastructure investment forecasts.
Consistency checks validated volume and value outputs against utility capital expenditure disclosures, smart grid deployment databases, and renewable energy interconnection filings across the projection horizon. Segmentation dimensions modeled include indicator type, sensing technology, end-user category, and installation environment alongside communication protocol adoption patterns. CAGRs derived from replacement cycle analysis of legacy electromechanical stock and penetration rate assumptions for digital units. Forecast inputs incorporate rural electrification program timelines and distributed generation interface mandates.
Underlying assumptions cover IEC 61850 adoption velocity, cellular module cost trajectories, and utility procurement centralization trends, with deviation risk concentrated in regulatory delay for Brazilian ANEEL mandatory rules and workforce scarcity for US cooperative field calibration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Heat Interface Unit Market