
 Japan High Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Japan High Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Japan High Voltage Direct Current (HVDC) Transmission Systems Market Foresight
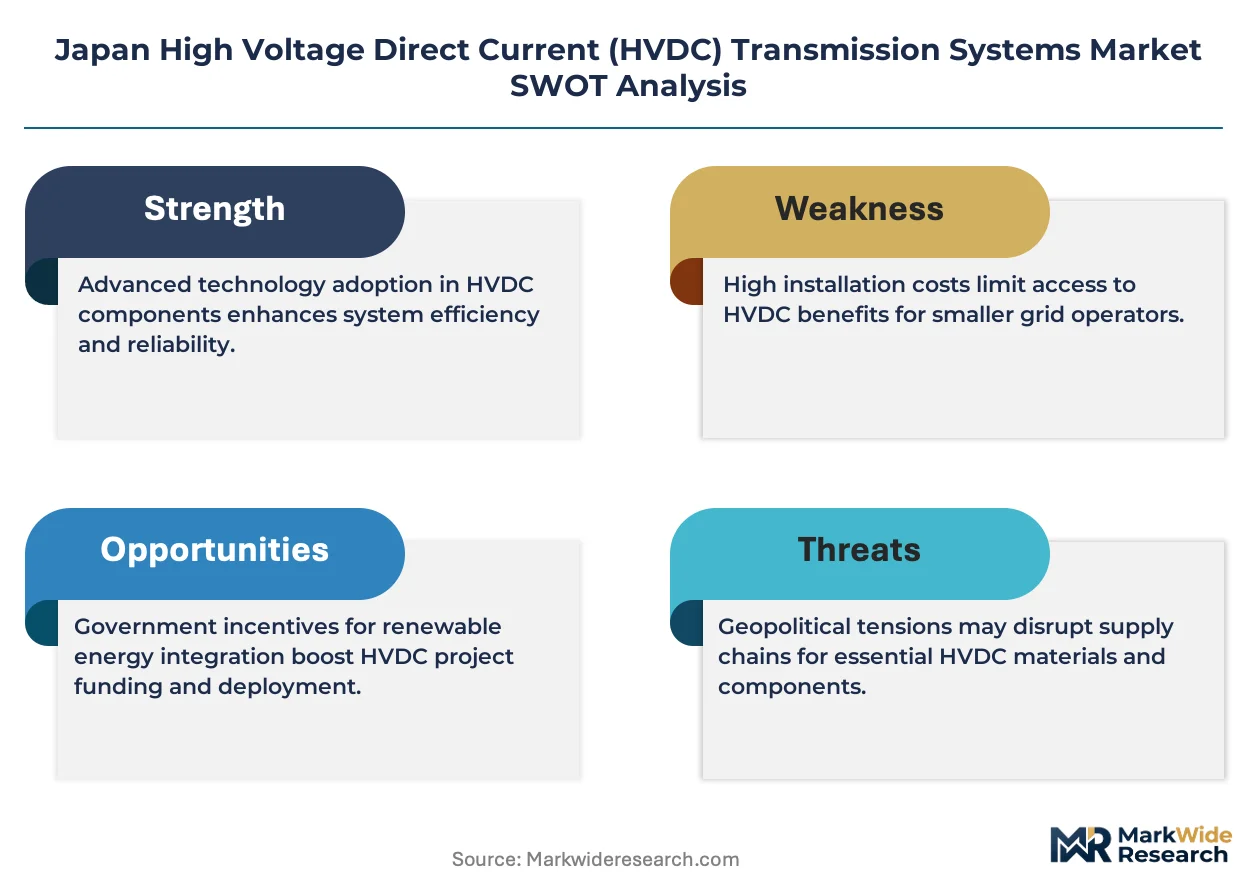
Japan's Sixth Strategic Energy Plan is recalibrating utility procurement toward inter-island HVDC corridors. Toshiba Corporation leverages its thyristor valve manufacturing heritage to anchor domestic converter station supply. Mitsubishi Electric Corporation competes through integrated gate commutated thyristor technology leadership. Hitachi Energy Ltd extends its footprint across offshore wind grid connections through specialized cable system integration.
High Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity across distances exceeding conventional AC economical limits, typically operating at voltages above 100 kV with line-commutated or voltage-source converter topologies. Converter stations dominate capital deployment due to semiconductor valve halls and filter banks comprising the majority of project cost. Voltage Source Converter technology is displacing line-commutated systems in subsea applications where black-start capability and compact footprint command premium positioning. Multi-Terminal DC configurations are attracting development capital for meshed offshore grids connecting dispersed wind arrays to multiple onshore landing points.
METI enforces grid codes through the Organization for Cross-regional Coordination of Transmission Operators while JIS standards govern equipment interoperability and seismic resilience requirements. The Electricity Business Act revisions mandate enhanced inter-regional transmission capacity, directly expanding HVDC project pipelines between Okinawa, Kyushu, and Honshu. Stakeholders must monitor feed-in tariff phase-out schedules and cross-regional transmission pricing reforms to time converter station deployment commitments.
Market Dynamics
Voltage Source Converter technology is rewriting procurement criteria for subsea cable projects, while METI's inter-regional transmission mandates force utilities to accelerate converter station deployment schedules across Japan's island archipelago.
Growth Catalysts
- Offshore wind clusters:Kyushu and Hokkaido developers are procuring subsea HVDC links to connect remote generation sites to Honshu load centers, creating sustained demand for converter station infrastructure.
- METI feed-in tariff revisions:Renewable energy pricing reforms are accelerating grid interconnection investments by independent power producers seeking guaranteed offtake agreements.
- Multi-Terminal DC configurations:Meshed offshore grid architectures are attracting development capital for connecting dispersed wind arrays to multiple onshore landing points.
Market Restraints
- Semiconductor valve cost concentration:Thyristor and IGBT supply chains concentrate among limited Asian foundry sources, exposing converter station budgets to input volatility.
- Seismic resilience engineering:JIS standards mandate specialized civil works for valve halls and filter banks, inflating capital intensity versus comparable European installations.
- Line-commutated converter obsolescence:Legacy LCC technology faces substitution pressure from VSC systems with black-start capability, stranding technical expertise in incumbent utilities.
Strategic Opportunities
- Okinawa interconnection gap:The southern island chain lacks robust HVDC links to mainland grids, representing underpenetrated territory for corridor development.
- Integrated cable-converter packages:Specialized system integration combining subsea cable laying with converter station commissioning is emerging as a differentiated service model.
- Electricity Business Act capacity mandates:Enhanced inter-regional transmission requirements create regulatory tailwinds for projects linking Kyushu, Shikoku, and Honshu.
Industry Challenges
- Power electronics specialist scarcity:Converter station commissioning requires expertise in harmonic filtering and reactive power management that outpaces domestic training pipeline output.
- Cross-regional transmission pricing uncertainty:Japan's Organization for Cross-regional Coordination of Transmission Operators has yet to finalize cost allocation frameworks, delaying project financial commitments.
- Legacy AC grid synchronization:Converter stations must integrate with 50Hz eastern and 60Hz western Japanese grids, complicating control system design and testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan High Voltage Direct Current (HVDC) Transmission Systems Market |
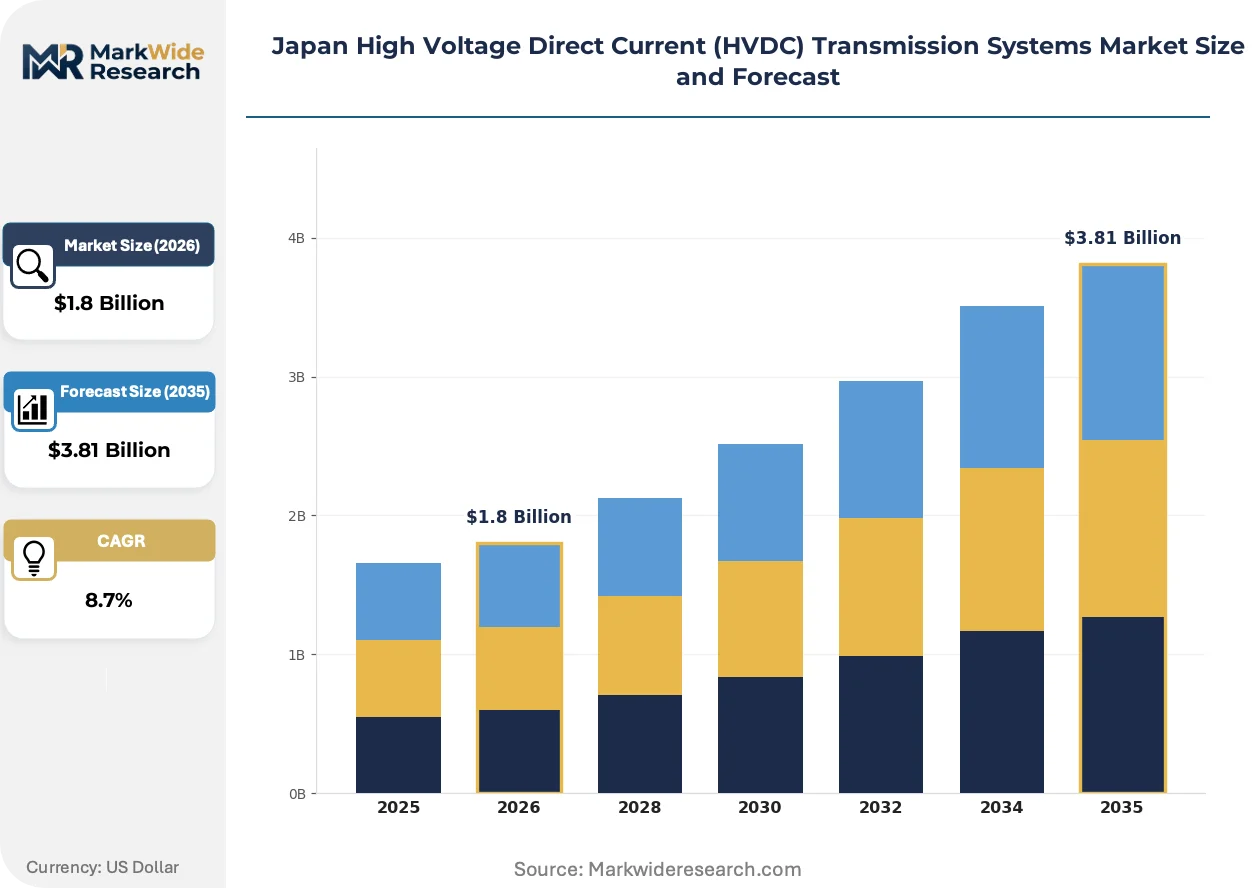
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Converter Stations, Inverters, Control Systems, Transformers Technology: Voltage Source Converter, Current Source Converter, Integrated Converter, Multi-Terminal DC End User: Utilities, Industrial, Offshore Wind, Renewable Energy Installation: Onshore, Offshore, Hybrid Systems, Upgrades |
| Companies Covered | Toshiba Corporation, Mitsubishi Electric Corporation, Sumitomo Electric Industries Ltd, Hitachi ABB Power Grids Ltd, Hitachi Energy Ltd, Toshiba Energy Systems, Hitachi Ltd, LS Electric, NKT A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan High Voltage Direct Current (HVDC) Transmission Systems Market Shifts & Advancements
Modular VSC platform architectures are compressing converter station deployment timelines, while METI's grid code enforcement drives standardization across Japan's historically balkanized regional utilities. These forces are converging to reshape equipment procurement and system integration practices.
Silicon carbide power semiconductors are rewriting thermal management requirements for high-voltage valve halls. Offshore wind developers in the Sea of Japan are piloting these devices at 350kV ratings to reduce cooling infrastructure footprint. The technology is compressing substation land requirements by approximately one-third versus conventional silicon IGBT installations.
METI's Sixth Strategic Energy Plan revisions mandate enhanced inter-regional transmission capacity between Okinawa, Kyushu, and Honshu. The Electricity Business Act amendments require utilities to publish ten-year corridor development schedules, forcing converter station procurement into synchronized tender cycles. Transmission operators are responding by consolidating valve hall contracts into multi-project framework agreements.
Long-term availability contracts are displacing traditional equipment-only procurement for subsea cable systems. Japanese offshore wind consortia now require fifteen-year service agreements covering cable monitoring, fault location, and repair vessel mobilization. This pattern is most visible in the Kyushu region, where developers face exposure to typhoon-induced cable damage and extended marine weather windows.
Japan High Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
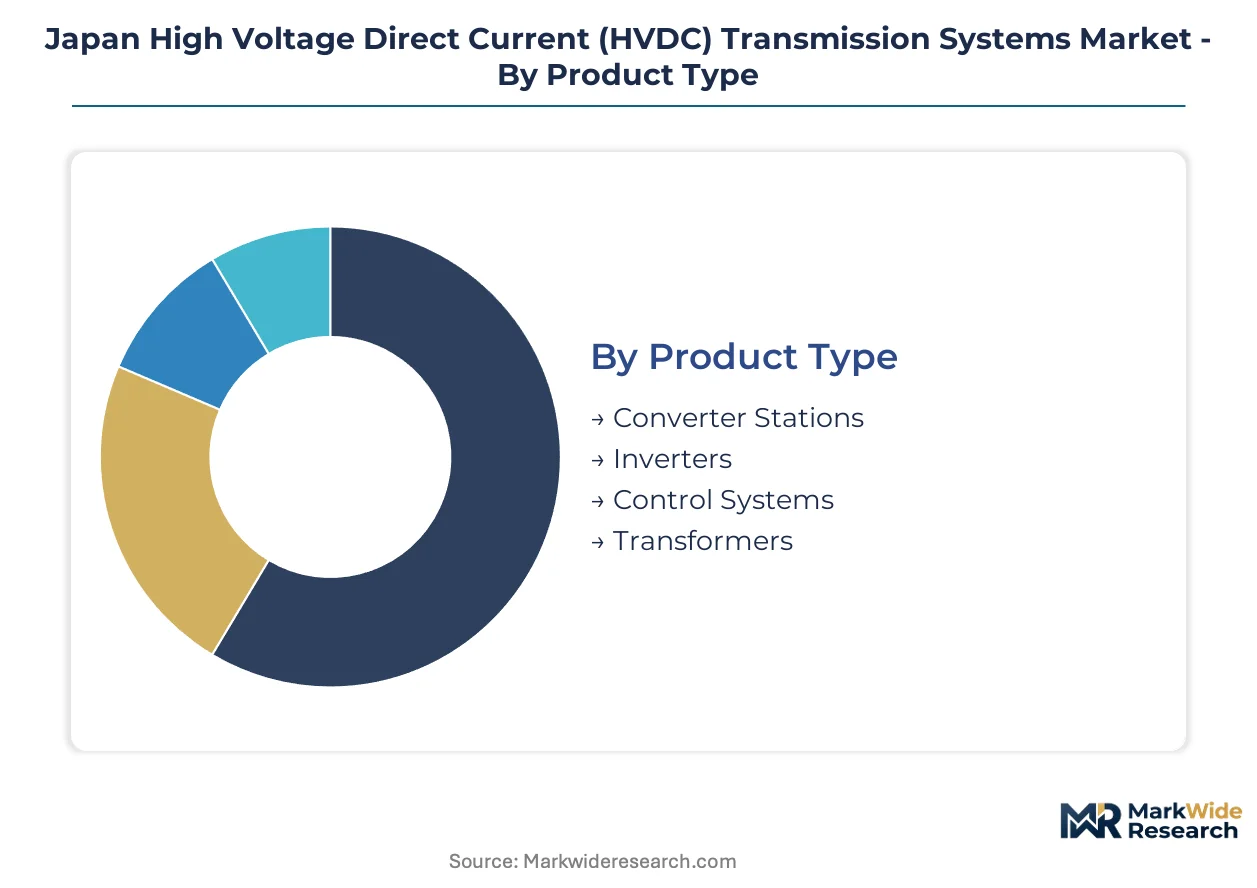
Segmentation reveals how procurement priorities diverge across Japan's island archipelago. Converter station specifications vary sharply between seismic-resistant onshore installations and compact offshore platforms. Technology choices map directly to METI's inter-regional transmission mandates and the grid codes enforced by the Organization for Cross-regional Coordination of Transmission Operators.
Product Type:
Replacement cycles for valve hall equipment are compressing as VSC technology obsoletes line-commutated systems, forcing utilities to rebalance capital deployment across component categories.
- Converter Stations:Semiconductor valve halls and filter banks dominate project economics, with thyristor and IGBT stacks requiring specialized seismic isolation per JIS standards. Procurement concentrates in Kyushu and Hokkaido where remote renewable clusters demand long-distance DC links to Honshu load centers, driven by METI's feed-in tariff phase-out schedules.
- Inverters:Power electronic modules convert DC transmission levels to grid-synchronous AC, with black-start capability now mandatory for offshore applications. Industrial facilities in western Japan's 60Hz zone procure these for factory-scale renewable integration, constrained by harmonic filtering requirements.
- Control Systems:Real-time monitoring platforms manage reactive power flow and grid synchronization across Japan's bifurcated 50Hz/60Hz network.
- Transformers:Converter transformers interface between AC collection networks and DC valve halls, with oil-immersed designs prevailing in onshore installations.
Converter Stations sits at the top of the volume ranking, with Control Systems climbing the fastest as digital grid management becomes critical for multi-terminal configurations.
Technology:
Cost tiering separates mature line-commutated infrastructure from premium VSC platforms commanding 40-60% capital premiums for black-start and compact footprint capabilities.
- Voltage Source Converter:Self-commutating IGBT or silicon carbide switches enable independent reactive power control and grid-forming capability. Subsea cable projects in the Sea of Japan specify VSC for offshore wind connections to Honshu, driven by METI's offshore wind auction rounds and typhoon-resilience requirements.
- Current Source Converter:Thyristor-based line-commutated designs persist in legacy interconnections where existing filter banks and harmonic compensation infrastructure represent sunk capital.
- Integrated Converter:Factory-assembled skid-mounted systems compress commissioning timelines for remote island installations.
- Multi-Terminal DC:Meshed grid architectures connect dispersed generation to multiple onshore landing points, with Okinawa interconnection studies evaluating three-terminal configurations linking the southern island chain to Kyushu.
Voltage Source Converter commands the dominant share of new procurement value, with Multi-Terminal DC gaining share fastest as meshed offshore grids advance from pilot to commercial scale.
End User:
Application-specific requirements fragment procurement specifications, with offshore wind developers demanding integrated cable-converter packages unavailable to traditional utility buyers.
- Utilities:Regional transmission operators procure converter stations under Electricity Business Act mandates, with ten-year corridor schedules synchronizing tender cycles across Kyushu Electric, Hokkaido Electric, and Okinawa Electric.
- Industrial:Steel and chemical facilities deploy medium-voltage DC links for process power quality, constrained by site-specific harmonic limits.
- Offshore Wind:Consortia in the Kyushu region require fifteen-year service agreements covering cable monitoring and repair vessel mobilization, driven by exposure to typhoon damage and extended marine weather windows.
- Renewable Energy:Independent power producers accelerate grid interconnection investments ahead of feed-in tariff revisions, with geothermal and solar clusters in Hokkaido procuring dedicated DC links.
Utilities anchor procurement volume, with Offshore Wind expanding most quickly as METI's sixth strategic energy plan prioritizes marine renewable capacity.
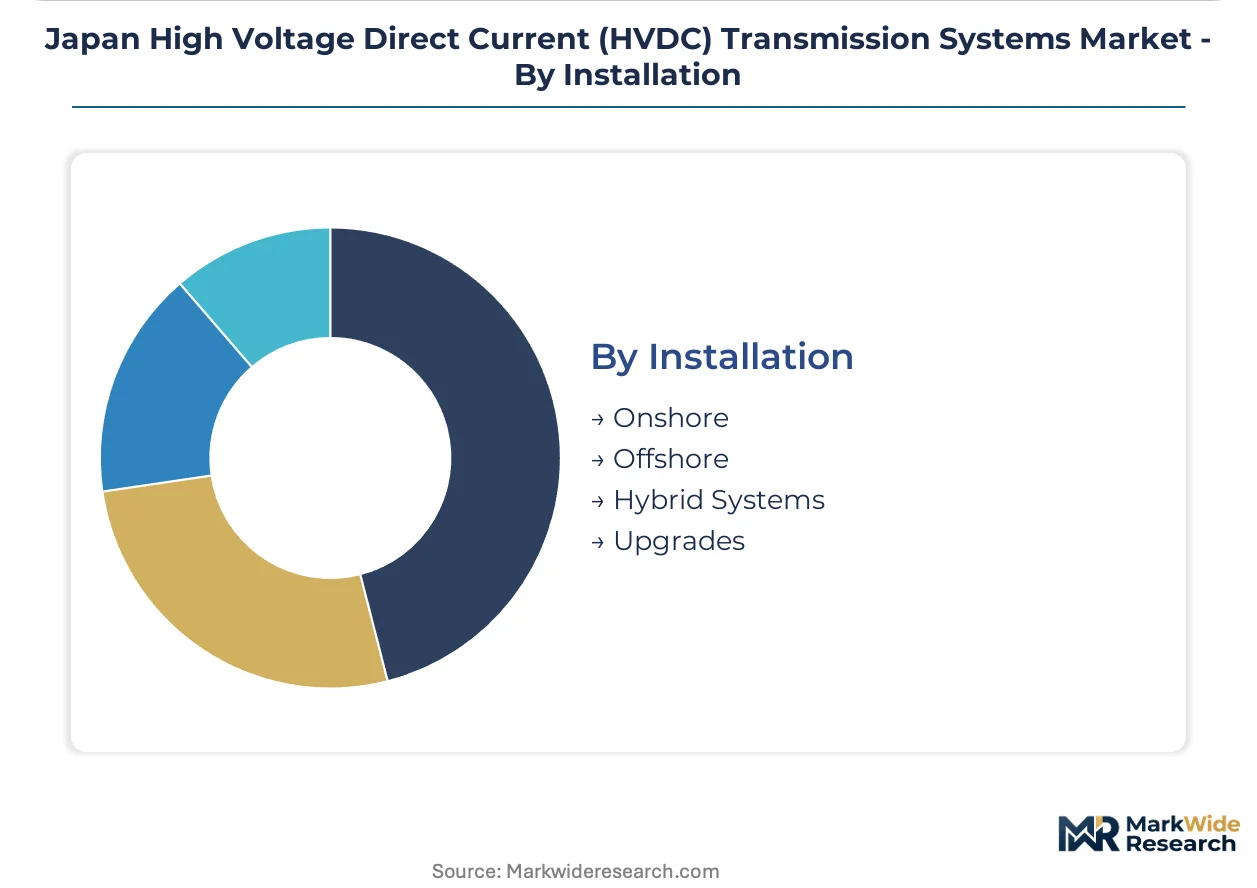
Installation:
Geography dictates civil works intensity, with seismic resilience engineering inflating Japanese onshore capital intensity versus comparable European installations.
- Onshore:Converter stations in earthquake-prone regions require base isolation systems and redundant cooling, with JIS standards mandating specialized valve hall construction that extends commissioning timelines.
- Offshore:Platform-mounted installations in the Sea of Japan and Pacific coast employ compact VSC designs to minimize topside weight, driven by jacket foundation cost constraints and typhoon loading specifications.
- Hybrid Systems:Combined onshore-offshore configurations integrate subsea cables with coastal converter stations, with the Kyushu-Honshu corridor evaluating hybrid architectures.
- Upgrades:Legacy LCC station retrofits to VSC capability involve complete valve hall replacement, with western Japan utilities assessing upgrade economics against greenfield construction.
Onshore installations retain the largest installed base, with Offshore deployments showing the steepest expansion trajectory as subsea cable project pipelines mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's power electronics engineering talent clusters in Kanto and Kansai industrial corridors, with converter station specialists concentrated at Toshiba and Mitsubishi Electric heritage facilities. This workforce distribution shapes regional procurement patterns and technology transfer pathways across the archipelago.
Kanto/Tokyo
Tokyo Electric Power and Chubu Electric operate the densest concentration of converter stations serving the 50Hz eastern grid. METI's Sixth Strategic Energy Plan mandates enhanced inter-regional capacity linking Kanto to western Japan through DC back-to-back stations. Yokohama-based engineering consultancies coordinate procurement frameworks for multi-terminal DC projects.
Kansai/Osaka
Kansai Electric maintains legacy line-commutated converter infrastructure at Sakaguchi and Minami-Iwaki interconnections. The 60Hz western grid requires specialized synchronization equipment for cross-regional DC links. Osaka industrial zones drive demand for medium-voltage DC systems in steel and chemical process applications.
Kyushu
Offshore wind developers in the Genkai Sea and Goto Islands region procure subsea HVDC links to transmit renewable generation to Honshu load centers. Kyushu Electric operates converter stations at Kanmon and Hikoshima supporting interconnection with Chugoku Electric. METI feed-in tariff revisions accelerate independent power producer investments in dedicated DC export corridors.
Hokkaido
Hokkaido Electric manages the Shinshinotsu-Tomakomai HVDC link connecting wind-rich northern zones to the Honshu grid. Geothermal and solar clusters in Yufutsu and Shimamaki require long-distance transmission infrastructure. JIS seismic standards govern valve hall construction across earthquake-prone coastal installations.
Okinawa
Okinawa Electric operates isolated grid infrastructure with limited interconnection to mainland systems. The southern island chain represents underpenetrated territory for three-terminal DC configurations linking to Kyushu. METI studies evaluate meshed offshore grid architectures connecting dispersed renewable arrays to multiple landing points.
Japan High Voltage Direct Current (HVDC) Transmission Systems Market Competitive Landscape
Capital-heavy producers with captive semiconductor foundry relationships compete with asset-light system integrators outsourcing valve stack manufacturing. The market structure consolidates around three domestic conglomerates controlling thyristor and IGBT converter technology. Strategic archetypes separate integrated equipment manufacturers, specialized cable system providers, and offshore wind turnkey contractors. Dominant competitive moves include multi-project framework agreements for valve hall contracts and fifteen-year service agreements covering subsea cable monitoring.
Among domestic integrated manufacturers, Toshiba Corporation, Mitsubishi Electric Corporation, and Hitachi Energy Ltd anchor the converter station supply base. Toshiba leverages thyristor valve manufacturing heritage at legacy facilities. Mitsubishi Electric occupies a position defined by power electronics module integration capabilities. Hitachi Energy exemplifies the cable-converter system integration archetype through specialized offshore wind project execution. Sumitomo Electric Industries Ltd represents the specialized cable manufacturing tier with subsea laying and repair vessel capabilities. LS Electric and NKT A/S sit within the international supplier segment addressing technology gaps in domestic valve stack production.
| Leading Market Players |
|---|
| Toshiba Corporation |
| Mitsubishi Electric Corporation |
| Sumitomo Electric Industries Ltd |
| Hitachi ABB Power Grids Ltd |
| Hitachi Energy Ltd |
| Toshiba Energy Systems |
| Hitachi Ltd |
| LS Electric |
| NKT A/S |
| Others |
Supply & Pricing Matrix
Silicon carbide wafer price indices cascade through Japan's HVDC valve hall supply chain, compressing margins at IGBT stack assemblers while amplifying pricing power for foundries with captive SiC crystal growth. Converter station procurement stratifies between premium VSC platforms commanding integrated service bundles and economy-tier LCC retrofits competing on equipment-only tenders.
Pricing Analysis
Bundled fifteen-year service agreements now capture forty to sixty percent of total contract value in offshore wind applications, while unbundled equipment-only procurement persists among regional utilities with in-house maintenance capabilities. Price differentiation hinges on black-start certification tier and seismic resilience grade per JIS standards, with typhoon-rated subsea cable packages carrying substantial premiums. Pricing pressure stems from semiconductor foundry concentration in Taiwan and South Korea, where input volatility transmits directly to converter station budgets. Industrial offtakers in western Japan's 60Hz zone exhibit highest price sensitivity due to process power quality alternatives, while Okinawa Electric and remote island utilities demonstrate lowest sensitivity given interconnection dependency.
Supply Chain Analysis
Power electronics engineering talent scarcity in Kanto and Kansai industrial corridors constrains valve stack manufacturing throughput, forcing Toshiba and Mitsubishi Electric to prioritize domestic converter station commitments over export orders. Thyristor and IGBT sourcing concentrates in Japan, Germany, and the United States, with silicon carbide substrates drawing from emerging North American and European crystal growth facilities. Supply chain risk centers on single-source vulnerability for 300mm SiC wafers qualified to HVDC voltage ratings. Distribution runs through multi-project framework agreements consolidating valve hall contracts across Kyushu, Hokkaido, and Okinawa corridor developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's HVDC market offers margin expansion through silicon carbide adoption curves and integrated cable-converter service bundling, with cost-down trajectories in power semiconductor thermal management enabling premium-tier positioning.
For Market Incumbents: Lock in multi-terminal DC framework agreements before METI finalizes cross-regional transmission pricing, securing valve hall commitments across the Kyushu-Honshu-Okinawa corridor pipeline. Deepen backward integration into silicon carbide substrate sourcing to defend margin position against foundry price volatility, while accelerating IGCT R&D to preempt Hitachi Energy's offshore wind system integration dominance. For New Entrants and Emerging Players: Specialized cable monitoring and repair vessel operators represent an underserved buyer archetype in the Kyushu offshore wind cluster, where fifteen-year availability contracts lack qualified domestic bidders. Target Okinawa three-terminal DC feasibility studies with compact VSC platform offerings, leveraging modular skid-mounted designs to compress commissioning timelines versus incumbent greenfield construction. For Investors and Strategic Acquirers: Asymmetric upside sits with cable-converter system integrators possessing subsea laying capabilities and converter station commissioning expertise, as METI's inter-regional mandates synchronize tender cycles into consolidated procurement waves. Monitor METI feed-in tariff phase-out schedules as the inflection signal for independent power producer grid interconnection investment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Terminal DC Framework Agreements | Consolidates valve hall procurement across Kyushu, Hokkaido, and Okinawa corridor developments under synchronized tender cycles. |
| Silicon Carbide Vertical Integration | Captures SiC substrate cost-down trajectories while securing supply priority for 350kV-rated HVDC valve stacks. |
| Integrated Cable-Converter Service Bundling | Combines subsea cable laying with fifteen-year availability contracts to differentiate from equipment-only competitors. |
| Seismic Resilience Certification Investment | Meets JIS valve hall construction standards mandatory for onshore installations in earthquake-prone regions. |
| Okinawa Interconnection Development | Addresses underpenetrated territory for three-terminal DC configurations linking the southern island chain to Kyushu. |
Research Methodology
Coverage spans Japan's five grid regions, with primary inputs from each territory's transmission operators and offshore wind developers. The analysis combines structured interviews with utility planning officers, IPP project developers, EPC contractors, and power electronics procurement leads with secondary validation through METI policy filings, the Organization for Cross-regional Coordination of Transmission Operators grid code disclosures, and JIS standards documentation. Bottom-up project pipeline aggregation triangulates against top-down equipment demand estimates from semiconductor valve manufacturers.
Segmentation granularity extends to converter station component categories, technology topology choices, end-user procurement archetypes, and installation geography across the projection horizon. CAGRs derive from weighted capacity buildout schedules and equipment replacement cycles, with explicit modeling of VSC substitution rates for legacy LCC infrastructure and multi-terminal DC adoption curves in offshore wind applications.
Underlying measurement precision varies by segment; converter station deployments carry tighter precision than control systems due to visible tender documentation, while Okinawa interconnection studies reflect greater uncertainty pending METI corridor feasibility completion. Forecasts embed assumptions regarding feed-in tariff revision timing and cross-regional transmission pricing finalization. Material deviation in METI policy implementation schedules or SiC substrate supply expansion warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Power Transmission Cables Market
Transmission and Distribution
Natural Gas Refueling Infrastructure Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Global Industrial Distribution Market