
 Global Virtual Pipeline Systems Market | 2026-2036
Global Virtual Pipeline Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Virtual Pipeline Systems Market Outlook
The price-performance gap between premium cryogenic systems and standard compressed natural gas tube trailers is hardening as end users segment procurement by delivery reliability requirements. Chart Industries leverages its integrated liquefaction and storage portfolio to dominate cryogenic virtual pipeline deployments across North American shale plays. Hexagon Composites ASA anchors the lightweight composite pressure vessel segment, sustaining manufacturing scale advantages in Type 4 cylinder production for mobile CNG distribution.
Virtual pipeline systems transport natural gas, hydrogen, or biogas via road, rail, or marine vessels using high-pressure tube trailers, cryogenic tankers, or ISO containers rather than fixed physical pipeline infrastructure, typically operating at pressures between 250 and 300 bar for compressed gas or minus 162 degrees Celsius for LNG to maintain product density and economic transport viability. The technology dimension shows compression systems commanding the largest installed base while monitoring solutions represent the fastest structural expansion as telemetry and leak detection become mandatory for fleet insurance and regulatory compliance. Liquefied natural gas product types retain margin concentration in premium remote power and marine bunkering applications, whereas compressed natural gas competes aggressively on unit economics for industrial manufacturing end users with predictable offtake profiles.
The US DOT PHMSA and EPA jointly govern cylinder recertification intervals and transport emissions thresholds, directly shaping fleet replacement cycles and equipment capital planning for operators. Europe's F-Gas Regulation and impending EU methane emissions standards are forcing technology transitions toward lower-venting compression and vapor recovery systems across deployed infrastructure. Stakeholders must weigh stranded asset risk in stationary CNG against mobile hydrogen-ready platform investments as fuel flexibility becomes the decisive procurement criterion.
Market Dynamics
The US DOT PHMSA cylinder recertification mandate is compressing fleet replacement cycles across North American operators, forcing capital redeployment toward hydrogen-ready platform investments ahead of fixed-pipeline economics.
Growth Catalysts
- Australia LNG hub repurposing:Export terminal infrastructure is redirecting liquefaction capacity toward domestic virtual pipeline distribution corridors serving regional Queensland and Western Australia industrial zones.
- EU F-Gas Regulation phase-down:The 2024-2030 refrigerant containment rules are accelerating vapor recovery system retrofits across European cryogenic transport fleets, creating equipment refresh demand.
- Remote mining electrification:Off-grid mineral processing facilities in Chilean Atacama and Canadian Arctic are procuring virtual pipeline gas-to-power systems where grid extension costs exceed $3 million per kilometer.
Market Restraints
- Composite cylinder feedstock concentration:Carbon fiber precursor supply concentrates in Japan and Germany, exposing Type 4 pressure vessel manufacturers to acrylonitrile price volatility and export license delays.
- Cryogenic boil-off technical ceiling:LNG tanker systems face inherent thermodynamic limits near 0.15% daily loss rates, constraining delivery radius economics for routes exceeding 72 hours.
- US EPA transport emissions friction:The 2027 heavy-duty truck NOx standards impose retrofit costs on tube trailer prime movers, narrowing margin pools for regional CNG distributors.
Strategic Opportunities
- India industrial corridor buildout:The Petroleum and Natural Gas Regulatory Board's 2025 city gas distribution licensing round opens 52 new geographical areas to compressed natural gas mobile delivery where pipeline laying remains stalled.
- Hydrogen blending convergence:Hydrogen-natural gas admixture up to 20% by volume is electrifying retrofit demand for compression and dispensing systems compatible with dual-specification molecules.
- Brazil biogas valorization:The Renovabio credit mechanism subsidizes biomethane injection into virtual pipeline networks, unlocking agricultural waste-to-energy aggregation models in São Paulo and Minas Gerais states.
Industry Challenges
- Cryogenic welder certification scarcity:ASME Section IX-qualified technicians for LNG tank fabrication concentrate in South Korea and Germany, extending project timelines for emerging market fleet expansion.
- Multi-jurisdictional homologation complexity:Tube trailer designs require sequential DOT, ADR, and ASME approvals for cross-border European and North American deployment, stretching product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Virtual Pipeline Systems Market |
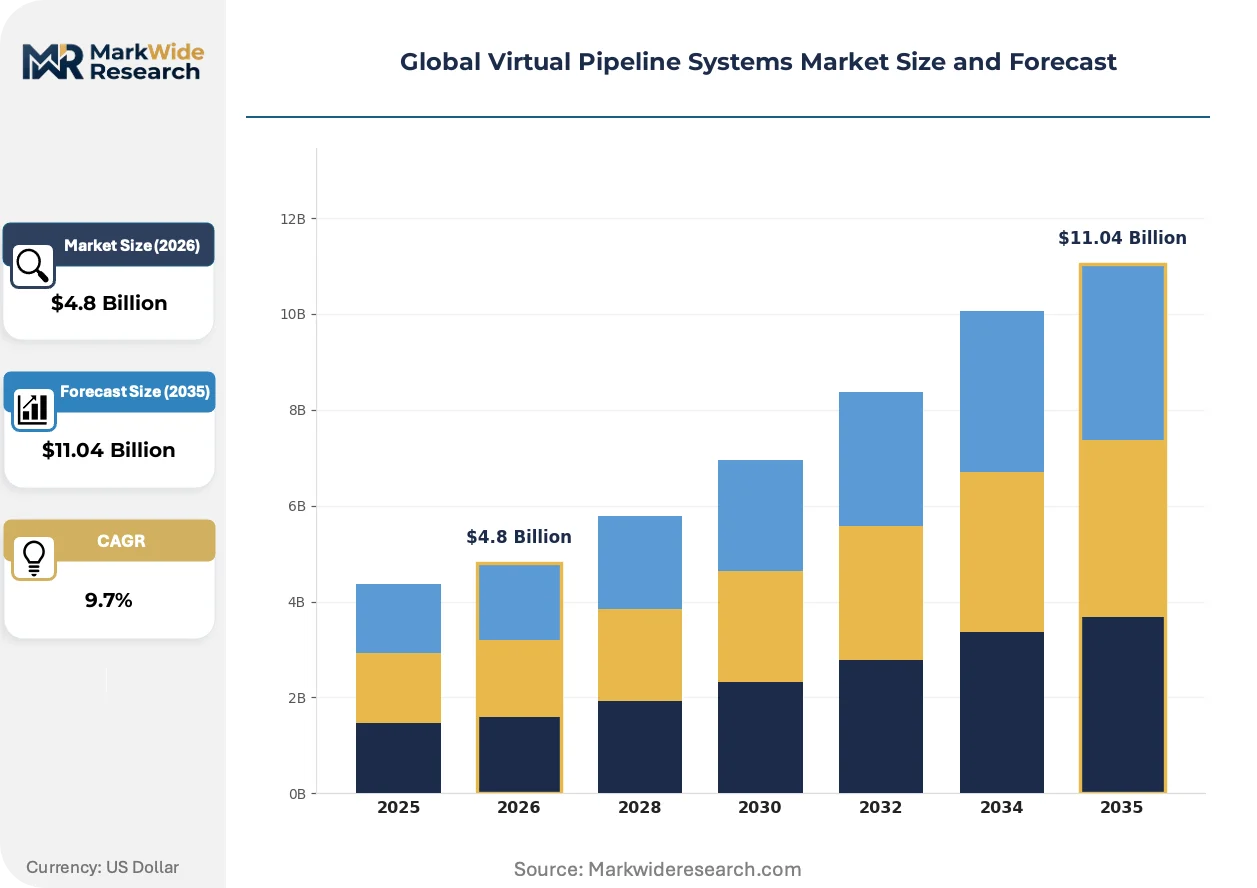
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compressed Natural Gas, Liquefied Natural Gas, Hydrogen, Biogas Technology: Pipeline Infrastructure, Storage Solutions, Compression Technology, Monitoring Systems End User: Utilities, Industrial Manufacturing, Transportation, Residential Deployment: Onshore, Offshore, Mobile, Stationary |
| Companies Covered | Chart Industries, Hexagon Composites ASA, Galileo Technologies S.A., NG Advantage LLC, Xpress Natural Gas, Baker Hughes, PETRONAS, Kinder Morgan, Stabilis Solutions, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Virtual Pipeline Systems Market Strategic Shifts
Telemetry integration and molecular flexibility are redefining equipment procurement criteria, as buyers prioritize transport assets capable of switching between natural gas, hydrogen, and biomethane without structural modification.
Modular liquefaction skid packages below 50 tonnes per day capacity are electrifying remote field gas monetization, enabling shale operators in Texas and Alberta to capture stranded wellhead gas without pipeline connection. Permian Basin producers are deploying these units at 18-month payback thresholds. The technology is compressing the minimum viable reserve size for commercialization by an order of magnitude.
Europe's impending EU methane emissions performance standards are mandating continuous monitoring and leak detection across compressed gas transport chains, forcing investment in IoT-enabled pressure vessel telemetry. The regulation tightens reporting granularity to component-level venting estimates. Cryogenic operators in Rotterdam and Hamburg are retrofitting vapor recovery units to preempt compliance deadlines.
Industrial offtake contracts are migrating toward take-or-pay structures indexed to hub pricing rather than fixed tariffs, transferring volume risk to virtual pipeline operators. Cement and steel manufacturers in Turkey and Mexico are insisting on Henry Hub or TTF linkage clauses. This reconfiguration is visible most acutely in Mediterranean markets where LNG spot liquidity enables price arbitration.
Global Virtual Pipeline Systems Market Segmentation
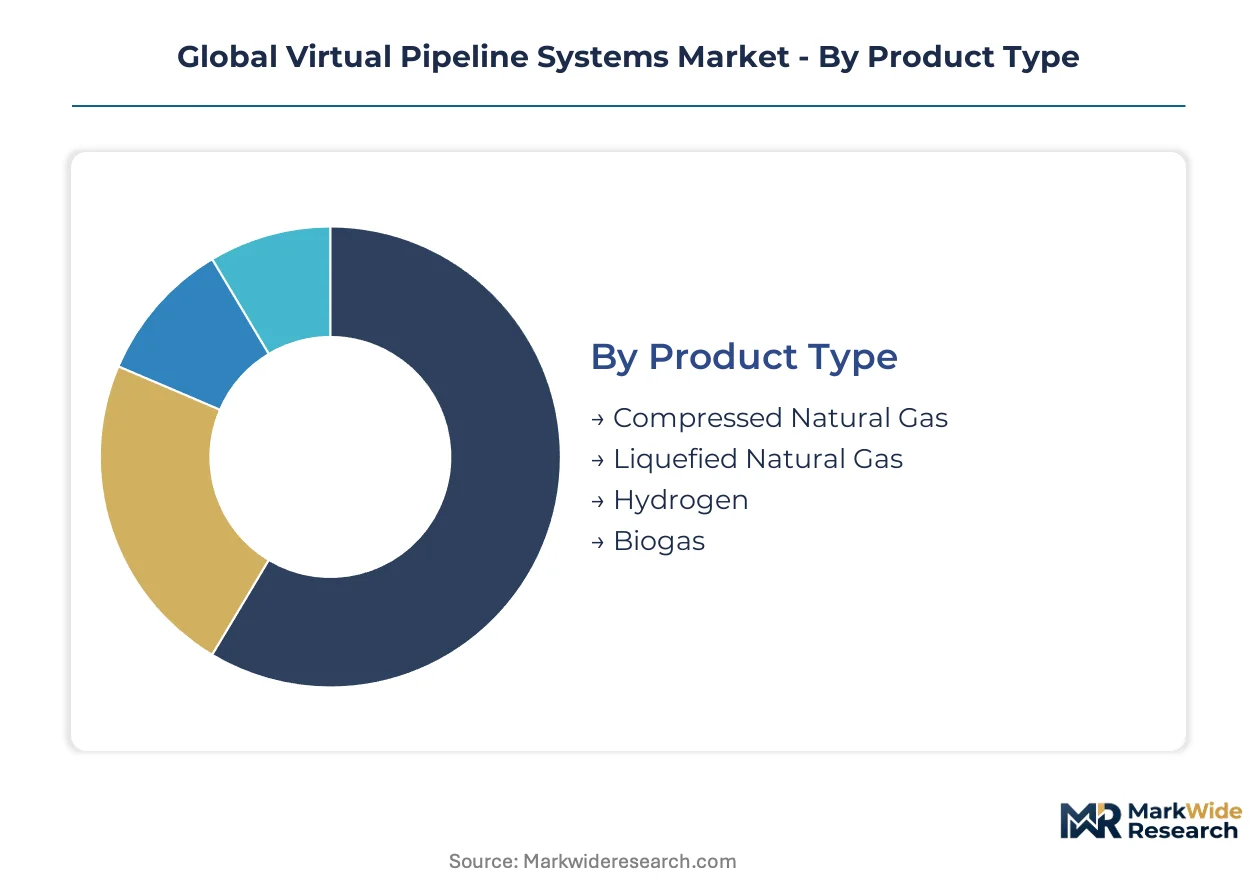
Virtual pipeline procurement splits sharply between standardized compressed gas tube trailers for industrial offtake and customized cryogenic systems for premium remote power applications. Technology selection hinges on delivery radius economics, boil-off tolerance thresholds, and regulatory compliance burdens across jurisdictions.
Product Type:
Standardization dominates compressed gas formats while cryogenic and hydrogen variants demand bespoke engineering for pressure, temperature, and material compatibility specifications.
- Compressed Natural Gas:Tube trailer systems operating at 250-300 bar pressure serve cement and steel manufacturers in Turkey, Mexico, and India where predictable demand profiles favor unit economics over delivery flexibility. Industrial procurement concentrates on fleet scale rather than individual trailer sophistication.
- Liquefied Natural Gas:Cryogenic tankers maintaining minus 162 degrees Celsius enable marine bunkering in Rotterdam and remote power generation in Australian mining corridors where grid extension costs exceed viable thresholds. Premium pricing reflects boil-off management complexity and vapor recovery system integration.
- Hydrogen:High-pressure composite vessels and liquid hydrogen tankers address emerging mobility and industrial feedstock demand in Germany and South Korea.
- Biogas:Upgraded biomethane injection into virtual pipeline networks leverages agricultural waste aggregation in São Paulo state under Brazil's Renovabio credit mechanism.
Most installed capacity flows through Compressed Natural Gas. Expansion is steepest in Hydrogen.
Technology:
Cost tiers separate mature compression hardware from telemetry-intensive monitoring platforms commanding software-like margin structures.
- Compression Technology:Reciprocating and diaphragm compressors constitute the foundational capital investment for CNG virtual pipeline operators, with fleet replacement cycles accelerating under US DOT PHMSA cylinder recertification mandates. Equipment refresh demand concentrates in North American shale corridors.
- Monitoring Systems:IoT-enabled pressure vessel telemetry incorporating leak detection and component-level venting estimates addresses EU methane emissions performance standards. Insurance underwriters in Rotterdam and Hamburg now mandate continuous monitoring for fleet coverage.
- Storage Solutions:Type 4 composite cylinders and cryogenic tanks anchor mobile and stationary deployment configurations.
- Pipeline Infrastructure:Modular liquefaction skids below 50 tonnes per day capacity monetize stranded wellhead gas in Texas and Alberta.
Compression Technology retains the largest installed base. Monitoring Systems are climbing the fastest as regulatory compliance tightens.
End User:
Volume concentration in industrial manufacturing contrasts with margin capture in transportation and utility applications requiring delivery reliability guarantees.
- Industrial Manufacturing:Cement, steel, and mining facilities in Chilean Atacama and Canadian Arctic procure gas-to-power systems where grid extension costs exceed $3 million per kilometer. Procurement patterns favor take-or-pay contracts indexed to Henry Hub or TTF pricing.
- Transportation:Marine bunkering and heavy-duty trucking fleets in Mediterranean ports drive LNG demand where spot liquidity enables price arbitration.
- Utilities:Regional distribution companies in Queensland and Western Australia repurpose LNG export terminal capacity for domestic virtual pipeline corridors.
- Residential:Limited to remote communities beyond fixed pipeline reach in Australian outback and Canadian territories.
Industrial Manufacturing absorbs the highest throughput volumes. Transportation is gaining share fastest on marine fuel switching.
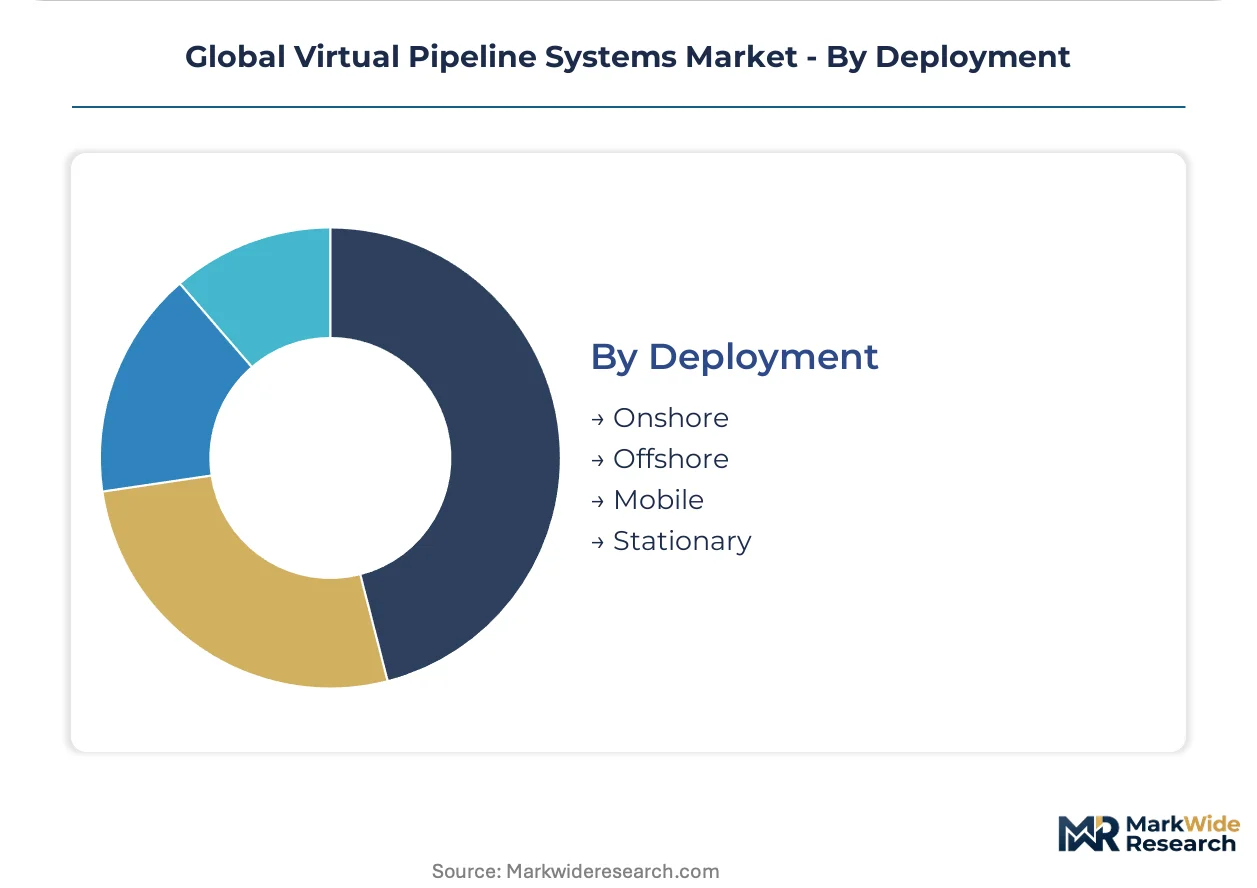
Deployment:
Mobility requirements dictate hardware specifications more than stationary installations, with offshore deployments demanding corrosion-resistant materials and dynamic positioning compatibility.
- Mobile:Tube trailer and tanker fleets enable route flexibility for industrial customers with variable offtake timing across India, Brazil, and Australia. Fleet utilization rates determine operator profitability.
- Onshore:Stationary storage and satellite regasification terminals serve mining camps and manufacturing clusters with consistent demand profiles.
- Stationary:Fixed compression and storage installations anchor hub-and-spoke distribution models.
- Offshore:Limited to platform supply and marine transfer operations requiring specialized vessel integration.
Mobile deployment carries the dominant fleet count. Onshore stationary capacity is expanding most quickly on industrial corridor buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia repurposes LNG export infrastructure for domestic distribution while the United States tightens transport safety mandates, revealing how regulatory divergence shapes capital deployment across virtual pipeline corridors.
United States
Shale operators in Texas and Alberta deploy modular liquefaction skids to monetize stranded wellhead gas at 18-month payback thresholds. DOT PHMSA cylinder recertification mandates compress fleet replacement cycles across North American operators. Permian Basin producers capture previously uneconomical reserves through sub-50 tonnes per day capacity installations.
Australia
Export terminal infrastructure redirects liquefaction capacity toward domestic virtual pipeline distribution serving regional Queensland and Western Australia industrial zones. The country's national energy regulator oversees city gas distribution licensing that opens geographical areas to compressed natural gas mobile delivery. Mining camps in the Pilbara region procure gas-to-power systems where grid extension costs exceed viable thresholds.
Germany
Hydrogen-natural gas admixture up to 20 percent by volume electrifies retrofit demand for compression systems compatible with dual-specification molecules. ECHA and EU F-Gas Regulation phase-down rules accelerate vapor recovery system retrofits across European cryogenic transport fleets. Industrial corridors in North Rhine-Westphalia anchor hydrogen-ready platform investments ahead of fixed-pipeline economics.
India
The Petroleum and Natural Gas Regulatory Board's 2025 city gas distribution licensing round opens 52 new geographical areas to compressed natural gas mobile delivery. Cement and steel manufacturers in Gujarat and Maharashtra insist on Henry Hub or TTF linkage clauses in take-or-pay contracts. Pipeline laying remains stalled across multiple industrial corridors, accelerating virtual pipeline procurement.
Brazil
The Renovabio credit mechanism subsidizes biomethane injection into virtual pipeline networks, unlocking agricultural waste-to-energy aggregation models. ANVISA and national environmental regulators shape certification requirements for compressed gas transport equipment. São Paulo and Minas Gerais states concentrate biogas upgrading facilities serving regional manufacturing clusters.
Global Virtual Pipeline Systems Market Competitive Environment
Top-tier vendors anchor cryogenic and composite vessel manufacturing, while mid-scale operators concentrate on regional compression and distribution services. The vendor base stratifies across integrated liquefaction specialists, lightweight pressure vessel fabricators, and mobile fleet operators. Equipment manufacturers and logistics providers represent the dominant strategic archetypes. Competitive positioning hardens through hydrogen-ready platform investments and vapor recovery system retrofits.
Within the integrated systems tier, Chart Industries and Baker Hughes occupy positions spanning liquefaction, storage, and transport asset fabrication. Hexagon Composites ASA exemplifies the lightweight composite pressure vessel archetype, anchoring Type 4 cylinder production for mobile CNG distribution. Galileo Technologies S.A. represents the specialized compression technology segment serving Latin American and European corridor development.
| Leading Market Players |
|---|
| Chart Industries |
| Hexagon Composites ASA |
| Galileo Technologies S.A. |
| NG Advantage LLC |
| Xpress Natural Gas |
| Baker Hughes |
| PETRONAS |
| Kinder Morgan |
| Stabilis Solutions, Inc. |
| Others |
Value Chain & Pricing Dynamics
EU methane emissions performance standards gate qualified supply access and premium-tier pricing power for cryogenic transport operators, compressing margin pools for non-compliant fleet owners while elevating certified equipment premiums across Rotterdam and Hamburg corridors.
Pricing Analysis
Capacity additions in Australia are reshaping price floors for LNG virtual pipeline deliveries as domestic liquefaction capacity repurposes from export terminals. Three-tier pricing structure across premium cryogenic, standard compressed gas, and economy tube trailer tiers separates delivery reliability guarantees. Cost compression in standard CNG segments is intensifying because industrial buyers in Turkey and Mexico insist on Henry Hub or TTF indexation. Cement and steel manufacturers exhibit highest price sensitivity, whereas marine bunkering operators accept premium positioning for boil-off management.
Supply Chain Analysis
Freight cost volatility from carbon fiber precursor suppliers in Japan and Germany propagates through Type 4 cylinder manufacturing economics. Manufacturing concentrates in South Korea, Germany, and the United States for cryogenic tank fabrication and ASME-qualified welding capacity. Raw material dependencies span acrylonitrile for composite vessels, nickel alloys for cryogenic containment, and high-pressure steel for tube trailer chassis. Single-source vulnerability concentrates in Japanese Toray carbon fiber supply. Distribution runs through hub-and-spoke models anchored at repurposed LNG export terminals and regional compression stations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
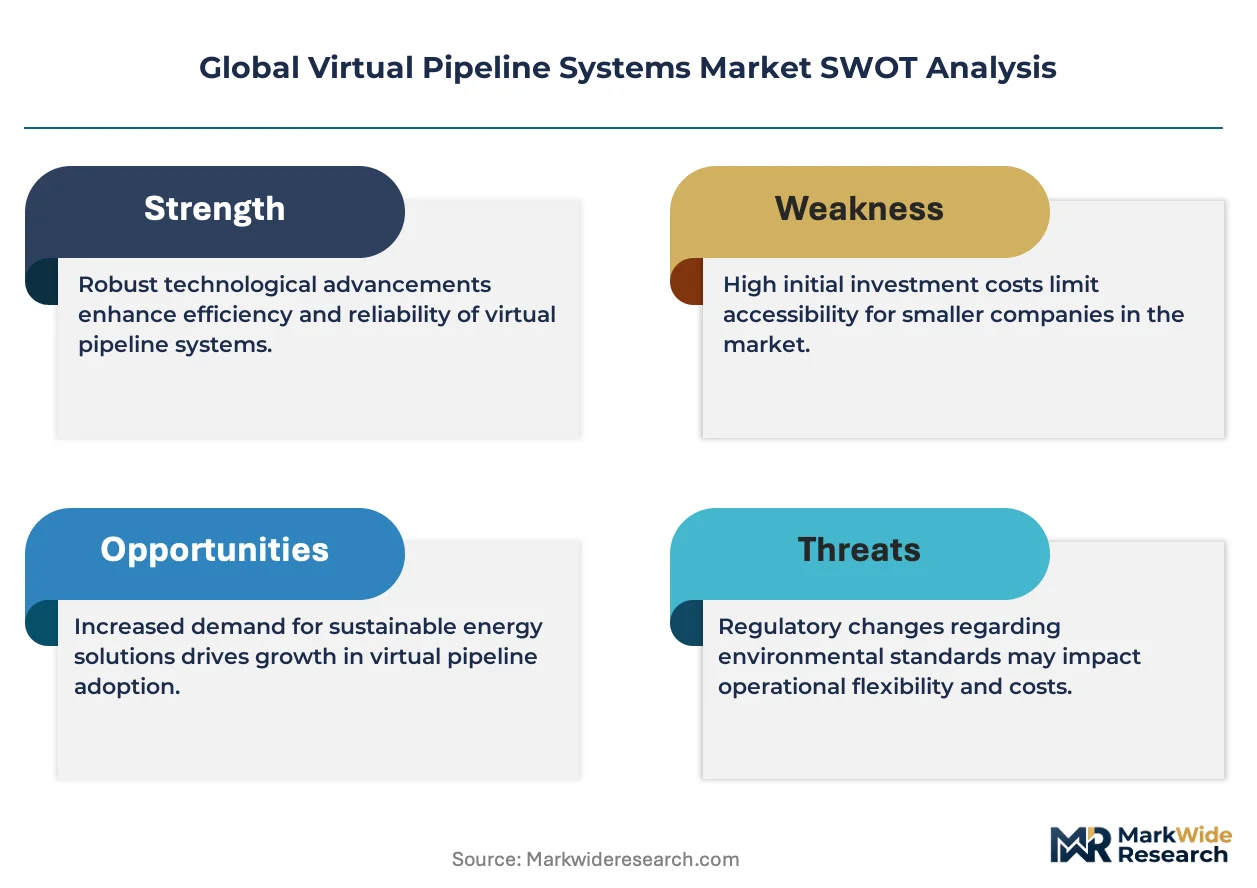
Virtual pipeline operators face a margin-expansion window as modular liquefaction skids compress stranded gas monetization costs and hydrogen-ready platforms command certification premiums.
For Market Incumbents: Deepen backward integration into composite cylinder precursor supply through offtake agreements with Japanese carbon fiber producers, insulating against acrylonitrile price volatility. Anchor fleet replacement cycles ahead of US DOT PHMSA recertification mandates to capture stranded demand from non-compliant regional distributors. Hydrogen-ready platform investments represent the critical defensive lever against emerging pure-play hydrogen logistics entrants. For New Entrants and Emerging Players: Industrial gas distributors in India's 52 newly licensed geographical areas offer the most penetrable white-space opportunity, where pipeline laying stalls create captive demand for mobile CNG delivery. Brazil's Renovabio credit mechanism enables biomethane aggregation plays with subsidized feedstock economics. A compression-systems leasing model with embedded telemetry compliance addresses capital-constrained mid-scale operators. For Investors and Strategic Acquirers: Valuations sit cheapest among regional fleet operators facing DOT PHMSA recertification cliffs without hydrogen transition capital. Long-term viability hinges on molecular flexibility—assets capable of natural gas, hydrogen, and biomethane carriage without structural modification. Monitor EU methane emissions enforcement granularity as the inflection signal for premium-tier equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen-Ready Platform Investment | Dual-specification compression assets future-proof fleet value against fuel switching in Germany's industrial corridors. |
| Vapor Recovery System Retrofit | EU F-Gas Regulation compliance unlocks insurance coverage and Rotterdam port access for cryogenic operators. |
| Modular Liquefaction Skid Deployment | Sub-50 tonnes per day units capture stranded Permian Basin wellhead gas at compressed payback thresholds. |
| Composite Cylinder Precursor Integration | Upstream control over Japanese carbon fiber supply mitigates Type 4 vessel cost volatility for fleet manufacturers. |
| Telemetry-Enabled Fleet Monitoring | IoT pressure vessel tracking satisfies EU methane performance standards and insurance underwriter mandates in Hamburg. |
Study Parameters
Multiple input streams — equipment procurement databases, regulatory filing repositories, and field operator interviews — were reconciled to construct market estimates. Primary conversations with virtual pipeline fleet managers, LNG terminal repurposing planners, compression technology procurement leads, and cryogenic tank fabrication engineers informed operational assumptions. Secondary validation drew from US DOT PHMSA safety filings, EU ECHA regulatory updates, Australian energy regulator licensing records, and customs trade data for pressure vessel imports. Bottom-up triangulation across installed fleet counts and top-down reconciliation against liquefaction capacity buildouts anchored value estimates.
Data-stream reconciliation across technology segmentation, geographic deployment patterns, and end-use industry absorption rates structured the analytical framework. Segmentation dimensions modeled include product type, technology tier, deployment mobility class, and regional regulatory cluster. CAGRs were derived from trend extrapolation of fleet replacement cycles and capacity addition announcements. Industry-specific forecast inputs incorporated DOT PHMSA recertification schedule impacts and EU methane emissions compliance deadlines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hydrogen blending mandate timing and carbon fiber export license restrictions. Forecasts reflect assumptions around regulatory enforcement consistency and feedstock price stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Pipeline Transportation Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Ring Main Unit Market