
 Middle-East and Africa DC Distribution Networks Market | 2026-2036
Middle-East and Africa DC Distribution Networks Market Size, Share, and Industry Trends Forecast 2026-2036
Middle-East and Africa DC Distribution Networks Market Foresight
Utility buyer consolidation across Gulf Cooperation Council states is repositioning procurement toward long-term DC infrastructure contracts. Equinix leverages its interconnection footprint to anchor premium colocation demand in Johannesburg and Dubai. Khazna Data Centers sustains capacity leadership through captive renewable offtake agreements tied to Abu Dhabi's clean energy mandates. Edgnex Data Centres competes on build-to-suit velocity for hyperscale tenants entering Riyadh and Cairo markets.
DC distribution networks transmit electrical power using direct current rather than alternating current, typically operating at voltages from 380V to 1500V for data center and industrial applications, with converter stations handling AC-to-DC rectification at entry points. These systems eliminate multiple conversion stages, cutting energy losses by roughly one-third compared with conventional AC distribution chains in hyperscale facilities. Modular Multilevel converter technology leads capital deployment across the region due to superior harmonic performance and scalable voltage blocking capability. Cables dominate component spending as subsea and underground HVDC links expand between North African renewable zones and Middle Eastern load centers.
Saudi Arabia's central energy regulator enforces grid codes that favor DC-ready interconnect standards for industrial zones and data center clusters. The UAE's federal standards body mandates efficiency benchmarks for power distribution infrastructure in free trade zones, directly shaping vendor qualification criteria. Egypt's electricity utility regulator promotes DC microgrid pilots for remote industrial sites under national electrification frameworks. Stakeholders must track how each national regulator harmonizes DC safety standards with existing AC-centric permitting regimes.
Market Dynamics
Utility-scale renewable integration across Saudi Arabia and the UAE is forcing data center operators to adopt native DC architectures that bypass legacy AC conversion stages entirely. This structural shift eliminates intermediate transformation losses while aligning with national clean energy mandates.
Growth Catalysts
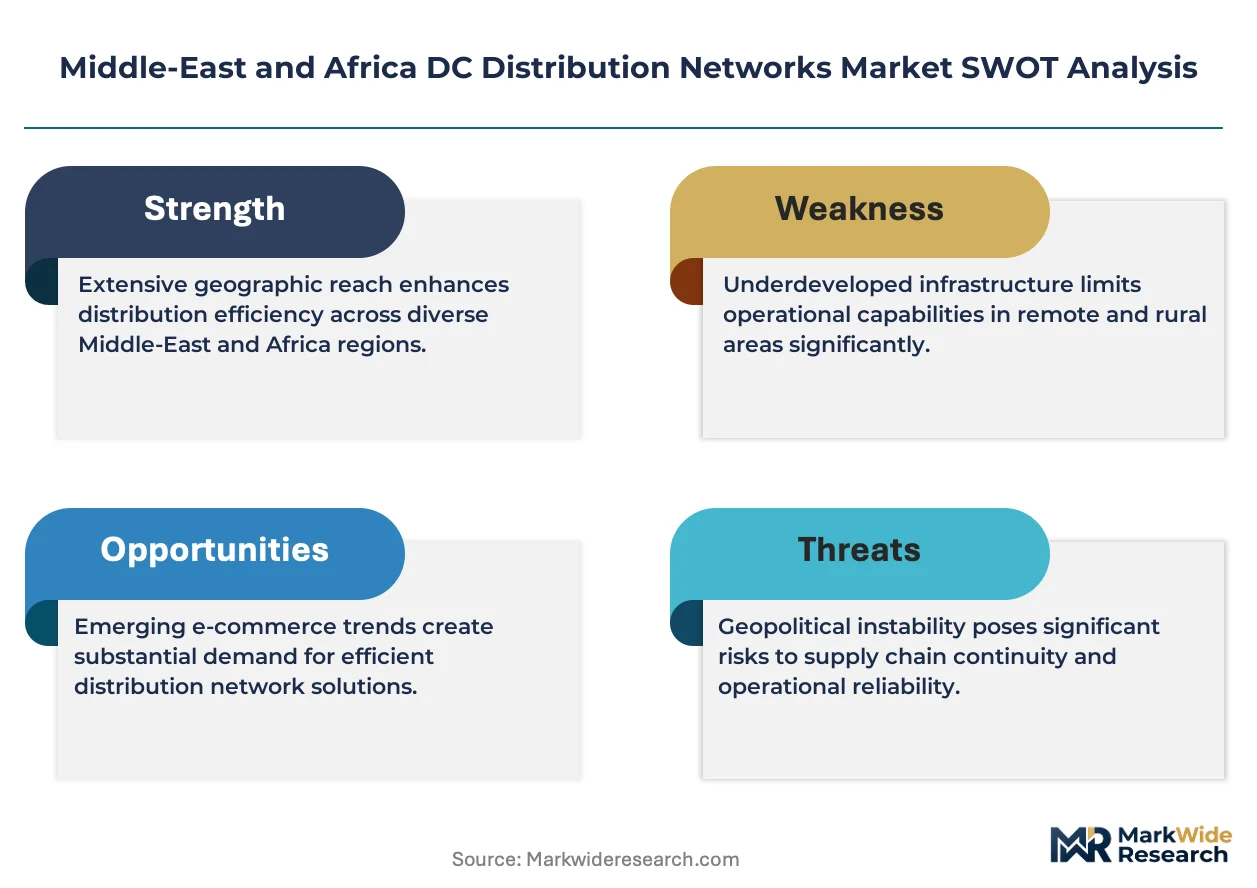
- Grid Code Modernization:Saudi Arabia's central energy regulator enforces DC-ready interconnect standards for industrial zones, compelling new data center builds to incorporate native DC distribution from commissioning.
- Hyperscale Compute Density:AI training clusters in Dubai and Riyadh now operate at power densities exceeding 50kW per rack, rendering conventional AC distribution thermally and economically unviable.
- Submarine Cable Expansion:HVDC links connecting North African solar zones to Middle Eastern load centers are creating dedicated DC corridors that bypass regional AC grid bottlenecks entirely.
Market Restraints
- Copper Price Volatility:Cable-intensive DC architectures face input cost pressure from LME copper fluctuations, with busbar and conductor assemblies representing disproportionate capital exposure.
- Converter Supply Concentration:Modular Multilevel converter manufacturing concentrates among European and East Asian suppliers, creating lead time vulnerability for GCC-based EPC contractors.
- Permitting Regime Friction:Egypt's electricity utility regulator maintains AC-centric safety certification pathways that delay DC microgrid commissioning for remote industrial pilots.
Strategic Opportunities
- Nigerian Industrial Corridors:Lagos-Ibadan manufacturing zones lack reliable grid infrastructure, creating first-mover advantage for DC microgrid developers offering captive power with renewable offtake.
- Green Hydrogen Integration:Electrolyzer facilities in Neom and Al Dhafra require massive DC input power, converging data center and industrial DC distribution standards around common voltage platforms.
- Build-to-Suit Channel Innovation:Hyperscale tenants in Riyadh and Cairo now contract directly with DC infrastructure specialists, bypassing traditional utility intermediaries for primary power distribution.
Industry Challenges
- Power Electronics Talent Scarcity:Converter station commissioning and harmonic tuning require specialized engineers that Gulf labor markets currently undersupply relative to deployment timelines.
- Legacy AC Integration Complexity:Brownfield data centers in Johannesburg and Dubai face costly retrofit cycles to synchronize existing UPS architectures with new DC bus feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle-East and Africa DC Distribution Networks Market |
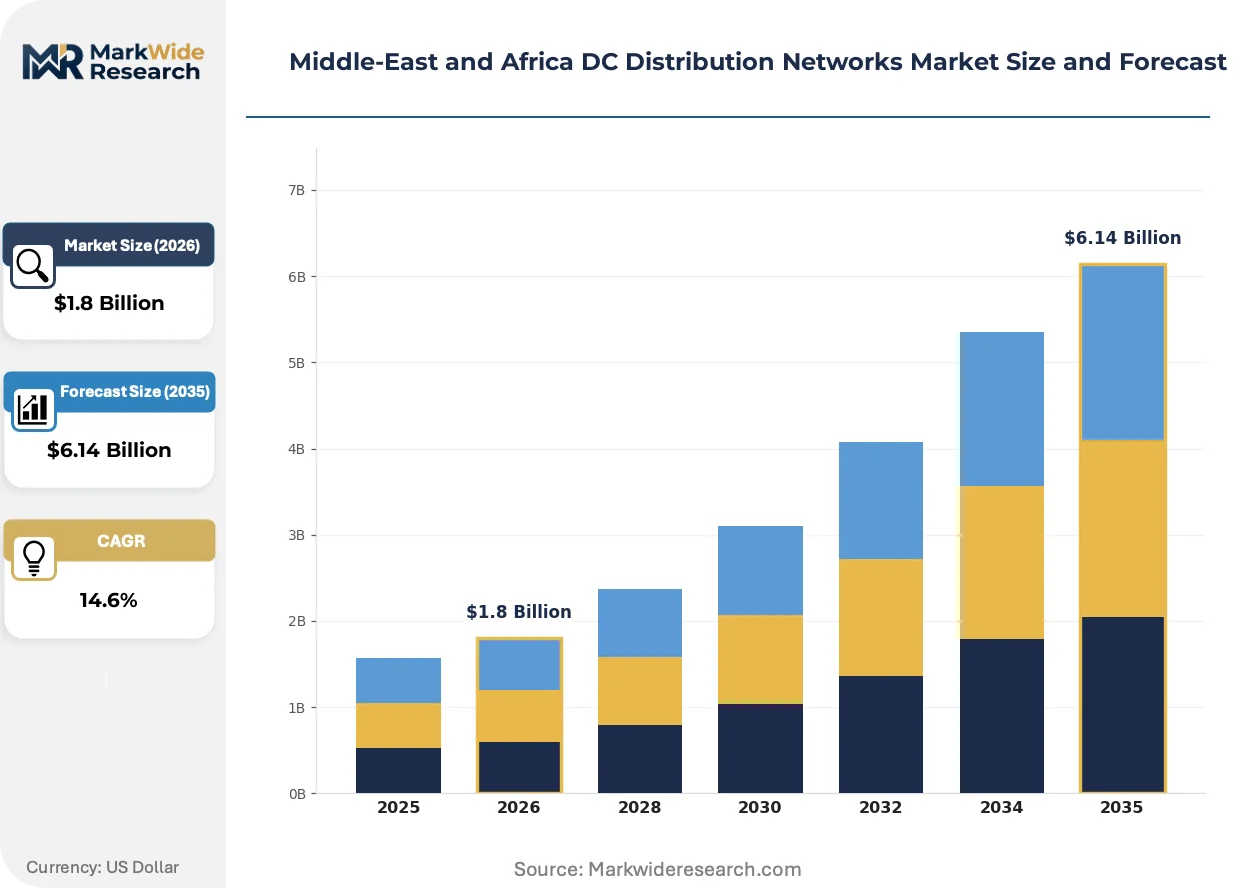
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: HVDC, VSC, LCC, Modular Multilevel Component: Transformers, Switchgear, Converter Stations, Cables End User: Utilities, Industrial, Renewable Energy, Commercial Installation: Onshore, Offshore, Urban, Rural |
| Companies Covered | Equinix, Edgnex Data Centres, Khazna Data Centers, Raxio Data Centres, Africa Data Centres, Gulf Data Hub, center3 (stc), Moro Hub, Digital Realty, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle-East and Africa DC Distribution Networks Market Shifts & Advancements
Power semiconductor advances and standardization pressures are compressing DC distribution system footprints while expanding voltage operating ranges. Vendors now compete on converter efficiency curves rather than capital cost alone.
Silicon carbide (SiC) power modules now dominate 1500V DC converter designs for hyperscale facilities, cutting switching losses by half versus conventional silicon IGBTs. Saudi-based operators are adopting these modules aggressively for thermal management advantages in desert climates. The technology is modularizing around standardized 250kW building blocks that simplify field maintenance and capacity expansion.
The UAE's federal standards body now mandates efficiency benchmarking for power distribution infrastructure in free trade zones, directly shaping vendor qualification criteria and disqualifying legacy AC-centric suppliers. Data center operators in Dubai must document end-to-end energy conversion losses to maintain operating licenses. This regulatory pressure is compressing procurement cycles as buyers pre-qualify only DC-native equipment vendors.
Hyperscale tenants now specify outcome-based power availability guarantees rather than equipment-centric procurement, transferring operational risk to DC infrastructure providers. Build-to-suit contracts in Riyadh and Cairo increasingly bundle 15-year power distribution performance with construction delivery. This contractual evolution is visible most acutely in Saudi Arabia's giga-project developments, where sovereign wealth-backed developers demand integrated power architecture liability from single-source contractors.
Middle-East and Africa DC Distribution Networks Market Segmentation
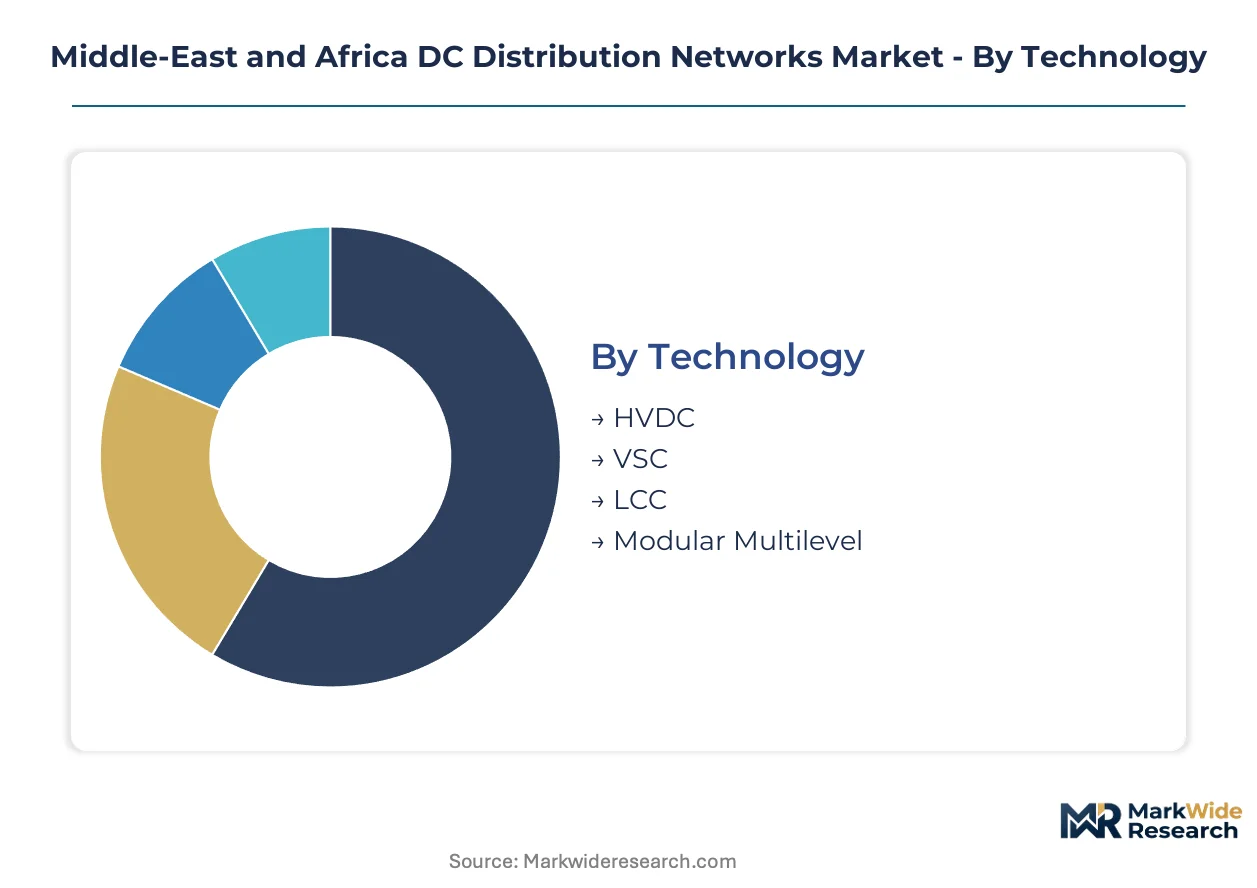
Technology choice dictates capital intensity and harmonic performance for DC distribution architectures across Middle Eastern and African markets. Component sourcing strategies vary sharply between utility-scale renewable corridors and hyperscale data center clusters. Installation environment determines cable specifications and converter station thermal management requirements.
Technology:
Converter topology selection hinges on voltage blocking requirements and grid code harmonization mandates from Saudi Arabia's central energy regulator.
- HVDC:Bulk power transmission across regional interconnects operates at 500kV and above. Submarine links between North African solar zones and Gulf load centers favor this technology for minimal line losses over distance.
- VSC:Voltage Source Converters enable independent active and reactive power control critical for weak grid interconnection. Abu Dhabi's industrial zones deploy VSC for renewable integration where grid strength varies.
- LCC:Line-commutated converters require strong synchronous networks and suit established utility corridors. Egyptian transmission utilities specify LCC for backbone reinforcement where existing AC infrastructure dominates.
- Modular Multilevel:Scalable voltage blocking and superior harmonic performance position this topology for data center clusters in Dubai and Riyadh. Saudi giga-projects mandate MMC for DC-ready industrial zone interconnects.
Volume sits with HVDC; growth tilts toward Modular Multilevel.
Component:
Procurement patterns diverge between cable-heavy submarine deployments and converter-intensive onshore data center builds.
- Transformers:AC-DC interface units handle voltage stepping at rectifier stations. UAE free trade zone mandates favor liquid-immersed designs with documented efficiency curves for operating license compliance.
- Switchgear:DC circuit breakers and disconnectors protect busbar architectures. Johannesburg brownfield retrofits drive demand for compact gas-insulated switchgear that synchronizes with legacy UPS systems.
- Converter Stations:Rectifier and inverter assemblies dominate capital expenditure in hyperscale facilities. Riyadh build-to-suit contracts bundle 15-year converter performance guarantees with construction delivery.
- Cables:Subsea and underground HVDC links between North Africa and the Middle East absorb disproportionate component spending. Copper price volatility creates margin pressure for EPC contractors bidding cable-intensive projects.
Spending concentrates on Cables; Converter Stations expand most quickly.
End User:
Power density requirements and renewable offtake structures determine voltage platform selection and architectural standardization.
- Utilities:Grid operators across the Gulf Cooperation Council enforce DC-ready interconnect standards for new industrial zone commissioning. Saudi Arabia's central energy regulator mandates native DC distribution for utility-scale renewable integration.
- Industrial:Manufacturing clusters in Neom and Al Dhafra require massive DC input for electrolyzer facilities. Green hydrogen production is converging data center and industrial DC standards around common 1500V platforms.
- Renewable Energy:Solar and wind farms in Egypt and Morocco feed HVDC corridors bypassing regional AC bottlenecks. Captive renewable offtake agreements tie Khazna Data Centers to Abu Dhabi's clean energy procurement mandates.
- Commercial:Colocation operators in Dubai and Johannesburg specify outcome-based power availability guarantees. Equinix leverages interconnection footprint to anchor premium demand for resilient DC distribution.
Industrial deployments lead volume; Commercial segments gain share fastest.
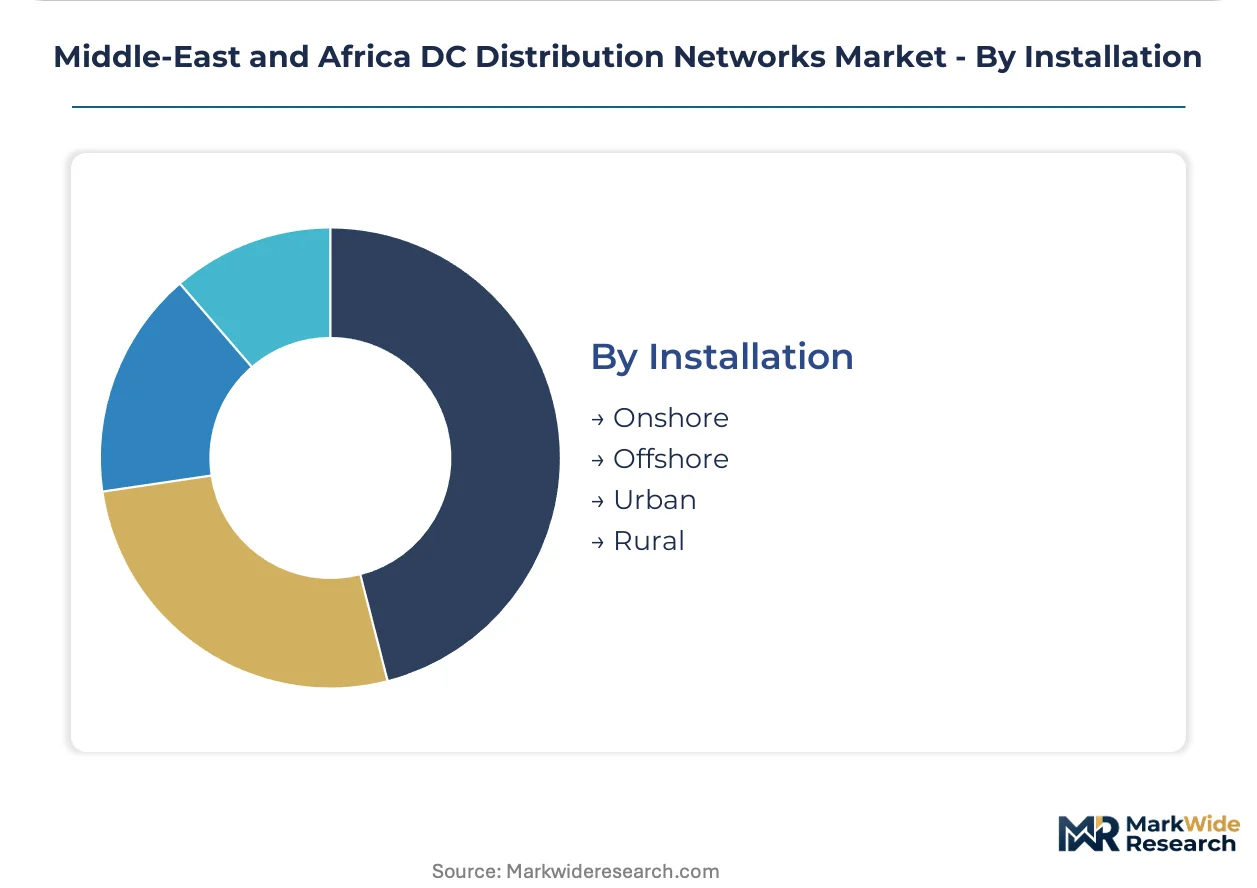
Installation:
Environmental exposure and population density shape thermal management strategies and cable routing constraints.
- Onshore:Desert installations in Saudi Arabia demand silicon carbide power modules for thermal management advantages. Converter stations require active cooling systems rated for ambient temperatures exceeding 50°C.
- Offshore:Subsea cable landings at Red Sea and Mediterranean coasts need corrosion-resistant terminations. HVDC links connecting North African renewable zones to Middle Eastern load centers dominate this category.
- Urban:Dubai's smart city initiatives and Cairo's dense commercial districts require compact underground vault configurations. Space constraints favor gas-insulated switchgear over air-insulated alternatives.
- Rural:Remote industrial sites in Egypt and Nigeria lack reliable grid infrastructure. DC microgrid pilots under national electrification frameworks target manufacturing zones with captive power requirements.
Onshore deployments hold volume; Urban installations show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data center operators concentrate procurement in Saudi Arabia and the United Arab Emirates, where sovereign wealth-backed giga-projects and smart city mandates are compressing DC infrastructure deployment timelines.
Saudi Arabia
Neom and Riyadh anchor hyperscale build-to-suit demand as sovereign wealth funds commission native DC distribution for AI training clusters. The central energy regulator enforces DC-ready interconnect standards for industrial zone commissioning. Eastern Province manufacturing corridors are integrating 1500V DC bus architectures for electrolyzer facilities.
United Arab Emirates
Dubai's smart city initiatives and Abu Dhabi's industrial free zones require resilient DC distribution architectures with documented efficiency curves. The federal standards body mandates efficiency benchmarking for power distribution infrastructure in free trade zones. Khazna Data Centers sustains capacity leadership through captive renewable offtake agreements tied to clean energy mandates.
Egypt
Cairo's dense commercial districts and Red Sea manufacturing zones lack reliable grid infrastructure, creating captive power opportunities for DC microgrid developers. The electricity utility regulator promotes DC microgrid pilots for remote industrial sites under national electrification frameworks. Subsea HVDC landings at Mediterranean coasts are connecting North African solar zones to domestic load centers.
South Africa
Johannesburg brownfield retrofits drive demand for compact gas-insulated switchgear that synchronizes with legacy UPS systems. National energy regulators are harmonizing DC safety standards with existing AC-centric permitting regimes. Cape Town's commercial colocation market is specifying outcome-based power availability guarantees rather than equipment-centric procurement.
Nigeria
Lagos-Ibadan manufacturing zones lack reliable grid infrastructure, creating first-mover advantage for DC microgrid developers offering captive power with renewable offtake. The national electrification framework targets remote industrial sites with unreliable grid access. Port Harcourt's energy-intensive processing facilities are evaluating native DC architectures to bypass conversion losses.
Middle-East and Africa DC Distribution Networks Market Competitive Landscape
European and East Asian converter manufacturers anchor the equipment tier; Gulf-based data center operators and EPC contractors hold the integration tier. The vendor base splits between consolidated power electronics specialists and fragmented regional system integrators. Three archetypes dominate: captive renewable offtake specialists, build-to-suit velocity players, and interconnection footprint anchors. Competitive intensity centers on converter supply security and 15-year performance guarantee bundling.
Within the captive renewable tier, Khazna Data Centers and Edgnex Data Centres exemplify operators securing long-term clean energy offtake to anchor DC infrastructure investments. Equinix occupies a position representing the interconnection-centric archetype, leveraging existing footprint to capture premium colocation demand. Among regional specialists, Raxio Data Centres and Africa Data Centres sit within the build-to-suit velocity segment targeting secondary city markets with compressed deployment timelines.
| Leading Market Players |
|---|
| Equinix |
| Edgnex Data Centres |
| Khazna Data Centers |
| Raxio Data Centres |
| Africa Data Centres |
| Gulf Data Hub |
| center3 (stc) |
| Moro Hub |
| Digital Realty |
| Others |
Supply & Pricing Matrix
Copper conductor assemblies transmit raw material volatility directly through cable procurement tiers, with LME price swings compressing margins for EPC contractors bidding submarine HVDC links between North African solar zones and Gulf load centers.
Pricing Analysis
Volume concentrates in utility-scale cable contracts while margins accrue to converter station specialists serving hyperscale data center builds. Three-tier pricing structure across premium, standard, and economy levels separates silicon carbide module configurations from conventional silicon IGBT alternatives, with efficiency certification tiers from the UAE federal standards body driving price differentiation. Cost compression in standard-tier converter assemblies is intensifying because European and East Asian manufacturing concentration extends lead times for GCC-based contractors. Hyperscale tenants in Riyadh and Cairo show least price sensitivity due to bundled 15-year performance guarantees, while Nigerian industrial microgrid developers face acute capital constraints.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for Modular Multilevel converter stations, bypassing traditional distribution intermediaries. Manufacturing concentrates in Germany, Japan, and South Korea for power semiconductor modules and converter assemblies. Raw material dependencies center on high-purity copper cathodes, silicon carbide wafers, and epoxy resin systems for module encapsulation. Single-source vulnerability in silicon carbide substrate supply creates exposure for Saudi giga-project timelines. Distribution runs through captive procurement teams at Khazna Data Centers, Edgnex Data Centres, and Equinix rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Converter supply concentration and copper price volatility are forcing consolidation among regional EPC contractors unable to secure long-term component offtake agreements.
For Market Incumbents: Lock in captive renewable offtake partnerships with Abu Dhabi's clean energy procurement programs to defend against Edgnex Data Centres' build-to-suit velocity. Secure backward integration into silicon carbide module sourcing through direct supplier agreements in Japan and Germany. Expand converter station maintenance capabilities to capture 15-year performance guarantee revenue streams now bundled in Riyadh contracts. For New Entrants and Emerging Players: Enter via Lagos-Ibadan manufacturing corridors where grid unreliability creates captive power demand without incumbent saturation. Target Egyptian DC microgrid pilots promoted under national electrification frameworks for remote industrial sites. Lead with outcome-based power availability contracting to bypass equipment-centric procurement barriers facing legacy AC suppliers. For Investors and Strategic Acquirers: Distressed-cycle entries favor converter maintenance specialists in South Africa where Johannesburg brownfield retrofits outpace local talent supply. Long-term viability hinges on positioning for sovereign wealth-backed giga-project waves across Saudi Arabia and the UAE. Watch HVDC cable landing permit approvals at Mediterranean and Red Sea coasts as inflection indicators for North African renewable export capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Renewable Offtake Agreement | Khazna Data Centers anchors Abu Dhabi capacity through clean energy procurement mandates. |
| Silicon Carbide Module Sourcing Partnership | Saudi operators secure thermal management advantages for desert climate installations. |
| Build-to-Suit Velocity Contracting | Edgnex Data Centres compresses Riyadh deployment timelines for hyperscale AI clusters. |
| Converter Maintenance Capability Buildout | Regional specialists capture 15-year performance guarantee revenue from bundled contracts. |
| HVDC Submarine Cable Landing Permit | Egyptian Mediterranean coast access enables North African solar export to Gulf load centers. |
Research Methodology
Regulatory filings from Saudi Arabia's central energy regulator, UAE federal standards documentation, and Egyptian electricity utility frameworks formed the secondary backbone. Primary interviews with EPC contractors, data center procurement directors, and converter station commissioning engineers were cross-referenced against customs data for HVDC cable imports and silicon carbide module trade flows. Bottom-up capacity aggregation across Dubai, Riyadh, and Johannesburg facilities was reconciled with top-down sovereign wealth deployment disclosures.
Bottom-up modeling tracked individual project announcements across Neom, Al Dhafra, and Cairo manufacturing zones against technology segmentation by converter topology. Analytical frameworks tested voltage platform adoption curves across 380V to 1500V operating ranges throughout the forecast period. CAGRs were derived from utility-scale renewable integration timelines and hyperscale data center commissioning schedules. Industry-specific inputs included grid code modernization enforcement patterns from Saudi Arabia's central energy regulator and copper price scenario modeling.
Forecast precision tightens around the base case; tail outcomes carry wider variance under copper price spike conditions or silicon carbide supply disruptions. Projections reflect assumptions regarding regulatory harmonization of DC safety standards with existing AC-centric permitting regimes across Egypt and South Africa. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Europe High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
South-East Asia DC Distribution Network Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
High Temperature Overhead Conductor Market