
 Natural Gas Refueling Infrastructure Market | 2026-2036
Natural Gas Refueling Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Gas Refueling Infrastructure Market Outlook
Multi-source equipment procurement is hardening across the natural gas refueling infrastructure sector as operators seek supply chain resilience. Clean Energy Fuels Corp leverages its station network density to anchor retail fueling positions in North American corridors. Chart Industries sustains technology leadership through cryogenic equipment specialization for liquefied natural gas terminals. Shell plc competes via integrated fuel supply chains that span upstream gas through downstream retail dispensing.
Natural gas refueling infrastructure comprises compressor stations, storage cascades, dispensers, and cryogenic systems engineered to deliver compressed natural gas at 3,600 psi or liquefied natural gas at minus 162 degrees Celsius for vehicle fueling. The primary purpose centers on displacing diesel and gasoline in high-mileage commercial applications where fuel cost differentials compound across fleet scale. Compressed natural gas dominates the technology dimension due to lower capital requirements and established engine compatibility, while liquefied natural gas captures the heavy-duty segment where energy density dictates range performance. Public transportation and commercial fleets anchor application demand, with centralized stations and on-site refueling commanding margin pools through volume commitments and operational control.
The US EPA tailpipe standards and NHTSA fuel economy regulations shape product specifications by mandating emission reductions that natural gas engines satisfy. California Air Resources Board zero-emission vehicle pathways and Low Carbon Fuel Standard credits further steer infrastructure investment toward renewable natural gas compatibility. OSHA and DOT pipeline safety standards govern station construction, pressurized equipment certification, and operator training protocols. Stakeholders must monitor evolving federal tax credit structures and state-level clean fleet mandates to time capital deployment and technology selection.
Market Dynamics
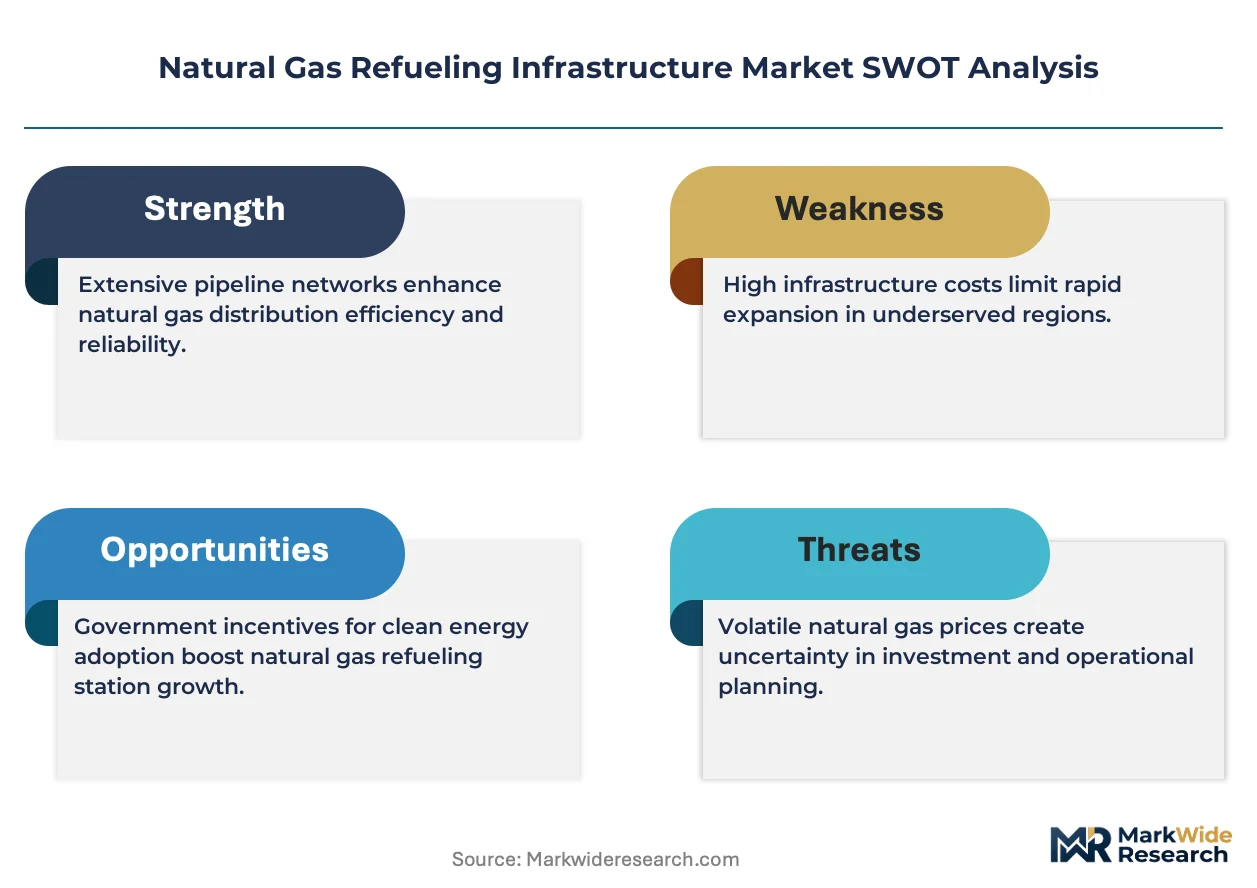
Fleet electrification timelines and renewable natural gas certification requirements are compressing investment windows for conventional CNG infrastructure while redirecting capital toward biomethane-compatible systems.
Growth Catalysts
- CARB Low Carbon Fuel Standard:California's credit trading system generates revenue streams for RNG-compatible station operators, accelerating infrastructure deployment along interstate freight corridors.
- Long-haul trucking:Walmart Transportation and J.B. Hunt are expanding dedicated CNG fleet contracts that lock in decade-long fuel purchase commitments with station developers.
- Pipeline density:Texas Gulf Coast industrial clusters leverage existing high-pressure distribution networks to minimize compressor station capital requirements for fleet refueling.
Market Restraints
- Electrification substitution:Battery-electric Class 8 trucks from Tesla Semi and Freightliner eCascadia threaten CNG's cost advantage in regional haul applications under 500 miles.
- Steel and nickel volatility:Cryogenic storage tank fabrication depends on austenitic stainless steel grades whose price swings compress equipment margins.
- Permitting fragmentation:Local air quality management districts in California impose site-specific emission offsets that extend station commissioning timelines by 8-14 months.
Strategic Opportunities
- Biogas corridor development:Landfill gas capture projects in Pennsylvania and Ohio offer stranded renewable methane supplies awaiting pipeline interconnection to vehicle fueling networks.
- Marine bunkering:LNG-powered container ships at Port of Long Beach create demand for shoreside truck-to-ship transfer infrastructure with dual-use vehicle fueling capability.
- Inflation Reduction Act credits:Section 45Q carbon capture incentives and alternative fuel infrastructure tax credits stack to improve project returns for RNG-upgraded stations.
Industry Challenges
- Cryogenic technician scarcity:LNG system maintenance requires ASME Section VIII certified welders and vacuum insulation specialists concentrated in Gulf Coast petrochemical hubs.
- Legacy diesel integration:Mixed-fleet operators face dual maintenance protocols and driver training complexity when operating CNG and diesel assets from shared terminals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Gas Refueling Infrastructure Market |
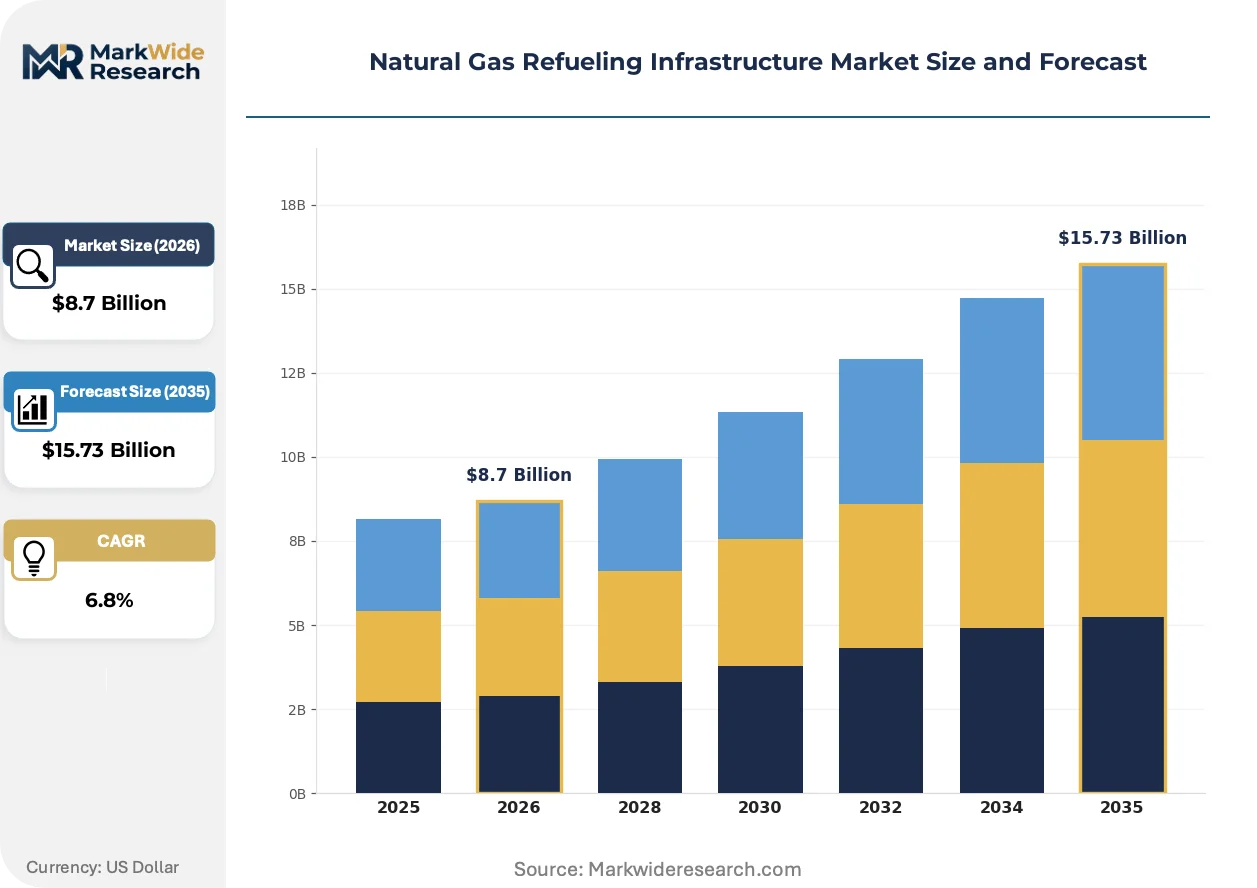
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Compressed Natural Gas, Liquefied Natural Gas, Biogas, Hydrogen Application: Public Transportation, Commercial Fleets, Light-Duty Vehicles, Heavy-Duty Vehicles Distribution Channel: Retail Stations, On-site Refueling, Centralized Stations, Containerized Solutions End User: Municipalities, Logistics Companies, Transit Authorities, Oil & Gas Industry |
| Companies Covered | Clean Energy Fuels Corp, Chart Industries, Parker Hannifin Corp, Cryostar SAS, Atlas Copco AB, Shell plc, China National Petroleum Corporation, Gilbarco Inc, Greka Engineering and Technology Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Gas Refueling Infrastructure Market Strategic Shifts
Digitization of fueling transactions and predictive maintenance systems are reconfiguring station economics while biomethane tracking technologies reshape fuel certification.
Dispenser-mounted RFID and fleet card automation is automating authorization and custody transfer at high-volume truck stops. Schneider National and Werner Enterprises are deploying telematics-integrated fueling that triggers payment upon nozzle connection without driver intervention. This compression of transaction friction enables unattended overnight fueling operations that maximize asset utilization rates.
EPA's Greenhouse Gas Emissions Standards for Heavy-Duty Vehicles—Phase 3 tighten CO2 limits through 2032, forcing engine manufacturers to certify natural gas powertrains with methane slip controls. Cummins and Westport Fuel Systems are responding with enhanced crankcase ventilation and closed-loop fuel systems that reduce unburned methane release. The compliance burden falls heaviest on urban refuse and transit applications where frequent stop-start cycles elevate slip risk.
Fleet procurement departments are consolidating fuel purchasing through third-party energy management platforms that aggregate volume across dispersed terminal networks. These arrangements displace direct station contracts and transfer price risk to intermediaries with hedging capabilities. The shift is most pronounced among private carriers with 500-plus unit fleets operating across multiple state jurisdictions.
Natural Gas Refueling Infrastructure Market Segmentation
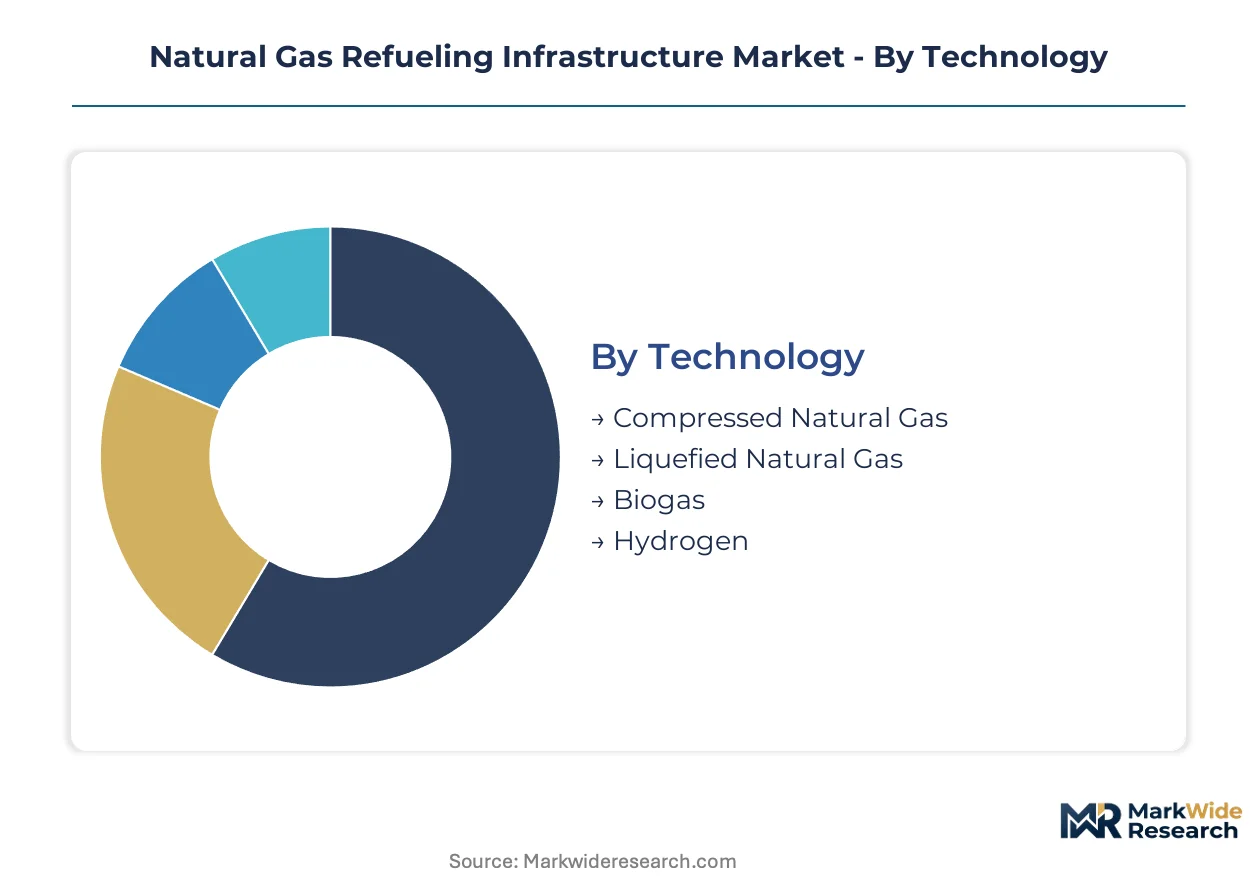
Technology selection dictates compressor specifications, storage cascade sizing, and dispenser pressure ratings across deployment scenarios. Application mix determines whether stations serve fixed-route transit or variable-route trucking, altering throughput design and land requirements. Distribution channel choice separates capital-light fleet operators from infrastructure developers bearing full station economics.
Technology:
Capital intensity escalates sharply from compressed gas systems through cryogenic liquefaction plants to multi-fuel platforms with hydrogen blending capability.
- Compressed Natural Gas:Three-stage reciprocating compressors deliver gas at 3,600 psi through time-fill or fast-fill dispensers. Fleet operators in Texas and California concentrate procurement here due to lower station buildout costs and established Cummins-Westport engine compatibility. CARB Low Carbon Fuel Standard credits improve project returns when stations add renewable natural gas certification.
- Liquefied Natural Gas:Cryogenic liquefiers cool methane to minus 162 degrees Celsius for storage in vacuum-insulated tanks. Heavy-duty corridor development along I-10 and I-40 corridors drives demand where energy density requirements exceed CNG range limits. ASME Section VIII certified fabrication and nickel-alloy storage vessels elevate capital requirements substantially above compressed gas alternatives.
- Biogas:Upgraded landfill and dairy digester methane requires gas cleanup skids before pipeline injection or vehicle fueling.
- Hydrogen:Proton exchange membrane electrolyzers or steam methane reformers with carbon capture enable multi-fuel station architectures.
Most installed capacity flows through Compressed Natural Gas. Expansion is steepest in Liquefied Natural Gas.
Application:
Route predictability separates segments with guaranteed throughput from those requiring retail accessibility and demand risk.
- Commercial Fleets:Dedicated return-to-base operations at distribution centers and manufacturing campuses enable private station economics with 90-plus percent utilization rates. Walmart Transportation and J.B. Hunt anchor procurement with decade-long fuel purchase commitments that de-risk developer capital. EPA Phase 3 greenhouse gas standards tighten through 2032, preserving natural gas cost advantages against diesel in high-mileage duty cycles.
- Public Transportation:Municipal bus agencies with fixed routes and overnight depot parking favor time-fill CNG systems with lower compressor sizing. Transit authorities in California cities face CARB zero-emission vehicle mandates that compress investment windows toward renewable natural gas compatibility or fleet electrification alternatives.
- Heavy-Duty Vehicles:Class 8 long-haul trucking demands fast-fill 3,600 psi dispensers or LNG cryogenic pumps with dual-nozzle configurations.
- Light-Duty Vehicles:Consumer passenger car adoption remains constrained by limited OEM model availability and retail station accessibility.
Volume concentrates in Commercial Fleets. Climbing the fastest are Heavy-Duty Vehicles.
Distribution Channel:
Ownership structure and throughput commitment level determine whether operators bear full capital burden or access third-party infrastructure.
- On-site Refueling:Captive stations at private terminals eliminate retail margin extraction and enable fuel cost pass-through to fleet operating budgets. Schneider National and Werner Enterprises deploy telematics-integrated fueling with RFID authorization that compresses transaction friction and maximizes asset utilization. Inflation Reduction Act alternative fuel infrastructure tax credits stack with Section 45Q carbon capture incentives for renewable natural gas-upgraded installations.
- Centralized Stations:Multi-fleet access points along interstate corridors require higher throughput design and public retail accessibility. Clean Energy Fuels Corp anchors network density in North American freight corridors with volume commitments from diversified carrier bases.
- Retail Stations:Public access points serving mixed fleets and occasional users carry demand risk and require convenience store revenue integration.
- Containerized Solutions:Skid-mounted compressor and storage units enable rapid deployment without permanent civil works.
Revenue pools deepest in On-site Refueling. Gaining share fastest are Centralized Stations.
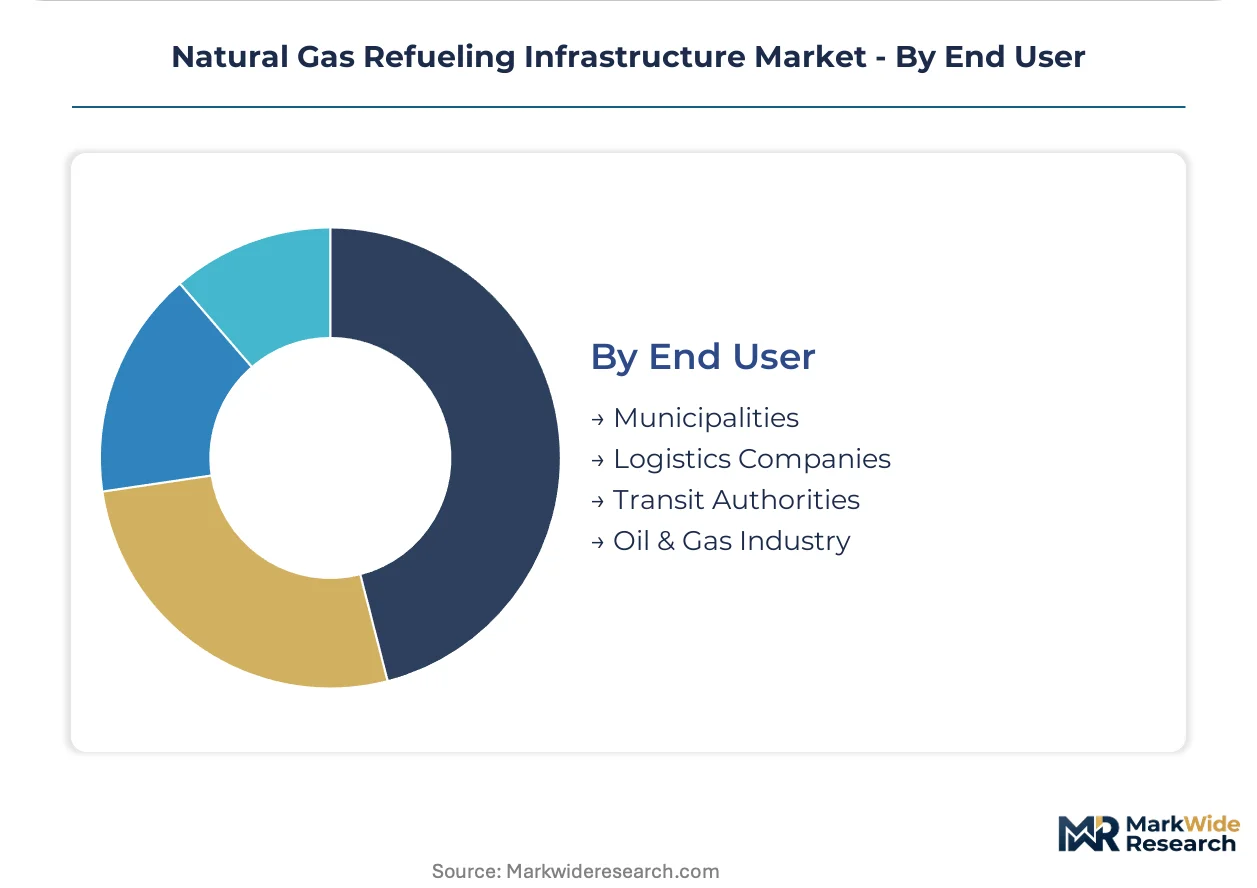
End User:
Procurement sophistication and balance sheet capacity separate municipal RFP processes from corporate fleet energy management platforms.
- Logistics Companies:Private carriers with 500-plus unit fleets aggregate fuel purchasing through third-party energy management platforms that displace direct station contracts and transfer price risk to intermediaries with hedging capabilities. Third-party logistics providers operating across multiple state jurisdictions drive consolidation of dispersed terminal network fueling arrangements.
- Municipalities:City and county governments issue RFPs with 10-15 year fuel purchase agreements that attract infrastructure developers seeking stable revenue streams. California local air quality management districts impose site-specific emission offsets that extend station commissioning timelines by 8-14 months.
- Transit Authorities:Regional public agencies blend federal transit administration capital grants with state clean fleet mandates to fund depot conversions.
- Oil & Gas Industry:Upstream and midstream operators leverage captive methane supplies for field service vehicle fleets.
Capital deployment concentrates with Logistics Companies. Steepest expansion trajectory belongs to Transit Authorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Gulf Coast industrial corridor anchors infrastructure deployment through its dense pipeline networks and heavy-duty freight concentration. Fleet operators exploit existing high-pressure distribution to minimize compressor capital outlays. This geographic pattern repeats across three additional national markets where regulatory pressure and industrial density intersect.
United States
California's Low Carbon Fuel Standard generates credit revenue streams for renewable natural gas-compatible station operators along interstate freight corridors. The EPA and NHTSA enforce Phase 3 greenhouse gas standards through 2032 that preserve natural gas cost advantages in high-mileage duty cycles. Texas Gulf Coast clusters leverage captive pipeline infrastructure to serve Walmart Transportation and J.B. Hunt fleet commitments with minimal incremental capital.
Germany
Industrial logistics corridors between Hamburg and Munich drive demand for LNG heavy-duty refueling along autobahn freight routes. The country's national transport regulator enforces CO2 fleet emission targets that accelerate alternative fuel infrastructure permitting. Bavarian manufacturing hubs anchor private station development for captive commercial fleets serving automotive and chemical supply chains.
China
Municipal bus agencies in Beijing-Tianjin-Hebei and Yangtze River Delta cities convert depots to compressed natural gas time-fill systems under national air quality mandates. The Ministry of Ecology and Environment enforces dual carbon goals that redirect provincial infrastructure subsidies toward biomethane-compatible equipment. Sichuan-Chongqing shale gas production clusters supply low-cost feedstock for regional trucking corridor development.
India
Compressed natural gas dominates urban transit conversions in Delhi-NCR and Maharashtra where city bus operators face tribunal-ordered emission deadlines. The Petroleum and Natural Gas Regulatory Board accelerates city gas distribution licensing that bundles vehicle fueling with residential and industrial connections. Gujarat industrial corridors deploy captive stations for cement and steel logistics fleets operating between Mundra Port and hinterland manufacturing zones.
Canada
British Columbia Low Carbon Fuel Standard mirrors California's credit mechanism, incentivizing renewable natural gas infrastructure along Vancouver-Seattle freight corridors. Environment and Climate Change Canada enforces methane reduction commitments that align provincial fleet procurement with biogas-upgraded station networks. Alberta oil sands service operators leverage stranded gas supplies for field vehicle captive fueling systems.
Natural Gas Refueling Infrastructure Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue hydrogen blending and multi-fuel platform architectures. The vendor base concentrates around three strategic archetypes: integrated energy majors with captive fuel supply chains, specialized cryogenic equipment fabricators, and network-density retail operators. Competitive positioning hardens through strategic partnerships linking upstream gas procurement to downstream fleet fueling contracts. Vertical integration of compression and storage manufacturing represents the dominant capacity expansion vector.
Within the network-density archetype, Clean Energy Fuels Corp exemplifies corridor-anchored retail positioning across North American freight routes. Chart Industries occupies the cryogenic specialization tier through liquefied natural gas terminal equipment dominance. Shell plc represents integrated energy major positioning with upstream-through-downstream fuel chain control. These three entities collectively illustrate the competitive structure without exhausting its participant roster.
| Leading Market Players |
|---|
| Clean Energy Fuels Corp |
| Chart Industries |
| Parker Hannifin Corp |
| Cryostar SAS |
| Atlas Copco AB |
| Shell plc |
| China National Petroleum Corporation |
| Gilbarco Inc |
| Greka Engineering and Technology Limited |
| Others |
Value Chain & Pricing Dynamics
Captive pipeline infrastructure integration in Texas and the US Gulf Coast anchors supply positions and pricing power for fleet-facing station developers. This backward integration into high-pressure distribution networks eliminates third-party gas procurement markups while locking in throughput commitments from Walmart Transportation and J.B. Hunt.
Pricing Analysis
Input-cost pass-through from austenitic stainless steel and nickel-alloy cryogenic vessels compresses equipment margins for LNG system fabricators. Three-tier pricing structure across ASME-certified premium, standard industrial, and containerized economy levels reflects certification burden and fabrication complexity. Pricing pressure stems from battery-electric Class 8 substitution threats in regional haul under 500 miles. Municipal transit authorities exhibit highest price sensitivity due to fixed budget cycles, while private logistics carriers with 500-plus unit fleets absorb premium positioning for operational control.
Supply Chain Analysis
ASME Section VIII certified welder availability concentrates in Gulf Coast petrochemical hubs and German industrial corridors around Hamburg and Munich. Cryogenic storage tank fabrication draws from austenitic stainless steel feedstocks and nickel-alloy vacuum insulation systems sourced through specialty metals distributors. Single-source vulnerability runs through concentrated ASME-certified fabrication capacity for pressure-rated components. Distribution runs through direct OEM-to-fleet contracts for captive stations and network-density retail operators for corridor-accessible infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Fleet procurement departments are consolidating through third-party energy management platforms that aggregate volume and transfer price risk, elevating specification requirements for RNG-compatible station architectures.
For Market Incumbents: Hedge electrification substitution by accelerating renewable natural gas certification investments before California Air Resources Board zero-emission mandates compress CNG investment windows. Reinforce corridor density through long-term fuel purchase commitments with J.B. Hunt and Schneider National that lock out competing network developers. Prioritize cryogenic technician training partnerships with Gulf Coast petrochemical institutes to defend service capabilities against capacity constraints. For New Entrants and Emerging Players: Begin with biogas corridor development in Pennsylvania and Ohio where stranded landfill methane awaits pipeline interconnection to vehicle fueling networks. Target marine bunkering infrastructure at Port of Long Beach where LNG-powered container ships create dual-use truck-to-ship transfer demand with vehicle fueling capability. Pursue telematics-integrated fueling partnerships with energy management platforms as the go-to-market angle for fleet aggregation. For Investors and Strategic Acquirers: Roll-up economics work for cryogenic equipment specialists because ASME certification barriers and vacuum insulation expertise concentrate in fragmented regional fabricators. Five-to-ten year viability hinges on RNG infrastructure upgrade cycles and Inflation Reduction Act credit stacking durability. Target acquisition archetype: regional station networks with renewable natural gas interconnection permits in Texas and California corridors. Watch EPA Phase 3 compliance timelines for natural gas engine manufacturers as the inflection signal for technology refresh capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Natural Gas Certification | CARB Low Carbon Fuel Standard credit eligibility secures decade-long revenue streams for corridor station operators. |
| Cryogenic Technician Training Partnerships | Gulf Coast petrochemical institute alliances address ASME Section VIII welder scarcity constraining LNG system maintenance capacity. |
| Telematics-Integrated Fueling Deployment | RFID-authenticated nozzle connections enable unattended overnight operations that maximize asset utilization for Schneider National and Werner Enterprises. |
| Biogas Corridor Pipeline Interconnection | Landfill gas capture projects in Pennsylvania and Ohio unlock stranded renewable methane supplies for vehicle fueling network expansion. |
| Marine Bunkering Infrastructure Dual-Use | Port of Long Beach shoreside transfer systems capture LNG container ship demand while serving heavy-duty trucking corridor fueling. |
Study Parameters
Direct dialogue with station developers, cryogenic equipment fabricators, fleet energy managers, and EPA regulatory affairs specialists grounded qualitative insights in operational realities. Secondary validation drew from EPA Greenhouse Gas Emissions Standards filings, CARB Low Carbon Fuel Standard credit transaction databases, FERC pipeline infrastructure reports, and SEC 10-K disclosures from publicly traded infrastructure operators. Bottom-up station deployment counts and top-down fuel consumption projections were triangulated to anchor volume estimates.
Bottom-up modeling of compressor station installations, storage cascade configurations, and dispenser throughput by technology tier was cross-checked against top-down fleet conversion trajectories and state-level clean fleet mandate schedules. Segmentation dimensions spanned compressed versus liquefied natural gas systems, commercial fleet versus public transportation applications, on-site versus centralized distribution channels, and logistics company versus municipal end-user procurement structures. CAGRs were derived from regression analysis of historical infrastructure deployment against regulatory compliance deadlines and fuel cost differential persistence across the analysis window.
Several conditions sit outside the modeled scope, including specific Inflation Reduction Act credit renewal outcomes beyond current authorization periods and unannounced battery-electric truck range breakthroughs that could accelerate Class 8 electrification substitution. Forecasts reflect assumptions about EPA Phase 3 compliance cost trajectories and CARB zero-emission vehicle pathway flexibility. Material deviation in federal tax credit structures or state-level clean fleet mandate enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Smart Fault Detection System for Power Transmission Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
LNG Infrastructure Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Pantograph Disconnector Market