
 Global Oil Storage Fee Rental Market | 2026-2036
Global Oil Storage Fee Rental Market Size, Share, and Industry Trends Forecast 2026-2036
Global Oil Storage Fee Rental Market Foresight
Refined product storage is expanding as refiners rebuild inventory buffers after years of lean operations. Royal Vopak dominates European liquid bulk infrastructure with specialized capacity for low-sulfur fuels. Oiltanking GmbH anchors German chemical corridor access through its Antwerp-Rotterdam-Rhine network. PSA International leverages Singapore's entrepôt status to capture transshipment storage flows between Middle Eastern producers and Asian buyers.
Oil storage fee rental denotes contracted access to tankage infrastructure where lessees pay periodic fees for custody transfer, blending, and throughput services without capital ownership. Modern floating roof tanks incorporate primary and secondary seal systems to minimize volatile organic compound emissions during crude oil handling. Tank farms command the largest revenue share due to their scale economies and integration with pipeline manifold systems. Spot leasing exhibits the fastest growth trajectory as commodity traders seek tactical inventory positions amid price volatility. Underground salt cavern storage retains premium pricing for strategic petroleum reserve applications where security and scale override unit costs.
EPA regulations under the Clean Air Act mandate vapor recovery and leak detection for aboveground storage tanks, elevating compliance costs for aging facilities. EU F-Gas Regulation and REACH framework impose material specifications on tank coatings and seal technologies that contact hydrocarbon streams. Singapore's Maritime and Port Authority enforces bunker fuel quality standards that drive demand for certified product segregation tankage. Stakeholders must monitor carbon border adjustment mechanisms and low-carbon fuel standards that could redirect product flows and reshape regional storage premiums.
Market Dynamics
Arbitrage-driven inventory cycling is compressing lease durations and fragmenting contract structures across tankage markets. Traders now rotate positions weekly rather than seasonally, forcing infrastructure owners to reconfigure tariff models around throughput velocity rather than static capacity reservation.
Growth Catalysts
- EU Green Deal biofuel mandates:European refiners are retrofitting existing tankage for hydrotreated vegetable oil and fatty acid methyl ester storage, generating incremental fee rental demand for dual-compatibility infrastructure.
- Floating roof seal technology:Advanced secondary seal systems for volatile organic compound control are expanding addressable market scope in EPA-regulated US Gulf Coast corridors where environmental compliance commands premium rates.
- Singapore bunker fuel quality enforcement:Maritime and Port Authority certification requirements for very low sulfur fuel oil segregation are tightening vessel supply chain standards and amplifying demand for certified independent storage.
Market Restraints
- Specialized steel input volatility:Corrosion-resistant alloys for sour crude service face price instability tied to nickel and molybdenum commodity swings, elevating replacement cost uncertainty for tank farm operators.
- Rotterdam-Antwerp supply concentration:Northwest European product storage capacity clusters within a 150-kilometer corridor, creating systemic congestion risk during simultaneous refinery maintenance cycles.
- Underground cavern technical limitation:Salt dome geology suitable for strategic petroleum reserve scale development is geographically sparse outside US Gulf Coast and select German sites, constraining expansion options.
Strategic Opportunities
- India product import infrastructure:Underdeveloped commercial tankage capacity at Mundra and Visakhapatnam ports creates first-mover positioning for fee-based operators as refining capacity lags domestic demand growth.
- Carbon border adjustment mechanism preparation:EU importers are pre-positioning certified low-carbon fuel inventories in Antwerp and Rotterdam ahead of 2026 full implementation, generating transitional storage demand.
- Digital twin and sensor convergence:Integration of real-time level monitoring with predictive maintenance platforms enables outcome-based service contracting that captures value from inventory visibility rather than cubic meter rental alone.
Industry Challenges
- API 653 inspection certification backlog:Qualified tank integrity assessors are concentrated among aging specialist pools, extending out-of-service periods for maintenance-scheduled capacity during peak demand windows.
- Legacy terminal automation integration:Brownfield sites with pneumatic control systems face complex retrofit requirements to interface with modern terminal management software, delaying operational efficiency gains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Oil Storage Fee Rental Market |
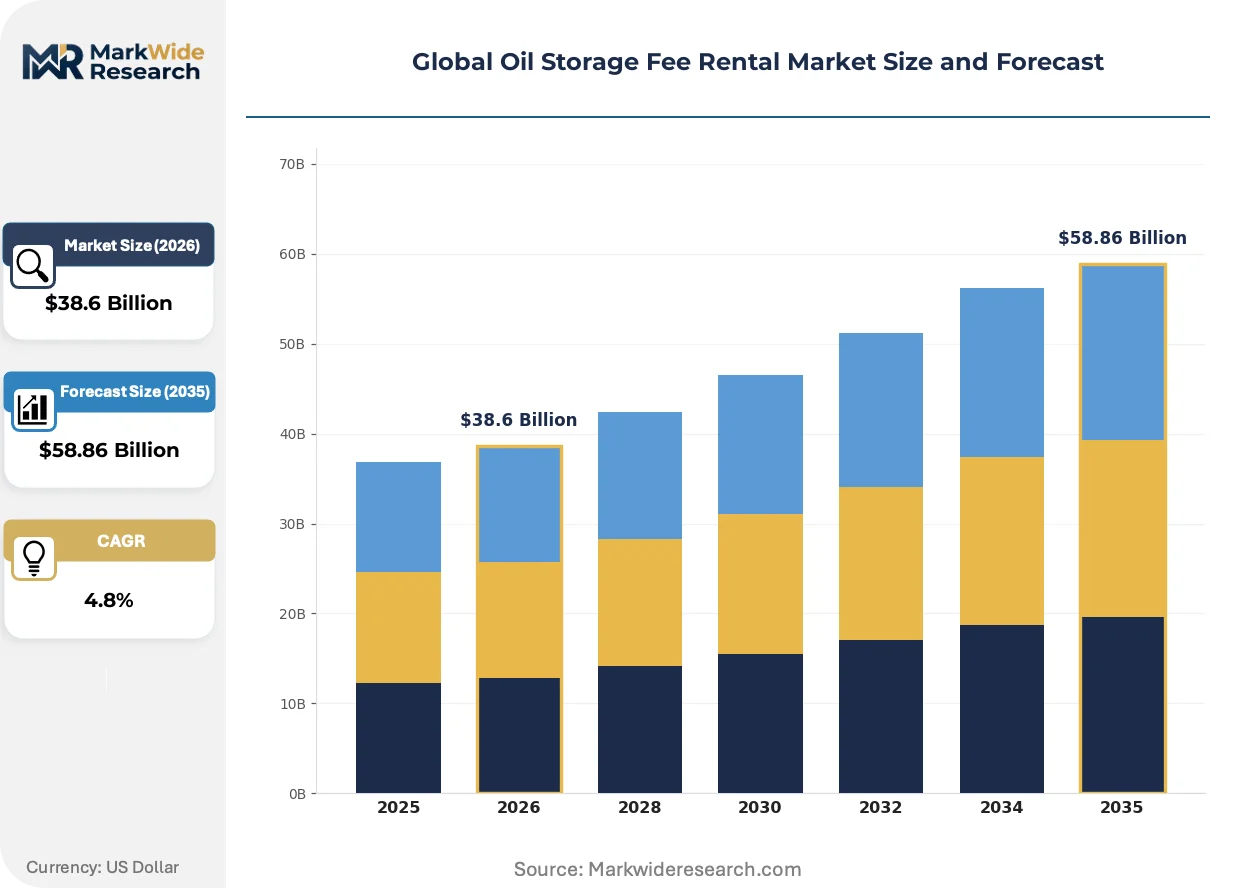
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Tank Farms, Underground Storage, Floating Roof Tanks, Spherical Tanks Application: Crude Oil, Refined Products, Petrochemicals, Biofuel Storage Customer Type: Oil Refiners, Trading Companies, Shipping Operators, Commodity Traders Contract Duration: Short Term, Mid Term, Long Term, Spot Leasing |
| Companies Covered | HORIZON TERMINALS, Feoso Group, PSA International, Oiltanking GmbH, VTTI, Royal Vopak, Jurong Port Universal Terminal Pte. Ltd., Sinopec Kantons Holdings Limited, Singapore Petroleum Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Oil Storage Fee Rental Market Shifts & Advancements
Floating roof tank design is converging with emissions control engineering as regulatory thresholds tighten and trader preferences shift toward certified low-leakage infrastructure. These developments are compressing the viable technology set and elevating capital requirements for competitive positioning.
Geodesic aluminum dome roof systems with integrated vapor recovery are consolidating market share in newbuild crude terminals. US Gulf Coast operators are specifying these structures for Eagle Ford and Permian-linked tankage to meet EPA Clean Air Act Maximum Achievable Control Technology standards. The technology is consolidating supplier tiers by eliminating marginal fabricators lacking API 650 Appendix G welding certification capabilities.
EU F-Gas Regulation phase-down schedules are accelerating membrane seal material transitions in existing floating roof retrofits. Refiners in the ARA cluster are replacing fluoropolymer primary seals with fluorine-free elastomer compounds to preempt 2027 import restrictions. Product segregation tankage for refrigerant-grade propane and butane is experiencing disproportionate compliance cost pressure as seal material specifications cascade through terminal engineering standards.
Spot market liquidity platforms are displacing traditional broker-mediated lease arrangements in Singapore and Houston. Commodity traders are accessing real-time capacity availability through terminal operator APIs, compressing contracting cycles from days to hours. This channel shift is most pronounced among independent trading houses lacking long-term throughput commitments with integrated oil majors.
Global Oil Storage Fee Rental Market Segmentation
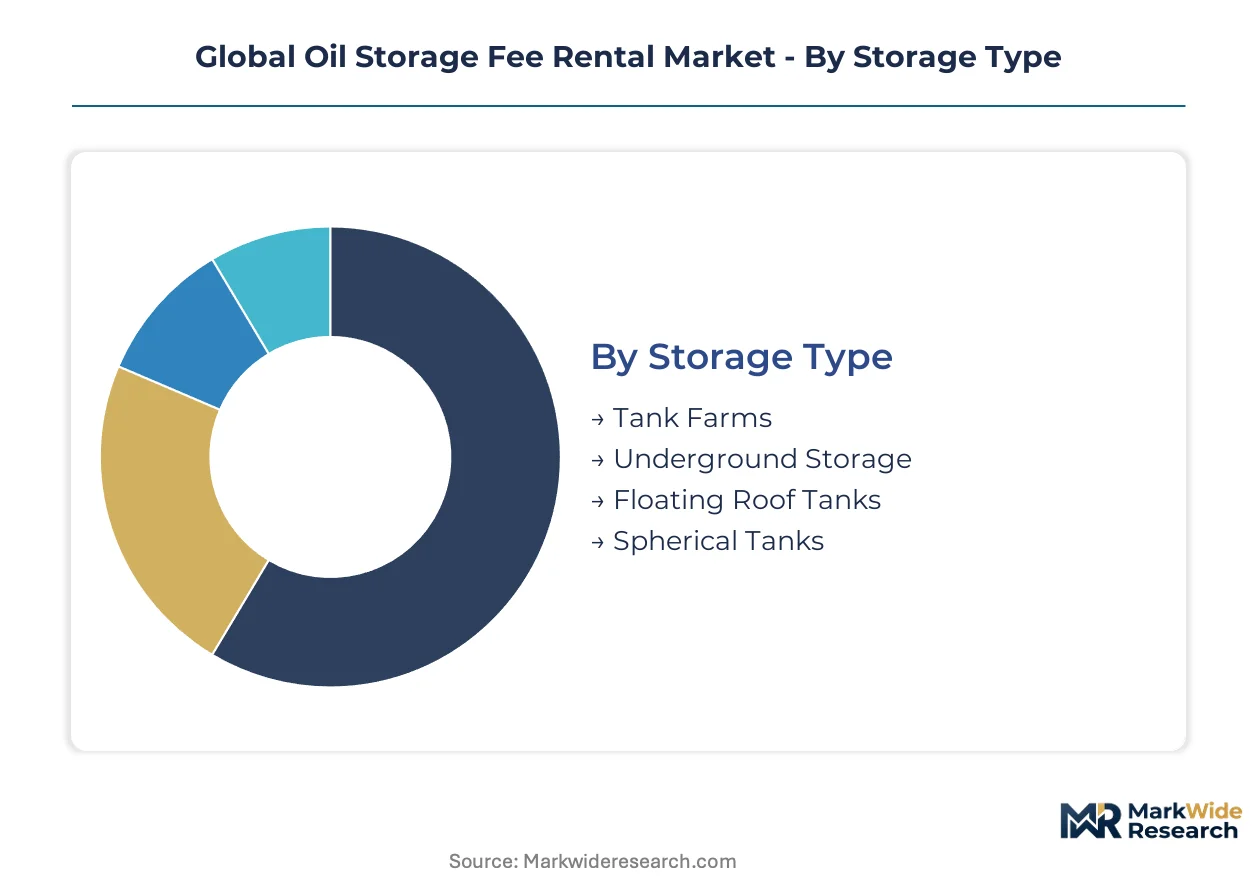
Oil storage fee rental markets fragment across infrastructure type, product handled, and counterparty risk profiles. Certification requirements vary sharply by segment, with EPA and EU F-Gas Regulation compliance costs determining viable operator economics in each category.
Storage Type:
EPA Clean Air Act Maximum Achievable Control Technology standards and EU F-Gas Regulation phase-down schedules impose divergent certification burdens across infrastructure categories.
- Tank Farms:Aboveground manifold-connected tankage with integrated pipeline systems commands scale premiums. Operators face API 653 inspection mandates and vapor recovery unit certification under EPA regulations. Demand concentrates at US Gulf Coast and ARA corridor hubs where traders require high-velocity throughput for arbitrage cycling.
- Underground Storage:Salt cavern and hard-rock facilities serve strategic petroleum reserve applications with 30-90 day injection/withdrawal cycles. Operators must demonstrate containment integrity under EPA Underground Injection Control permits or equivalent national geological survey certifications. Premium pricing persists where security and scale override unit costs.
- Floating Roof Tanks:Primary and secondary seal systems minimize volatile organic compound emissions during crude handling. Seal material transitions to fluorine-free compounds are accelerating under EU F-Gas Regulation timelines.
- Spherical Tanks:High-pressure vessels for liquefied petroleum gas and pressurized petrochemicals require ASME Section VIII pressure vessel certification and national boiler safety approvals.
Leading the category by volume: Tank Farms. Expanding most quickly: Floating Roof Tanks as environmental compliance tightens specification requirements.
Application:
Product-specific handling requirements determine tank coating specifications, segregation protocols, and therefore fee tier structures across rental contracts.
- Crude Oil:Sour crude service demands corrosion-resistant alloy construction and specialized internal coatings certified under NACE SP0169 standards. Demand clusters at Singapore and US Gulf Coast terminals serving arbitrage traders rotating weekly positions.
- Refined Products:Low-sulfur gasoline and diesel segregation requires dedicated manifold systems and certified cleanliness protocols. EU Green Deal biofuel mandates are retrofitting existing capacity for hydrotreated vegetable oil compatibility.
- Petrochemicals:Aromatic and olefin storage demands nitrogen blanketing systems and moisture exclusion certification under petrochemical industry handling standards.
- Biofuel Storage:Fatty acid methyl ester and hydrotreated vegetable oil handling requires material compatibility verification for elastomer seals and tank coatings under REACH framework specifications.
Volume leader: Crude Oil. Steepest expansion trajectory: Biofuel Storage as European refiners rebuild tankage for renewable mandate compliance.
Customer Type:
Counterparty credit profiles and throughput commitment structures segment rental pricing into distinct risk tiers with corresponding contract security requirements.
- Oil Refiners:Integrated operators with captive demand seek long-term reservation contracts with throughput guarantees. Credit support requirements are minimal given parent company balance sheet backing.
- Trading Companies:Mercuria and Trafigura-type houses rotate inventory tactically, demanding spot flexibility and API-enabled real-time capacity visibility. Letter of credit or margin posting requirements escalate with contract brevity.
- Shipping Operators:Vessel owners require transshipment tankage at Singapore and Rotterdam for bunker fuel blending and quality certification.
- Commodity Traders:Independent houses lacking major throughput commitments pay premium rates for short-duration access and rapid custody transfer capabilities.
Dominant contract volume: Oil Refiners. Fastest contract structure growth: Trading Companies as spot market liquidity platforms displace broker-mediated arrangements.
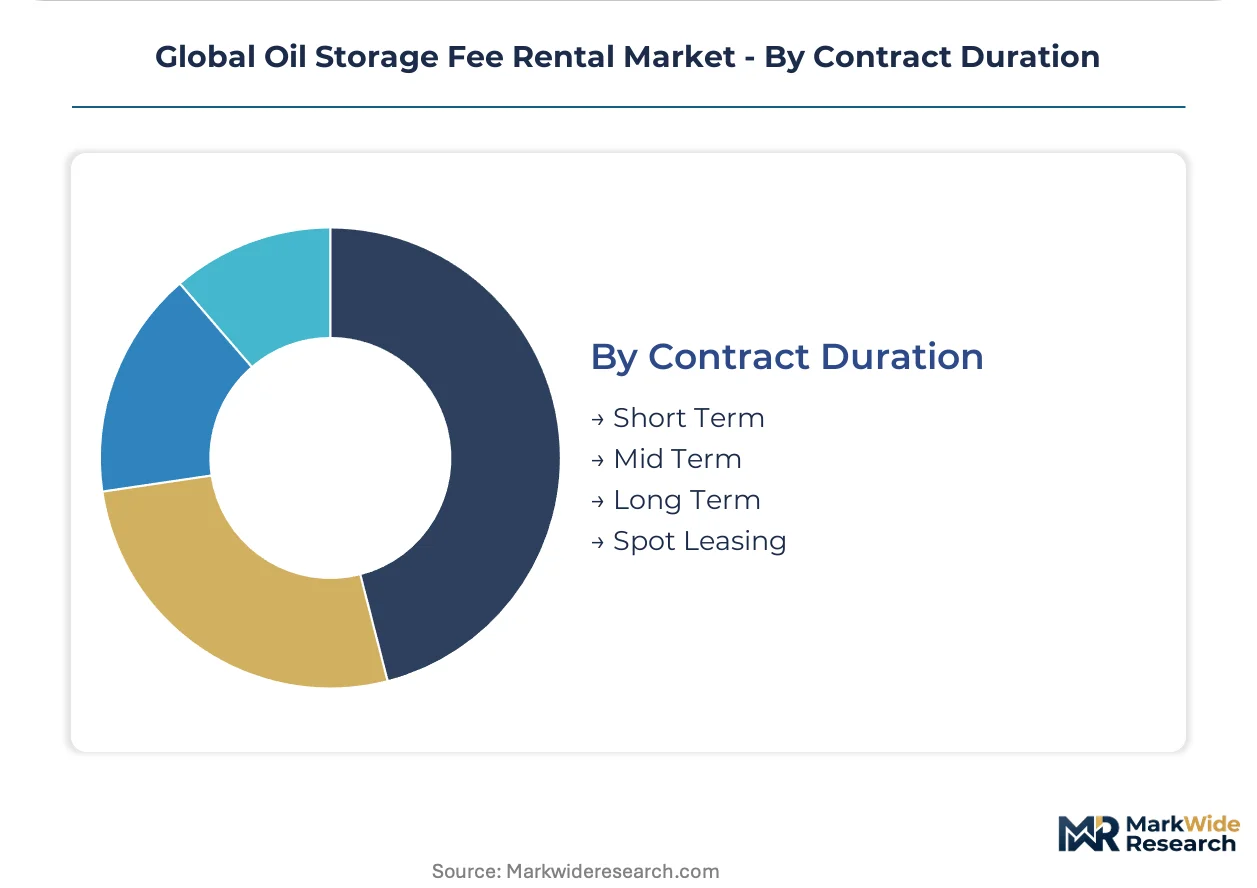
Contract Duration:
Duration selection reflects inventory strategy — strategic buffer building versus tactical arbitrage cycling — with tariff models reconfiguring around velocity rather than static reservation.
- Long Term:3-10 year take-or-pay structures dominate refiner captive capacity and strategic petroleum reserve leasing. Tariffs amortize capital recovery over extended horizons with inflation escalation clauses.
- Mid Term:6-36 month contracts balance commitment security with operational flexibility for seasonal demand patterning.
- Short Term:1-6 month arrangements serve maintenance cycle coverage and supply disruption hedging with elevated per-unit rates reflecting re-leasing risk.
- Spot Leasing:Hourly to weekly access through terminal operator APIs enables real-time arbitrage positioning. Singapore and Houston liquidity platforms compress contracting cycles from days to hours.
Revenue base anchor: Long Term. Gaining share fastest: Spot Leasing as traders fragment inventory cycles amid price volatility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes more crude oil than it produces, creating sustained demand for storage infrastructure at import and blending hubs. Singapore and Rotterdam serve as critical arbitrage nodes where traders rotate inventory between production basins and consumption centers. Storage fee premiums concentrate at these bottlenecks where pipeline, vessel, and tankage systems intersect.
United States
Gulf Coast refiners are rebuilding inventory buffers after years of lean operations, driving demand for tank farm capacity around Houston and Corpus Christi. EPA Clean Air Act Maximum Achievable Control Technology standards mandate vapor recovery systems for aboveground storage, elevating compliance costs for operators. The Permian-linked tankage corridor in Texas incorporates geodesic aluminum dome roof systems to meet emission thresholds.
Singapore
Maritime and Port Authority enforcement of very low sulfur fuel oil segregation standards is tightening supply chain certification requirements for bunker fuel storage. Traders access real-time capacity through terminal operator APIs, compressing spot leasing cycles from days to hours. Jurong Island anchors the regional tankage cluster where Middle Eastern crude streams blend for Asian buyer specifications.
Germany
EU F-Gas Regulation phase-down schedules are accelerating membrane seal material transitions in floating roof retrofits across the Antwerp-Rotterdam-Rhine corridor. Refiners replace fluoropolymer primary seals with fluorine-free elastomer compounds to preempt 2027 import restrictions. Salt cavern facilities in Lower Saxony serve strategic petroleum reserve applications with 30-90 day injection cycles.
Netherlands
Carbon border adjustment mechanism preparation is driving EU importers to pre-position certified low-carbon fuel inventories in Rotterdam ahead of 2026 full implementation. Royal Vopak dominates liquid bulk infrastructure with specialized capacity for hydrotreated vegetable oil and fatty acid methyl ester storage. The port's manifold-connected tankage enables high-velocity throughput for arbitrage cycling traders.
China
Domestic refining capacity expansion at Mundra and Visakhapatnam lags demand growth, creating import dependency that requires commercial tankage development. Sinopec Kantons Holdings anchors fee-based infrastructure positioning along coastal provinces. National oil companies prioritize long-term reservation contracts with throughput guarantees over spot market participation.
Global Oil Storage Fee Rental Market Competitive Landscape
Top-tier vendors anchor integrated terminal networks with pipeline manifold systems, while mid-scale operators compete on specialized product handling and regional access. The market structures around three archetypes: global infrastructure owners with multi-continental footprints, regional specialists dominating single-country corridors, and trading-house-affiliated operators capturing captive throughput. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators seek to lock in refiner commitments.
Among Singapore-based terminal operators, PSA International and Jurong Port Universal Terminal exemplify the entrepôt specialist archetype, leveraging the city-state's position between Middle Eastern producers and Asian buyers. Royal Vopak occupies a position representing the global infrastructure owner model with European liquid bulk dominance. Oiltanking GmbH anchors the regional specialist tier through German chemical corridor access. These three company structures illustrate how geographic positioning and counterparty relationships segment competitive space.
| Leading Market Players |
|---|
| HORIZON TERMINALS |
| Feoso Group |
| PSA International |
| Oiltanking GmbH |
| VTTI |
| Royal Vopak |
| Jurong Port Universal Terminal Pte. Ltd. |
| Sinopec Kantons Holdings Limited |
| Singapore Petroleum Company Limited |
| Others |
Supply & Pricing Matrix
EU Green Deal biofuel mandates are forcing European refiners to procure dual-compatibility tankage for hydrotreated vegetable oil and fatty acid methyl ester storage, compelling terminal operators to absorb retrofit capital costs into fee structures while spot markets fragment contract tenures.
Pricing Analysis
Short lead-time premiums dominate spot leasing arrangements as commodity traders rotate inventory positions weekly rather than seasonally. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and throughput velocity, with API 653-certified tankage commanding rate premiums. Cost compression in legacy pneumatic-control terminals is intensifying because digital twin integration demands capital outlays that aging facilities struggle to amortize. Trading companies exhibit highest price sensitivity due to margin-thin arbitrage cycling, while strategic petroleum reserve lessees accept premium rates for security and scale.
Supply Chain Analysis
Dual-sourcing requirements for corrosion-resistant alloys are emerging as refiners hedge against nickel and molybdenum price volatility in sour crude service applications. Supply concentrates in the United States, Germany, and Singapore where specialized fabricators cluster near demand hubs. Raw material dependencies center on high-grade steel plate, elastomer seal compounds, and vapor recovery unit components. Single-source vulnerability persists for fluorine-free elastomer formulations under EU F-Gas Regulation phase-down timelines. Distribution runs through terminal operator direct channels and API-enabled liquidity platforms displacing traditional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The oil storage fee rental market sits in a technology-transition phase as geodesic aluminum dome roof systems with integrated vapor recovery displace conventional floating roof designs under tightening EPA Clean Air Act standards.
For Market Incumbents: Deepen vertical integration into seal material supply chains to preempt fluoropolymer import restrictions under EU F-Gas Regulation timelines. Expand certified capacity at Singapore and ARA corridor hubs where trader demand concentrates. Retrofit legacy pneumatic control systems to capture outcome-based service contracting value from inventory visibility platforms. For New Entrants and Emerging Players: Terminal operator API channels offer lowest-friction entry paths for independent trading houses seeking real-time capacity visibility without long-term throughput commitments. Target underdeveloped commercial tankage at Mundra and Visakhapatnam ports where Indian product import infrastructure lags demand growth. Lead with digital twin-enabled predictive maintenance platforms that differentiate from incumbent static cubic meter rental models. For Investors and Strategic Acquirers: The window for entry favors mid-scale operators with specialized biofuel compatibility certifications ahead of carbon border adjustment mechanism full implementation. Five-to-ten year viability hinges on regulatory compliance positioning rather than commodity cycle timing. Watch for API 653 inspection certification backlogs as inflection indicator — extended out-of-service periods signal capacity scarcity pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Expands addressable market share at Singapore and ARA corridor bottlenecks where trader demand concentrates. |
| Backward Integration | Captures fluorine-free elastomer supply chains ahead of EU F-Gas Regulation 2027 import restrictions. |
| Green Certification Program | Positions tankage for hydrotreated vegetable oil and fatty acid methyl ester handling under EU Green Deal mandates. |
| Technology Licensing | Monetizes geodesic aluminum dome roof designs for EPA Clean Air Act compliance in US Gulf Coast terminals. |
| Long-term Supply Agreement | Locks in refiner throughput commitments amid arbitrage-driven inventory cycling fragmentation. |
Research Methodology
Trade publications, customs records, and terminal operator regulatory filings formed the secondary backbone of this analysis. Primary interviews with tank farm operations directors, commodity trading house logistics managers, refinery procurement leads, and EPC contractors specialized in storage infrastructure validated demand-side assumptions. Bottom-up capacity utilization modeling and top-down fee rental revenue triangulation anchored market size estimation across the analysis window.
Historical trendline analysis of tankage construction cycles and lease rate trajectories informed projection frameworks. Segmentation dimensions modeled include storage type, product handled, customer archetype, and contract duration tier. CAGRs were derived from capacity expansion pipelines and tariff model evolution rather than extrapolated from single-point observations. Forecast inputs incorporated EPA regulatory compliance cost curves and EU F-Gas Regulation phase-down schedules as demand shapers.
The model holds under stable regulatory enforcement timelines; deviation in carbon border adjustment mechanism implementation pace or API 653 inspector supply constraints would shift capacity availability assumptions materially. Deviation in nickel and molybdenum commodity volatility would alter replacement cost uncertainty for sour crude service tankage.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Energy Logistics Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Transmission and Distribution Fault Detection Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
North America DC Distribution Network Market
Transmission and Distribution
Global Industrial Distribution Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market