
 Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market Outlook
China's offshore wind corridor from Jiangsu to Fujian is tilting regional HVDC investment toward submarine cable systems. Siemens Energy anchors European-Asian technology transfer through its converter platform designs. Hitachi Energy leverages its Japanese manufacturing base to compete on ultra-high-voltage thyristor reliability. LS ELECTRIC Co., Ltd. dominates domestic Korean procurement for island interconnector projects.
High-Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity across distances exceeding 600 kilometers with losses below 3% per 1000 km, primarily serving cross-border interconnection and remote renewable evacuation. Voltage Source Converter technology leads new project awards due to superior grid-forming capability and black-start functionality. Offshore installation segments command premium engineering margins where submarine cable laying and platform integration create specialized contractor ecosystems. Long-distance transmission applications sustain mature demand across Australia's remote mining corridors and Southeast Asian archipelago links.
China's MEE enforces marine environmental assessments for submarine cable routes, while Japan's METI mandates earthquake-resistant converter station designs under revised grid codes. India's CEA is drafting HVDC corridor standards for renewable energy zones in Rajasthan and Gujarat. Stakeholders must monitor how divergent national certification timelines affect cross-border project delivery schedules.
Market Dynamics
Voltage Source Converter technology is displacing Line-Commutated Converter architectures across new project awards, compressing supplier margins on thyristor-based equipment while elevating grid-forming capability requirements.
Growth Catalysts
- Offshore wind evacuation corridors:China's coastal provinces from Jiangsu to Fujian mandate submarine HVDC links for gigawatt-scale wind farms, creating dedicated procurement streams for subsea cable-laying contractors.
- MIIT grid interconnection standards:China's tightened technical specifications for renewable penetration force synchronous condenser retrofits and converter station upgrades across provincial grids.
- Australian mining corridor electrification:Remote iron ore and lithium operations in Western Australia's Pilbara region require long-distance HVDC feeders to displace diesel generation.
Market Restraints
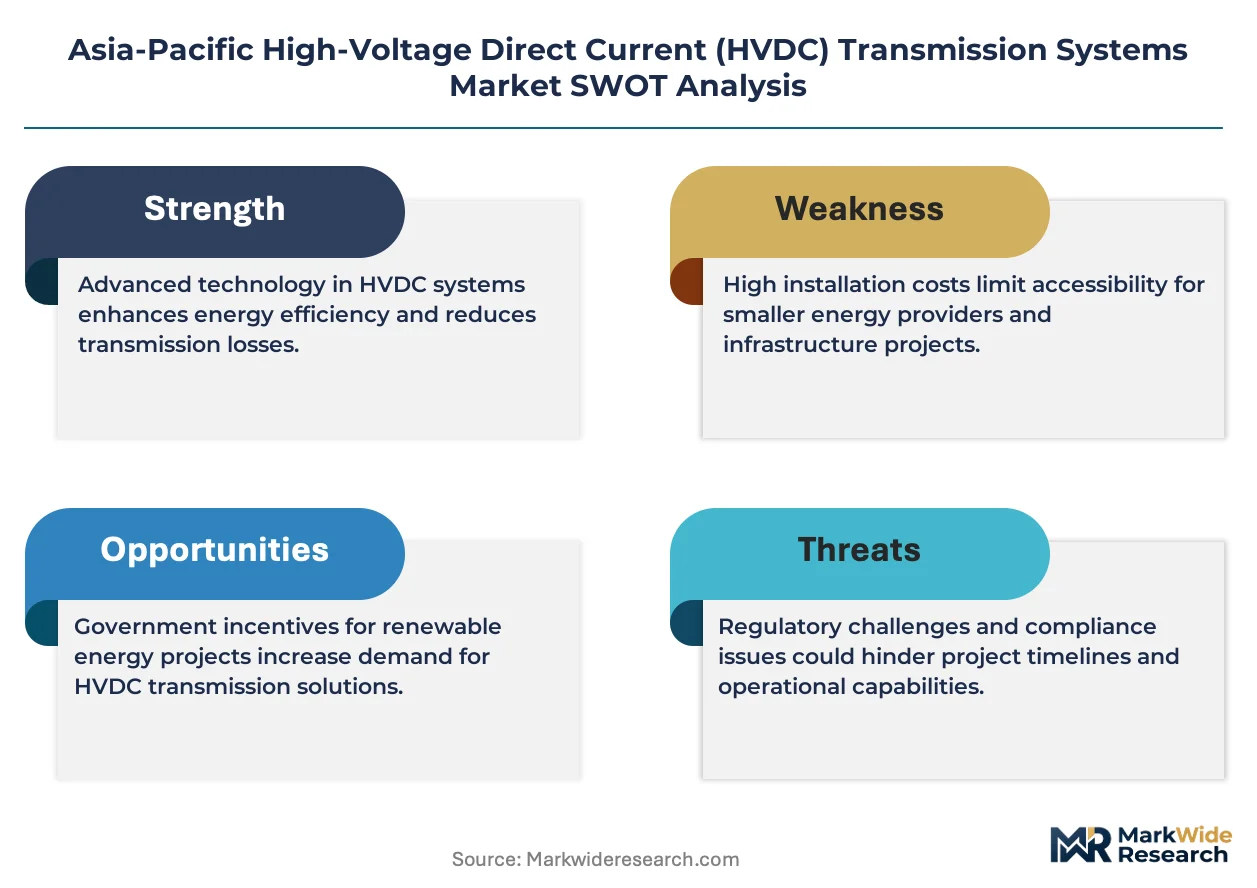
- Submarine cable supply concentration:European and Japanese cable manufacturers control 80% of qualified 525 kV+ subsea capacity, exposing Asian project timelines to single-source bottlenecks.
- Copper and rare earth input volatility:Converter station manufacturing depends on dysprosium and terbium for permanent magnet components, with Chinese export quotas amplifying price swings.
- Seismic design mandates:Japan's METI earthquake-resistant converter station specifications add 15-20% capital cost premiums versus conventional installations.
Strategic Opportunities
- Vietnam's offshore wind licensing round:The government's 7 GW seabed lease auction creates first-mover positioning for HVDC system integrators before domestic supply chains mature.
- Multi-terminal VSC overlay networks:Converging DC circuit breaker technology with modular multilevel converters enables meshed grid architectures beyond point-to-point links.
- India's CEA renewable zone standards:Draft HVDC corridor specifications for Rajasthan and Gujarat solar-wind hybrids will mandate dedicated transmission access codes.
Industry Challenges
- Subsea cable installation vessel scarcity:Only four Asia-Pacific flagged vessels rated for 500 kV+ cable burial operate across the region, compressing project windows.
- Converter station commissioning timelines:China's MEE marine environmental assessments and Japan's METI grid code certifications run on non-synchronized calendars, delaying cross-border interconnector energization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market |
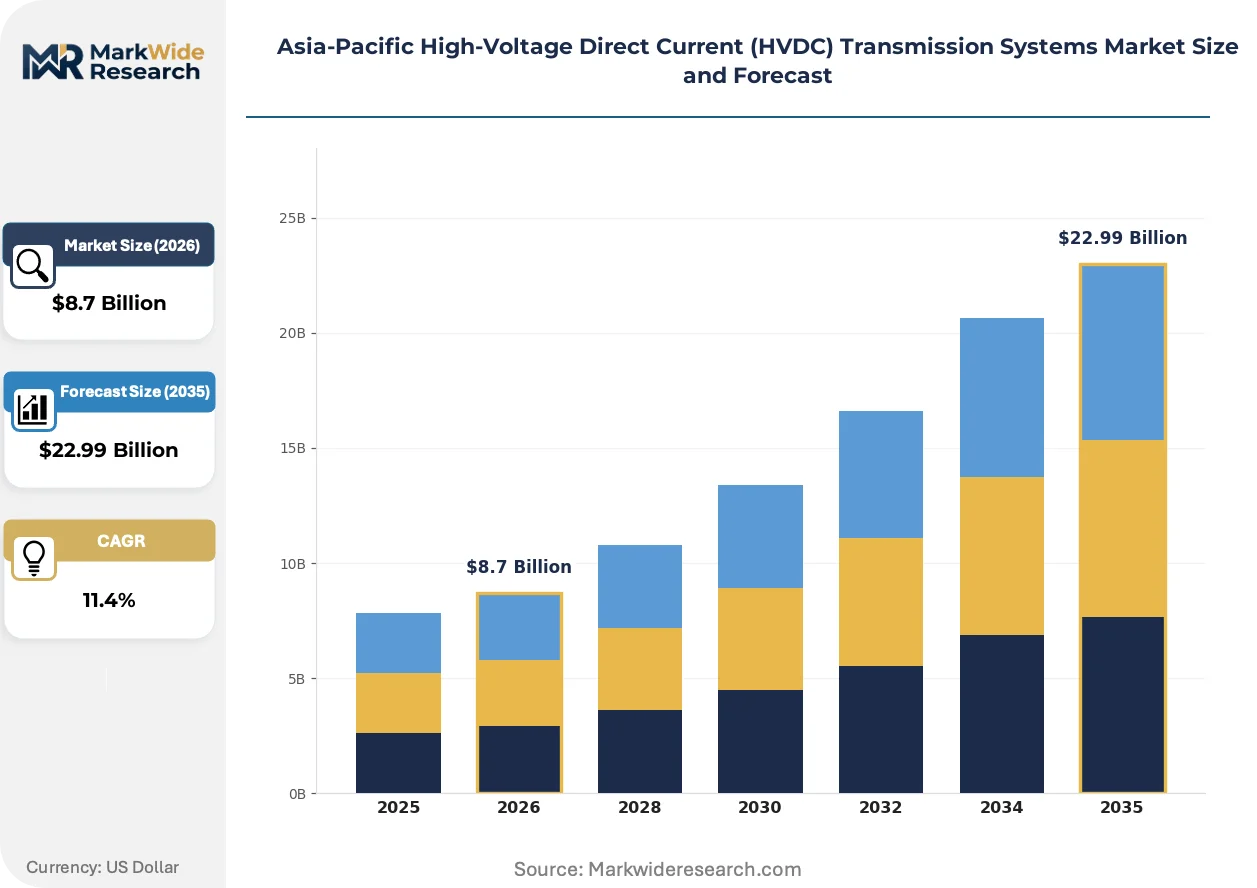
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Line Commutated Converter, Voltage Source Converter, Hybrid Converter, Others Application: Renewable Energy Integration, Long-Distance Transmission, Urban Power Supply, Offshore Wind Farms End User: Utilities, Industrial Sector, Renewable Energy Producers, Commercial Buildings Installation: Onshore, Offshore, Underground, Overhead |
| Companies Covered | GE Vernova, Prysmian Group, Hitachi Energy, LS ELECTRIC Co., Ltd., NR Electric Co., Ltd., Siemens Energy, Toshiba Corporation, NKT A/S, Mitsubishi Electric Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market Strategic Shifts
Modular multilevel converter topologies are compressing substation footprints while enabling black-start services, reshaping how island grids and offshore platforms integrate bulk power transfer.
Silicon carbide power semiconductors are migrating from traction and aerospace applications into HVDC valve assemblies. Japanese converter manufacturers now prototype 3.3 kV SiC modules for medium-voltage DC collection networks. This migration from silicon IGBTs is halving switching losses and enabling air-cooled converter halls versus liquid cooling infrastructure.
China's MEE marine environmental assessment protocols now require benthic habitat mapping across entire cable route corridors before seabed disturbance permits issue. The industrial consequence extends front-end engineering timelines by 8-14 months for Taiwan Strait and Yellow Sea projects. Offshore wind developers in Fujian and Guangdong provinces are responding by pre-emptively commissioning multi-beam sonar surveys two years ahead of financial close.
State-owned grid operators across the Asia-Pacific region are consolidating HVDC procurement into framework agreements spanning 5-7 year horizons. This buyer concentration is displacing project-specific tendering, forcing equipment vendors to absorb volume-commitment penalties and localize converter platform fabrication. The shift is most visible in China's State Grid Corporation annual ultra-high-voltage batch tenders, where 2024-2026 commitments now cover twelve submarine and land cable corridors.
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
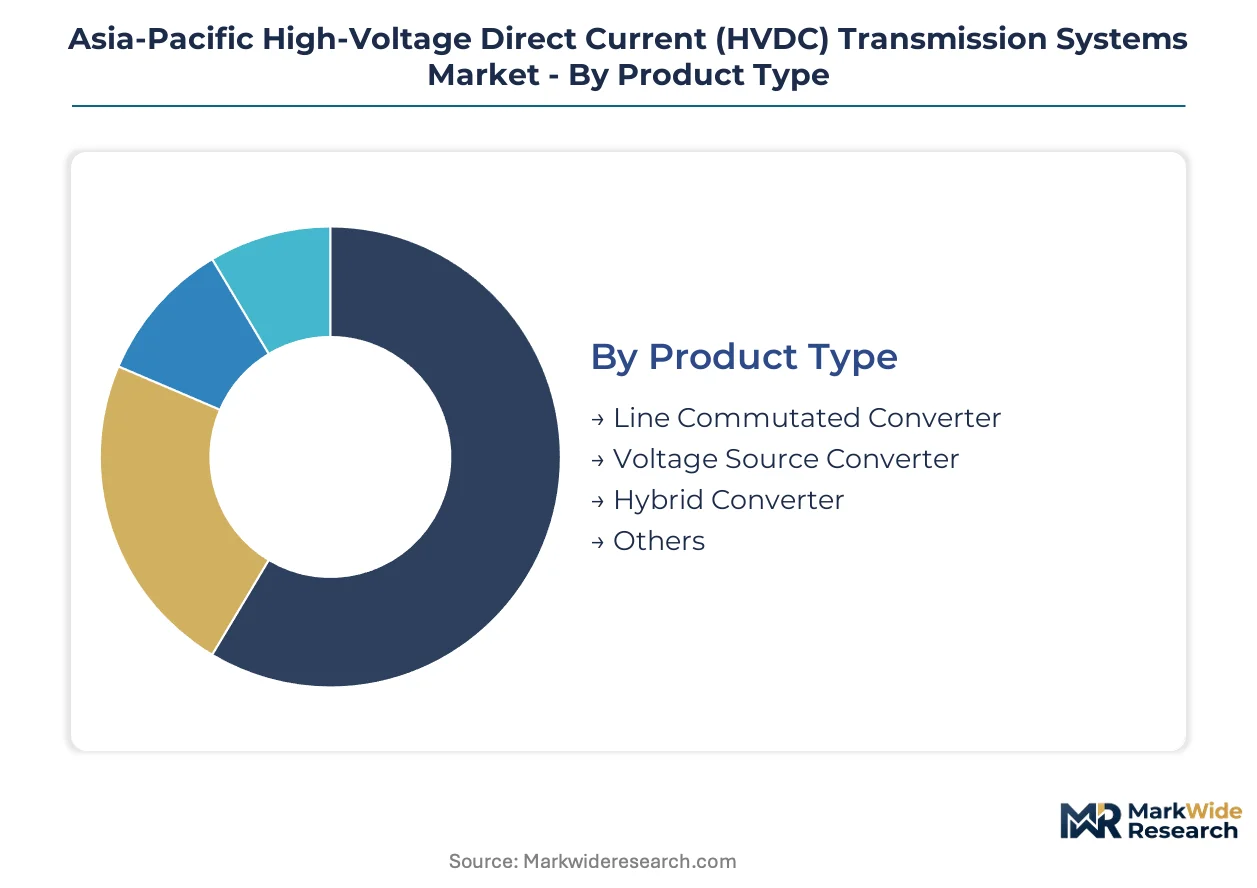
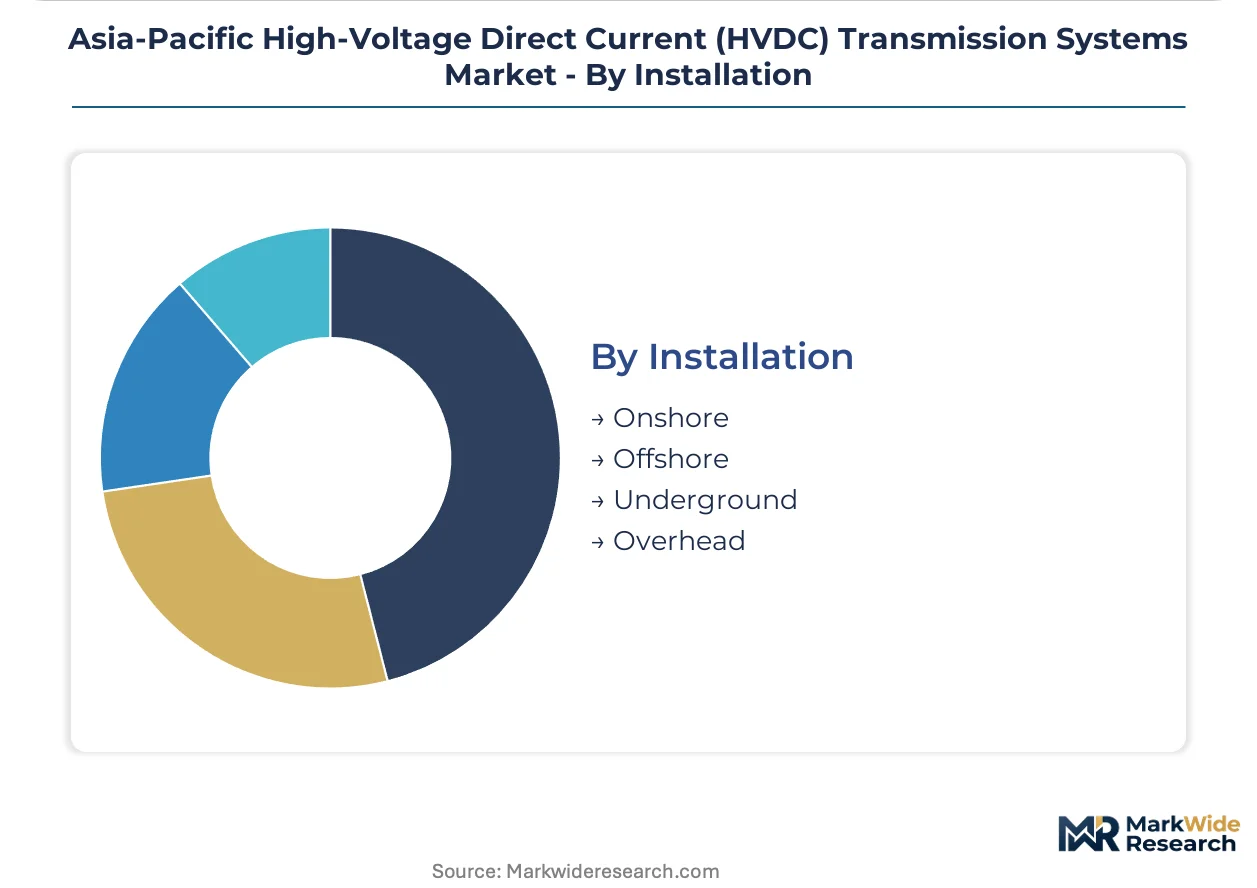
HVDC system procurement cycles vary dramatically across technology types and installation environments. Converter technology selection locks in 25-30 year asset lifecycles, while installation mode determines front-end engineering duration and contractor specialization requirements.
Product Type:
Voltage Source Converter platforms refresh every 8-12 years through software-defined control upgrades, whereas Line Commutated Converter hardware remains static for decades. Procurement velocity concentrates where grid-forming capability commands premium pricing.
- Voltage Source Converter:Modular multilevel topology enables black-start functionality and reactive power support without synchronous compensation. China's coastal provinces from Jiangsu to Fujian specify VSC for offshore wind evacuation where grid stability mandates fast-frequency response.
- Line Commutated Converter:Thyristor-based architectures dominate legacy bulk transmission corridors exceeding 800 kilometers with established reliability records. Australia's Pilbara mining region continues procuring LCC for iron ore electrification where capital cost sensitivity outweighs grid services requirements.
- Hybrid Converter:Combines thyristor rectification with IGBT inversion for cost-optimized asymmetric power flow.
- Others:Experimental topologies including current source converters for specialized industrial feeds.
Line Commutated Converter dominates installed base across the Asia-Pacific region. Voltage Source Converter is where expansion concentrates as renewable penetration tightens grid code requirements.
Application:
Project economics diverge sharply between greenfield renewable evacuation and brownfield urban reinforcement. Offshore wind applications command engineering margins 40-60% above terrestrial equivalents due to marine logistics complexity.
- Offshore Wind Farms:Submarine cable systems rated 320-525 kV connect gigawatt-scale arrays to onshore substations across China's Taiwan Strait and Yellow Sea corridors. Fujian and Guangdong developers pre-emptively commission benthic surveys 24 months ahead of permitting to accommodate MEE marine environmental protocols.
- Renewable Energy Integration:Collector systems aggregate dispersed solar and wind assets onto HVDC backbones for long-distance injection. India's Rajasthan and Gujarat renewable zones are driving procurement as CEA drafts dedicated transmission access codes for hybrid solar-wind projects.
- Long-Distance Transmission:Point-to-point links exceeding 600 kilometers serve remote resource extraction and archipelago interconnection.
- Urban Power Supply:Compact VSC substations with reduced audible noise and electromagnetic footprint penetrate dense metropolitan load centers.
Long-Distance Transmission holds the deepest installed base across Australian mining corridors and Southeast Asian island links. Offshore Wind Farms is climbing the fastest as China's coastal provinces accelerate seabed leasing.
End User:
Utility procurement runs on 5-7 year framework agreements with volume-commitment penalties, while industrial buyers negotiate project-specific tenders with faster decision cycles.
- Utilities:State Grid Corporation and China Southern Power Grid consolidate ultra-high-voltage batch tenders covering twelve submarine and land corridors through 2026. Procurement concentration forces equipment vendors to localize converter platform fabrication or absorb penalty clauses.
- Renewable Energy Producers:Offshore wind developers in Vietnam's 7 GW seabed licensing round seek first-mover positioning before domestic supply chains mature, compressing supplier qualification timelines.
- Industrial Sector:Remote mining and smelting operations in Western Australia specify dedicated HVDC feeders to displace diesel generation.
- Commercial Buildings:Data center campuses in Singapore and Tokyo evaluate medium-voltage DC distribution for hyperscale efficiency gains.
Utilities dominate capital deployment across the Asia-Pacific region. Renewable Energy Producers is gaining share fastest as Vietnam, Taiwan, and South Korea accelerate offshore wind procurement.
Installation:
Marine installation windows compress project schedules to 4-6 month annual weather windows, while terrestrial methods permit year-round construction with lower contractor specialization barriers.
- Offshore:Only four Asia-Pacific flagged vessels rated for 500 kV+ cable burial operate across the region, creating single-source bottlenecks for Taiwan Strait and Yellow Sea projects. Subsea platform integration with converter stations demands joint-venture structures between European technology licensors and Asian marine contractors.
- Onshore:Converter station construction follows standardized civil engineering patterns with established EPC pricing benchmarks. Japan's METI earthquake-resistant specifications add 15-20% capital cost premiums versus conventional installations.
- Underground:Urban corridor routing through dense metropolitan areas requires horizontal directional drilling and thermal management systems.
- Overhead:Lattice tower corridors persist across Australia's interior and India's Rajasthan desert where right-of-way constraints are minimal.
Onshore installation retains the largest cumulative footprint across existing transmission networks. Offshore is expanding most quickly as submarine cable procurement scales with China's offshore wind corridor development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Fujian-Guangdong submarine cable corridor anchors Asia-Pacific HVDC deployment, with China's offshore wind zones underwriting regional investment gravity. State Grid Corporation's batch tendering consolidates procurement across coastal provinces, while Japan's island interconnectors and Australia's mining corridors sustain parallel demand streams.
China
Jiangsu and Fujian provinces drive submarine HVDC procurement for gigawatt-scale offshore wind arrays. MIIT tightened grid interconnection standards force synchronous condenser retrofits across provincial networks. The Taiwan Strait corridor concentrates cable-laying contractor activity as developers commission benthic surveys 24 months ahead of MEE permitting.
Japan
Island interconnector projects between Honshu and Kyushu sustain thyristor-based system demand. METI mandates earthquake-resistant converter station designs that add capital cost premiums to conventional installations. The Chubu region around Nagoya hosts specialized fabrication for seismic-rated platform components.
South Korea
Jeju Island power links and offshore wind evacuation routes drive procurement for Voltage Source Converter platforms. Domestic content requirements favor local suppliers for island interconnector projects. LS ELECTRIC Co., Ltd. anchors Korean fabrication capacity through dedicated converter platform production.
Australia
Western Australia's Pilbara mining region requires long-distance HVDC feeders to displace diesel generation at remote iron ore and lithium operations. The country's national energy regulator maintains technical standards for remote resource extraction electrification. Queensland's renewable energy zones are evaluating collector system integration with interstate transmission backbones.
India
Rajasthan and Gujarat solar-wind hybrid zones are driving procurement as CEA drafts dedicated HVDC corridor standards. The country's central electricity authority mandates transmission access codes for renewable energy zones. Gujarat's Kutch Peninsula concentrates early-mover developer activity ahead of formal regulatory finalization.
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream on converter valves and submarine cable manufacturing. The supplier base concentrates around European-Japanese technology licensors and emerging Asian fabricators. Three archetypes dominate: full-system integrators with offshore platform capabilities, cable specialists with subsea installation assets, and domestic champions serving protected procurement markets. Competitive moves center on framework agreement volume commitments and converter platform localization mandates.
Among European-Asian technology transfer partners, Siemens Energy and Hitachi Energy occupy positions bridging design licensing with regional manufacturing scale. LS ELECTRIC Co., Ltd. exemplifies the domestic champion archetype, leveraging Korean industrial policy preferences for island interconnector awards. These three entities represent distinct competitive vectors: technology transfer, manufacturing proximity, and procurement protection.
| Leading Market Players |
|---|
| GE Vernova |
| Prysmian Group |
| Hitachi Energy |
| LS ELECTRIC Co., Ltd. |
| NR Electric Co., Ltd. |
| Siemens Energy |
| Toshiba Corporation |
| NKT A/S |
| Mitsubishi Electric Corporation |
| Others |
Value Chain & Pricing Dynamics
European and Japanese cable manufacturers control 80% of qualified 525 kV+ subsea capacity, concentrating margin capture in the upstream manufacturing tier while downstream system integrators absorb volume-commitment penalties under framework agreements. This asymmetry forces converter platform vendors to localize fabrication or forfeit procurement access to State Grid Corporation batch tenders.
Pricing Analysis
MIIT grid interconnection standards dictate the pricing tier structure across converter station procurement, separating seismic-rated Japanese METI-certified installations from conventional Chinese coastal configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying as domestic Korean suppliers leverage LS ELECTRIC Co., Ltd.'s localized fabrication capacity. Renewable energy producers in Vietnam's licensing round exhibit highest price sensitivity, while Japanese utilities under METI mandates accept premium positioning for earthquake-resistant designs.
Supply Chain Analysis
Dysprosium and terbium feedstock from Chinese export quotas anchors converter valve manufacturing costs, with permanent magnet components drawing from concentrated rare earth processing capacity. Copper conductor supply rests on Chilean and Peruvian mining output, while submarine cable insulation compounds source from German and Japanese petrochemical specialists. Single-source vulnerability in 500 kV+ cable-laying vessels creates chokepoint exposure for Taiwan Strait projects. Distribution runs through state-owned utility framework agreements with 5-7 year horizons, displacing project-specific tendering channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HVDC procurement is consolidating into platform-economics structures where interoperability standards and converter control software ecosystems determine supplier lock-in. Meshed DC grid architectures enabled by circuit breaker convergence will reshape competitive positioning toward system orchestration capabilities.
For Market Incumbents: Insulate thyristor-based revenue streams against VSC displacement by embedding synchronous condenser retrofit services into MIIT compliance offerings. Anchor converter platform localization in Fujian and Guangdong provinces to satisfy State Grid Corporation volume-commitment penalties. Defensive patent positioning around modular multilevel converter control algorithms provides leverage against emerging Korean and Chinese equipment vendors. For New Entrants and Emerging Players: Build out Vietnam's 7 GW seabed licensing round before domestic supply chain maturation closes qualification windows. Target Australia's Pilbara mining corridor electrification where capital cost sensitivity outweighs grid services requirements and incumbent presence remains thin. Lead with hybrid converter architectures combining thyristor rectification with IGBT inversion for asymmetric power flow applications. For Investors and Strategic Acquirers: Capital is best deployed toward subsea cable installation vessel operators and marine survey contractors serving MEE benthic habitat mapping requirements. Long-term viability hinges on exposure to front-end engineering timelines extending 8-14 months for Yellow Sea projects. Watch for CEA finalization of Rajasthan and Gujarat HVDC corridor standards as inflection indicator for Indian market acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Converter Platform Localization | State Grid Corporation framework agreements mandate domestic fabrication or penalty absorption. |
| Submarine Cable Vessel Acquisition | Only four Asia-Pacific flagged vessels rated for 500 kV+ burial operate across the region. |
| Seismic Certification Investment | METI earthquake-resistant specifications add 15-20% capital cost premiums in Japanese procurement. |
| Multi-terminal VSC Overlay Development | DC circuit breaker convergence enables meshed grid architectures beyond point-to-point links. |
| Benthic Survey Pre-commissioning | MEE marine environmental protocols extend front-end engineering timelines by 8-14 months. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of regulatory filings, project development databases, and equipment procurement records. Interviews with utility planning officers, EPC contractors, submarine cable manufacturers, and grid code certification specialists informed demand-side and supply-side assessments. Secondary validation drew from MIIT technical specifications, MEE environmental protocols, METI grid codes, CEA draft standards, and IEA transmission investment tracking. Bottom-up project pipeline analysis triangulated against top-down macroeconomic load growth assumptions.
Forecast inputs span converter technology type, installation environment, application segment, and end-user procurement mode across the projection horizon. Segmentation modeling incorporated voltage class, platform topology, submarine versus terrestrial routing, and utility versus industrial buyer archetype. CAGRs were derived from weighted average of historical award patterns and pipeline conversion probability. Industry-specific inputs included offshore wind seabed leasing velocity, rare earth export quota trajectories, and vessel availability constraints.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-owned equipment vendors or Japanese SiC semiconductor specialists would shift outcomes. Cross-checking against IEA and national regulator transmission investment disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Germany DC Distribution Network Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
South America City Gas Distribution Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Fixed Series Compensation Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
High Voltage Direct Current (HVDC) Transmission System Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Modular Sub-Station Market