
 Gas Insulated Substation Market | 2026-2036
Gas Insulated Substation Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Insulated Substation Market Intelligence
Fluoronitrile-based gas mixtures, an eco-friendly alternative to sulfur hexafluoride (SF6), is consolidating its role as the preferred dielectric medium in new high-voltage GIS designs. Siemens Energy AG leverages its 'blue portfolio' of SF6-free products to capture contracts under stringent environmental regulations. General Electric Company competes through its g³ (Green Gas for Grid) technology, developed in partnership with Hitachi Ltd, to serve utilities seeking lower carbon footprints.
A gas insulated substation is a compact, metal-encapsulated switchgear that uses a compressed insulating gas, traditionally SF6 at high pressure, for dielectric insulation. Its primary function is to provide reliable switching, protection, and control for high-voltage electrical circuits in space-constrained environments like urban centers. High voltage systems dominate investment from utilities for national grid expansions. The renewable energy end-user segment represents the fastest-growing opportunity, specifically for outdoor and modular installations.
The EU F-Gas Regulation directly mandates reductions in SF6 usage, shaping product development toward alternatives. In parallel, standards from the IEC and monitoring by the US EPA govern the technical specifications, safety, and handling protocols for high-voltage switchgear. Manufacturers must now decide whether to invest in a single SF6-alternative technology or maintain a portfolio of solutions for varied regional compliance and customer preferences.
Market Dynamics
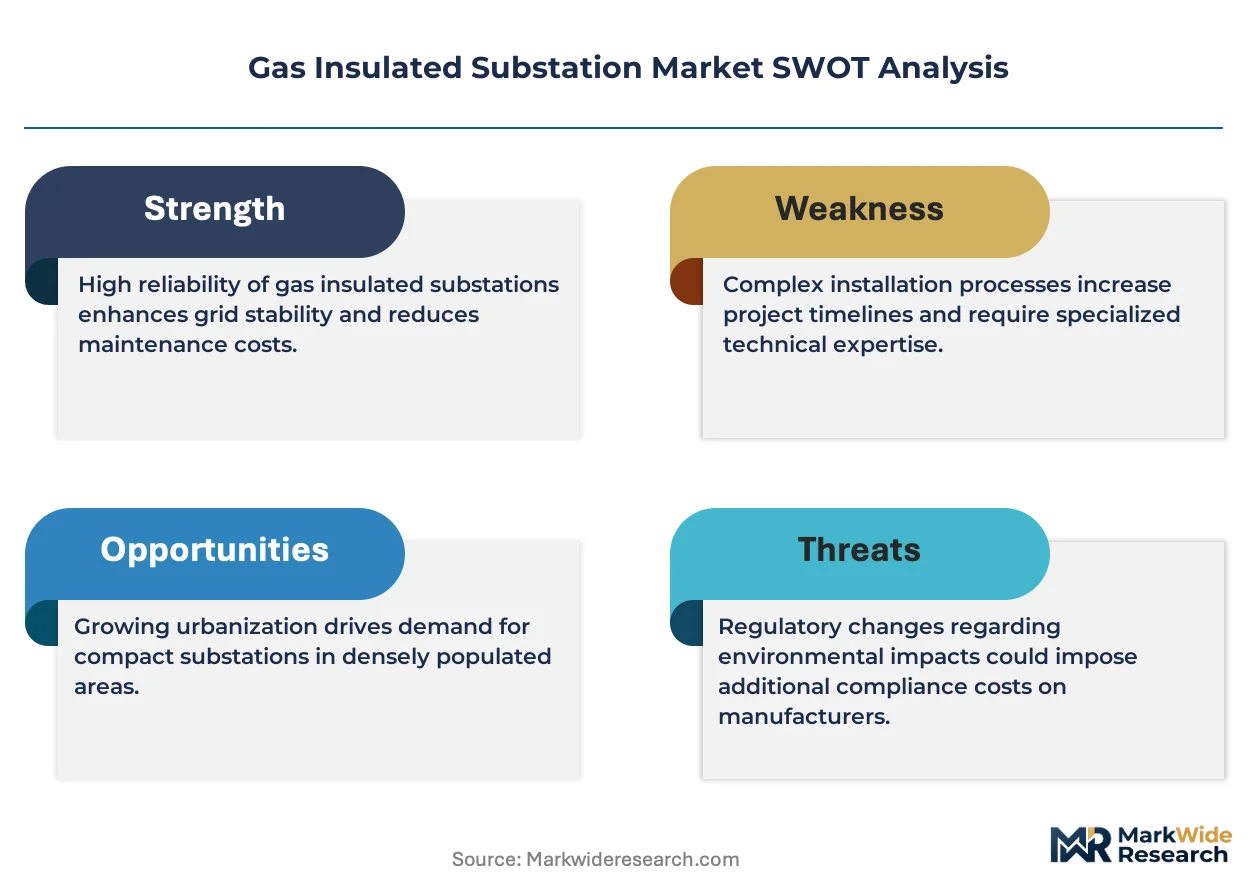
The imperative to phase out sulfur hexafluoride (SF6) under regulatory scrutiny is the central force shaping the market. This pressure compels a technology transition towards environmentally benign insulating gases for high-voltage switchgear applications.
Growth Catalysts
- Renewable Energy Integration:Demand from offshore wind and large-scale solar farms requires compact, high-performance GIS for efficient grid connection and space optimization in high-value land or sea locations.
- Grid Modernization in China:State-led investment in upgrading high-voltage transmission networks, driven by the nation's dual carbon goals, creates sustained demand for GIS technology.
- EU F-Gas Regulation:The mandated phase-down of potent greenhouse gases creates a captive market for SF6-free alternatives across European utilities, accelerating technology adoption.
Market Restraints
- High Initial Capital Outlay:GIS installations carry a significant upfront investment compared to traditional air-insulated substations, limiting adoption by budget-constrained utilities in developing economies.
- Performance Data Scarcity:SF6-alternatives like fluoronitrile mixtures lack the decades of in-field operational history of SF6, creating hesitation among conservative utility asset managers.
- Fluoronitrile Supply Concentration:Key components for eco-friendly gas mixtures are sourced from a few chemical manufacturers, posing a potential supply chain bottleneck risk.
Strategic Opportunities
- Data Center Power Infrastructure:The need for uninterruptible, high-density power for hyperscale data centers creates an opportunity for compact, highly reliable GIS solutions.
- Grid Expansion in India:India's national grid expansion, guided by the Central Electricity Authority (CEA), presents a vast, underpenetrated market for new GIS installations.
- Digitalization and IoT Integration:Embedding sensors into GIS units for predictive maintenance and asset health monitoring opens new service-based revenue streams for manufacturers.
Industry Challenges
- Specialized Workforce Scarcity:A shortage of technicians skilled in the handling and diagnostics of both high-pressure gas systems and next-generation digital control platforms is a key constraint.
- Legacy System Interoperability:Integrating new SF6-free GIS units with existing grid assets that still rely on SF6 technology presents significant engineering and operational challenges.
- Evolving IEC Standards:Navigating evolving IEC standards for SF6-alternative gases and associated certification timelines delays new product introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Insulated Substation Market |
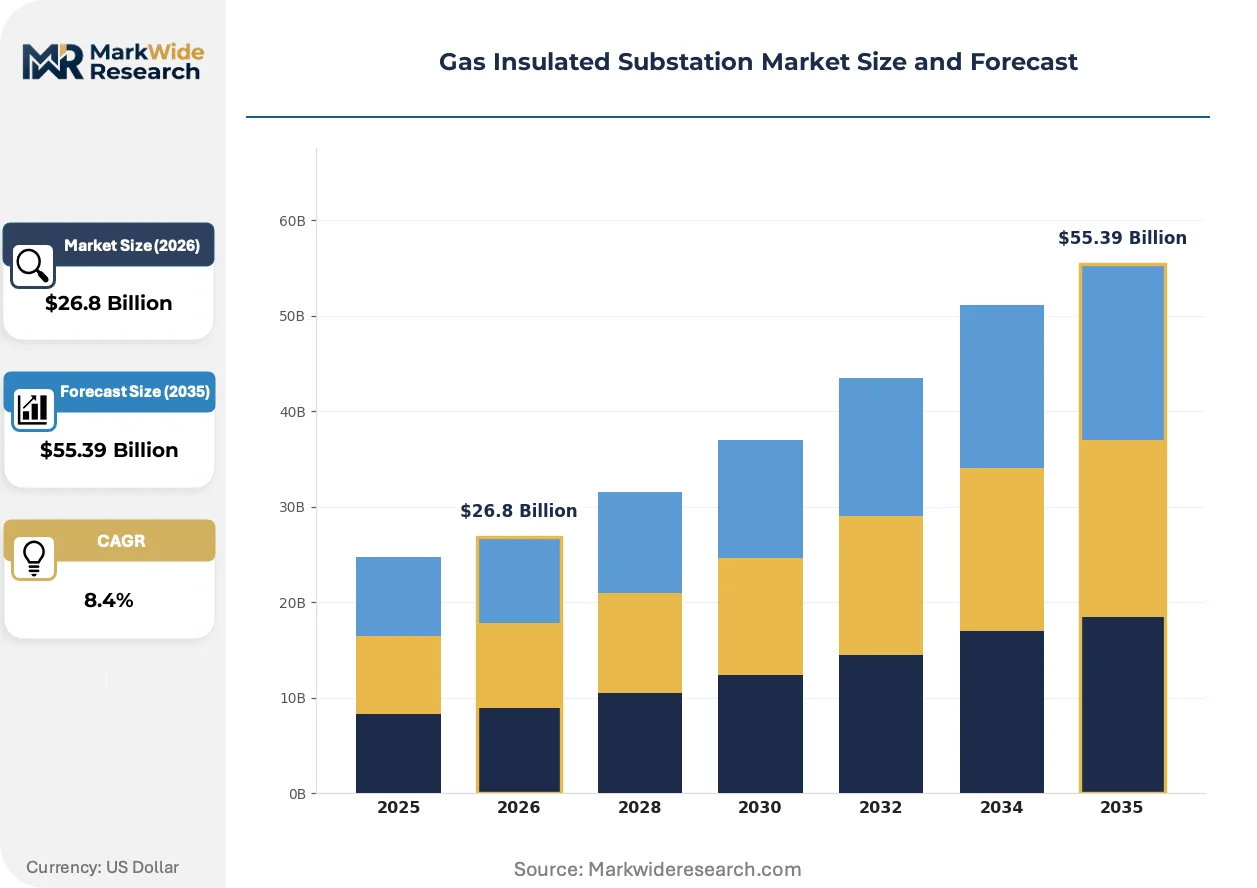
| Market Size in 2026 | $26.8 Billion |
| Market Size in 2035 | $55.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High Voltage, Medium Voltage, Low Voltage, Switchgear End User: Utilities, Industrial Facilities, Commercial Buildings, Renewable Energy Technology: Air Insulated, Hybrid Systems, Digital Solutions, Control Systems Installation: Indoor, Outdoor, Modular, Fixed |
| Companies Covered | ABB Ltd, Siemens Energy AG, General Electric Company, Mitsubishi Electric Corporation, Schneider Electric SE, Hitachi Ltd, Larsen & Toubro Limited, Toshiba Energy Systems & Solutions Corporation, Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Insulated Substation Market Strategic Shifts & Innovations
Decarbonization mandates and grid decentralization are fundamentally altering substation design and investment priorities. The focus is shifting from simple capacity expansion to integrating intermittent renewables and enhancing grid resilience through advanced, environmentally compliant technologies.
Digital twin technology creates a virtual replica of a physical GIS asset for simulation, diagnostics, and operational planning. Utilities adopt this for predictive maintenance and operator training, reducing physical interventions and extending asset life. This capability is modularizing GIS design, enabling component-level upgrades and flexible deployment in decentralized energy networks.
Regulatory frameworks like the US Inflation Reduction Act (IRA) provide significant incentives for investments in clean energy infrastructure. This policy accelerates utility capital expenditure on grid upgrades necessary to connect new renewable generation sources. The high-voltage GIS segment benefits directly, as these projects require compact and efficient substation solutions.
A shift in procurement sees utilities moving from one-time capital purchases towards long-term service agreements that cover maintenance and end-of-life gas handling. This unbundles the physical asset from its operational management, favoring suppliers who offer comprehensive lifecycle support. This is most visible in Europe, where the F-Gas Regulation makes compliant gas management a critical service.
Gas Insulated Substation Market Segmentation
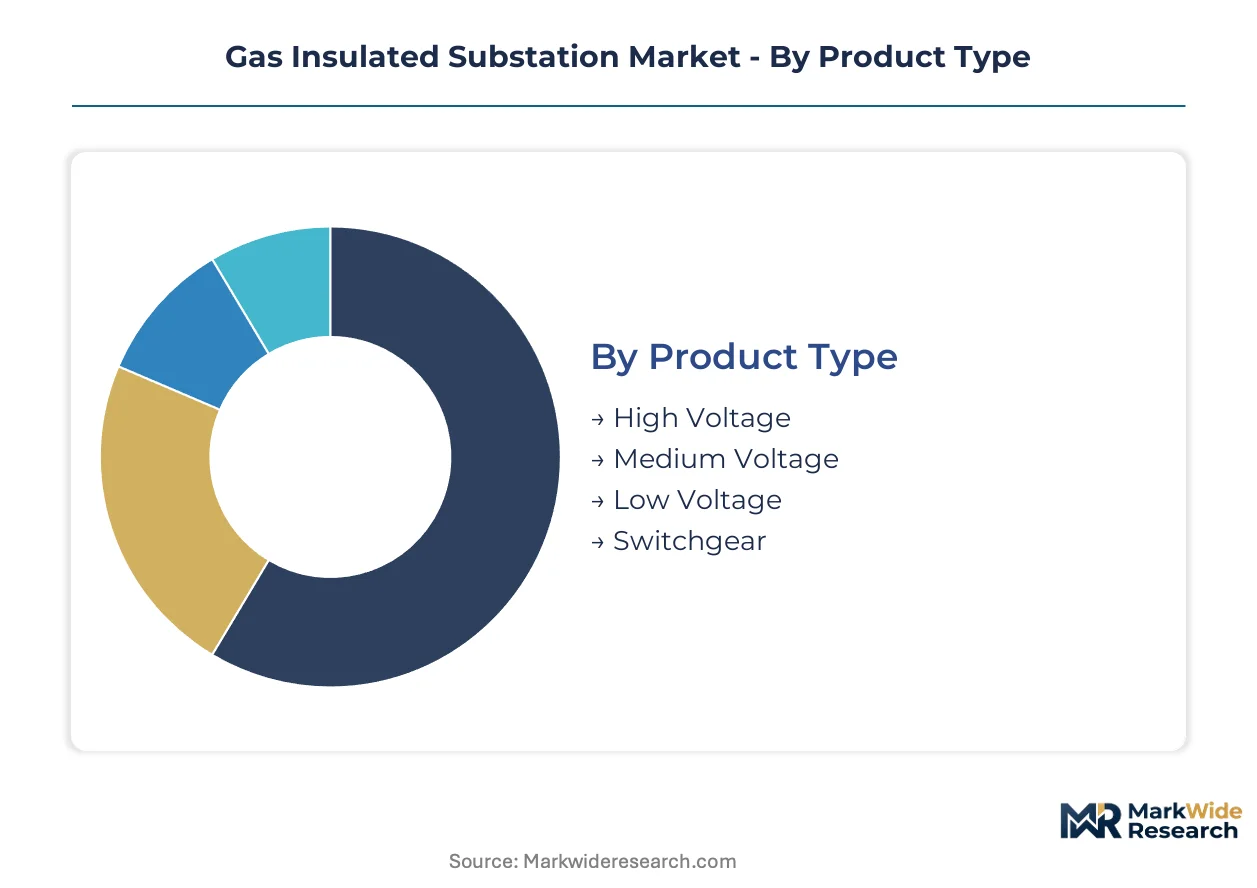
The Gas Insulated Substation (GIS) market segmentation reflects diverse operational needs and technological advancements across the global energy infrastructure. Understanding these segments helps manufacturers tailor offerings to specific utility requirements and emerging grid modernization projects.
Product Type:
Buyer decisions for GIS product types center on voltage requirements and integration needs within the existing grid infrastructure.
- High Voltage:These systems operate at 145 kV and above, crucial for long-distance power transmission and primary substations. Demand concentrates heavily within China's grid modernization initiatives, driven by the nation's dual carbon goals.
- Switchgear:Encompasses the core components for circuit protection, control, and isolation within a GIS unit. Investment in SF6-free switchgear is accelerating across Europe due to the EU F-Gas Regulation.
- Medium Voltage:These GIS units typically operate between 1 kV and 145 kV, serving distribution networks and industrial applications. Utilities in India are upgrading medium voltage infrastructure.
- Low Voltage:Designed for voltages below 1 kV, these compact systems are used in commercial buildings and specialized industrial facilities. Commercial building projects prioritize space-saving designs.
High Voltage leads on scale; Switchgear leads on momentum.
End User:
The end-user application dictates the specific GIS configuration, influencing design and operational parameters.
- Utilities:National and regional power companies deploying GIS for grid expansion, stability, and reliability. Utilities prioritize long-term asset reliability and compliance with standards from bodies like the IEC.
- Renewable Energy:Projects like offshore wind farms and large-scale solar installations require compact, high-performance GIS for efficient grid connection. This segment represents the fastest-growing trajectory, particularly for outdoor and modular installations.
- Industrial Facilities:Manufacturing plants, data centers, and heavy industries use GIS for robust and compact power distribution. Hyperscale data centers require uninterruptible, high-density power solutions.
- Commercial Buildings:Urban commercial developments and high-rise structures utilize GIS for space-constrained, reliable power supply. Urbanization trends drive demand for compact substation footprints.
Utilities drive foundational demand; Renewable Energy represents the fastest-growing trajectory.
Technology:
Technology choices reflect the ongoing digital transformation of grid assets and the imperative for enhanced monitoring.
- Hybrid Systems:These combine elements of air-insulated and gas-insulated switchgear, offering a balance of compactness and cost-effectiveness. Utilities seek hybrid solutions for substation upgrades in constrained spaces.
- Digital Solutions:Involves integrating sensors, communication protocols, and analytics for real-time monitoring and predictive maintenance. Digital twin technology is adopted by utilities for simulation and operational planning.
- Air Insulated:Traditional substation technology using atmospheric air for insulation, typically less compact than GIS. Developing economies still deploy air-insulated systems due to lower initial capital outlay.
- Control Systems:These manage and automate the operation of GIS components, ensuring grid stability and protection. Modern control systems facilitate remote operation and integration with SCADA.
Digital Solutions drive future-proof grid operations, while Hybrid Systems gain share through integration.
Installation:
Installation type is primarily determined by available space, environmental exposure, and operational flexibility.
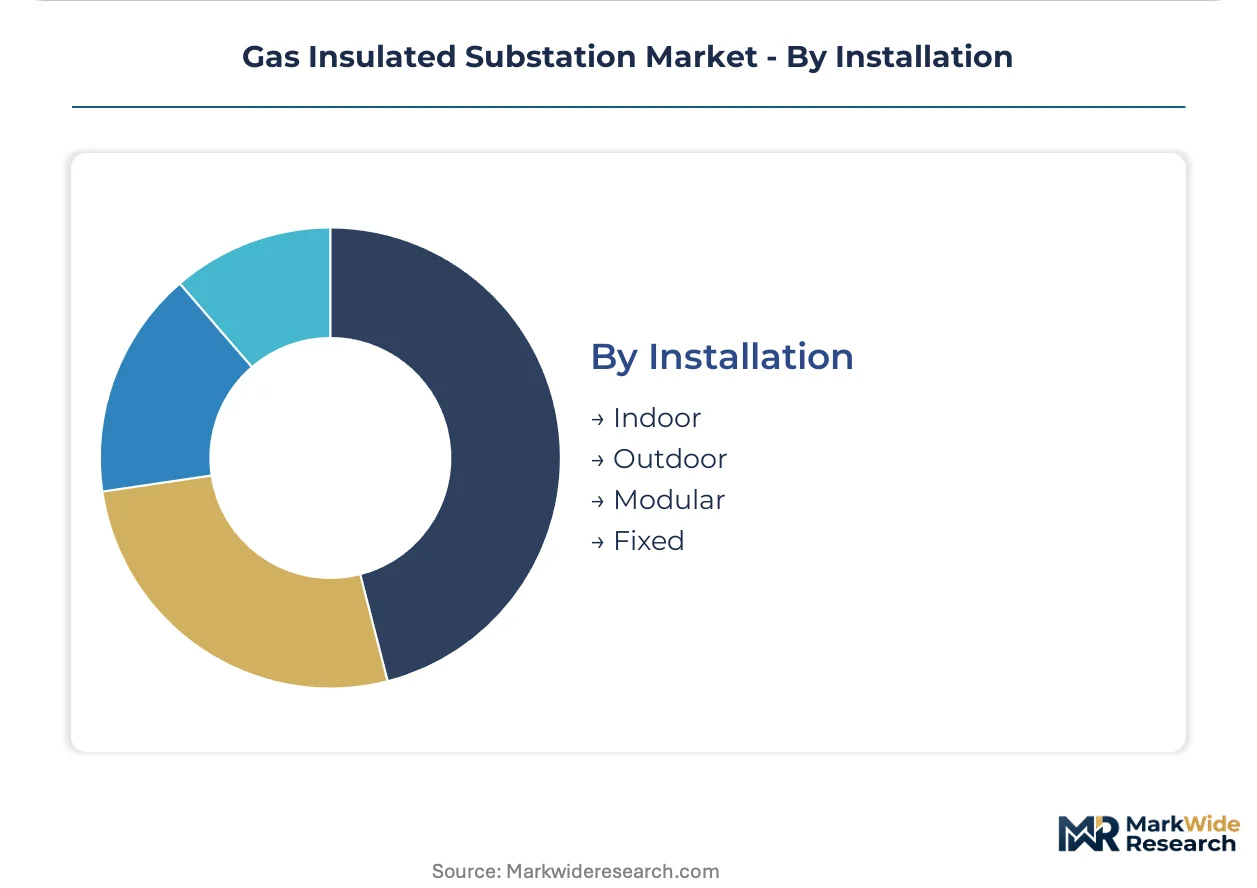
- Indoor:GIS units installed within a building or enclosure, offering protection from environmental elements and requiring less land area. Urban centers favor indoor installations due to space constraints.
- Outdoor:GIS units designed for direct outdoor exposure, often used in renewable energy projects and remote substations. Offshore wind connections frequently deploy robust outdoor GIS solutions.
- Modular:Pre-assembled and factory-tested GIS components that can be quickly deployed and expanded. Modular designs reduce installation time and enhance flexibility for decentralized energy networks.
- Fixed:Permanently installed GIS configurations, typically for large, central substations with long operational lifespans. National grid expansions in countries like India utilize fixed installations.
Modular installations offer deployment flexibility; Outdoor systems adapt to environmental conditions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's rapid industrialization and urbanization drive significant demand for Gas Insulated Substations (GIS) across the global market. Key regions worldwide are focused on grid modernization, renewable energy integration, and phasing out SF6 gas. Regulatory mandates and national infrastructure plans shape investment priorities in these diverse geographies.
China
State-led investment in upgrading high-voltage transmission networks creates sustained demand for GIS technology. The nation's dual carbon goals accelerate the deployment of advanced, compact substation solutions. The Yangtze River Delta region, a major economic hub, sees significant activity in new grid connections for industrial growth.
Germany
The imperative to phase out sulfur hexafluoride (SF6) under the EU F-Gas Regulation drives demand for SF6-free GIS alternatives. Renewable energy integration, particularly from offshore wind, requires compact and efficient substations. Bavaria, a leader in renewable energy generation, invests heavily in modernizing its grid infrastructure.
India
India's national grid expansion, guided by the Central Electricity Authority (CEA), presents a vast market for new GIS installations. Utilities are upgrading medium voltage infrastructure to enhance reliability and capacity. Maharashtra, with its significant industrial base, is a key focus for these essential grid modernization projects.
United States
Investments in clean energy infrastructure, spurred by the US Inflation Reduction Act (IRA), accelerate utility capital expenditure on grid upgrades. Connecting new renewable generation sources requires compact and efficient substation solutions. California, with its ambitious clean energy targets, leads in deploying advanced GIS technology for grid resilience.
Gas Insulated Substation Market Key Industry Players
Global majors compete with regional champions across technological innovation and market access within the Gas Insulated Substation market. The market structure appears moderately consolidated, characterized by a tiered landscape of established players and niche specialists. Strategic archetypes include diversified industrial conglomerates, specialized switchgear manufacturers, and emerging SF6-free solution providers. Dominant competitive moves involve strategic partnerships for technology development and portfolio diversification into eco-friendly solutions.
Global industrial conglomerates like Siemens Energy AG and General Electric Company occupy significant positions, leveraging their extensive R&D capabilities to develop next-generation SF6-free technologies. These companies often represent the premium tier, offering comprehensive solutions for high-voltage applications. Hitachi Ltd, a diversified Japanese conglomerate, also sits within this group of major players, contributing to the development of advanced g³ (Green Gas for Grid) technology in partnership with General Electric Company.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens Energy AG |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Schneider Electric SE |
| Hitachi Ltd |
| Larsen & Toubro Limited |
| Toshiba Energy Systems & Solutions Corporation |
| Eaton Corporation PLC |
| Others |
Cost & Logistics Intelligence
Diversified industrial conglomerates, with their extensive R&D budgets, influence both supply chain stability and the pricing of advanced Gas Insulated Substation (GIS) technologies. Their control over proprietary SF6-free solutions allows them to shape market offerings and maintain pricing discipline.
Pricing Analysis
Input cost pass-through for specialized fluoronitrile gas mixtures significantly impacts the project-based pricing model for Gas Insulated Substations. Price differentiation stems from advanced SF6-free technology and comprehensive after-sales service agreements, including compliant gas handling. Pricing softness emerges from the high initial capital outlay, particularly for budget-constrained utilities in emerging markets. Hyperscale data centers, prioritizing uninterruptible power and uptime, demonstrate lower price sensitivity compared to these developing economy utilities.
Supply Chain Analysis
Domestic content mandates, such as those spurred by the US Inflation Reduction Act, are reshaping sourcing for Gas Insulated Substation components. Geographic supply concentrates in China for high-voltage components and in a few chemical manufacturers for fluoronitrile gas mixtures. Raw material dependencies include specialized insulating gases and high-grade electrical components. Single-source vulnerability for SF6-alternative chemicals poses a key structural risk. Direct sales and long-term contracts with utilities define the dominant downstream distribution model.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Gas Insulated Substation market functions as a stable compounder, driven by the continuous imperative for global grid modernization. This foundational demand ensures sustained investment in critical electrical infrastructure.
For Market Incumbents: Cement leadership by aggressively investing in SF6-free technology R&D, anticipating evolving IEC standards. Offer comprehensive lifecycle service agreements, including specialized gas handling, to counter threats from focused alternative solution providers. Strengthen channel control with major utilities through long-term partnerships and certification investments in eco-friendly GIS.
For New Entrants and Emerging Players: Capture market share by targeting the rapidly expanding renewable energy end-user segment, especially for offshore wind connections. Focus on modular, compact SF6-free solutions that reduce installation time and land footprint. A go-to-market angle centered on rapid deployment and environmental compliance can penetrate new projects.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized SF6-free component manufacturers offering proven alternative dielectric gases. The market offers long-term viability, driven by global decarbonization mandates and the need for enhanced grid resilience. An acquisition target profile includes firms with proprietary fluoronitrile-based gas mixtures or advanced digital monitoring solutions. The signal to watch is the accelerated adoption rate of SF6-free technologies under new regulatory frameworks.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Grid modernization initiatives in China require substantial high-voltage GIS deployments for new transmission networks. |
| Green Manufacturing Transition | The EU F-Gas Regulation drives the shift to SF6-free production processes. |
| Strategic Partnership | General Electric Company partnered with Hitachi Ltd to develop g³ technology. |
| Digitalization and IoT Integration | Embedding sensors into GIS units enables predictive maintenance for utilities. |
| Long-term Service Agreements | Utilities are shifting procurement towards comprehensive lifecycle support in Europe. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window to inform this analysis. Primary research involved discussions with utility planning officers, EPC contractors, and R&D directors at leading GIS manufacturers. Secondary validation utilized IEC standards documents, US EPA reports, EU F-Gas Regulation texts, and national grid expansion plans. Bottom-up market sizing was triangulated with top-down validation against industry revenue figures.
Segment-weighting across product type, end-user, technology, and installation formed the core of the forecasting framework. Growth rates were derived from historical data, projected infrastructure investments, and anticipated technology adoption curves over the analysis window. Industry-specific inputs included renewable energy project pipelines and regional grid modernization budgets. This approach quantified market evolution across various dimensions.
Regulatory shifts, technological breakthroughs in insulation gases, and geopolitical tensions affecting critical component supply are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding these external factors and market responses. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Ring Main Unit Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
South Africa High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Overhead Line Fault Passage Indicator Market
Transmission and Distribution
Transmission Towers Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market