
 Iron Ore Mining Market | 2026-2036
Iron Ore Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Ore Mining Market Outlook
Multi-source procurement is consolidating as steelmakers reduce reliance on single-origin supply chains. Vale S.A. leverages its Carajás high-grade reserves to command premium contracts with Asian mills. Rio Tinto Group anchors its position through autonomous hauling networks spanning Western Australia's Pilbara. BHP Group Limited competes on volume scale, sustaining integrated rail-port infrastructure that lowers delivered cost to China.
Iron ore mining encompasses the extraction and beneficiation of iron-bearing minerals, primarily hematite and magnetite, with ore grades typically ranging from 58% to 65% iron content by weight; the material feeds blast furnaces and direct-reduction plants that produce crude steel. Hematite deposits dominate seaborne trade due to higher natural iron content and lower processing intensity, while magnetite requires grinding and magnetic separation but offers superior consistency for pelletizing. Steel manufacturing consumes over 90% of mined output, with construction and automotive sectors drawing downstream derivative demand. Autonomous hauling technology is displacing conventional truck fleets, compressing unit operating costs and extending mine life at mature pits.
Environmental regulators in Australia, Brazil, and China impose escalating compliance burdens on tailings management and Scope 3 emissions disclosure. Australia's EPA frameworks mandate progressive rehabilitation bonds, while China's MEE enforces stricter import quality standards that disadvantage lower-grade exporters. Stakeholders must monitor how carbon border adjustments and green steel premiums reshape ore quality premiums and capital allocation across the project pipeline.
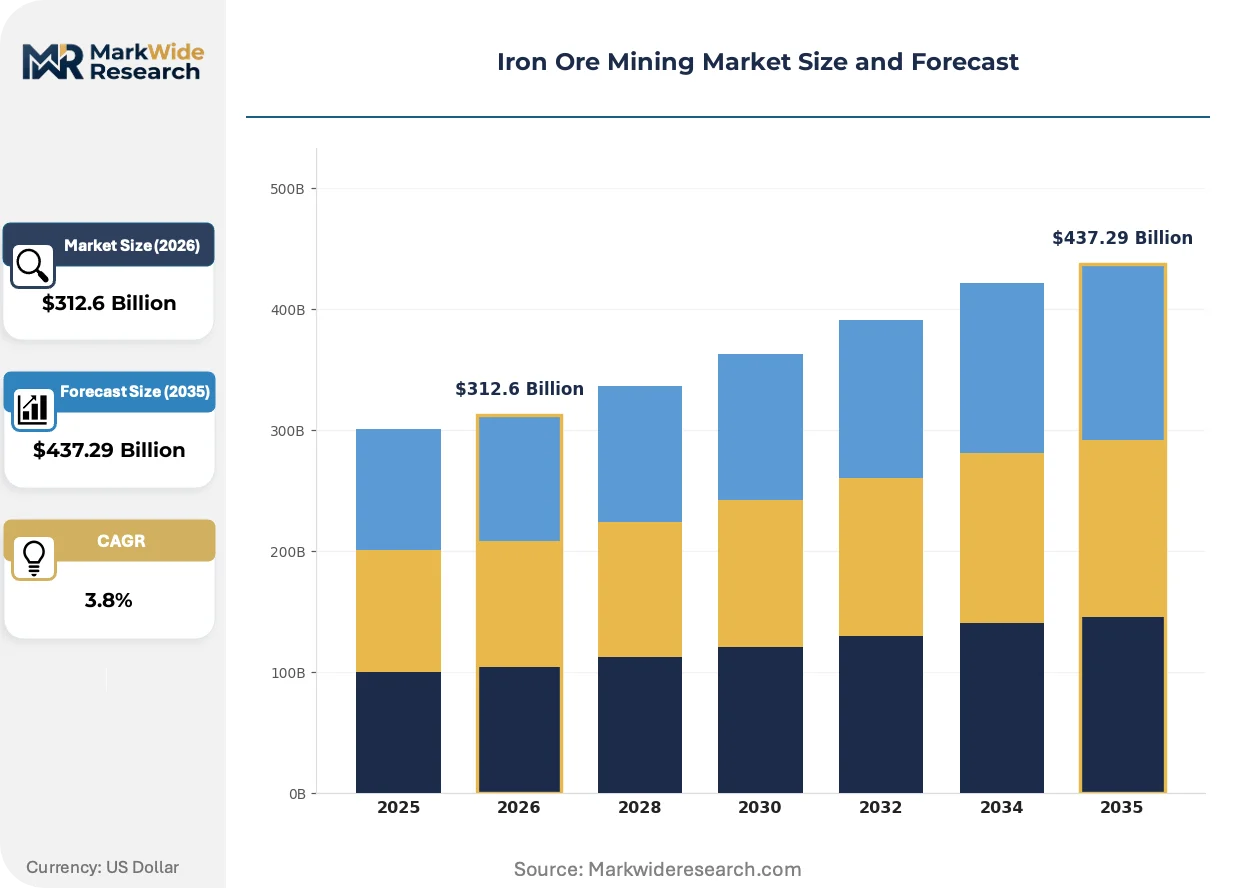
Market Dynamics
Autonomous hauling systems are compressing unit operating costs across the Pilbara and Carajás basins, forcing marginal producers to accelerate technology adoption or exit seaborne trade.
Growth Catalysts
- China's dual carbon goals:Beijing's MEE enforcement of stricter import quality standards is pulling premium-grade hematite into blast furnaces and displacing lower-grade alternatives from procurement portfolios.
- Direct-reduction steelmaking:Hydrogen-based DRI-EAF routes in Europe and the Middle East are creating dedicated demand for high-purity pellet feed that magnetite beneficiation delivers.
- Pilbara infrastructure scale:Australia's integrated rail-port networks are sustaining delivered cost advantages to Asian mills that smaller basins cannot replicate.
Market Restraints
- Diesel price volatility:Open-pit haulage fleets remain 85% diesel-dependent, exposing operators to fuel cost swings that autonomous systems only partially offset.
- Carajás-Pilbara duopoly:Two supply basins control over 60% of seaborne trade, concentrating disruption risk from weather, labor action, or tailings incidents.
- Scrap steel substitution:Electric arc furnace operators in Turkey, the US, and Southeast Asia are expanding scrap intake, eroding iron ore's share of metallic feedstock.
Strategic Opportunities
- West African greenfield development:Simandou and Mbalam-Nabeba deposits offer untapped high-grade reserves for producers seeking supply chain diversification beyond Australian and Brazilian dominance.
- EU Carbon Border Adjustment Mechanism:CBAM phase-in from 2026 creates premium pricing tiers for ore with verified low-Scope 3 emissions, rewarding integrated miners with renewable-powered logistics.
- Digital twin convergence:Real-time pit optimization software fused with predictive maintenance algorithms is opening 15-20% throughput gains at mature operations without greenfield capital.
Industry Challenges
- Autonomous systems integration:Legacy mine control architectures require multi-year retrofit cycles to interface with fleet automation platforms, delaying payback timelines.
- Tailings engineer scarcity:Australia's EPA and Brazil's ANM are tightening dam safety certification requirements faster than universities can produce qualified geotechnical specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Ore Mining Market |
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $437.29 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hematite, Magnetite, Limonite, Siderite End User: Steel Manufacturing, Construction, Automotive, Energy Sector Mining Method: Open-pit, Underground, Placer, In-situ Technology: Blast Mining, Continuous Mining, Hydrometallurgy, Autonomous Hauling |
| Companies Covered | Vale S.A., Rio Tinto Group, BHP Group Limited, Fortescue Metals Group Ltd, Anglo American plc, ArcelorMittal, Cleveland-Cliffs Inc., NMDC Limited, China Baowu Steel Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Ore Mining Market Strategic Shifts
Battery-electric haulage and hydrogen fuel cell trials are colliding with tightening Scope 3 disclosure mandates, rewriting capital allocation priorities across the project pipeline.
Autonomous drilling rigs equipped with real-time ore-grade sensors are electrifying blast pattern optimization in Western Australia's Pilbara. Rio Tinto and BHP are deploying these systems across multiple pits, compressing drilling cycle times by 30% and reducing explosive waste. The technology is electrifying margin recovery at deposits previously considered marginal on head-grade alone.
Europe's CSRD and EU Green Deal disclosure frameworks now mandate granular Scope 3 emissions reporting from imported steel feedstock. This is forcing Asian mills to demand certified low-carbon ore documentation, with Australian producers responding through blockchain-tracked supply chain audits. The regulation is most acute for German and Dutch steelmakers facing 2030 climate targets.
Steelmakers are consolidating procurement through long-term offtake partnerships that bundle ore supply with carbon credit arrangements. Spot market liquidity is thinning as Chinese mills, Japanese trading houses, and Korean steel groups lock in decade-long contracts with tier-one producers. This behavior is most visible in China's coastal provinces where provincial governments are enforcing dual carbon compliance through state-owned enterprise procurement directives.
Iron Ore Mining Market Segmentation
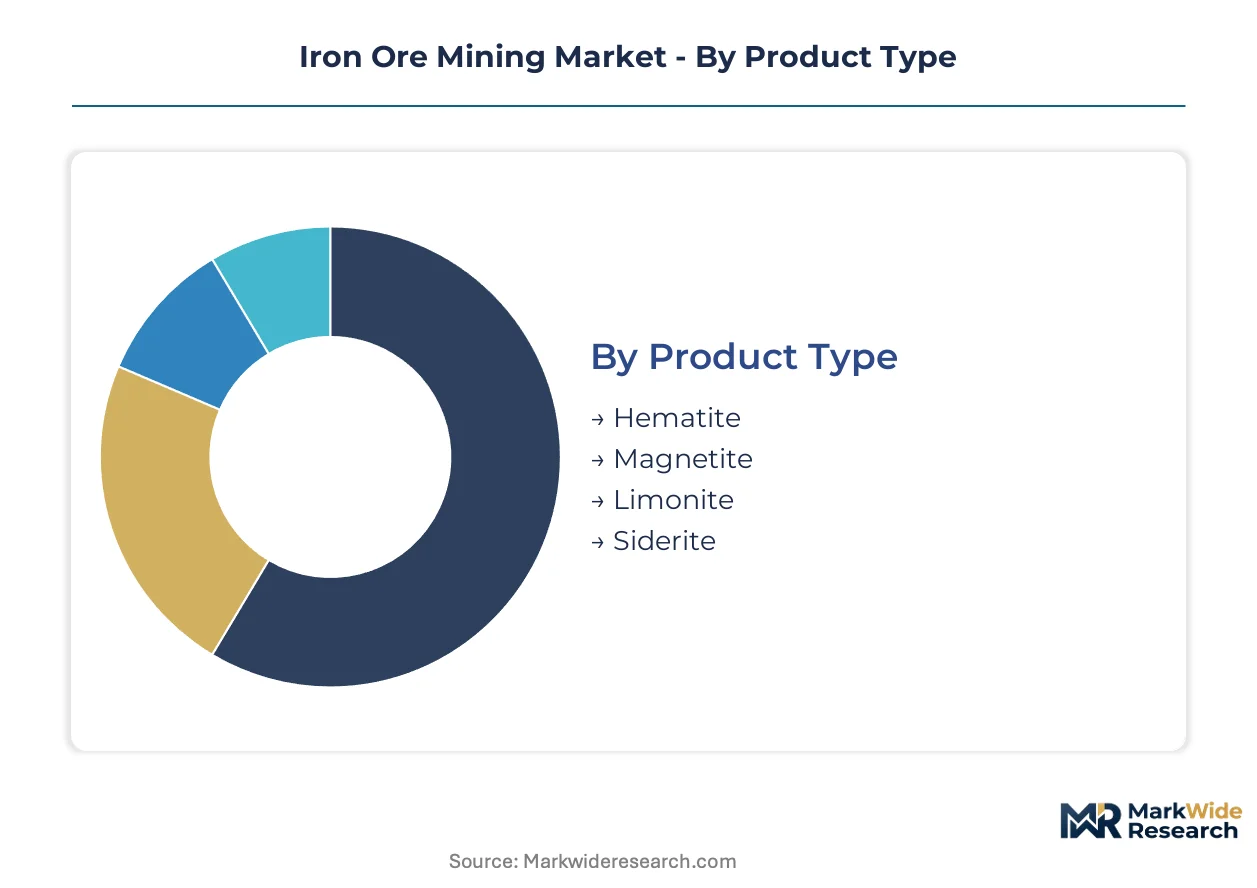
Iron ore mining segmentation reveals how ore chemistry, extraction economics, and steelmaking technology intersect to determine value capture. Understanding these dimensions exposes where premium pricing concentrates and which operational models face compression.
Product Type:
Supply concentration in high-grade deposits has elevated hematite and magnetite above lower-grade alternatives in procurement hierarchies.
- Hematite:Iron content typically ranges from 58% to 67% by weight with minimal processing requirements before blast furnace charging. Australia's Pilbara operators and Brazil's Carajás basin command premium seaborne pricing for lump and fines grades, with China's MEE import standards reinforcing quality premiums.
- Magnetite:Requires grinding and magnetic separation to achieve commercial grades of 65% to 70% iron, yet delivers superior pelletizing consistency for direct-reduction steelmaking. European hydrogen-based DRI-EAF projects are pulling dedicated offtake agreements from magnetite-rich deposits in Canada and Sweden.
- Limonite:Lower-grade hydrated iron oxide with nickel and cobalt co-product potential in lateritic formations; Indonesia and Philippines operations supply stainless steel feedstock.
- Siderite:Iron carbonate ore requiring calcination before smelting; limited commercial extraction in Austria and China serves specialty ferroalloy applications.
Hematite absorbs the bulk of installed capacity; magnetite is expanding most quickly.
End User:
Cost tier differentiation separates commodity steel producers from specialized alloy manufacturers in ore procurement specifications.
- Steel Manufacturing:Blast furnace operators in China, Japan, and Korea consume over 90% of mined output, with tier-one mills paying premiums for low-alumina, low-phosphorus lump ore to optimize coke rates and slag volumes.
- Construction:Rebar and structural steel demand from Southeast Asian infrastructure projects pulls medium-grade fines into electric arc furnace feedstock blends.
- Automotive:Advanced high-strength steel specifications require ultra-low residual element content, directing procurement toward certified low-impurity ore from Western Australian operations.
- Energy Sector:Pipeline steel and offshore platform grades demand sour-gas-resistant metallurgy, with specialized plate mills sourcing specific chemical compositions from select deposits.
Steel Manufacturing commands the dominant volume share; Automotive is climbing the fastest on quality-premium expansion.
Mining Method:
Volume economics favor surface extraction, though ore body geometry and overburden ratios determine method selection at specific deposits.
- Open-pit:Surface excavation dominates seaborne supply, with Pilbara and Carajás operations achieving sub-$15 per ton cash costs through scale and automation.
- Underground:Kiruna-type sublevel caving in Sweden and Michigan's Menominee range accesses deep hematite bodies where surface exhaustion has occurred.
- Placer:Alluvial concentration processes recover heavy mineral sands with iron-titanium co-products; limited scale in India and Southeast Asia.
- In-situ:Solution mining and bioleaching trials target low-grade magnetite formations in Western Australia and Finland where conventional excavation is uneconomic.
Open-pit operations absorb the bulk of installed capacity; In-situ methods are gaining share fastest on marginal ore body viability.
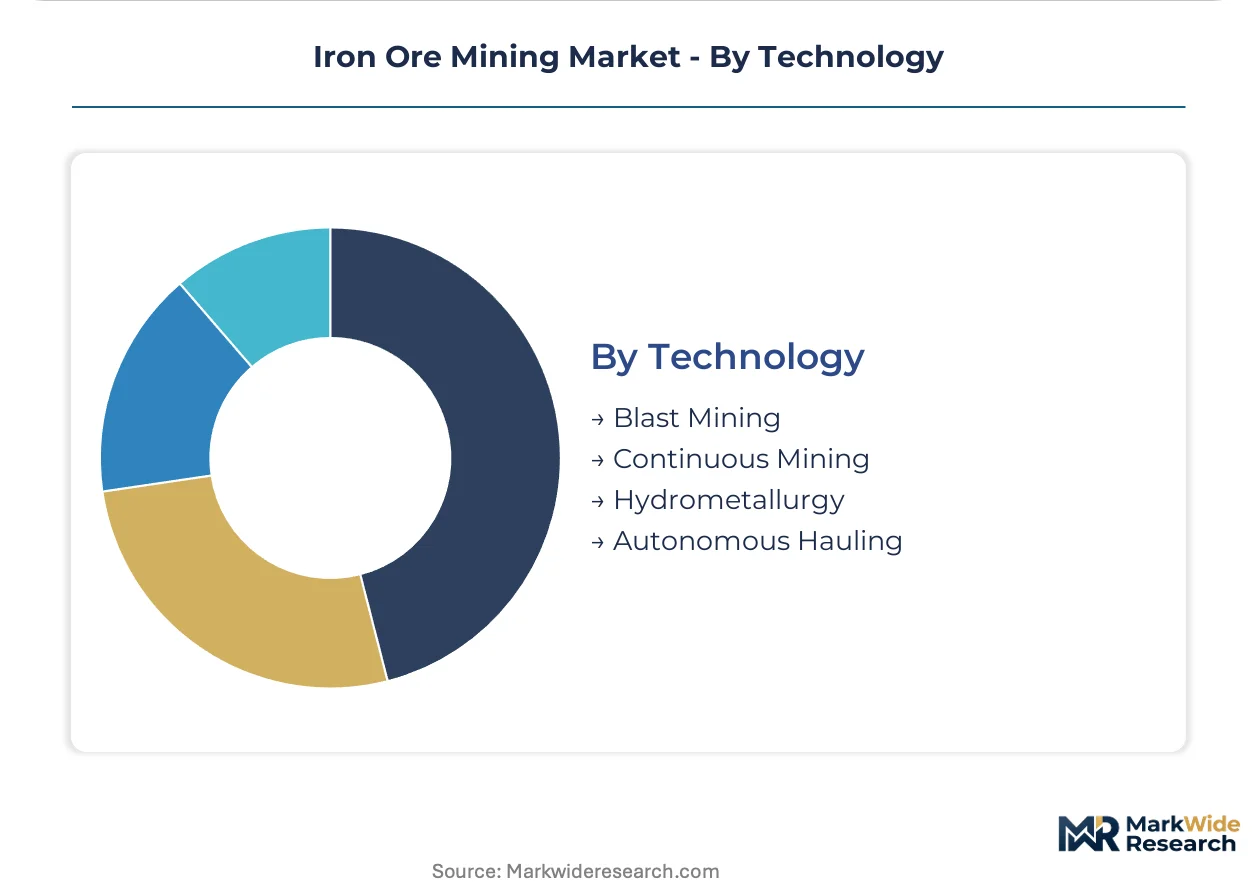
Technology:
Margin compression from autonomous systems is forcing technology adoption across all extraction scales to defend cost positions.
- Blast Mining:Drill-and-blast fragmentation remains standard for hard rock hematite, with real-time ore-grade sensors reducing explosive waste and improving mill feed consistency.
- Continuous Mining:Bucket-wheel and surface miner applications in soft overburden and transitional ore zones reduce diesel exposure and labor intensity.
- Hydrometallurgy:Pressure leaching and solvent extraction processes recover nickel-cobalt-iron co-products from lateritic limonite; Indonesia's HPAL projects exemplify this pathway.
- Autonomous Hauling:Rio Tinto and BHP deployments across Pilbara pits have compressed unit operating costs and extended mine life, with Vale scaling similar systems at Carajás.
Blast Mining retains the dominant installed base; Autonomous Hauling is expanding most quickly on payback validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's steel sector consumes more than half of global seaborne iron ore, while Australia's Pilbara and Brazil's Carajás basins supply the dominant export volumes. Procurement patterns now pivot on carbon intensity metrics and ore grade specifications rather than delivered cost alone.
Australia
Pilbara operators supply low-alumina, low-phosphorus lump and fines to Japanese and Korean blast furnaces. The country's EPA mandates progressive rehabilitation bonds for tailings facilities. Western Australia's integrated rail-port infrastructure sustains sub-$15 per ton cash costs at mature open-pit operations.
Brazil
Carajás high-grade hematite reserves command premium pricing from Asian mills seeking MEE-compliant import grades. ANM tailings dam safety regulations are tightening certification requirements faster than qualified geotechnical specialists enter the workforce. Northern Pará state's Serra Norte complex anchors Vale's autonomous hauling deployments.
China
Provincial governments enforce dual carbon compliance through state-owned enterprise procurement directives favoring premium-grade imports. The MEE's stricter quality standards are displacing lower-grade ore from coastal mill portfolios. Hebei province's Tangshan steel cluster faces binding emissions caps that reshape feedstock sourcing.
India
Domestic blast furnace expansion drives demand for high-grade lump ore from Odisha and Chhattisgarh deposits. NMDC Limited operates under Ministry of Steel directives prioritizing captive mine development for public sector mills. Karnataka's Bellary-Hospet belt hosts the country's densest concentration of merchant mining licenses.
Sweden
Kiruna-type sublevel caving accesses deep magnetite bodies for European hydrogen-based DRI-EAF projects. The EU Green Deal and CSRD frameworks mandate granular Scope 3 emissions reporting from imported steel feedstock. LKAB's operations in Norrbotten county are pivoting toward fossil-free pellet production for German and Dutch steelmakers.
Iron Ore Mining Market Competitive Environment
Autonomous hauling deployment dominates the current landscape as tier-one producers compress unit costs and extend mine life. The market structure concentrates around a Pilbara-Carajás duopoly controlling over sixty percent of seaborne trade, with mid-tier operators defending margin positions through niche grade specialization. Two strategic archetypes prevail: scale-driven integrated miners with captive infrastructure, and grade-specialized developers targeting direct-reduction feedstock premiums. Competitive moves center on technology licensing partnerships and backward integration into renewable-powered logistics chains.
Among Brazilian and Australian integrated miners, Vale S.A., Rio Tinto Group, and BHP Group Limited exemplify the scale-driven archetype through their command of tier-one basin infrastructure and autonomous fleet deployments. These entities occupy positions where ore quality premiums and carbon certification capabilities increasingly determine contract terms with Asian mills.
| Leading Market Players |
|---|
| Vale S.A. |
| Rio Tinto Group |
| BHP Group Limited |
| Fortescue Metals Group Ltd |
| Anglo American plc |
| ArcelorMittal |
| Cleveland-Cliffs Inc. |
| NMDC Limited |
| China Baowu Steel Group |
| Others |
Value Chain & Pricing Dynamics
Captive rail-port infrastructure in Western Australia and Northern Brazil anchors both supply positioning and pricing power for tier-one producers, while marginal operators without integrated logistics face structural cost disadvantages in contract negotiations with Asian mills.
Pricing Analysis
Long-term offtake contracts bundle ore supply with carbon credit documentation and quality certification, unbundling spot market exposure from premium-tier procurement. Pricing stratifies across premium low-impurity lump, standard fines grades, and economy-tier high-alumina alternatives, with China's MEE import standards reinforcing quality premiums. Cost compression in lower-grade segments is intensifying because autonomous hauling investments at Pilbara and Carajás operations compress delivered costs to coastal Chinese mills. State-owned steel groups in Hebei and Jiangsu provinces exhibit highest price sensitivity due to binding emissions caps, while Japanese trading houses show lowest sensitivity through decade-long volume commitments.
Supply Chain Analysis
Empty bulk carrier backhauls and ore stockpile rotation create reverse-logistics optimization opportunities at Chinese port terminals, with Australian miners experimenting with blockchain-tracked cargo documentation for circular supply chain verification. Supply concentrates in Australia, Brazil, and emerging West African deposits at Simandou and Mbalam-Nabeba. Operations draw from diesel fuel, ammonium nitrate explosives, and steel grinding media as critical inputs. Single-source vulnerability runs through the Pilbara-Carajás duopoly controlling over sixty percent of seaborne trade. Distribution runs through long-term offtake partnerships with integrated rail-port-ship networks rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
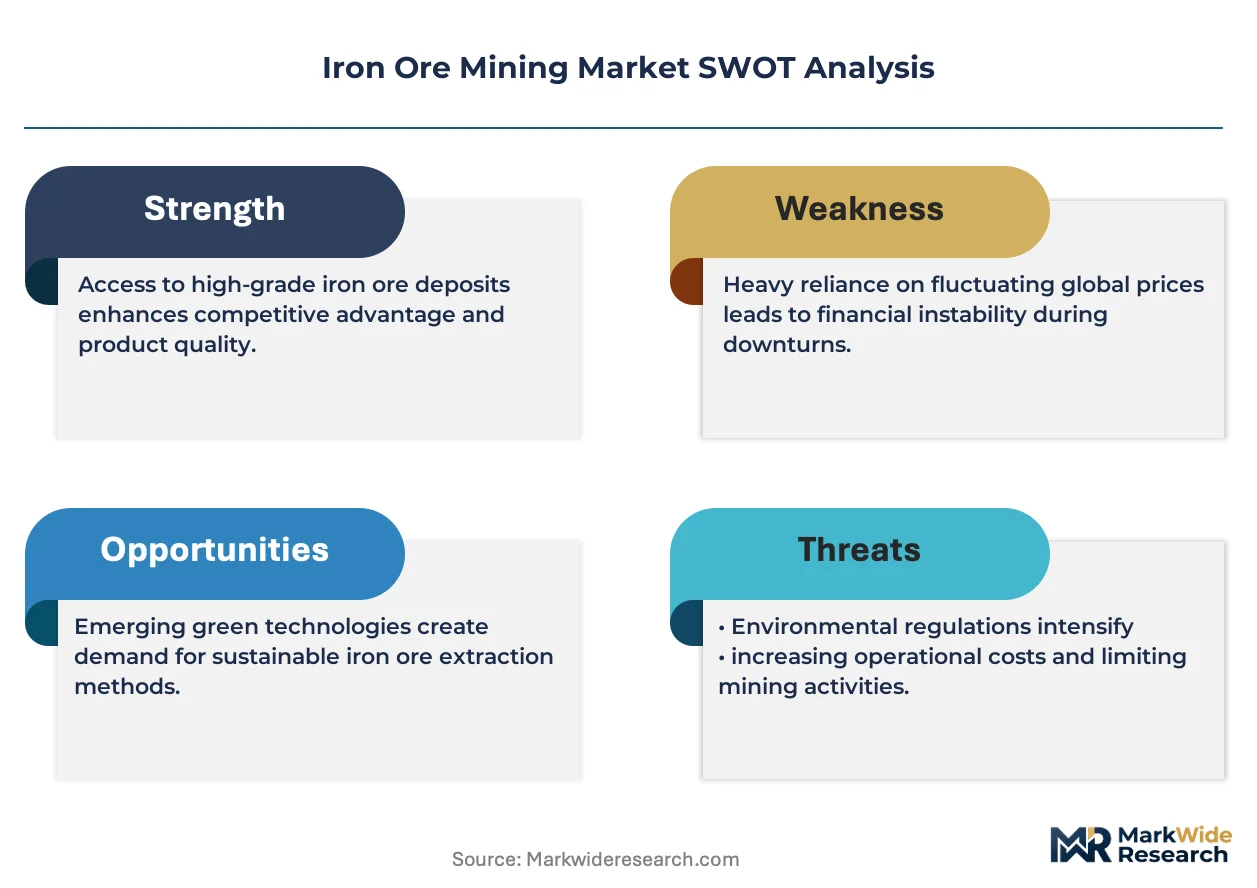
Autonomous hauling capital requirements and carbon certification burdens are consolidating market share toward integrated miners with captive infrastructure, forcing sub-scale operators toward niche grade specialization or exit.
For Market Incumbents: Anticipate scrap steel substitution acceleration in Turkey and Southeast Asia by deepening pellet feed integration for hydrogen-based DRI-EAF routes in Europe. Lock in renewable-powered logistics certifications ahead of EU Carbon Border Adjustment Mechanism phase-in to defend premium contract positioning against emerging West African supply. For New Entrants and Emerging Players: EU Green Deal and CSRD disclosure frameworks in Europe open a window for magnetite pellet feed developers with verified low-Scope 3 emissions documentation. Target German and Dutch steelmaker procurement committees with fossil-free pellet supply partnerships, leveraging blockchain-tracked supply chain audits as the primary go-to-market credential. For Investors and Strategic Acquirers: Exit pathways concentrate in autonomous technology licensing and carbon credit bundling arrangements rather than pure volume scale. Five-to-ten year viability hinges on integrated rail-port infrastructure ownership or exclusive high-grade reserve access. Monitor CBAM implementation pace and Chinese provincial emissions enforcement intensity as inflection indicators for premium-grade ore demand shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Hauling Deployment | Rio Tinto and BHP deployments across Pilbara pits compress unit operating costs and extend mine life at mature operations. |
| Renewable-Powered Logistics Certification | Australian producers respond to CSRD mandates with blockchain-tracked supply chain audits for German and Dutch steelmakers. |
| West African Greenfield Development | Simandou and Mbalam-Nabeba deposits offer supply chain diversification beyond Australian and Brazilian dominance. |
| Hydrogen-Based DRI-EAF Feedstock Partnerships | European steel projects pull dedicated offtake agreements from magnetite-rich deposits in Canada and Sweden. |
| Digital Twin Convergence | Real-time pit optimization software fused with predictive maintenance algorithms opens throughput gains without greenfield capital. |
Study Parameters
Document review covered customs and trade data, mining ministry production statistics, and environmental regulatory filings, complemented by interviews with mine operations directors, procurement leads at Asian steel mills, tailings engineering specialists, and autonomous systems integration managers. Secondary validation drew from ANM dam safety reports, Australia's EPA rehabilitation bond disclosures, and China's MEE import quality standards. Bottom-up reserve and production estimates were triangulated against top-down seaborne trade flow analysis.
Historical cost curve positioning was cross-referenced against expert panel input on autonomous technology adoption timelines and carbon border adjustment implementation scenarios. Segmentation modeling spanned ore chemistry, extraction method, steelmaking technology route, and regional regulatory cluster dimensions across the projection horizon. CAGRs were derived from demand elasticity modeling against crude steel output forecasts and scrap substitution penetration curves, with hydrogen-based DRI-EAF capacity buildout schedules as a critical demand-side input.
Caveats apply where Chinese provincial emissions enforcement intensity, Brazilian tailings dam certification delays, or West African infrastructure financing gaps could materially shift the outlook. Practitioners should monitor CBAM regulatory finalization, autonomous hauling retrofit completion rates, and scrap steel price spreads for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
United States Oil and Gas Pipeline Maintenance, Repair, Overhaul (MRO) Market
Oil & Gas
Saudi Arabia Drilling Services Market
Oil & Gas
US Sand Control Systems Market
Oil & Gas
Rig and Oilfield Mats Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Vacuum Gas Oil Market
Oil & Gas
Aqueous Flare Meter Market
Oil & Gas
Wired Drill Pipe Sales Market
Oil & Gas
Underground Gas Storage (UGS) Market
Oil & Gas
Oilfield Rotary Table Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
India Artificial Lift Systems Market
Oil & Gas
North America Perforating Gun Market
Oil & Gas
Methane Hydrate Extraction Market
Oil & Gas
United Arab Emirates Oil and Gas Downstream Market
Oil & Gas
Australia Oil and Gas Midstream Market