
 Fuse Rails Market | 2026-2036
Fuse Rails Market Size, Share, and Industry Trends Forecast 2026-2036
Fuse Rails Market Analysis
The premium-commodity split in fuse rails is shifting as rail operators demand IEC-certified copper assemblies while cost-sensitive industrial buyers accept aluminum alternatives. Siemens Mobility leverages its rail electrification portfolio to dominate premium fuse rail contracts in European mass transit. CRRC Corporation anchors supply for China's domestic high-speed rail expansion through captive manufacturing scale. Rittal competes in industrial enclosure-integrated fuse rail systems for manufacturing plant electrification.
Fuse rails are conductive mounting structures that house cylindrical or blade-type fuses, typically fabricated from electrolytic copper or aluminum extrusions with rated current capacities from 16A to 1250A, serving to distribute protected electrical circuits across switchgear and traction power systems. Modular fuse rails sustain above-average growth as data centers and renewable energy installations favor field-expandable bus configurations over fixed standard units. Rack-mounted installations lead in telecommunications and server infrastructure where space optimization drives specification, while wall-mounted configurations remain mature in conventional industrial motor control panels.
The International Electrotechnical Commission's IEC 60269 series governs fuse and fuse rail interchangeability across EU member states, compelling manufacturers to maintain dual certification for market access. China's GB standards and India's BIS certification create parallel compliance tracks that fragment supplier qualification requirements. Stakeholders must monitor material substitution trends as copper-aluminum composite designs challenge traditional pure copper specifications without sacrificing thermal performance.
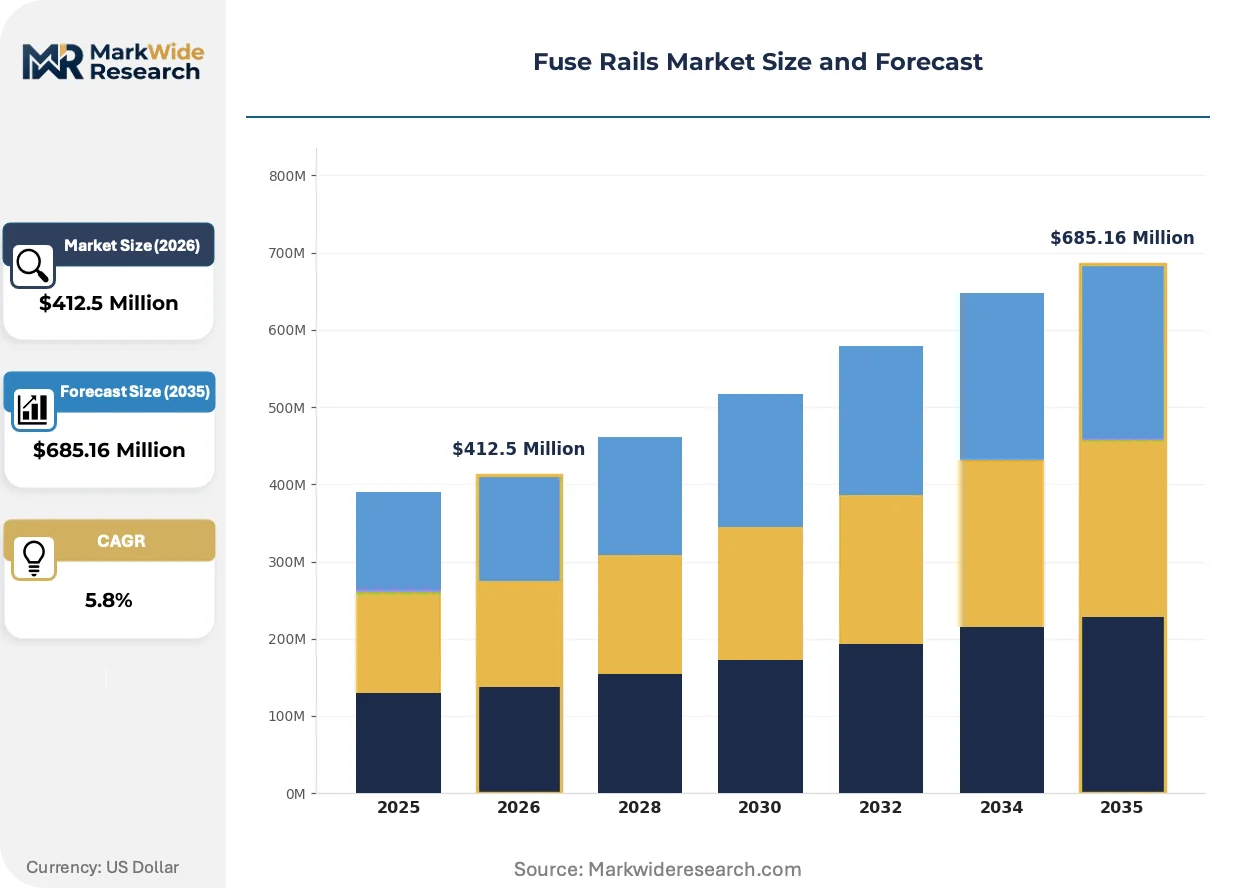
Market Dynamics
Copper price volatility is forcing rail electrification contractors to requalify fuse rail specifications, compressing procurement cycles and fragmenting supplier tiers between certified premium producers and aluminum-alternative vendors.
Growth Catalysts
- Railway Electrification Mandates:India's Dedicated Freight Corridor and metro expansion projects under the Ministry of Railways are accelerating fuse rail procurement for 25kV traction systems. IEC 60269 compliance requirements ensure sustained replacement demand across EU member states as legacy infrastructure ages.
- Copper-Aluminum Composite Designs:Hybrid conductor materials are expanding addressable market share in cost-sensitive industrial segments without sacrificing thermal performance benchmarks. These assemblies reduce raw material exposure while maintaining ampacity ratings.
- Data Center Bus Expansion:Field-configurable modular fuse rails are displacing fixed units in hyperscale facilities, driven by unpredictable power distribution growth patterns. Rack-mounted configurations dominate server infrastructure where space optimization dictates specification.
Market Restraints
- Copper Price Volatility:LME copper futures swings above 15% annually are compressing margins for electrolytic copper fabricators and forcing hedging costs onto smaller suppliers.
- Supply Concentration Risk:High-purity electrolytic copper for fuse rails concentrates among Chilean and Peruvian mining operations, exposing procurement to export quota disruptions and logistics bottlenecks.
- Dual Certification Burden:IEC 60269 and China's GB standards create parallel compliance tracks that fragment supplier qualification requirements and extend product development timelines.
Strategic Opportunities
- Renewable Energy Integration:Solar and wind farm switchgear installations favor expandable bus configurations, creating white space for modular fuse rail vendors outside traditional rail electrification.
- India's PLI Scheme:Production-linked incentives for domestic electrical equipment manufacturing are attracting component localization investments that reduce import dependency for fuse rail assemblies.
- Smart Grid Convergence:Integration of fuse rails with digital monitoring systems enables predictive maintenance contracts, shifting revenue models from product sales to service-based arrangements.
Industry Challenges
- Certification Timeline Compression:BIS and IEC parallel testing requirements for Indian export markets extend qualification cycles, delaying contract awards and straining working capital.
- Legacy Panel Integration:Retrofit installations in existing industrial motor control systems face mechanical incompatibility with modern fuse rail dimensions, requiring custom adapter fabrication.
- Specialized Welding Expertise:Copper-aluminum bimetallic joint fabrication demands skilled technicians in short supply, constraining production scaling for composite designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fuse Rails Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Fuse Rails, Modular Fuse Rails, Safety Fuse Rails, High Voltage Fuse Rails Industry Vertical: Energy, Automotive, Manufacturing, Telecommunications Installation: Wall-Mounted, Rack-Mounted, Panel-Mounted, Surface-Mounted Material: Plastic, Aluminum, Copper, Composite |
| Companies Covered | Siemens Mobility, Alstom, Hitachi Rail, Stadler Rail, CAF, CRRC Corporation, Kawasaki Heavy Industries, Thales Group, Rittal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fuse Rails Market Emerging Trajectories
Material science advances and regulatory harmonization pressures are reshaping fuse rail specification standards, while procurement digitization accelerates vendor switching and compresses contract cycles.
Copper-aluminum composite extrusions are converging with traditional pure copper specifications in traction power applications, offering comparable thermal conductivity at reduced material cost. Siemens Mobility and CRRC Corporation procurement teams are piloting these hybrids for non-critical distribution circuits. The technology is converging with established supply chains by leveraging existing aluminum extrusion infrastructure without requiring greenfield copper smelting investments.
REACH substance restrictions and the EU Green Deal's embodied carbon requirements are compelling fuse rail manufacturers to document supply chain provenance and eliminate cadmium-plated contacts. Industrial buyers in Germany and France now mandate Environmental Product Declarations for switchgear assemblies. High-speed rail projects in Spain and Italy are responding by specifying recycled-content copper certifications.
Digital procurement platforms are consolidating vendor evaluation for rail electrification contractors, compressing qualification from 18-month cycles to 90-day automated assessments. Tier-1 EPC firms in China and India are displacing distributor networks with direct manufacturer portals. This shift is most visible in CRRC Corporation's centralized sourcing for domestic high-speed rail expansion, where fuse rail specifications are standardized across provincial procurement offices.
Fuse Rails Market Segmentation
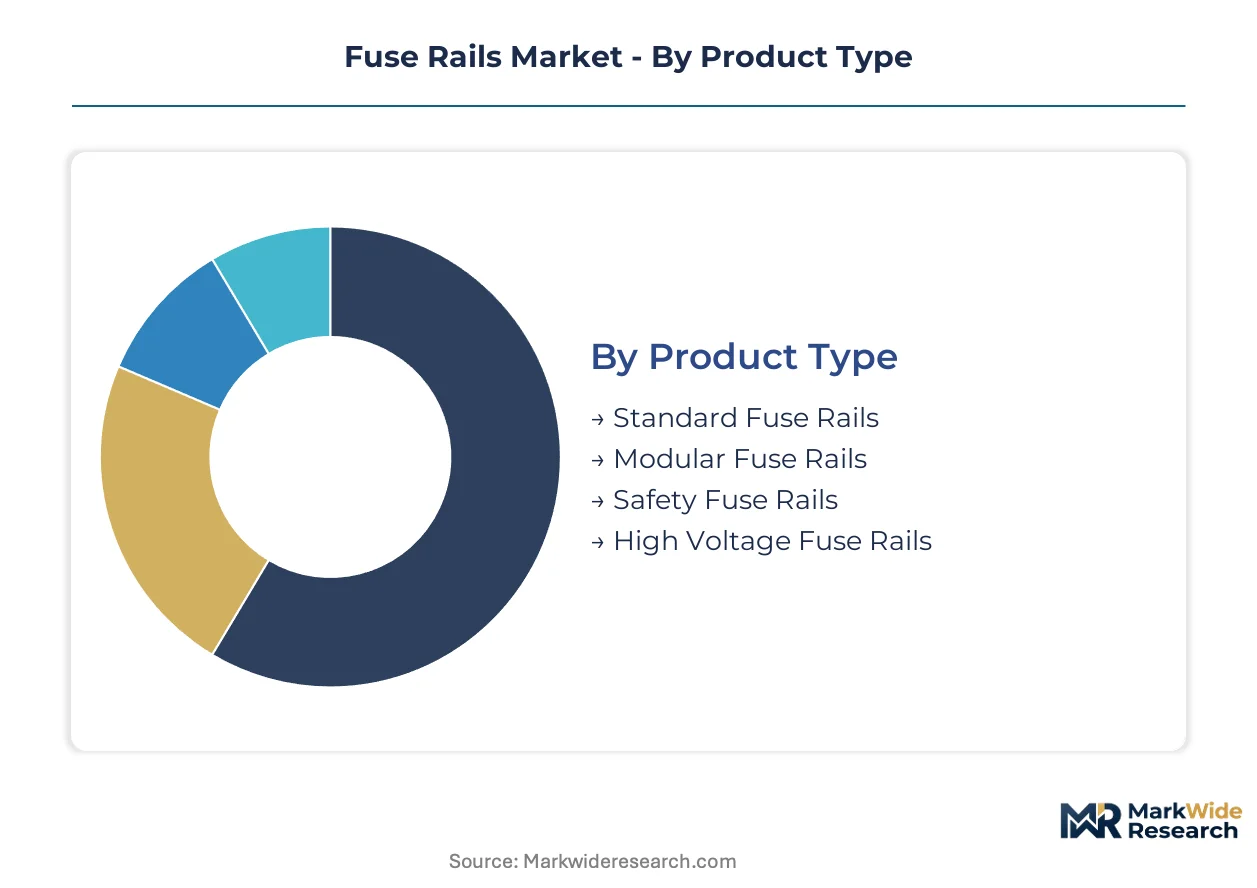
Fuse rail procurement patterns diverge sharply across application contexts, with rail electrification contractors demanding certified high-voltage assemblies while industrial buyers prioritize cost-optimized configurations. Specification standards from IEC and national regulators fragment addressable markets by compliance tier rather than geography alone.
Product Type:
Technical specification hierarchy separates commodity fuse protection from mission-critical traction power distribution, with voltage rating and modularity defining procurement qualification tiers.
- High Voltage Fuse Rails:Engineered for 25kV traction systems and medium-voltage switchgear, these assemblies use electrolytic copper busbars with reinforced porcelain or polymer housings. Railway electrification projects in Germany and China concentrate demand here, with IEC 60269 certification mandatory for EU contractor qualification.
- Modular Fuse Rails:Field-expandable bus configurations accommodate unpredictable load growth in data centers and renewable energy installations. Rack-mounted variants dominate hyperscale facility deployments where space optimization and hot-swap capability override initial cost considerations.
- Standard Fuse Rails:Fixed-dimension copper or aluminum extrusions serve conventional industrial motor control panels with predictable circuit protection requirements.
- Safety Fuse Rails:Integrated arc-flash containment and touch-safe housings address manufacturing plant electrification where OSHA and EU machinery directives mandate operator protection.
Mature deployment sits with Standard Fuse Rails in legacy industrial infrastructure. Newer deployment is concentrated in Modular configurations serving data center bus expansion.
Industry Vertical:
End-use concentration patterns reveal divergent material specifications, with rail and energy sectors absorbing premium copper assemblies while automotive and telecom buyers accept aluminum alternatives.
- Energy:Solar and wind farm switchgear installations favor expandable bus configurations, creating sustained procurement for modular fuse rails with outdoor-rated enclosures. Grid-scale battery storage projects in India and China are accelerating specification of high-current copper assemblies.
- Automotive:Electric vehicle manufacturing plants and charging infrastructure networks drive demand for compact, high-density fuse rail systems. Cost pressures here favor aluminum conductor variants where thermal cycling requirements permit material substitution.
- Manufacturing:Industrial motor control panels and machine tool electrification sustain steady replacement demand for wall-mounted standard fuse rails across mature factory footprints.
- Telecommunications:Server rack power distribution units specify slim-profile rack-mounted fuse rails optimized for horizontal space constraints in colocation facilities.
Procurement volume clusters in Energy verticals. Margin expansion is climbing the fastest in Automotive electrification infrastructure.
Installation:
Mounting configuration selection reflects facility vintage and spatial economics, with rack optimization displacing conventional panel mounting in new construction.
- Rack-Mounted:Horizontal and vertical rail configurations maximize power density in server infrastructure and telecommunications switching centers. These installations prioritize tool-free fuse replacement and integrated cable management over raw material cost.
- Wall-Mounted:Traditional surface attachment dominates existing industrial motor control installations where retrofit compatibility constrains specification flexibility. India's manufacturing corridor expansion sustains replacement demand here.
- Panel-Mounted:Flush integration into switchgear enclosures serves OEM electrical equipment manufacturers with standardized cutout dimensions.
- Surface-Mounted:Exposed conduit applications in commercial building electrical rooms favor these configurations for maintenance accessibility.
Specification inertia protects Wall-Mounted share in brownfield industrial sites. Rack-Mounted configurations are expanding most quickly in greenfield data center construction.
Material:
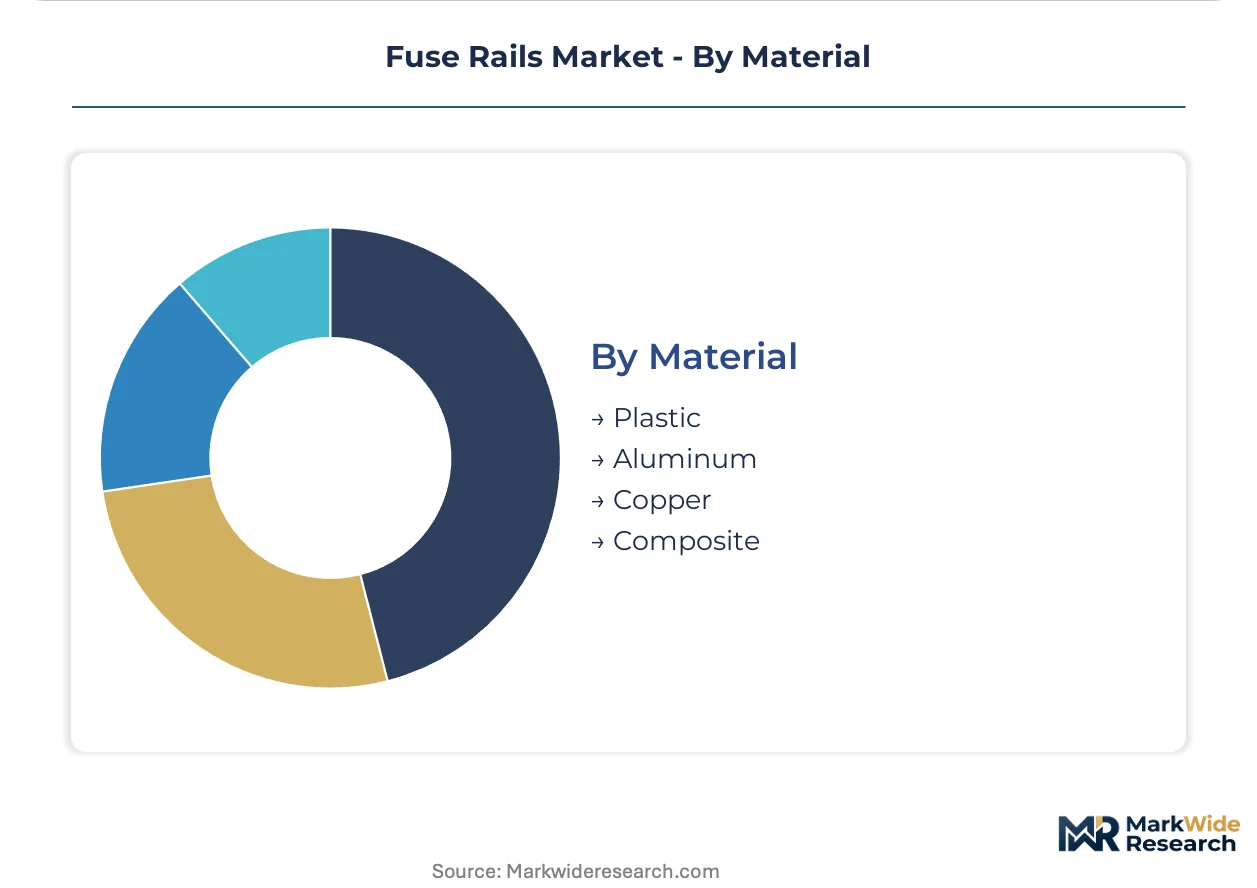
Conductor material selection hinges on thermal performance requirements against raw material cost exposure, with composite designs emerging as a viable middle tier.
- Copper:Electrolytic grade busbars deliver superior conductivity and oxidation resistance for high-current traction power and critical switchgear applications. LME price volatility above 15% annually is forcing contractors to requalify specifications and compress procurement cycles.
- Composite:Copper-aluminum bimetallic extrusions and plated hybrid designs challenge pure copper specifications in cost-sensitive industrial segments without sacrificing ampacity ratings. Siemens Mobility and CRRC Corporation procurement teams are piloting these for non-critical distribution circuits.
- Aluminum:Lightweight extrusions with tin-plated contact surfaces serve lower-current industrial applications where weight reduction and cost containment outweigh conductivity optimization.
- Plastic:Structural housings and insulating supports complement metallic conductors, with glass-reinforced polymers replacing legacy Bakelite in high-temperature rail applications.
Volume concentration remains with Copper in certified rail electrification contracts. Composite designs are gaining share fastest as hedging costs propagate through supply chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor anchors European fuse rail procurement as Germany's rail electrification program accelerates component sourcing for 25kV traction systems. Manufacturers cluster around Dortmund and Essen to serve Deutsche Bahn's infrastructure renewal timeline.
Germany
Deutsche Bahn's 2030 electrification targets drive sustained demand for IEC 60269-certified high-voltage fuse rails across regional and high-speed networks. The EU Green Deal's embodied carbon requirements mandate Environmental Product Declarations for switchgear assemblies. Siemens Mobility leverages its captive manufacturing in Bavaria to secure premium contracts for Munich and Stuttgart metro expansions.
China
CRRC Corporation's centralized procurement for high-speed rail expansion concentrates fuse rail demand in the Yangtze River Delta manufacturing belt. GB standards compliance creates parallel certification tracks alongside IEC requirements for export-oriented suppliers. Zhengzhou and Changsha rail equipment clusters absorb domestic production capacity for 350km/h line electrification projects.
India
The Dedicated Freight Corridor and metro expansion under the Ministry of Railways accelerate 25kV traction fuse rail procurement for Western and Eastern corridor segments. BIS certification requirements fragment supplier qualification timelines for domestic and export markets. The Delhi-Mumbai Industrial Corridor attracts component localization investments under PLI scheme incentives.
United States
Amtrak's Northeast Corridor electrification and commuter rail upgrades sustain demand for high-current copper assemblies in Philadelphia and Boston maintenance facilities. FERC grid interconnection standards influence switchgear specification for renewable energy integration. Texas and California data center construction drives rack-mounted modular fuse rail procurement for hyperscale power distribution.
Japan
Shinkansen network refurbishment and urban metro automation sustain precision fuse rail demand through Kawasaki and Nagoya industrial clusters. METI's energy efficiency directives accelerate specification of low-loss conductor materials in traction power systems. Osaka-based rail equipment suppliers maintain JIS certification for domestic procurement preference.
Fuse Rails Market Vendor Landscape
Capital-heavy producers compete with asset-light designers as integrated rail OEMs maintain captive fuse rail fabrication while electrical component specialists serve industrial retrofit markets. The market structure tiers between certified premium suppliers for traction power and commodity aluminum vendors for cost-sensitive applications. Three archetypes dominate: rail-integrated electrification divisions, independent switchgear component fabricators, and enclosure-integrated system vendors. Consolidation pressure manifests through strategic partnerships for composite material qualification and geographic licensing for IEC-GB dual certification.
Among rail-integrated producers, Siemens Mobility and CRRC Corporation exemplify the captive supply archetype, leveraging in-house fabrication to control specification and delivery timelines for electrification projects. Rittal occupies a position within the enclosure-integrated tier, bundling fuse rail assemblies with climate-controlled housing systems for manufacturing plant applications. These three anchors demonstrate how vertical scope and certification breadth determine contract access across premium and standard market tiers.
| Leading Market Players |
|---|
| Siemens Mobility |
| Alstom |
| Hitachi Rail |
| Stadler Rail |
| CAF |
| CRRC Corporation |
| Kawasaki Heavy Industries |
| Thales Group |
| Rittal |
| Others |
Supply Flow & Price Mechanics
Rail electrification contractors at Deutsche Bahn and CRRC Corporation command project-based procurement structures that tether fuse rail pricing to IEC 60269 certification tiers rather than raw copper spot markets. This buyer concentration forces suppliers to absorb LME volatility through fixed-price electrification contracts while competing for aluminum-alternative specifications in cost-sensitive industrial segments.
Pricing Analysis
Value-based pricing anchors on traction power system uptime guarantees, with Siemens Mobility and Alstom bundling fuse rail assemblies into 25-year electrification performance contracts. Three-tier pricing structure across premium, standard, and economy levels separates IEC-certified copper traction assemblies from BIS-grade industrial units and uncertified aluminum alternatives. Pricing pressure stems from copper futures swings above fifteen percent annually, compressing margins for electrolytic fabricators. Tier-1 rail operators exhibit lowest price sensitivity due to compliance mandates, while manufacturing plant buyers in India's industrial corridors drive aggressive aluminum substitution.
Supply Chain Analysis
Single-source vulnerability sits with Chilean and Peruvian high-purity electrolytic copper mining operations that feed German and Chinese rail equipment clusters. Raw material flows draw from Zambian cathode suppliers, Yangtze River Delta extrusion facilities, and Bavarian precision machining centers. Commodity price volatility represents the dominant structural risk, with LME hedging costs propagating through procurement cycles. Distribution runs through CRRC Corporation's centralized sourcing portals and Siemens Mobility's captive fabrication networks, displacing traditional distributor tiers in premium segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fuse rails market operates as a vertical-integration race where captive copper smelting and composite extrusion capabilities determine contract access across electrification megaprojects.
For Market Incumbents: Anticipate aluminum-alternative vendors penetrating India's PLI-subsidized manufacturing corridor by accelerating copper-aluminum composite R&D partnerships with Yangtze River Delta metallurgy institutes. Secure backward integration into electrolytic copper refining through offtake agreements with Chilean mining consortiums, insulating procurement from LME volatility that threatens fixed-price rail contracts. Certification investment in dual IEC-GB testing facilities defends position against emerging Chinese suppliers targeting export markets. For New Entrants and Emerging Players: Launch via direct manufacturer portals targeting India's Dedicated Freight Corridor component localization mandates, bypassing established distributor networks that Siemens Mobility dominates. White-space concentration sits with modular fuse rail configurations for hyperscale data center bus expansion in Texas and California, where rack-mounted specifications remain underpenetrated by rail-focused incumbents. Pursue renewable energy switchgear integration as the most penetrable application, leveraging field-expandable designs that incumbent rail suppliers underinvest in. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap composite extrusion specialists with captive aluminum infrastructure in China's Henan province, positioned to capture cost-sensitive industrial share without greenfield smelting investments. Long-term viability hinges on dual-certification capabilities spanning IEC, GB, and BIS standards as procurement regionalization accelerates. Watch CRRC Corporation's centralized sourcing standardization across provincial rail offices as the signal for vendor consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Refining | Captive smelting secures electrolytic grade supply for Deutsche Bahn traction contracts against LME volatility. |
| Composite Material Qualification Partnership | Joint R&D with Yangtze River Delta institutes accelerates copper-aluminum bimetallic certification for cost-sensitive segments. |
| Dual Certification Facility Investment | Parallel IEC-GB testing capability unlocks CRRC Corporation export procurement and Indian PLI scheme incentives. |
| Direct Manufacturer Portal Launch | Bypassing distributor networks captures margin compression in India's Ministry of Railways centralized sourcing. |
| Renewable Energy Switchgear Integration | Modular fuse rail expansion into solar and wind farm installations diversifies revenue beyond rail electrification cycles. |
Methodological Framework
Trade association filings, customs import records, and IEC certification databases formed the secondary backbone, cross-referenced with primary interviews involving rail electrification procurement officers at Deutsche Bahn and CRRC Corporation, switchgear OEM technical directors, and copper alloy metallurgists at Yangtze River Delta research institutes. Bottom-up and top-down triangulation validated volume estimates against electrolytic copper consumption patterns in traction power applications.
Bottom-up modeling anchored on segment-level current capacity deployments across high-voltage, modular, standard, and safety fuse rail configurations, while top-down analysis calibrated aggregate market evolution against railway electrification capital expenditure disclosures. Segmentation dimensions spanned product voltage rating, installation mounting type, conductor material grade, and end-use vertical concentration. CAGRs derived from curve-fitting historical procurement cycles against announced electrification project timelines.
Copper price volatility, BIS certification timeline extensions, and railway project commissioning delays are the dominant revision risks. Deviation in LME futures trajectory would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Japan High Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
North America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Gas Insulated Substation Market
Transmission and Distribution
Pantograph Disconnector Market
Transmission and Distribution
Virtual Pipeline Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Mexico Pipeline Services Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market