
 Distribution Lines and Poles Market | 2026-2036
Distribution Lines and Poles Market Size, Share, and Industry Trends Forecast 2026-2036
Distribution Lines and Poles Market Analysis
Aftermarket service revenue for pole inspection, treatment, and structural reinforcement is narrowing as original equipment margins compress under raw material volatility. Valmont Industries leverages its global galvanizing footprint to sustain pricing power across steel pole categories. Prysmian Group anchors its position through integrated conductor and cable manufacturing that reduces project procurement complexity for utilities.
Distribution lines and poles comprise the physical infrastructure—conductors, cross-arms, insulators, and support structures—transmitting electrical power from substations to end users at voltages typically below 69 kV, with pole materials selected based on mechanical loading, corrosion exposure, and lifecycle cost. Steel poles dominate urban and coastal deployments where termite resistance and wind ratings exceed wood capabilities, while composite poles represent the fastest-growing material category as utilities pursue reduced maintenance intervals and extended asset life. Overhead installation retains overwhelming share but faces margin pressure from underground hybrid configurations in dense commercial corridors where reliability premiums justify higher capital outlay.
FERC reliability standards and NESC clearance requirements in the United States mandate minimum pole strength ratings and conductor separation distances that directly shape material selection and installation economics. India's CEA technical standards for distribution infrastructure and the country's PLI scheme for power sector equipment create compliance pathways that favor domestic pole and conductor sourcing. Stakeholders must monitor how evolving grid hardening mandates and carbon-accounting frameworks for embodied emissions in steel and concrete reshape total-cost-of-ownership calculations across material categories.
Market Dynamics
Grid hardening mandates and raw material volatility are compressing original equipment margins while forcing utilities toward lifecycle-cost procurement models for distribution infrastructure.
Growth Catalysts
- India's PLI scheme for power sector equipment:Domestic manufacturing incentives accelerate pole and conductor sourcing from local foundries and rolling mills, reducing import dependency for rural electrification programs.
- Steel pole specifications under IEC standards:Wind-loading requirements above 150 km/hr are phasing out treated wood in coastal and high-altitude corridors across multiple utilities.
- Composite material advancement:Fiberglass-reinforced polymer poles with 80-year design life are penetrating maintenance-averse utility segments in hurricane-prone territories.
Market Restraints
- Zinc price volatility:Hot-dip galvanizing costs fluctuate with London Metal Exchange pricing, squeezing margin predictability for steel pole fabricators.
- Cross-arm supply concentration:Laminated wood cross-arm production clusters in Baltic states, creating single-source vulnerability for North American utilities.
- Underground cable substitution:XLPE-insulated medium-voltage cables in dense commercial districts capture reliability-premium projects that would otherwise deploy overhead construction.
Strategic Opportunities
- Vietnam's industrial zone expansion:Manufacturing park electrification outside Ho Chi Minh City and Hanoi requires hundreds of thousands of new distribution poles annually through 2030.
- Digital twin integration:LiDAR-derived pole loading models combined with real-time weather feeds enable predictive maintenance contracts that monetize asset data.
- EU Green Deal embodied carbon accounting:Steel pole producers with electric arc furnace feedstock and renewable energy certificates capture preferential procurement scoring from European distribution system operators.
Industry Challenges
- Lineworker certification bottlenecks:Journeyman training programs for live-line work and composite pole installation cannot scale to match utility hiring targets in competitive labor markets.
- Legacy wood pole inspection backlogs:Ground-line decay assessment and structural rating protocols require manual field crews, creating asset visibility gaps for utilities with million-pole fleets.
- Interoperability friction with AMI:Smart meter communication modules and pole-mounted sensors demand unified mounting standards that conflict with existing hardware inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distribution Lines and Poles Market |
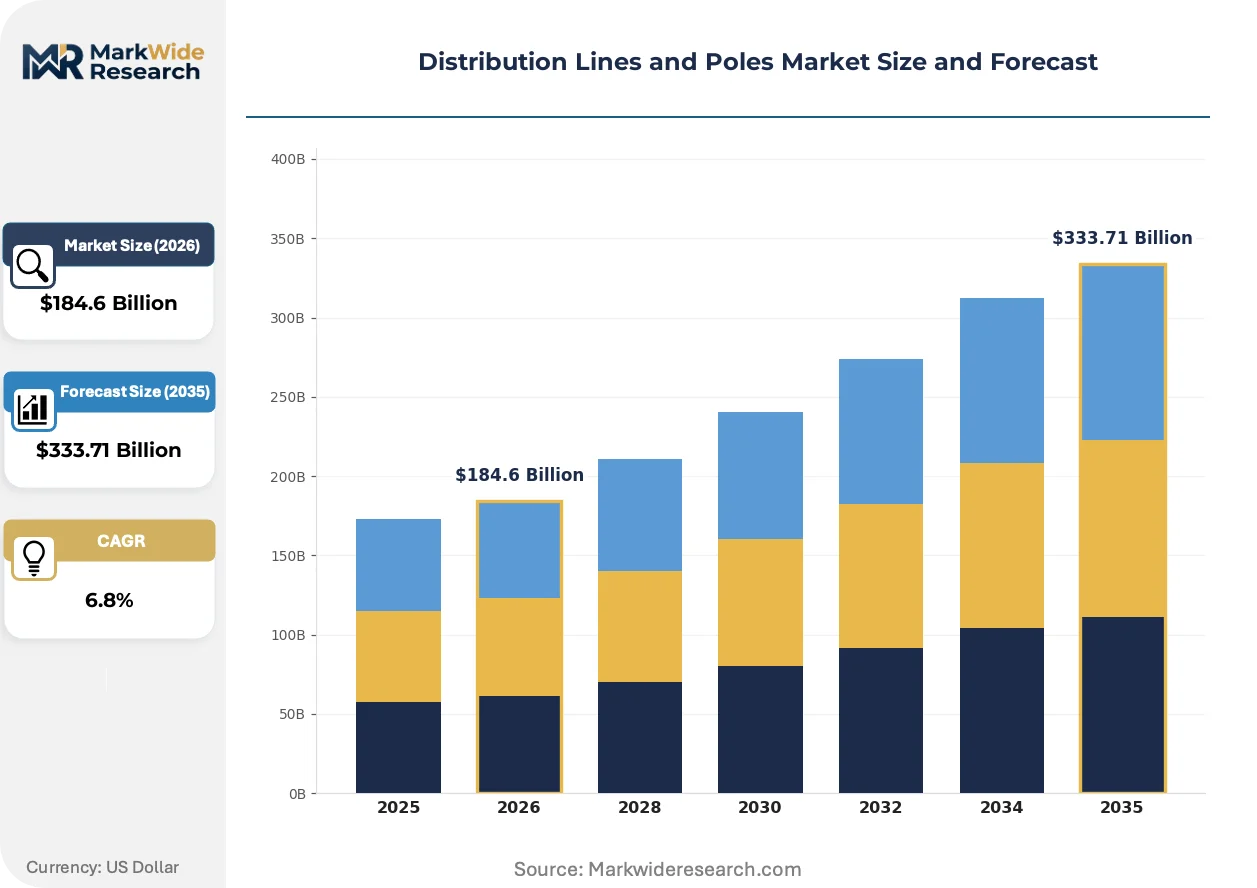
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $333.71 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wooden Poles, Steel Poles, Composite Poles, Concrete Poles Installation Type: Underground, Overhead, Hybrid, Subsurface End User: Utilities, Industrial Facilities, Commercial Properties, Residential Areas Voltage Rating: Low Voltage, Medium Voltage, High Voltage, Extra High Voltage |
| Companies Covered | Valmont Industries, Prysmian Group, Nexans, Stella-Jones, Koppers Utility & Industrial Products, APAR Industries, ZTT, KEI Industries, Bell Lumber & Pole Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distribution Lines and Poles Market Emerging Trajectories
Asset virtualization and predictive analytics are restructuring how utilities procure, operate, and retire distribution infrastructure across voltage classes and material categories.
Digital twin platforms for overhead distribution assets is virtualizing traditional inspection workflows. Mid-sized municipal utilities in the US Southeast are piloting drone-captured photogrammetry combined with finite element stress modeling to defer physical climb inspections. This technology is virtualizing the relationship between asset condition assessment and capital replacement scheduling, compressing O&M budgets toward software subscriptions.
EU CSRD sustainability disclosure requirements are mandating scope 3 emissions tracking for distribution infrastructure procurement. Steel and concrete pole suppliers must now provide Environmental Product Declarations with cradle-to-grave carbon footprints to qualify for framework agreements. German distribution system operators have responded by inserting embodied carbon clauses into technical specifications, effectively creating dual-gate compliance for material selection.
Integrated design-build contracting is consolidating engineering, material supply, and installation risk under single-source agreements. Investor-owned utilities in Texas and Florida are abandoning traditional bid-spec procurement for storm-hardening programs, instead awarding multi-year framework contracts to turnkey providers. This pattern is most visible in coastal wind zones where schedule certainty outweighs unit price optimization for regulatory rate-case recovery.
Distribution Lines and Poles Market Segmentation
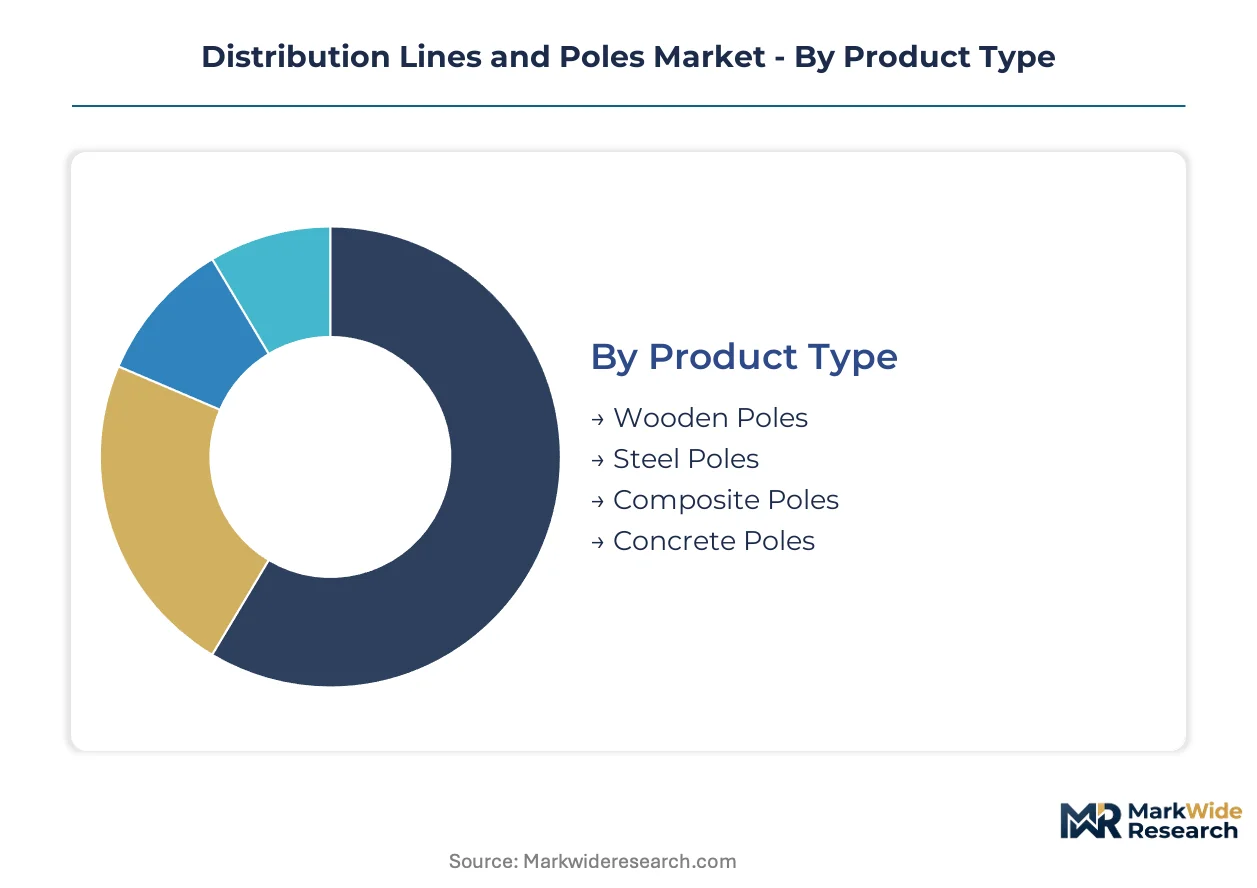
Segmentation in distribution infrastructure reveals how material selection, installation method, and voltage class interact to determine procurement economics. Each dimension carries distinct after-sales-service intensity, from pole treatment regimens to conductor inspection cycles.
Product Type:
After-sales-service intensity varies dramatically across pole materials, with inspection frequency and remediation protocols driving lifecycle cost divergence.
- Wooden Poles:Sawn timber or laminated structures dominate rural and low-density deployments where capital constraints outweigh maintenance burden. Ground-line decay assessment and periodic treatment cycles create recurring service revenue streams for utilities with million-pole fleets. By volume, Wooden Poles leads. By growth pace, Composite Poles is ahead.
- Steel Poles:Hot-dip galvanized tubular or polygonal sections withstand wind ratings exceeding 150 km/hr per IEC standards, displacing treated wood in coastal India and high-altitude corridors. Hot-dip galvanizing maintenance and weld inspection protocols sustain aftermarket service contracts.
- Composite Poles:Fiberglass-reinforced polymer structures with 80-year design life penetrate hurricane-prone territories seeking reduced maintenance intervals.
- Concrete Poles:Prestressed spun concrete withstands termite exposure and fire risk in urban India and Southeast Asian industrial zones.
Material selection increasingly hinges on total-cost-of-ownership calculations that embed inspection labor and replacement scheduling.
Installation Type:
Capital intensity and regulatory clearance requirements fragment procurement patterns across installation methodologies.
- Overhead:Conductor-on-pole configurations retain dominant share across rural electrification programs in India and Vietnam due to lower first-cost and ease of fault location. Storm damage vulnerability sustains hardening upgrade cycles.
- Underground:XLPE-insulated medium-voltage cables capture reliability-premium projects in dense commercial districts where outage costs exceed capital outlay differentials.
- Hybrid:Mixed overhead-underground configurations optimize cost-reliability tradeoffs in suburban corridors transitioning from rural to urban density.
- Subsurface:Direct-buried or duct-bank installations serve aesthetic-sensitive historic districts and airport approach zones with strict height restrictions.
Overhead retains volume leadership while Underground claims the steepest expansion trajectory in premium reliability segments.
End User:
Procurement sophistication and specification authority concentrate differently across customer categories.
- Utilities:Investor-owned and public power entities drive standardization through framework agreements and multi-year storm-hardening contracts in Texas and Florida.
- Industrial Facilities:Manufacturing parks outside Ho Chi Minh City and Hanoi demand dedicated distribution infrastructure with high fault-current withstand.
- Commercial Properties:Retail and office developers prioritize aesthetic pole finishes and underground service entrance in premium locations.
- Residential Areas:Subdivision developers balance first-cost constraints with homeowner association aesthetic requirements.
Utilities dominate procurement volume while Industrial Facilities generate the fastest order growth.
Voltage Rating:
Insulation coordination and clearance standards scale non-linearly with voltage class, reshaping material specifications.
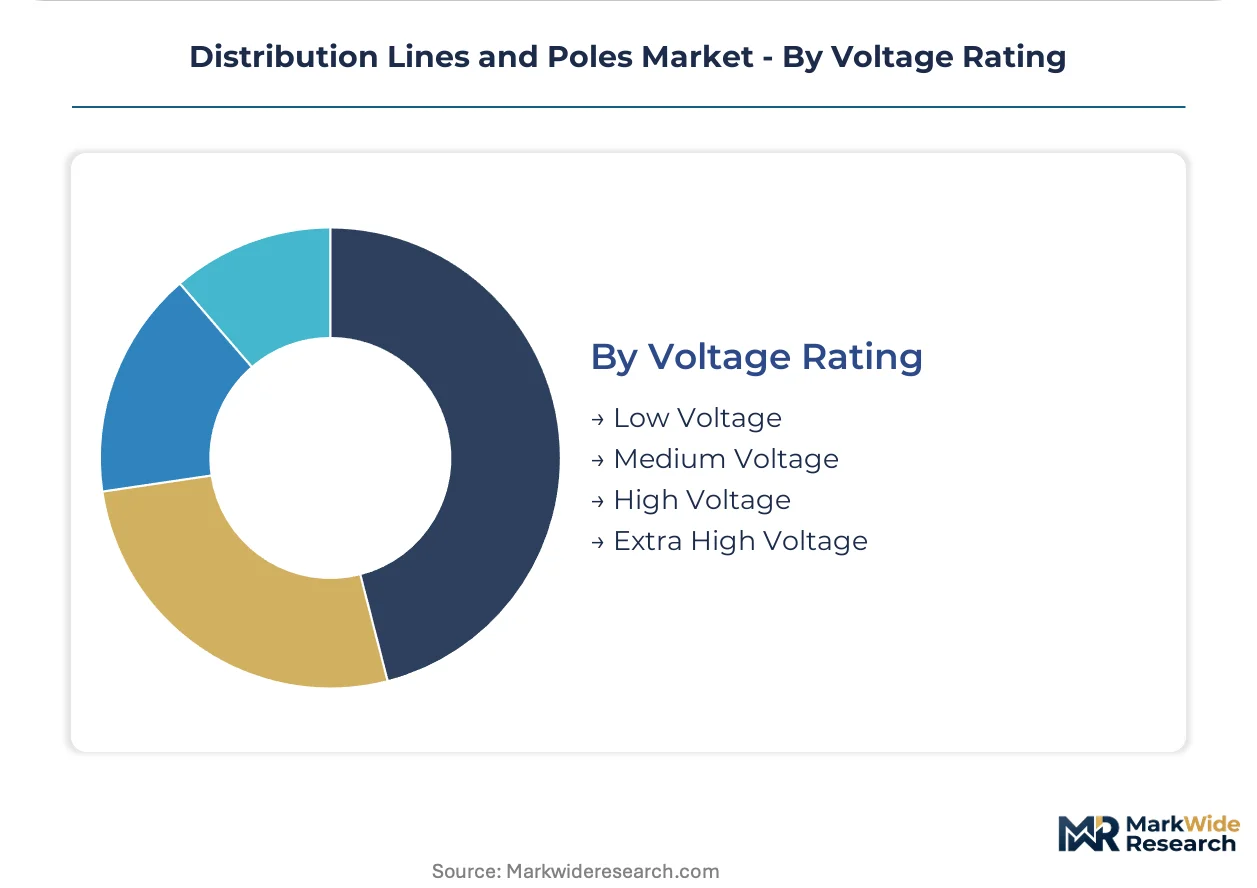
- Low Voltage:Secondary distribution below 1 kV serves residential drops and small commercial connections with standardized pole-top assemblies.
- Medium Voltage:Primary distribution between 1 kV and 69 kV constitutes the core revenue base, with conductor sizing and pole strength ratings varying by span length and loading.
- High Voltage:Subtransmission circuits between 69 kV and 230 kV require engineered pole structures with guy-wire or self-supporting configurations.
- Extra High Voltage:Bulk power transfer above 230 kV transitions to lattice towers rather than distribution poles, blurring segment boundaries with transmission infrastructure.
Medium Voltage anchors revenue concentration while Low Voltage expands most quickly through rural electrification scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exhibits the highest demand elasticity as rural electrification programs prioritize volume procurement, while Germany and the United States show price inelasticity where reliability premiums and storm-hardening mandates dominate capital allocation decisions.
United States
Investor-owned utilities in Texas and Florida drive multi-year framework contracts for storm-hardening programs where schedule certainty outweighs unit price optimization. FERC reliability standards and NESC clearance requirements mandate minimum pole strength ratings that reshape material selection economics. The Southeast corridor from Florida through Georgia concentrates underground hybrid deployments in dense commercial districts.
India
Rural electrification programs and smart grid investments require millions of new distribution poles and conductors annually through state-led distribution companies. CEA technical standards for distribution infrastructure and the PLI scheme for power sector equipment create compliance pathways favoring domestic pole and conductor sourcing. Manufacturing clusters in Gujarat and Maharashtra supply galvanized steel poles to utilities prioritizing wind-loading specifications above 150 km/hr.
Germany
Distribution system operators insert embodied carbon clauses into technical specifications following EU CSRD sustainability disclosure requirements. EU Green Deal frameworks mandate scope 3 emissions tracking for distribution infrastructure procurement. Industrial zones in North Rhine-Westphalia and Bavaria pilot digital twin platforms for overhead asset virtualization.
Vietnam
Manufacturing park electrification outside Ho Chi Minh City and Hanoi requires hundreds of thousands of new distribution poles annually through 2030. National power development plans prioritize grid expansion to industrial load centers in the south and north. The Binh Duong and Dong Nai provinces concentrate foreign direct investment in electronics manufacturing with dedicated distribution infrastructure demands.
Brazil
Utilities in São Paulo and Minas Gerais states expand grid infrastructure to serve industrial load centers in southeastern manufacturing corridors. ANVISA-equivalent national electric energy regulator standards govern distribution infrastructure technical specifications. The Campinas and Sorocaba industrial clusters drive demand for high fault-current withstand poles in dedicated manufacturing park electrification.
Distribution Lines and Poles Market Vendor Landscape
Capability concentration sits with specialized pole fabricators and integrated conductor manufacturers; scale advantage sits with diversified industrial conglomerates and global galvanizing networks. The market structures around three tiers: turnkey design-build contractors capturing storm-hardening frameworks, material specialists dominating specific product categories, and regional fabricators serving utility procurement localization mandates. Strategic moves concentrate on integrated design-build contracting consolidation and multi-year framework agreement capture.
Among North American-listed entities, Valmont Industries exemplifies the scale-driven tier through its global galvanizing footprint, while Stella-Jones occupies a position within wood pole specialization. Prysmian Group anchors the integrated conductor manufacturing archetype. These three represent distinct competitive positioning vectors without overlapping core capability claims.
| Leading Market Players |
|---|
| Valmont Industries |
| Prysmian Group |
| Nexans |
| Stella-Jones |
| Koppers Utility & Industrial Products |
| APAR Industries |
| ZTT |
| KEI Industries |
| Bell Lumber & Pole Company |
| Others |
Supply Flow & Price Mechanics
The Shanghai-Rotterdam container corridor's freight volatility transmits directly into landed costs for galvanized steel poles and laminated wood cross-arms, compressing margin buffers for fabricators while forcing utilities toward multi-year framework contracts that lock in volume commitments against price spikes.
Pricing Analysis
Aftermarket service revenue from pole inspection, treatment, and structural reinforcement drives lifetime value capture for specialized contractors. Three-tier pricing structure across premium, standard, and economy levels separates turnkey design-build providers from material-only suppliers and regional fabricators. Cost compression in the standard tier is intensifying because zinc price volatility on the London Metal Exchange erodes hot-dip galvanizing margins. Rural electrification programs in India exhibit the highest price sensitivity, while storm-hardening mandates in Florida and Texas show price inelasticity where schedule certainty dominates procurement decisions.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for steel pole fabricators sourcing hot-rolled coil feedstock. Manufacturing gravity centers on India, China, and the United States for pole fabrication, with laminated wood cross-arm production clustering in the Baltic states. Raw material inputs draw from zinc ingots for galvanizing, fiberglass resin systems for composite poles, and prestressed concrete for urban deployments. Single-source vulnerability in Baltic cross-arm supply creates procurement risk for North American utilities. Distribution runs through direct utility framework agreements and EPC contractor channels rather than distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in a cyclical recovery phase as grid hardening capital cycles follow storm damage patterns and regulatory reliability mandates. Infrastructure replacement waves in hurricane-prone territories provide the cyclical driver justifying multi-year procurement visibility.
For Market Incumbents: Build switching-cost moats through integrated design-build contracting that consolidates engineering, material supply, and installation risk under single-source agreements. Incumbents should deepen backward integration into captive galvanizing capacity to defend against zinc price volatility. Certification investment in IEC wind-loading standards above 150 km/hr creates technical barriers against low-cost regional entrants. Channel control through multi-year framework agreements with investor-owned utilities in Texas and Florida locks out competitor access to premium storm-hardening projects.
For New Entrants and Emerging Players: Vietnam's industrial zone expansion outside Ho Chi Minh City and Hanoi offers white-space opportunity where foreign direct investment in electronics manufacturing outpaces local pole fabrication capacity. Entrants should target composite pole segments in hurricane-prone territories where 80-year design life specifications displace traditional materials. A go-to-market angle anchored in digital twin integration—LiDAR-derived loading models with predictive maintenance subscriptions—differentiates against incumbent hardware-only positioning.
For Investors and Strategic Acquirers: Regional fabricators with domestic content compliance for India's PLI scheme represent the acquisition target archetype with embedded regulatory optionality. Long-term viability across the analysis window hinges on exposure to rural electrification volume programs and smart grid sensor integration capabilities. The signal to watch is embodied carbon accounting adoption by European distribution system operators, which would revalue electric arc furnace feedstock producers with renewable energy certificates.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Design-Build Contracting | Consolidates engineering, supply, and installation risk for Texas and Florida storm-hardening programs. |
| Backward Integration into Galvanizing | Captures margin from zinc price volatility while ensuring quality control for IEC wind-loading specifications. |
| Digital Twin Platform Development | Monetizes asset data through predictive maintenance contracts with municipal utilities in the US Southeast. |
| Composite Material Scale-Up | Addresses maintenance-averse utility segments in hurricane-prone territories with 80-year design life poles. |
| Domestic Manufacturing Localization | Qualifies for India's PLI scheme while reducing freight exposure on the Shanghai-Rotterdam corridor. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with utility planning officers, EPC contractors, pole fabricator procurement heads, and aftermarket service directors; and secondary validation through FERC reliability filings, CEA technical standards documentation, EU CSRD sustainability disclosures, and customs trade data for steel and wood product categories. Bottom-up triangulation against top-down market sizing ensured consistency across volume and value estimates.
Forecast inputs considered pole material substitution dynamics, installation method migration patterns, and voltage class expansion trajectories across the projection horizon. Segmentation dimensions modeled include product type, installation methodology, end-user category, and voltage rating tier. CAGRs were derived from utility capital expenditure planning cycles and regulatory mandate implementation schedules. Industry-specific inputs encompassed rural electrification program targets in India and industrial zone electrification timelines in Vietnam.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated energy infrastructure conglomerates or technology-enabled predictive maintenance platforms would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Energy Cable Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Power Transmission Lines and Towers Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
HVDC Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Middle East High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
China High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Digital Substation Market
Transmission and Distribution
Electricity Transmission Infrastructure Market