
 Heavy-Duty Truck Megapack Battery Systems Market | 2026-2036
Heavy-Duty Truck Megapack Battery Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy-Duty Truck Megapack Battery Systems Market Insights
Project finance tied to battery-as-a-service leasing is tilting competitive dynamics toward capital-heavy platforms that can underwrite long-duration asset risk. Tesla Energy leverages its integrated energy ecosystem to bundle charging infrastructure with cell supply. CATL anchors its position through massive manufacturing scale across multiple continents. BYD sustains cost leadership via backward integration into raw material refining and in-house production of lithium iron phosphate cells.
Heavy-duty truck megapack battery systems are high-capacity energy storage assemblies designed for integration into Class 8 and comparable commercial vehicles, typically employing lithium-ion or emerging solid-state chemistries with pack-level capacities exceeding 500 kWh and thermal management architectures capable of sustaining repeated fast-charging cycles. Their primary purpose is to displace diesel propulsion in weight-sensitive, distance-intensive freight operations where energy density and cycle life determine vehicle uptime. Lithium-ion chemistry dominates current deployments due to established supply chains and proven manufacturing equipment, while solid-state technology occupies the frontier of R&D investment as manufacturers chase higher energy density with reduced thermal runaway risk. Fast charging infrastructure competes with modular battery swapping as the critical enabler for long-haul transport applications where dwell time directly impacts fleet revenue.
The EPA's Phase 3 greenhouse gas standards for heavy-duty vehicles in the United States and the EU's CO2 emission performance standards for heavy-duty vehicles are mandating zero-emission powertrain penetration rates that directly translate to megapack battery procurement obligations. China's MIIT administers new energy vehicle subsidy thresholds and GB standards that shape which cell formats qualify for domestic truck OEM supply contracts. Fleet operators and cell suppliers must monitor regulatory divergence between jurisdictions to avoid stranded asset risk from incompatible certification requirements.
Market Dynamics
Total cost of ownership parity with diesel powertrains is compressing fleet conversion timelines, forcing battery suppliers to underwrite charging infrastructure alongside cell supply contracts.
Growth Catalysts
- EU CO2 emission performance standards:Mandated zero-emission powertrain penetration rates are creating binding procurement obligations for megapack systems in long-haul freight fleets operating across Germany, France, and the Netherlands.
- Battery-as-a-service leasing:Capital-light fleet operators are accelerating adoption through project finance structures that transfer asset risk to platform providers with balance sheet capacity.
- Silicon-anode chemistries:Higher energy density formulations are extending single-charge range thresholds, reducing the infrastructure density required for cross-country corridor operations.
Market Restraints
- Lithium carbonate price volatility:Raw material input costs swing with spot market conditions in Chile and Australia, compressing cell margin structures and deterring long-term contract pricing.
- Fast-charging infrastructure gaps:Corridor coverage remains sparse outside China's coastal provinces and Germany's autobahn network, limiting route flexibility for battery-electric Class 8 operations.
- Thermal runaway containment:Pack-level safety architectures add weight and volume overhead, reducing payload capacity in weight-sensitive bulk freight applications.
Strategic Opportunities
- India's freight electrification corridors:The Delhi-Mumbai Industrial Corridor and Dedicated Freight Corridor projects are creating anchor demand for high-capacity battery systems in domestic truck OEM supply contracts.
- Modular battery swapping:Standardized pack formats compatible with automated exchange stations are emerging as an alternative to fast-charging for time-critical logistics operations in China's port hinterlands.
- US Inflation Reduction Act domestic content credits:Cell and module assembly incentives are reshaping supply chain geography toward North American manufacturing footprints.
Industry Challenges
- Battery management system firmware certification:Functional safety validation to ISO 26262 ASIL-D standards extends development timelines and requires specialized embedded systems engineering talent pools concentrated in Germany and Japan.
- Pack-to-chassis integration complexity:Legacy truck OEM assembly lines require reconfiguration for skateboard architectures, creating tooling friction and supplier qualification bottlenecks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy-Duty Truck Megapack Battery Systems Market |
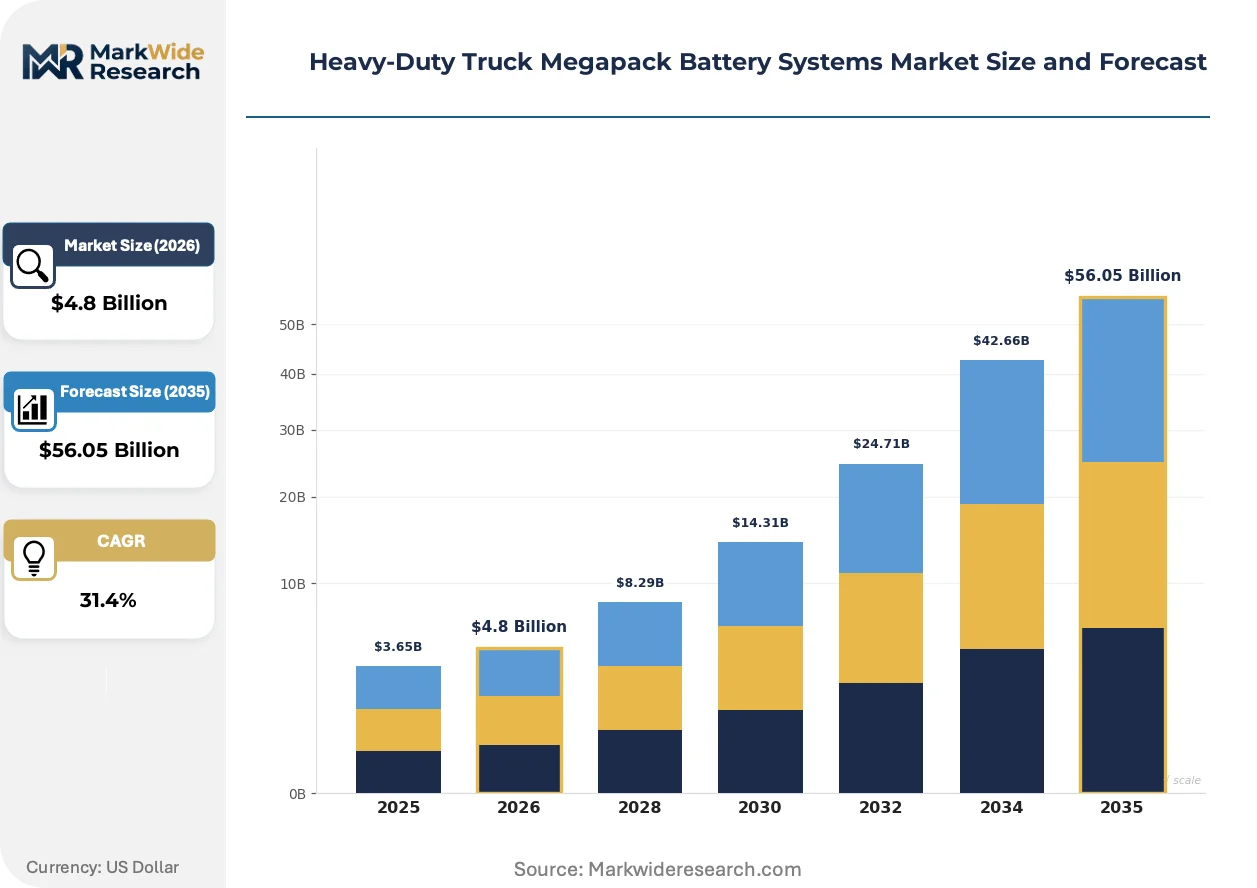
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $56.05 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-Ion, Solid-State, Nickel-Metal Hydride, Lead Acid, Sodium-Ion Technology: Battery Management System, Thermal Management, Fast Charging, Modular Design, Wireless Connectivity Application: Long-Haul Transport, Construction Hauling, Mining Operations, Waste Collection, Emergency Response End User: Fleet Operators, Freight Logistics, Heavy Equipment Rentals, Municipal Service Providers, Mining Corporations |
| Companies Covered | Tesla Energy, CATL, BYD, LG Energy Solution, Samsung SDI, Northvolt, Daimler Truck, TRATON Group, Volvo Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy-Duty Truck Megapack Battery Systems Market Trends and Innovations
Digital twin architectures are reshaping how cell degradation gets modeled across fleet operations, compressing warranty risk assessment cycles and enabling predictive maintenance contracts.
Cell-level sensing networks with distributed temperature and voltage monitoring are digitizing state-of-health estimation accuracy. Fleet operators with 500-plus vehicle deployments are mandating these architectures in new procurement specifications. The resulting data granularity is compressing insurance underwriting cycles and enabling residual value guarantees previously unavailable in secondary battery markets.
EPA Phase 3 greenhouse gas standards are tightening CO2 intensity thresholds for heavy-duty vehicles through 2032. US-based fleet operators are responding by accelerating zero-emission powertrain pilot programs in drayage and regional haul segments. California's Advanced Clean Trucks regulation is amplifying this effect, with the state's CARB certification becoming a de facto national compliance benchmark for OEM product planning.
Service contract unbundling is separating battery performance guarantees from vehicle chassis warranties. Large fleet operators with in-house maintenance capabilities are negotiating direct cell supplier relationships, bypassing traditional OEM service networks. This pattern is most visible in Germany's autobahn freight corridors and China's Yangtze River Delta manufacturing belts, where uptime penalties dominate supplier selection criteria.
Heavy-Duty Truck Megapack Battery Systems Market Segmentation
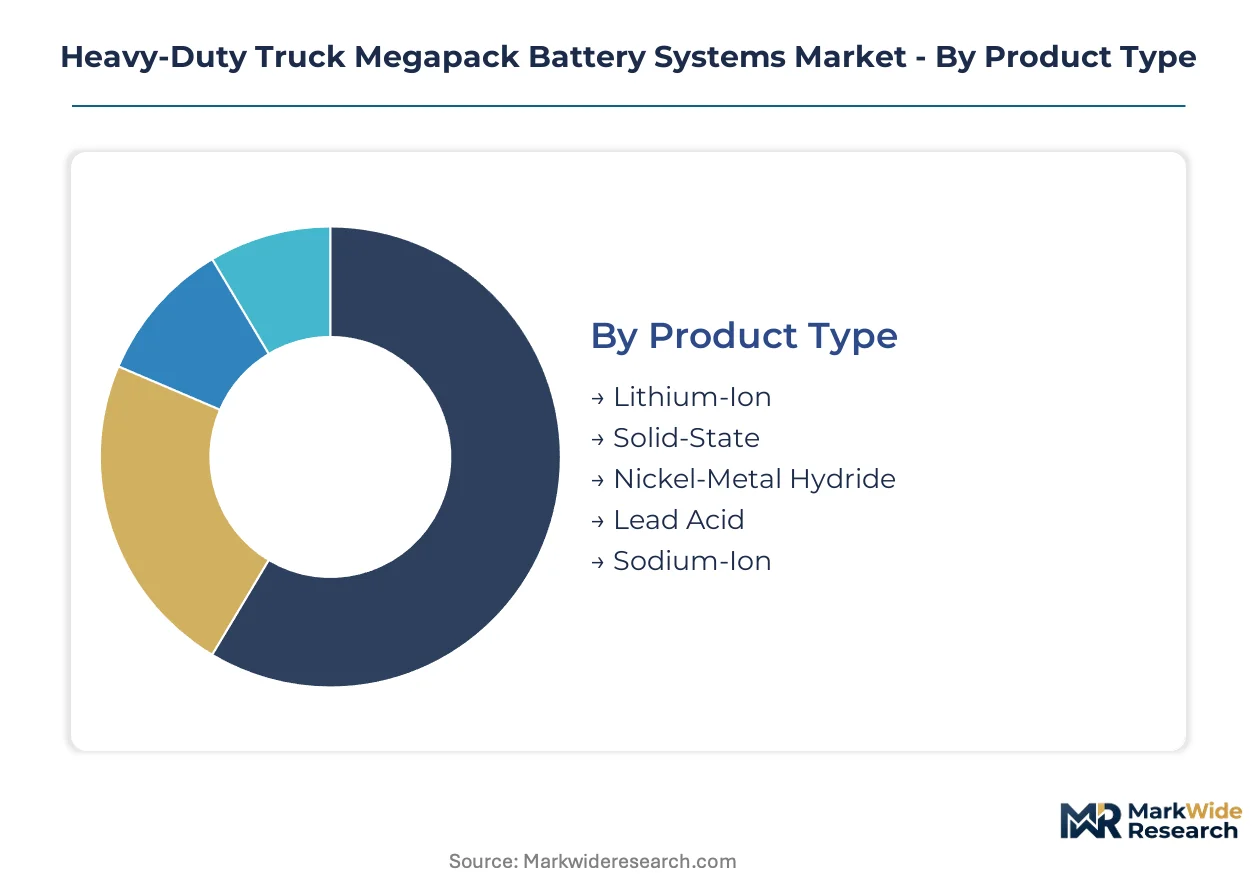
Segmentation in heavy-duty truck megapack battery systems reveals distinct service intensity profiles across chemistry types and operational use cases. Fleet operators prioritize segments with proven degradation modeling and warranty-backed residual value guarantees.
Product Type:
After-sales service intensity varies sharply across chemistries, with solid-state architectures demanding specialized thermal calibration protocols that lithium-ion has rendered routine through standardization.
- Lithium-Ion:Proven lithium-nickel-manganese-cobalt and lithium-iron-phosphate formulations dominate current procurement. German autobahn freight corridors and California's drayage fleets anchor demand as total cost of ownership equations stabilize around established cycle life benchmarks.
- Solid-State:Emerging ceramic-electrolyte designs promise higher energy density with reduced thermal runaway risk. Toyota and QuantumScape pilot programs in Japan and the United States are concentrating early adoption in premium long-haul segments where payload sensitivity justifies technology premiums.
- Nickel-Metal Hydride:Legacy chemistry retains niche presence in municipal waste collection fleets with moderate duty cycles and established recycling infrastructure.
- Lead Acid:Limited to auxiliary power applications and starter systems in hybrid architectures across emerging market truck conversions.
- Sodium-Ion:Prussian white cathode formulations from CATL and BYD target cost-sensitive construction hauling in China's interior provinces where lithium supply security concerns reshape procurement criteria.
By volume, Lithium-Ion leads. By growth pace, Solid-State is ahead.
Technology:
Cost tier stratification separates integrated platform providers from component specialists, with full-stack battery management system vendors commanding service contract premiums.
- Battery Management System:Cell-level sensing networks with distributed temperature and voltage monitoring digitize state-of-health estimation. Fleet operators with 500-plus vehicle deployments in Germany's Ruhr industrial cluster mandate these architectures in procurement specifications.
- Thermal Management:Liquid cooling loops and phase-change materials sustain repeated fast-charging cycles in Australia's Pilbara mining corridors where ambient temperatures exceed 45°C. Pack-level safety architectures add weight overhead that constrains payload capacity.
- Fast Charging:Megawatt-scale charging protocols from ABB and Siemens enable 30-minute replenishment windows along Germany's autobahn network and China's G4 Beijing-Hong Kong-Macau Expressway.
- Modular Design:Standardized pack formats compatible with automated exchange stations emerge as alternatives to fast-charging in China's Yangtze River Delta port hinterlands.
- Wireless Connectivity:Over-the-air firmware updates and predictive maintenance telemetry compress warranty risk assessment cycles for US-based fleet operators managing dispersed regional haul networks.
Procurement concentrates in Battery Management System and Thermal Management for new deployments, with Fast Charging infrastructure representing the steepest expansion trajectory as corridor coverage extends.
Application:
Customer type differentiation separates asset-heavy owner-operators from capital-light rental fleets, with uptime penalty structures reshaping supplier selection criteria.
- Long-Haul Transport:Cross-country freight operations between Rotterdam and Milan or Los Angeles and Dallas demand energy density above 300 Wh/kg. Silicon-anode chemistries extend single-charge range thresholds, reducing infrastructure density requirements.
- Construction Hauling:Site-to-site material transport in India's Delhi-Mumbai Industrial Corridor creates anchor demand for ruggedized pack enclosures with vibration resistance certification.
- Mining Operations:Underground and open-pit extraction sites in Western Australia's Pilbara region and Chile's Atacama Desert prioritize thermal runaway containment in confined operational envelopes.
- Waste Collection:Stop-start urban duty cycles with predictable range requirements suit lower-cost sodium-ion and nickel-metal hydride configurations in European municipal fleets.
- Emergency Response:Fire apparatus and disaster relief vehicles in Japan's earthquake-prone prefectures demand 100% state-of-charge availability with grid-independent charging capability.
Long-Haul Transport commands the largest installed base, while Mining Operations is climbing the fastest as extraction electrification mandates tighten.
End User:
Supply concentration among tier-one cell manufacturers produces divergent procurement leverage across end user categories, with mining corporations wielding volume-scale negotiation power unavailable to municipal service providers.
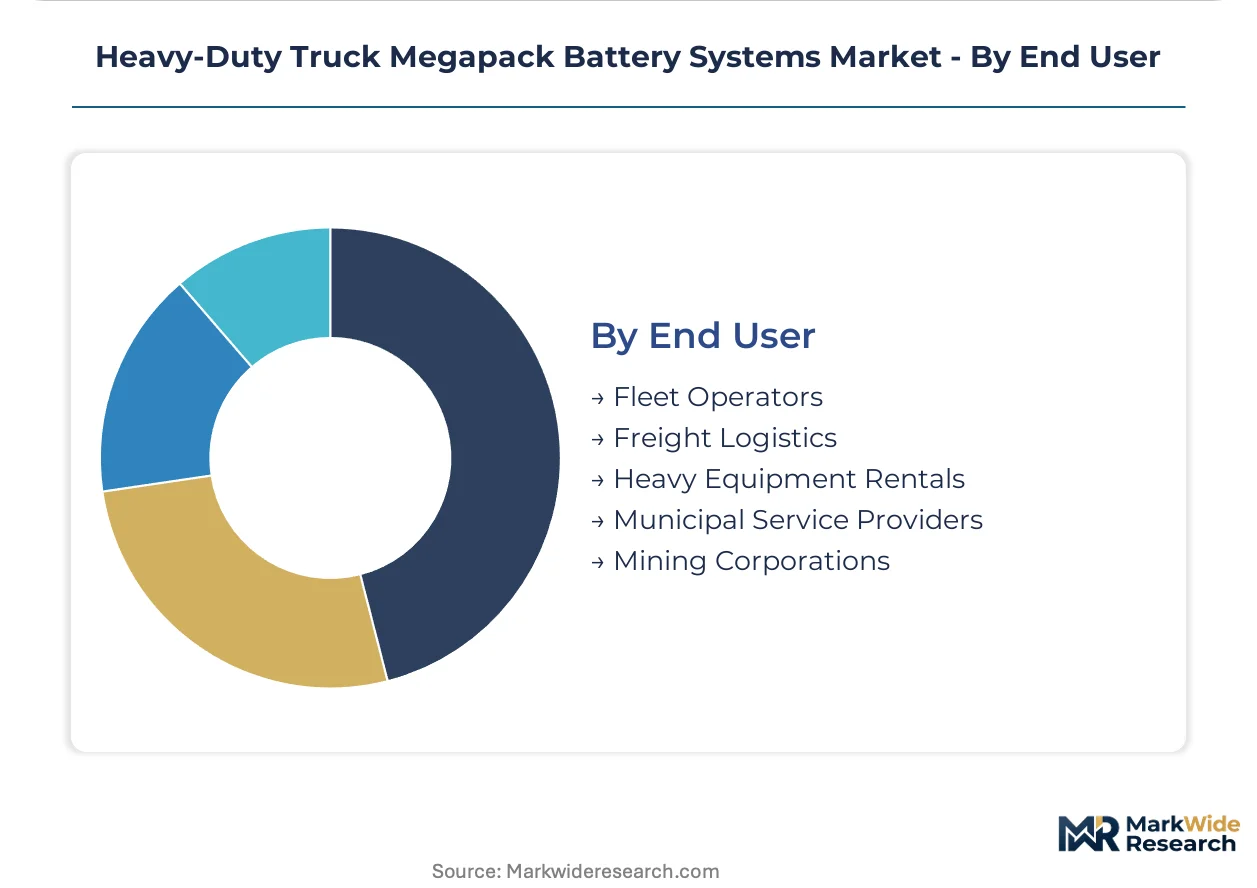
- Fleet Operators:Schneider National and J.B. Hunt-scale operators with 10,000-plus vehicle portfolios negotiate direct cell supplier relationships, bypassing traditional OEM service networks for performance guarantees.
- Freight Logistics:DHL and FedEx ground operations prioritize modular battery swapping compatibility in China's Pearl River Delta manufacturing belts where dwell time penalties dominate supplier selection.
- Heavy Equipment Rentals:United Rentals and Ashtead Group fleets demand flexible lease structures transferring residual value risk to platform providers with balance sheet capacity for long-duration asset exposure.
- Municipal Service Providers:City of Los Angeles Sanitation and Berliner Stadtreinigungsbetriebe procurement cycles extend 18-24 months with certification requirements to EU CO2 emission performance standards.
- Mining Corporations:Rio Tinto and BHP electrification commitments in Western Australia and Chile drive high-capacity system orders with 15-year service life specifications and extreme-environment thermal management.
Fleet Operators represent the deepest procurement volume. Mining Corporations are gaining share fastest as extraction sector decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China runs a substantial surplus in heavy-duty truck megapack battery systems, exporting cells and complete packs to Germany and the United States while importing raw lithium feedstock from Australia and Chile. Germany and the United States remain net importers of finished battery systems despite aggressive domestic manufacturing buildouts under industrial policy frameworks.
China
CATL and BYD anchor production capacity across Fujian and Guangdong provinces, supplying domestic OEMs and export markets simultaneously. MIIT administers GB standards and new energy vehicle subsidy thresholds that determine which cell formats qualify for truck supply contracts. The Yangtze River Delta manufacturing belt concentrates automated battery swapping infrastructure development for port hinterland logistics.
Germany
CATL's Erfurt facility and Northvolt's planned Heide factory are reversing import dependence for European truck OEMs. The EU's CO2 emission performance standards for heavy-duty vehicles mandate zero-emission powertrain penetration rates that translate directly to megapack procurement obligations. The Ruhr industrial cluster hosts fleet operators with 500-plus vehicle deployments mandating advanced battery management architectures.
United States
Tesla Energy's Nevada operations and emerging cell plants in Michigan and Kentucky are scaling to meet EPA Phase 3 greenhouse gas standards tightening through 2032. The Inflation Reduction Act's domestic content credits reshape supply chain geography toward North American assembly footprints. California's CARB certification functions as a de facto national compliance benchmark, with Los Angeles and Long Beach drayage fleets anchoring early adoption.
India
The Delhi-Mumbai Industrial Corridor and Dedicated Freight Corridor projects generate anchor demand for high-capacity systems in domestic truck OEM supply contracts. The PLI scheme for advanced chemistry cell manufacturing incentivizes local production scale-up. Gujarat and Maharashtra industrial zones concentrate procurement activity from construction hauling and mining electrification commitments.
Australia
Pilbara mining corridors drive extreme-environment thermal management specifications for open-pit extraction electrification. The country's lithium spodumene exports to China dominate upstream material flows, though downstream cell manufacturing remains absent. Western Australia hosts Rio Tinto and BHP electrification pilots with 15-year service life requirements.
Heavy-Duty Truck Megapack Battery Systems Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream with narrower scope but deeper technical concentration. The vendor base stratifies into three tiers: integrated energy platforms with charging infrastructure bundling, pure-play cell manufacturers with multi-continent manufacturing scale, and captive suppliers owned by truck OEMs. Consolidation pressures favor capital-heavy platforms capable of underwriting battery-as-a-service leasing structures. Dominant competitive moves include capacity expansion across multiple continents and strategic partnerships securing raw material offtake agreements.
Within the integrated platform tier, Tesla Energy exemplifies vertical scope spanning cell production through charging network deployment. CATL and BYD occupy positions as scale-driven cell specialists with backward integration into raw material refining. These three anchors represent divergent strategic postures: ecosystem bundling versus manufacturing scale versus cost leadership through upstream control.
| Leading Market Players |
|---|
| Tesla Energy |
| CATL |
| BYD |
| LG Energy Solution |
| Samsung SDI |
| Northvolt |
| Daimler Truck |
| TRATON Group |
| Volvo Group |
| Others |
Pricing and Supply Chain Analysis
CATL's 85% utilization rate at its Ningde facilities is compressing supplier margins while forcing tier-two cell makers toward aggressive price positioning. This capacity glut in China's coastal provinces simultaneously enables fleet procurement leverage and pressures raw material contract renegotiations across the lithium value chain.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on cycle life certification grade and thermal management complexity, with mining fleet specifications commanding premiums above regional haul configurations. Cost compression in the standard tier is intensifying because sodium-ion alternatives are reshaping procurement benchmarks for construction hauling. Municipal service providers exhibit the highest price sensitivity due to elongated 18-24 month procurement cycles, while mining corporations with 15-year service life requirements demonstrate the lowest.
Supply Chain Analysis
Extended payment terms from 90 to 120 days are becoming standard for tier-one cell suppliers absorbing working capital strain from raw material pre-payments. Geographic concentration centers on China, South Korea, and Japan for cell manufacturing, with Australia and Chile feeding lithium carbonate and spodumene concentrate dependencies. Single-source vulnerability in electrolyte additive supply from Japanese specialty chemical producers poses structural risk. Distribution runs through OEM-integrated platform providers rather than independent distributors, concentrating channel control with Tesla Energy, CATL, and BYD.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against hydrogen fuel cell powertrains gaining traction in Germany's autobahn freight corridors and Japan's port drayage operations. Battery-electric incumbents must navigate range parity claims from fuel cell OEMs while maintaining total cost of ownership advantages.
For Market Incumbents: Build regulatory certification moats by securing EPA Phase 3 compliance pathways and CARB certification ahead of tightening CO2 intensity thresholds. Secure backward integration into lithium refining in Australia and Chile to isolate margin structures from carbonate spot volatility. Hydrogen fuel cell range claims in long-haul segments represent the immediate substitute threat requiring cycle life documentation rebuttals. For New Entrants and Emerging Players: India's Delhi-Mumbai Industrial Corridor and Dedicated Freight Corridor projects represent the most penetrable entry point for construction hauling and mining electrification commitments. Sodium-ion formulations for cost-sensitive interior provinces in China offer technology differentiation without lithium supply security exposure. A battery-as-a-service leasing platform structure transfers residual value risk while bypassing capital-intensive manufacturing scale requirements. For Investors and Strategic Acquirers: Capital is best deployed toward integrated energy platforms with charging infrastructure bundling capability and balance sheet capacity for long-duration asset exposure. Five-to-ten year viability hinges on corridor coverage extension along major freight routes. The inflection signal to watch is megawatt-scale charging protocol standardization between ABB, Siemens, and Chinese equipment providers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lithium Refining | Captive supply from Australia's Pilbara region insulates margin structures from carbonate spot volatility. |
| Battery-as-a-Service Platform Launch | Project finance structures transfer residual value risk to capital-heavy platforms with underwriting capacity. |
| Megawatt-Scale Charging Infrastructure Partnership | Corridor coverage along Germany's autobahn network enables 30-minute replenishment windows for fleet operators. |
| Solid-State Chemistry R&D Investment | Toyota and QuantumScape pilot programs concentrate early adoption in payload-sensitive premium long-haul segments. |
| Modular Battery Swapping Standardization | Automated exchange stations in China's Yangtze River Delta port hinterlands reduce dwell time penalties. |
Research Methodology
Cross-validation between fleet operator procurement directors and cell supplier commercial executives anchors the qualitative findings. Primary interviews with OEM platform engineers, charging infrastructure developers, mining corporation electrification leads, and regulatory affairs specialists at CARB and EPA were combined with secondary validation from EPA Phase 3 regulatory filings, MIIT GB standard publications, EU CO2 emission performance standard documents, and lithium trade flow customs data. Bottom-up cell shipment aggregation and top-down fleet conversion modeling were triangulated against corridor infrastructure deployment timelines.
Calibration against historical fleet procurement cycles and charging infrastructure buildout rates shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include battery chemistry type, thermal management architecture, application use case, and end user category with fleet scale tiering. CAGRs were derived from elasticity-adjusted adoption curves incorporating total cost of ownership parity thresholds and regulatory mandate compliance deadlines. Silicon-anode energy density improvements and solid-state manufacturing yield trajectories served as technology-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in lithium carbonate spot prices, freight rate volatility, or industrial electricity pricing would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and charging infrastructure deployment schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Southeast Asia Battery Market
Batteries
Cobalt-Free Battery Market
Batteries
Middle-East and Africa Battery Cell Market
Batteries
Power Tool Batteries Market
Batteries
Military Battery Market
Batteries
Battery Materials Market
Batteries
Electrolyte Solutions for Li-Ion Batteries Market
Batteries
Modular Battery Market
Batteries
Modular Battery Pack Market
Batteries
Industrial Backup Battery Market
Batteries
Medical Batteries Market
Batteries
Battery Swapping Market
Batteries
Echelon Utilization of Power Battery Market
Batteries
India SLI Battery Market
Batteries
Thin Film Photovoltaic and Batteries Market
Batteries
Europe Rechargeable Battery Market