
 Smart Fault Detection System for Power Transmission Market | 2026-2036
Smart Fault Detection System for Power Transmission Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Fault Detection System for Power Transmission Market Analytics
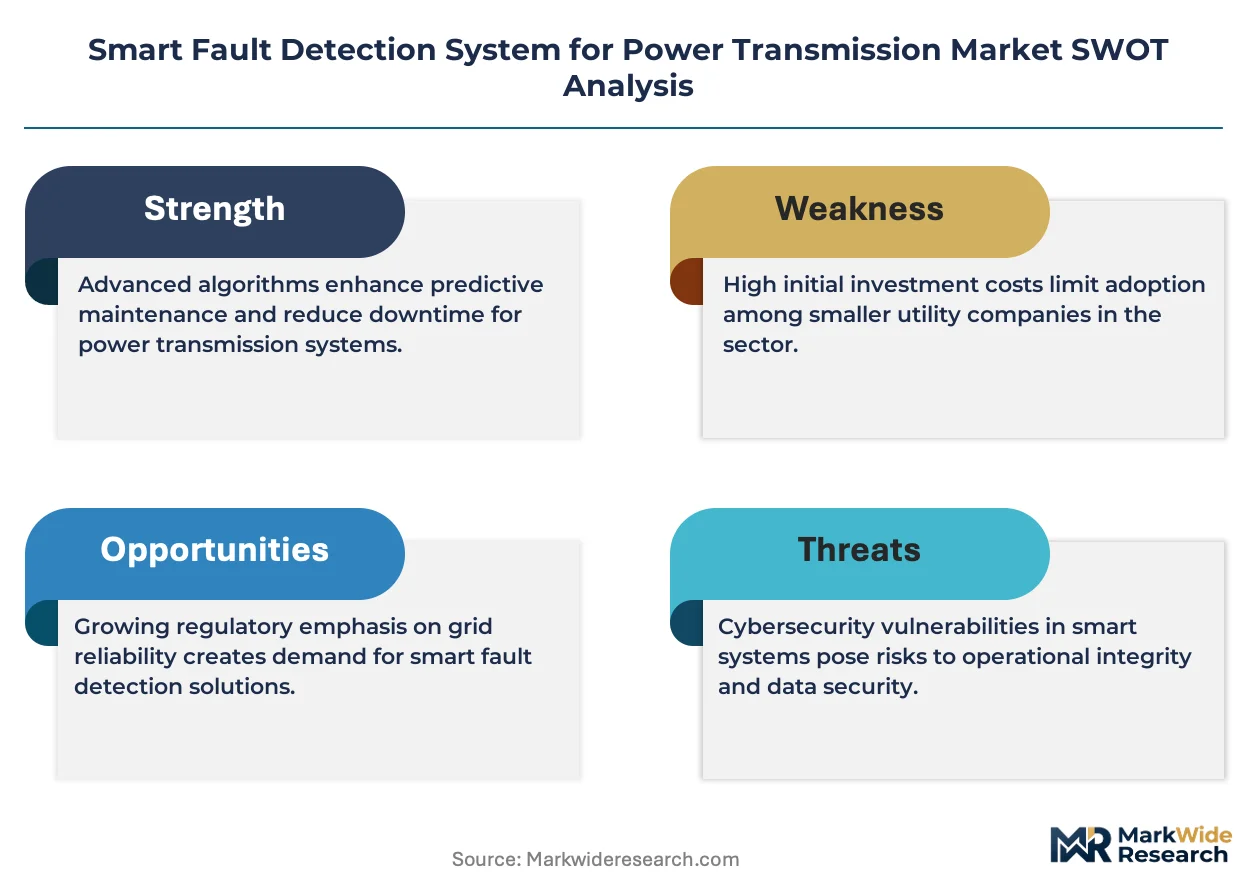
IEC 61850 compliance certification is unwinding the competitive landscape for grid automation suppliers, forcing smaller players into costly qualification cycles. Siemens leverages its deep substation automation portfolio to sustain engineering relationships with European transmission operators. ABB anchors its position through integrated protection and control systems that span protection relays to centralized analytics platforms.
A smart fault detection system for power transmission deploys synchronized phasor measurement units, traveling-wave sensors, and edge-computing nodes to identify insulation failures, conductor faults, and switching anomalies within sub-cycle timeframes. The technology serves to minimize outage duration, reduce equipment thermal stress, and enable condition-based asset replacement across high-voltage networks. Artificial Intelligence and Machine Learning segments attract the steepest R&D allocation as utilities demand autonomous fault classification without human-in-the-loop validation. Cloud-based Solutions occupy the fastest-expanding solution category, though On-premise Solutions retain preference among security-sensitive transmission operators in regulated markets.
FERC Order 693 in the United States mandates reliability standards that directly compel transmission owners to deploy advanced fault detection and disturbance monitoring equipment. IEC 61850 and IEEE C37.118 frameworks govern interoperability and synchrophasor data exchange, shaping product architecture decisions for vendors targeting multi-utility deployments. Stakeholders must weigh the pace of AI model regulatory acceptance against the operational risk of fully automated protection actions in meshed transmission topologies.
Market Dynamics
AI-driven autonomous protection actions are fragmenting engineering consensus across transmission operators, pitting reliability engineers against cybersecurity officers over unsupervised fault clearance protocols in meshed high-voltage networks.
Growth Catalysts
- FERC Order 693:United States transmission owners must deploy advanced disturbance monitoring equipment, creating procurement mandates for synchronized phasor measurement units and traveling-wave sensors.
- Distributed renewable integration:Germany's Energiewende acceleration forces grid operators to monitor bidirectional power flows, driving demand for sub-cycle fault detection across converter-interfaced generation clusters.
- Edge computing nodes:Real-time inference at substation level eliminates latency to centralized control centers, enabling autonomous islanding decisions during cascading failures.
Market Restraints
- Rare earth magnet supply concentration:Phasor measurement unit manufacturing depends on Chinese-processed neodymium, exposing procurement timelines to export quota volatility.
- IEC 61850 Edition 2.1 compliance costs:Smaller automation vendors face 18-24 month qualification cycles, consolidating supplier tiers around established substation integrators.
- Optical fiber sensor fragility:Distributed acoustic sensing cables suffer mechanical degradation in gall-prone transmission corridors, limiting deployment in high-wind zones.
Strategic Opportunities
- India's National Grid modernization:Power Grid Corporation of India seeks vendor partnerships for 765 kV line monitoring, creating entry points for AI-native fault classification platforms.
- Digital twin convergence:Integration of real-time fault detection with predictive asset models enables condition-based replacement of surge arresters and instrument transformers.
- Cloud-based analytics:European transmission system operators are piloting centralized pattern recognition across multiple control areas, reducing per-utility AI training costs.
Industry Challenges
- Protection engineer scarcity:Utilities in the United States and Germany report 40% vacancy rates in relay settings and coordination roles, delaying commissioning of multi-vendor protection schemes.
- Legacy relay interoperability:Electromechanical and static relays installed in the 1980s lack IEC 61850 communication stacks, forcing expensive parallel retrofit paths during upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Fault Detection System for Power Transmission Market |
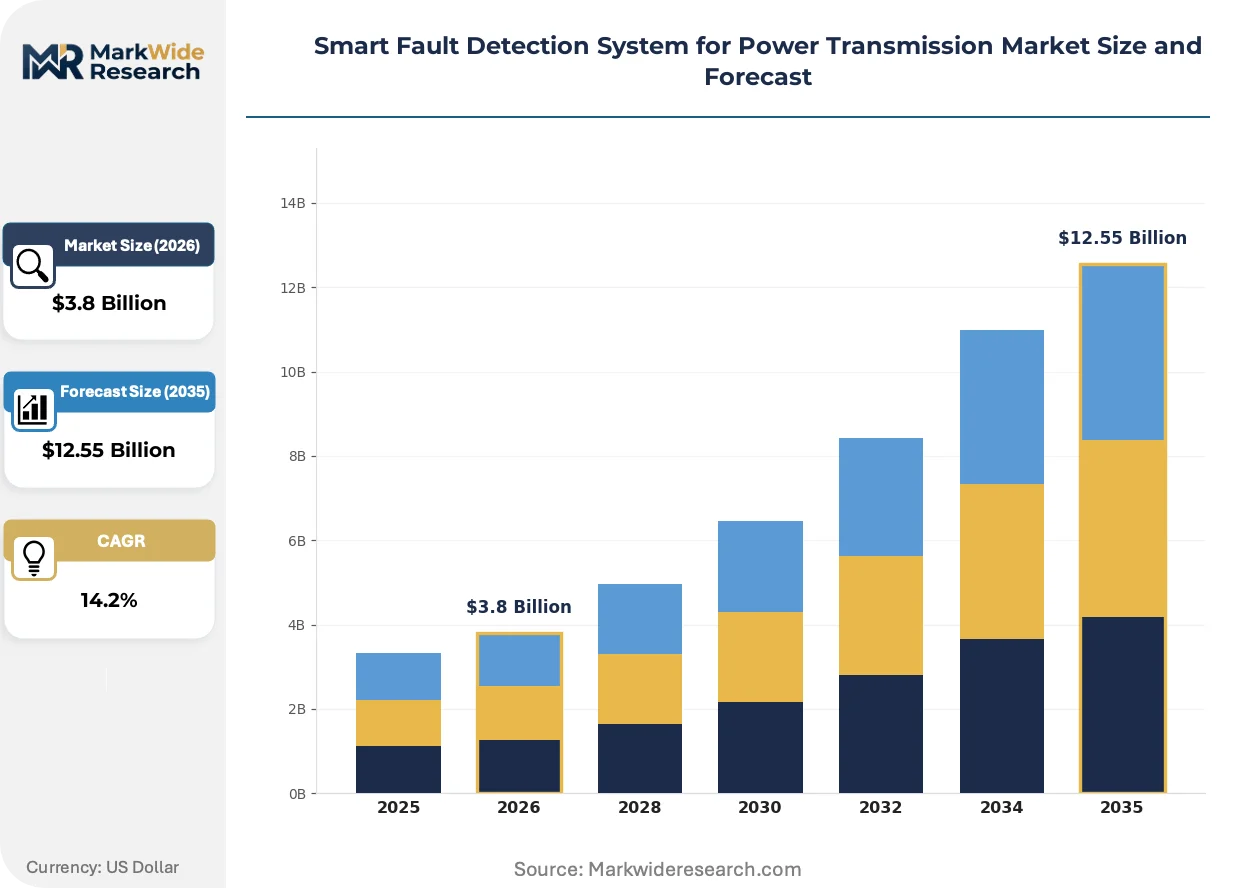
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Artificial Intelligence, Machine Learning, IoT, Sensor Technology End User: Utilities, Renewable Energy, Independent Power Producers, Transmission Operators Application: Asset Monitoring, Predictive Maintenance, Real-time Analysis, Remote Diagnostics Solution: Cloud-based Solutions, On-premise Solutions, Hybrid Solutions, Managed Services |
| Companies Covered | Schneider Electric, Siemens, ABB, General Electric, Eaton, Honeywell, Rockwell Automation, Emerson Electric, Schweitzer Engineering Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Fault Detection System for Power Transmission Market Evolving Landscape
Computational architectures for transmission fault detection are bifurcating between centralized cloud analytics and hardened edge inference, with procurement criteria increasingly weighted toward cybersecurity certification rather than raw detection speed.
Traveling-wave fault location algorithms are fragmenting vendor roadmaps as utilities demand sub-300-meter accuracy on mixed overhead-underground circuits. European transmission operators in Germany and the Netherlands are deploying these sensors on 380 kV corridors first, compressing competitive differentiation around sensor fusion techniques that combine electromagnetic time-of-arrival with distributed temperature data.
The EU Cybersecurity Act's critical infrastructure certification framework is mandating Common Criteria EAL4+ evaluation for protection and control systems sold into transmission networks. Siemens and ABB are rearchitecting product lines to achieve this baseline, while smaller specialists face 18-month evaluation timelines that freeze feature roadmaps. German TSOs are now requiring this certification in tender specifications, effectively filtering non-compliant vendors from large-scale framework agreements.
Subscription-based fault analytics are displacing perpetual license models among North American municipal utilities and cooperative transmission groups. These buyers lack capital budgets for on-premise AI infrastructure but require continuous model updates for evolving fault signatures. The shift is most visible in Texas and California, where independent system operator data-sharing agreements enable pooled training datasets that improve detection accuracy for uncommon switching transients.
Smart Fault Detection System for Power Transmission Market Segmentation
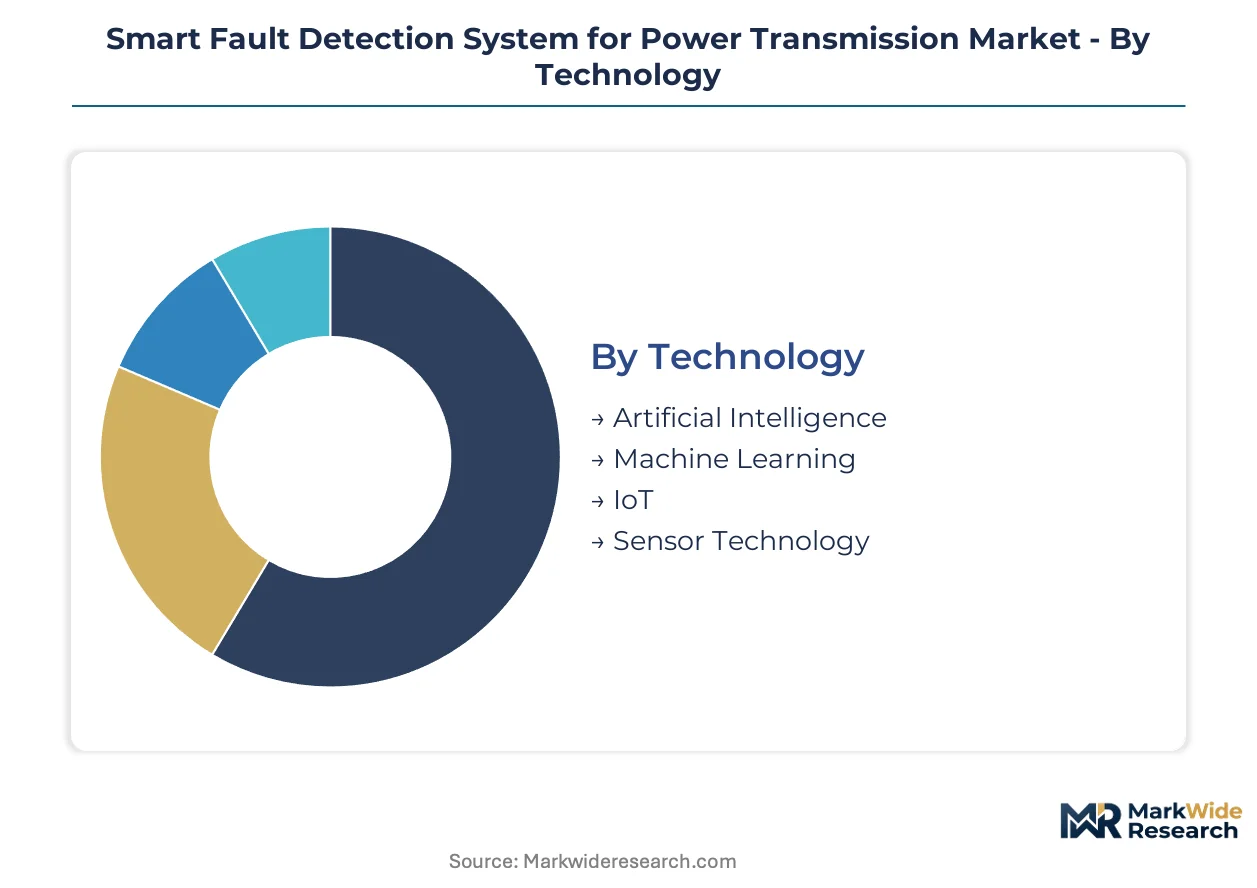
Segmentation in the smart fault detection market reflects divergent procurement philosophies across transmission operators. Regulatory mandates and cybersecurity certification requirements shape technology selection more than raw performance specifications.
Technology:
FERC Order 693 and IEC 61850 frameworks create tiered compliance burdens that favor certain architectures over others.
- Artificial Intelligence:Autonomous fault classification algorithms process synchrophasor streams without human validation loops. German transmission operators mandate these capabilities for 380 kV corridor monitoring under EU Cybersecurity Act critical infrastructure rules.
- Machine Learning:Pattern recognition models trained on historical disturbance records identify incipient insulation degradation. United States municipal utilities pool training datasets through independent system operator agreements to improve detection of uncommon switching transients.
- IoT:Sensor networks enable distributed monitoring across geographically dispersed substations.
- Sensor Technology:Traveling-wave and distributed acoustic sensing hardware provides sub-cycle fault location data.
Established volume favors Sensor Technology; emerging adoption favors Artificial Intelligence.
End User:
Capital intensity and regulatory exposure create distinct procurement rhythms across buyer categories.
- Utilities:Vertically integrated power companies deploy comprehensive fault detection platforms across generation, transmission, and distribution assets. These buyers face FERC Order 693 mandates requiring synchronized phasor measurement unit deployment on high-voltage networks.
- Transmission Operators:Grid-scale specialists prioritize IEC 61850 Edition 2.1 compliance to maintain interoperability across multi-vendor protection schemes. German TSOs now require Common Criteria EAL4+ certification in tender specifications.
- Renewable Energy:Wind and solar developers need converter-interfaced generation monitoring for bidirectional power flow detection.
- Independent Power Producers:Merchant generators seek cost-optimized fault detection for interconnection compliance.
Transmission Operators concentrate the steepest R&D allocation; Renewable Energy offers the steepest expansion trajectory.
Application:
Operational priorities shift detection system design toward either predictive or reactive capabilities.
- Real-time Analysis:Sub-cycle fault identification enables autonomous protection actions during cascading failures. Edge computing nodes at substation level eliminate latency to centralized control centers, satisfying requirements for meshed network islanding decisions.
- Predictive Maintenance:Condition-based asset replacement models forecast surge arrester and instrument transformer end-of-life. Integration with digital twin platforms allows European transmission system operators to optimize capital replacement schedules.
- Asset Monitoring:Continuous thermal and mechanical stress tracking supports long-term equipment health assessment.
- Remote Diagnostics:Centralized analytics platforms reduce per-utility AI training costs through pooled pattern recognition.
Real-time Analysis commands premium pricing; Predictive Maintenance is climbing the fastest.
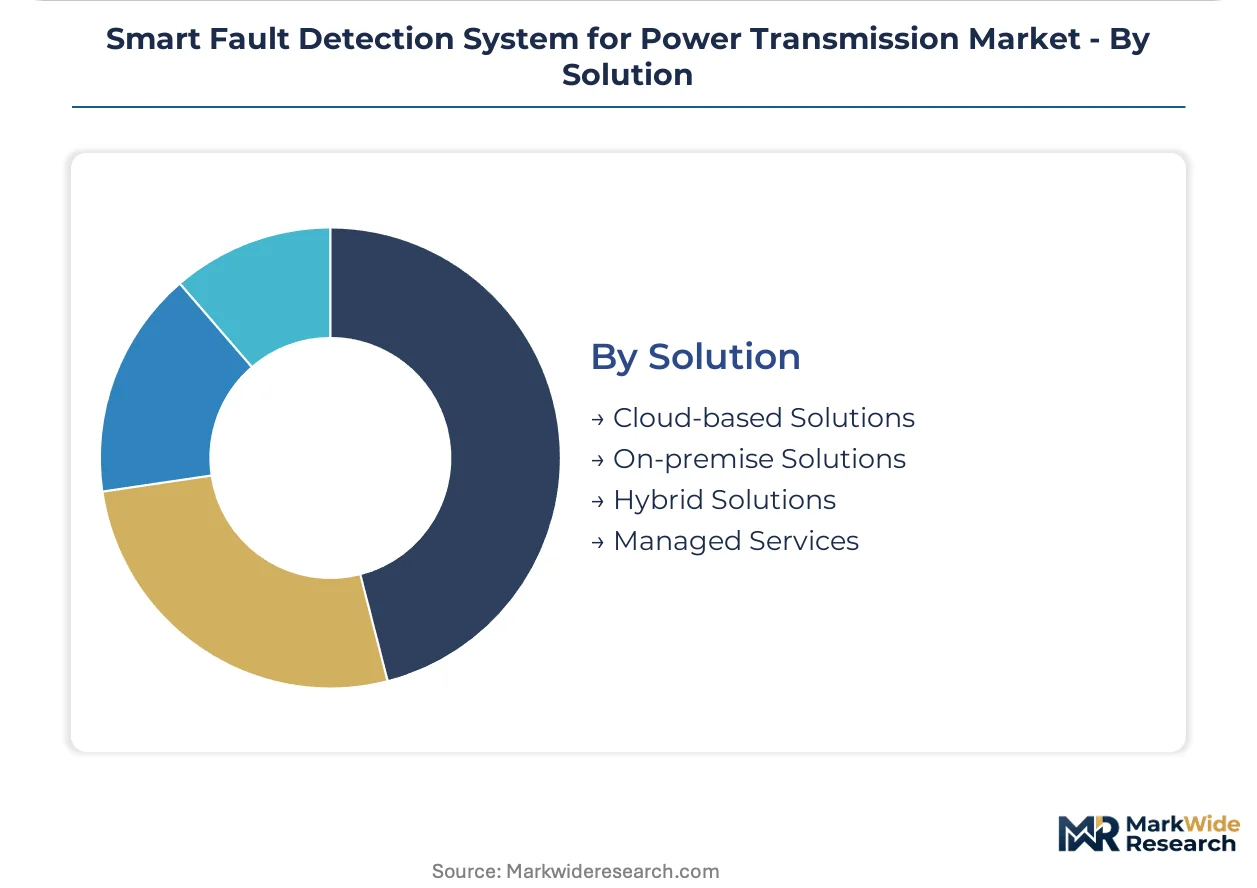
Solution:
Security sensitivity and capital availability fragment deployment models across buyer types.
- Cloud-based Solutions:Subscription analytics models displace perpetual licenses among capital-constrained buyers. Texas and California municipal utilities leverage these arrangements for continuous model updates without on-premise infrastructure investment.
- On-premise Solutions:Air-gapped systems retain preference among security-sensitive transmission operators in regulated markets. Common Criteria EAL4+ evaluation requirements extend procurement cycles but satisfy EU Cybersecurity Act mandates for critical infrastructure.
- Hybrid Solutions:Split architectures process sensitive protection data locally while pushing analytics to cloud environments.
- Managed Services:Outsourced monitoring and model maintenance addresses protection engineer scarcity in United States and German markets.
On-premise Solutions anchor regulated utility spending; Cloud-based Solutions are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FERC Order 693 mandates advanced disturbance monitoring equipment across United States transmission networks, while Germany's Energiewende acceleration and China's dual carbon goals create parallel procurement pressures for sub-cycle fault detection systems.
United States
Independent system operators in Texas and California pool training datasets for AI-native fault classification platforms. FERC Order 693 compels transmission owners to deploy synchronized phasor measurement units on high-voltage corridors. The Electric Reliability Council of Texas operates the most advanced edge-computing substation network for autonomous islanding decisions.
Germany
Transmission system operators monitor bidirectional power flows from converter-interfaced renewable clusters. The EU Cybersecurity Act mandates Common Criteria EAL4+ certification for protection systems, filtering non-compliant vendors from framework agreements. TenneT TSO deploys traveling-wave sensors across 380 kV corridors in Lower Saxony and North Rhine-Westphalia.
China
State Grid Corporation accelerates procurement of AI-driven protection platforms for ultra-high-voltage DC transmission lines. MIIT standards govern synchrophasor data exchange architectures for multi-vendor deployments. The Yangtze River Delta concentration of substation automation manufacturing supplies domestic and export markets.
India
Power Grid Corporation of India seeks vendor partnerships for 765 kV line monitoring and AI-native fault classification. CEA regulations mandate disturbance recording equipment on national grid interconnections. Maharashtra and Gujarat host the steepest deployment trajectories for renewable integration monitoring.
Japan
Tokyo Electric Power Company deploys edge-computing nodes for real-time inference during seismic events. METI guidelines shape interoperability requirements for protection system upgrades. The Kanto region concentrates demand for hybrid cloud-on-premise architectures in security-sensitive installations.
Smart Fault Detection System for Power Transmission Market Competitive Landscape
Listed leaders compete with private specialists across certification compliance and engineering relationship dimensions. The supplier base concentrates around established substation integrators capable of absorbing IEC 61850 Edition 2.1 qualification cycles. Three archetypes dominate: diversified industrial conglomerates with deep automation portfolios, pure-play protection specialists with relay engineering expertise, and AI-native software vendors seeking utility partnerships. Competitive moves center on cybersecurity certification achievement and strategic partnerships for digital twin convergence.
Within the diversified industrial tier, Siemens and ABB exemplify engineering relationship strategies with European transmission operators. Schneider Electric occupies a position bridging automation hardware and cloud-based analytics for capital-constrained municipal utilities. Schweitzer Engineering Laboratories anchors the protection specialist archetype with deep relay settings expertise in North American markets.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| ABB |
| General Electric |
| Eaton |
| Honeywell |
| Rockwell Automation |
| Emerson Electric |
| Schweitzer Engineering Laboratories |
| Others |
Value Network & Pricing Analysis
Silicon carbide power modules displacing silicon IGBTs in traveling-wave sensor architectures are redrawing procurement geography toward Chinese wafer foundries while compressing margins for European sensor integrators facing 30-40% component cost deltas. This substitution dynamic concentrates pricing power with semiconductor suppliers capable of qualifying automotive-grade SiC for grid applications, forcing fault detection system vendors to absorb upfront engineering costs or cede tier-one utility contracts to vertically integrated competitors.
Pricing Analysis
Certification level creates the primary spread between on-premise and cloud-based deployment tiers, with Common Criteria EAL4+ evaluation adding 18-24 month qualification premiums to hardware offerings. Three-tier pricing structure separates air-gapped substation systems from hybrid architectures and pure SaaS analytics, with municipal utilities in Texas and California exhibiting highest price sensitivity due to capital budget constraints. Cost compression in edge-computing node tiers is intensifying because Chinese manufacturers are flooding the substation automation component market with IEC 61850-compatible modules.
Supply Chain Analysis
Rare earth magnet processing in China underwrites 70% of global phasor measurement unit manufacturing capacity, creating single-source vulnerability for neodymium-dependent current sensors. German engineering houses and Japanese precision electronics suppliers anchor high-reliability sensor assembly, while South Korean memory semiconductor feeds edge-computing inference hardware. Distribution runs through authorized substation integrators rather than direct OEM relationships, with ABB, Siemens, and Schneider Electric controlling qualification gateways that determine vendor access to European transmission operator frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AI-native autonomous protection represents a high-growth disruption justified by FERC Order 693 procurement mandates compelling synchronized phasor measurement deployment across United States high-voltage corridors. Transmission operators now face binary technology transitions: retrofit legacy electromechanical protection or engineer greenfield AI-classification systems for meshed renewable integration.
For Market Incumbents: Fortify engineering relationships with European transmission system operators by accelerating Common Criteria EAL4+ certification timelines ahead of 2025 tender cycles. Deepen backward integration into SiC power module sourcing through partnerships with Chinese wafer foundries qualified for automotive-grade production. Prioritize digital twin convergence capabilities to defend against AI-native software vendors encroaching on predictive maintenance contracts.
For New Entrants and Emerging Players: Differentiate on sub-300-meter fault location accuracy for mixed overhead-underground circuits, a specification gap European TSOs are now writing into 380 kV corridor tenders. Target India's 765 kV National Grid modernization as the most penetrable geography, where Power Grid Corporation of India actively seeks vendor partnerships for AI-native classification platforms. Pursue subscription-based managed service models to bypass capital expenditure barriers among United States municipal utilities.
For Investors and Strategic Acquirers: EU Cybersecurity Act EAL4+ mandates reshape the acquisition landscape by filtering non-compliant vendors from German TSO framework agreements, concentrating deal flow around certified protection specialists. Long-term viability favors suppliers with demonstrated utility engineering relationships spanning relay settings through centralized analytics. Monitor IEC 61850 Edition 3.0 draft circulation as the signal indicating qualification cycle reset and potential vendor tier consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Acceleration | Common Criteria EAL4+ achievement unlocks German TSO framework agreement eligibility before 2025 tender windows. |
| Digital Twin Platform Integration | Real-time fault detection convergence with predictive asset models enables condition-based replacement scheduling for European operators. |
| Edge Computing Node Localization | Substation-level inference eliminates latency to control centers, satisfying autonomous islanding requirements in Texas ERCOT networks. |
| Cloud Analytics Partnership Structure | Subscription models displace perpetual licenses among capital-constrained North American municipal utilities and cooperatives. |
| Traveling-Wave Sensor Fusion Development | Electromagnetic time-of-arrival combined with distributed temperature data compresses competitive differentiation on 380 kV corridors. |
Research Methodology
Initial hypotheses were tested against primary input from transmission planning officers, protection relay engineers, grid cybersecurity specialists, and substation automation procurement leads and refined through secondary validation against FERC Order 693 implementation filings, IEC 61850 conformance test records, EU Cybersecurity Act certification databases, and independent system operator data-sharing agreements. Bottom-up equipment deployment estimates triangulated against top-down utility capital expenditure disclosures.
Variance decomposition across technology, end-user, application, and solution segments anchored the analytical framework, with CAGRs derived from installed base growth rates and replacement cycle acceleration for electromechanical relay retirements. Modeled inputs included renewable integration penetration curves, rare earth magnet supply quota volatility, and protection engineer vacancy rates across United States and German markets.
Material uncertainties — rare earth export restrictions, IEC 61850 Edition 3.0 timeline revisions, and AI model regulatory acceptance pacing — sit outside the modeled envelope. Forecasts reflect documented assumptions about standard adoption trajectories and certification backlog clearance. Practitioners should keep alternative scenarios live as Chinese semiconductor self-sufficiency targets and European critical raw materials legislation evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
US Electricity Transmission and Distribution Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Underground Cabling EPC Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Water Storage System Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Electrical Transmission Azimuth Thruster Market
Transmission and Distribution
Transmission Line Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Canada High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
Southeast Asia Power Transmission and Distribution Market
Transmission and Distribution
Germany High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Modular Sub-Station Market
Transmission and Distribution
Gas Insulated Transmission Lines Market