
 Australia High Voltage Direct Current (HVDC) Transmission Systems Market | 2026-2036
Australia High Voltage Direct Current (HVDC) Transmission Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Australia High Voltage Direct Current (HVDC) Transmission Systems Market Outlook
The Clean Energy Finance Corporation's expanded mandate is recalibrating the capital structure for HVDC projects across Australia's National Electricity Market. ABB Ltd leverages its voltage source converter expertise to anchor tender positions for offshore interconnector developments. Siemens Energy competes through integrated system offerings that bundle converter stations with submarine cable packages. Hitachi Energy differentiates via its hybrid system portfolio designed for asynchronous grid links between Tasmania and the mainland.
High Voltage Direct Current transmission systems employ power electronic converters to transmit bulk electricity across distances exceeding conventional alternating current economic thresholds, typically operating at voltages above 100 kV with line-commutated or self-commutated converter topologies. These systems primarily enable long-distance power transfer with lower losses and facilitate asynchronous grid interconnection between regions with incompatible frequencies. Voltage source converter technology leads deployment for offshore wind integration due to its black-start capability and compact footprint. Underground installation types command premium positioning in environmentally sensitive corridors where overhead routing faces planning constraints. Renewable energy providers represent the fastest-growing end user category as developers seek firm export pathways for remote generation assets.
The Australian Energy Market Operator and the Clean Energy Regulator jointly shape HVDC investment timelines through integrated system plan mandates and renewable energy target compliance pathways. Standards Australia and the International Electrotechnical Commission define equipment certification requirements that filter market access for converter and cable suppliers. Stakeholders must monitor the pace of the Australian Renewable Energy Agency's funding rounds to time participation in emerging interconnector procurement cycles.
Market Dynamics
The Australian Energy Market Commission's grid connection standard revisions are compressing procurement timelines for converter station equipment, forcing renewable developers to pre-position capital before final regulatory clearance.
Growth Catalysts
- Integrated System Plan mandates:The Australian Energy Market Operator's pathway requirements are binding transmission planners to HVDC corridors for offshore wind export, creating guaranteed demand visibility for converter station suppliers.
- Queensland renewable zones:State-level renewable energy target compliance pathways are accelerating procurement of asynchronous link technology to connect remote solar and wind assets to the National Electricity Market.
- Voltage source converter maturation:Black-start capability and compact substation footprints are electrifying developer preference for self-commutated topologies over line-commutated alternatives in Bass Strait interconnector planning.
Market Restraints
- Submarine cable supply concentration:European and Japanese cable manufacturers control specialized HVDC subsea manufacturing capacity, exposing Australian projects to 18-24 month lead time volatility.
- Copper and rare earth input costs:Converter station power electronic stacks depend on dysprosium and terbium supplies concentrated in Chinese processing facilities, creating procurement cost uncertainty.
- Standards Australia certification friction:Equipment approval pathways for IEC 62501-compliant converter valves impose 12-18 month pre-commissioning delays that compress project IRRs.
Strategic Opportunities
- Tasmania-mainland asynchronous links:Hybrid HVDC-LCC systems for Bass Strait interconnection represent underpenetrated demand for vendors with legacy thyristor and modern VSC integration expertise.
- Clean Energy Finance Corporation mandate expansion:Debt and equity instruments now explicitly cover transmission infrastructure, lowering cost of capital for merchant interconnectors.
- Underground corridor premium positioning:Environmentally sensitive routing through the Great Dividing Range is electrifying demand for XLPE-insulated cable systems over overhead lines in Victorian renewable export zones.
Industry Challenges
- Power electronics specialist scarcity:Converter control system engineering talent pools in Australia remain shallow relative to project pipeline scale, forcing reliance on fly-in-fly-out commissioning teams from European suppliers.
- Multi-vendor integration complexity:Asynchronous grid links require harmonizing protection schemes between legacy synchronous generators in Tasmania and inverter-based resources on the mainland, stretching system integration timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia High Voltage Direct Current (HVDC) Transmission Systems Market |
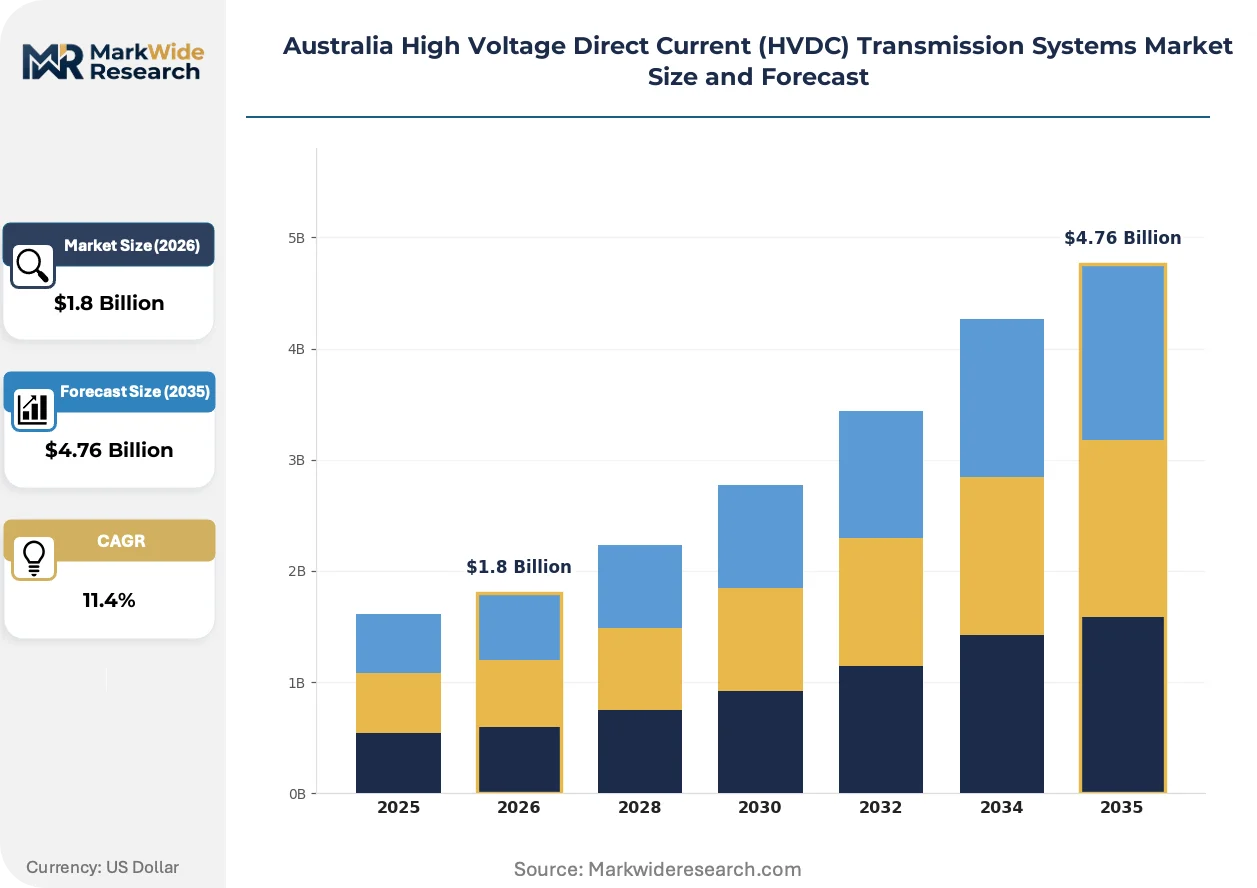
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Voltage Source Converter, Current Source Converter, Hybrid Systems, Integrated Systems End User: Utilities, Industrial Developers, Renewable Energy Providers, Government Agencies Installation Type: Onshore, Offshore, Underground, Overhead Application: Grid Interconnection, Long-Distance Transmission, Renewable Integration, Energy Trading |
| Companies Covered | ABB Ltd, Siemens AG, General Electric Company, Mitsubishi Electric Corporation, Toshiba Corporation, Hitachi Energy, Siemens Energy, Prysmian SpA, NKT A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia High Voltage Direct Current (HVDC) Transmission Systems Market Strategic Shifts
Modular converter station architectures are compressing deployment timelines for remote renewable export projects across Australia's eastern seaboard. Three developments are restructuring supplier positioning and procurement patterns.
Modular multilevel converter technology is electrifying offshore wind integration economics. The topology eliminates AC filters and reduces transformer footprint by half compared to two-level VSC designs. Developers in the Gippsland offshore zone are specifying MMC-based collector platforms to minimize seabed foundation mass. This electrifying platform standardization is forcing incumbent suppliers to retool manufacturing lines or cede tender positions to Asian competitors with mature MMC supply chains.
The Australian Renewable Energy Agency's funding round sequencing is compressing interconnector procurement cycles. Grant milestone requirements bind developers to converter station supply agreements before final investment decision, transferring equipment selection risk earlier in project development. Victorian and Queensland proponents are responding by pre-qualifying dual-source converter suppliers to maintain negotiating leverage against compressed timelines.
Buyer consortium structures are displacing single-asset procurement for Bass Strait interconnectors. Renewable developers, state transmission utilities, and offshore wind leaseholders are forming special purpose vehicles to aggregate converter station orders and capture volume pricing. This aggregation behavior is most visible in the Star of the South project cluster, where shared converter platforms are being negotiated across multiple offtake agreements rather than asset-by-asset contracting.
Australia High Voltage Direct Current (HVDC) Transmission Systems Market Segmentation
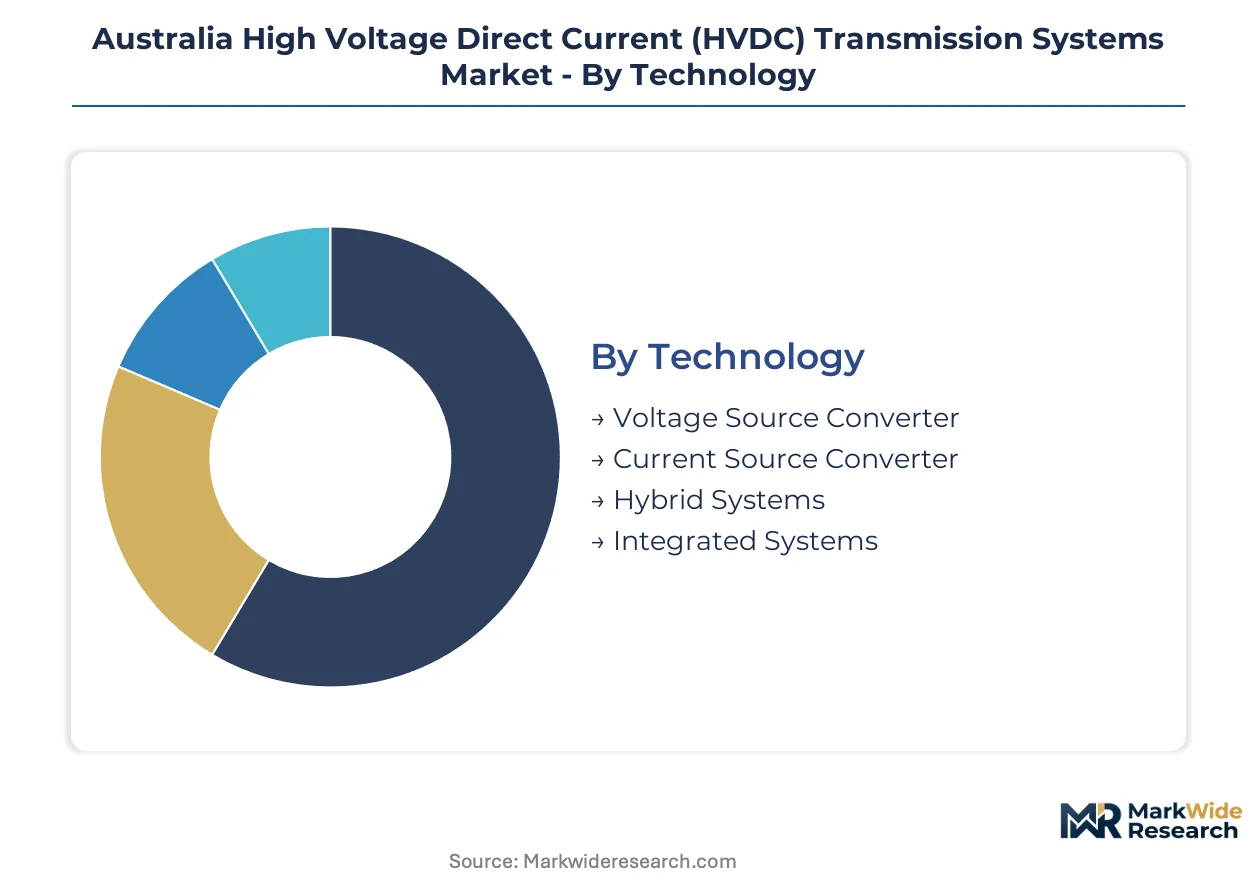
Technology choices in Australia's HVDC market determine project economics and regulatory compliance. Converter topology selection shapes capital allocation across the National Electricity Market's offshore wind corridors and Bass Strait interconnectors.
Technology:
Voltage source converters command premium positioning while current source alternatives anchor volume deployment in legacy infrastructure.
- Voltage Source Converter:Self-commutated topology employing insulated-gate bipolar transistors enables black-start capability and compact substation footprints. Demand concentrates in Gippsland offshore wind zones where Australian Energy Market Operator mandates require grid-forming inverters for weak network connections.
- Current Source Converter:Line-commutated thyristor-based systems dominate established Bass Strait links between Tasmania and Victoria. Procurement from Powerlink Queensland and TasNetworks favors this mature technology for high-capacity bulk transfer where synchronous inertia support is prioritized over voltage control flexibility.
- Hybrid Systems:Combined LCC-VSC architectures address asymmetric grid strength between Tasmania's hydro-dominated system and mainland inverter-based resources.
- Integrated Systems:Factory-assembled converter platforms with pre-commissioned control systems compress site installation timelines for remote Queensland renewable export projects.
Mature deployment sits with Current Source Converter. Newer deployment is concentrated in Voltage Source Converter.
End User:
Utility procurement patterns diverge from merchant developer timelines across the Australian Energy Market Commission's revised connection standards.
- Utilities:State-owned transmission network service providers including TransGrid, AusNet Services, and ElectraNet anchor baseline demand through regulated asset base mechanisms. Their procurement cycles align with Integrated System Plan staging, creating predictable converter station order pipelines for Bass Strait and Queensland renewable zone interconnectors.
- Renewable Energy Providers:Offshore wind leaseholders in the Bass Strait and solar developers in Queensland's Fitzroy and Northern Queensland renewable energy zones are expanding most quickly. Clean Energy Finance Corporation debt facilities now explicitly cover transmission infrastructure, lowering cost of capital for merchant interconnectors serving these generators.
- Industrial Developers:Mining and smelting operations in Western Australia's Pilbara region pursue private HVDC links to remote renewable generation.
- Government Agencies:Australian Renewable Energy Agency grant milestones bind public-sector proponents to accelerated equipment selection timelines.
Procurement scale favors Utilities. Procurement velocity is climbing fastest among Renewable Energy Providers.
Installation Type:
Submarine cable routing through the Bass Strait drives cost differentiation between seabed and terrestrial corridors.
- Offshore:Submarine cable systems with XLPE or mass-impregnated insulation connect Gippsland offshore wind arrays to mainland substations. European and Japanese cable manufacturers control specialized manufacturing capacity, exposing Star of the South and other projects to 18-24 month lead time volatility.
- Underground:XLPE-insulated land cable systems command premium positioning through environmentally sensitive corridors in the Great Dividing Range where Victorian planning constraints block overhead routing. This installation type is gaining share fastest as renewable export zones face community opposition to transmission towers.
- Onshore:Converter stations and terrestrial cable terminations concentrate in existing transmission hubs including Loy Yang and Bulwer Island.
- Overhead:Traditional tower-based transmission retains cost advantage in Queensland's sparse interior renewable zones.
Established capacity sits with Overhead. Regulatory and community pressure is shifting new deployment toward Underground.
Application:
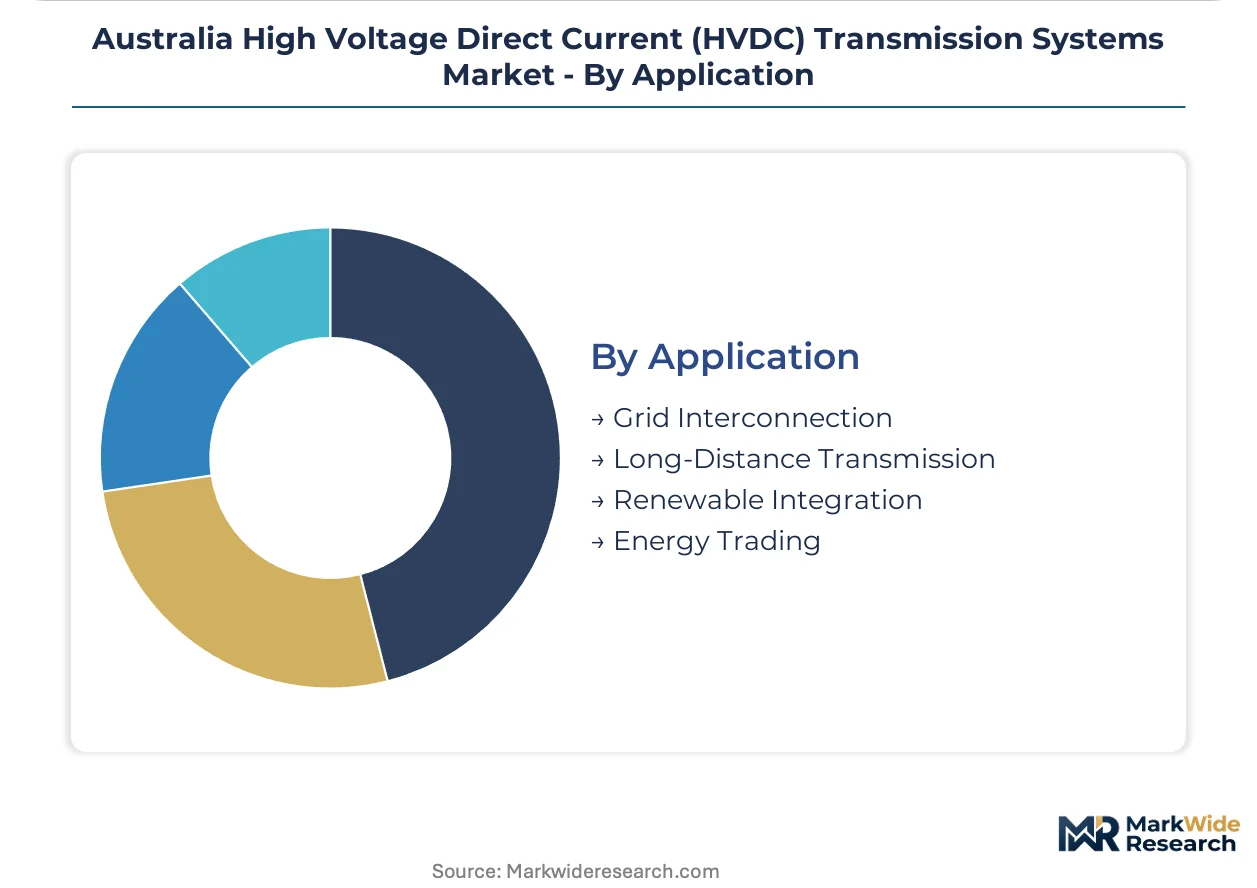
Grid interconnection mandates from the Australian Energy Market Operator create guaranteed demand visibility distinct from merchant energy trading economics.
- Grid Interconnection:Asynchronous links between Tasmania and mainland NEM regions require HVDC to bridge frequency and stability differences. The Marinus Link and Basslink 2 proposals anchor procurement demand for bi-directional converter stations with synchronous condenser support.
- Renewable Integration:Remote solar and wind assets in Queensland's Northern and Central renewable energy zones need firm export pathways. This application is expanding most quickly as state renewable energy target compliance pathways accelerate procurement timelines.
- Long-Distance Transmission:Bulk transfer beyond 600 kilometers where AC losses exceed HVDC converter station capital costs.
- Energy Trading:Merchant interconnectors enabling arbitrage between Queensland and Victorian price zones.
Regulatory certainty concentrates deployment in Grid Interconnection. Developer interest is surging fastest in Renewable Integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The National Electricity Market's renewable energy zones function as de facto special economic zones, concentrating converter station procurement in Queensland and Victoria corridors.
New South Wales
Transmission network service provider TransGrid anchors demand through regulated asset base mechanisms aligned with Integrated System Plan staging. The Australian Energy Market Operator's pathway requirements bind planners to HVDC corridors for remote renewable export. The Central-West Orana Renewable Energy Zone concentrates procurement activity for asynchronous link technology connecting solar assets to Sydney load centers.
Victoria
Offshore wind leaseholders in the Gippsland zone accelerate procurement of voltage source converter platforms with black-start capability. The Clean Energy Finance Corporation's expanded mandate now explicitly covers transmission infrastructure, lowering cost of capital for merchant interconnectors. The Star of the South project cluster drives shared converter platform negotiations across multiple offtake agreements.
Queensland
State-owned Powerlink Queensland favors current source converter systems for high-capacity bulk transfer from Fitzroy and Northern Queensland renewable energy zones. State-level renewable energy target compliance pathways compress procurement timelines for converter station equipment. The Northern Queensland Clean Energy Hub concentrates demand for underground XLPE-insulated cable systems through environmentally sensitive Great Dividing Range corridors.
Tasmania
Hydro Tasmania's dominance creates asymmetric grid strength requiring hybrid HVDC-LCC architectures for Bass Strait interconnection. The Marinus Link and Basslink 2 proposals anchor bi-directional converter station demand with synchronous condenser support. State transmission utility TasNetworks coordinates procurement with Victorian counterparts through special purpose vehicle structures.
Western Australia
Mining and smelting operations in the Pilbara region pursue private HVDC links to remote renewable generation outside the National Electricity Market. The Australian Renewable Energy Agency's funding rounds bind developers to accelerated equipment selection timelines. The Pilbara Energy Hub concentrates industrial developer interest in merchant interconnectors serving iron ore and lithium processing loads.
Australia High Voltage Direct Current (HVDC) Transmission Systems Market Competitive Environment
European producers anchor one tier; Japanese specialists hold established positions in submarine cable manufacturing. The vendor base concentrates around converter station integrators and cable specialists, with tiering between full-system providers and component-focused suppliers. Three archetypes dominate: integrated system bundlers, voltage source converter technology specialists, and submarine cable manufacturers. Capacity expansion and strategic partnerships represent the dominant competitive moves as project pipelines compress procurement cycles.
Within the integrated system tier, ABB Ltd and Siemens Energy exemplify full-service positioning, while Hitachi Energy occupies a specialist role in hybrid system architectures. Among European cable fabricators, Prysmian SpA and NKT A/S represent the concentrated supply base for subsea manufacturing capacity. These named entities anchor competitive dynamics without exhaustively mapping participant strategies.
| Leading Market Players |
|---|
| ABB Ltd |
| Siemens AG |
| General Electric Company |
| Mitsubishi Electric Corporation |
| Toshiba Corporation |
| Hitachi Energy |
| Siemens Energy |
| Prysmian SpA |
| NKT A/S |
| Others |
Value Chain & Pricing Dynamics
London Metal Exchange copper futures and Chinese rare earth export quotas cascade through Australian HVDC converter station procurement, compressing margins for European power electronics suppliers while elevating pricing premiums for Japanese cable manufacturers with captive material hedges.
Pricing Analysis
Lead-time-driven pricing stratification separates urgent converter station orders from scheduled procurement cycles. Project developers facing Australian Energy Market Commission connection deadlines absorb 15-25% premiums for sub-12-month delivery slots against standard 24-month timelines. Three-tier pricing structure across premium expedited, standard scheduled, and economy spot-inventory levels reflects dysprosium and terbium cost pass-through volatility from Chinese processing facilities. Price differentiation hinges on IEC 62501 certification tier and bundled commissioning support. Renewable energy providers exhibit highest price sensitivity due to merchant interconnector economics, while state-owned utilities anchor volume at negotiated contract rates.
Supply Chain Analysis
Direct-to-utility channels handle regulated asset base procurement for TransGrid and Powerlink Queensland, while project-specific EPC bundles serve merchant offshore wind developers. Geographic supply concentration centers on Germany and Switzerland for converter valve manufacturing, Japan and Italy for submarine cable fabrication, and China for rare earth processing and power semiconductor substrates. Raw material dependencies encompass copper cathode, XLPE insulation compound, and IGBT modules. Single-source vulnerability in subsea cable manufacturing exposes Australian projects to European capacity allocation decisions. Distribution runs through tier-one system integrators for complex Bass Strait interconnectors and direct OEM relationships for standardized Queensland renewable zone links.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around vendors with integrated converter-cable capabilities as procurement timeline compression from Australian Renewable Energy Agency grant milestones squeezes out pure-play component suppliers lacking project execution bandwidth.
For Market Incumbents: Hedge against rare earth supply disruption through long-term offtake agreements with Australian critical minerals developers rather than spot-market exposure. Anchor converter station margins by backward integration into power semiconductor module sourcing, countering Chinese processing facility pricing power. Defensive positioning requires pre-qualifying dual-source cable suppliers to mitigate European manufacturing concentration risk. For New Entrants and Emerging Players: Industrial offtakers in Western Australia's Pilbara region represent an underserved buyer archetype seeking private HVDC links outside National Electricity Market regulatory frameworks. Hybrid LCC-VSC system integration for Tasmania-mainland asynchronous links offers the most penetrable technology segment where European incumbents lack specialized deployment experience. Go-to-market execution should leverage Australian Renewable Energy Agency funding round timing to embed equipment selection before incumbent pre-qualification deadlines. For Investors and Strategic Acquirers: Distressed-cycle entries favor converter control system engineering boutiques in Melbourne and Sydney facing talent scarcity pressure from project pipeline scale. Long-term viability across the projection horizon rests on positioning for Marinus Link and Basslink 2 procurement waves rather than merchant interconnector merchant risk. Watch Australian Energy Market Operator Integrated System Plan revision timing as the inflection signal for capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Converter Station Capacity Expansion | ABB Ltd and Siemens Energy are scaling Australian engineering presence to capture Marinus Link procurement cycles. |
| Submarine Cable Supply Agreement | Prysmian SpA and NKT A/S are locking multi-project volume commitments across Star of the South cluster developments. |
| Hybrid System Technology Licensing | Hitachi Energy is transferring LCC-VSC integration IP to local partners for Tasmania-mainland link execution. |
| Backward Integration into Rare Earth Sourcing | Converter station suppliers are offtaking Australian critical minerals to reduce Chinese processing dependency. |
| Modular Platform Standardization | Factory-assembled converter platforms compress site installation timelines for Queensland renewable export projects. |
Study Parameters
Independent corroboration across Australian Energy Market Operator Integrated System Plan documentation, Clean Energy Finance Corporation investment mandate disclosures, and Standards Australia certification registers underwrites the qualitative findings. Primary interviews with utility planning officers at TransGrid and Powerlink Queensland, IPP project developers in Gippsland and Fitzroy renewable zones, EPC contractors specializing in submarine cable installation, and grid operators managing Tasmania-mainland interconnection were synthesized with secondary validation. Bottom-up project pipeline aggregation triangulates against top-down regulatory mandate analysis.
Rate-of-change decomposition across the modeling period isolates technology substitution effects, regulatory timeline compression, and raw material cost pass-through. Segmentation dimensions encompass converter topology, end-user procurement archetype, installation type, and application purpose. CAGRs derive from equipment order visibility windows and commissioning schedule probability weighting. Forecast inputs incorporate Australian Renewable Energy Agency funding round sequencing and copper futures curve trajectory.
Revisions become necessary when submarine cable manufacturing capacity allocation shifts, Chinese rare earth export quota policy changes, or Australian Energy Market Commission grid connection standard timelines extend materialize. Forecasts reflect documented assumptions regarding project financing closure rates and equipment supplier delivery performance. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Pipeline Services Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Surge Tank Market
Transmission and Distribution
High Voltage Transmission Substation Market
Transmission and Distribution
United Kingdom High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Middle-East and Africa DC Distribution Networks Market
Transmission and Distribution
Africa High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Transmission and Distribution Equipment Market
Transmission and Distribution
Global Overhead Line Conductors Market
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Heat Interface Unit Market
Transmission and Distribution
Series Compensation System Sales Market
Transmission and Distribution
Global Load Break Switch Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market