
 LNG Infrastructure Market | 2026-2036
LNG Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
LNG Infrastructure Market Outlook
Long-term tolling and maintenance service contracts are restructuring how LNG infrastructure returns get captured across project lifecycles. Cheniere Energy leverages its tolling model to lock in revenue visibility regardless of commodity swings. Bechtel Corporation anchors global EPC execution capacity with a backlog concentrated in Gulf Coast and Middle East megaprojects. Shell plc differentiates through integrated shipping-to-regasification asset control spanning multiple continents.
LNG infrastructure encompasses the physical systems for natural gas liquefaction, cryogenic storage, marine transport, and regasification, typically operating at temperatures below minus 162 degrees Celsius to reduce gas volume by roughly 600 times for efficient intercontinental shipment. Its primary commercial purpose is to bridge geographically separated gas supply basins and demand centers where pipeline economics fail. Liquefaction terminals command the dominant share of capital deployment and margin capture given their front-loaded engineering intensity and long construction timelines. Floating LNG technology represents the fastest-expanding segment as it unlocks stranded offshore reserves without requiring onshore land acquisition or permanent coastal footprint. Distribution networks remain the most mature element with established tariff frameworks but face pressure to integrate digital monitoring for leak detection and throughput optimization.
The U.S. Federal Energy Regulatory Commission governs siting and environmental review for export terminals, while the EU F-Gas Regulation and REACH framework constrain allowable methane leakage rates and equipment fluorinated gas content for European-connected assets. Japan's METI sets import quality specifications that shape liquefaction train design standards across supplier countries. Stakeholders must weigh regulatory compliance timelines against construction lead times when committing capital to multi-decade infrastructure positions.
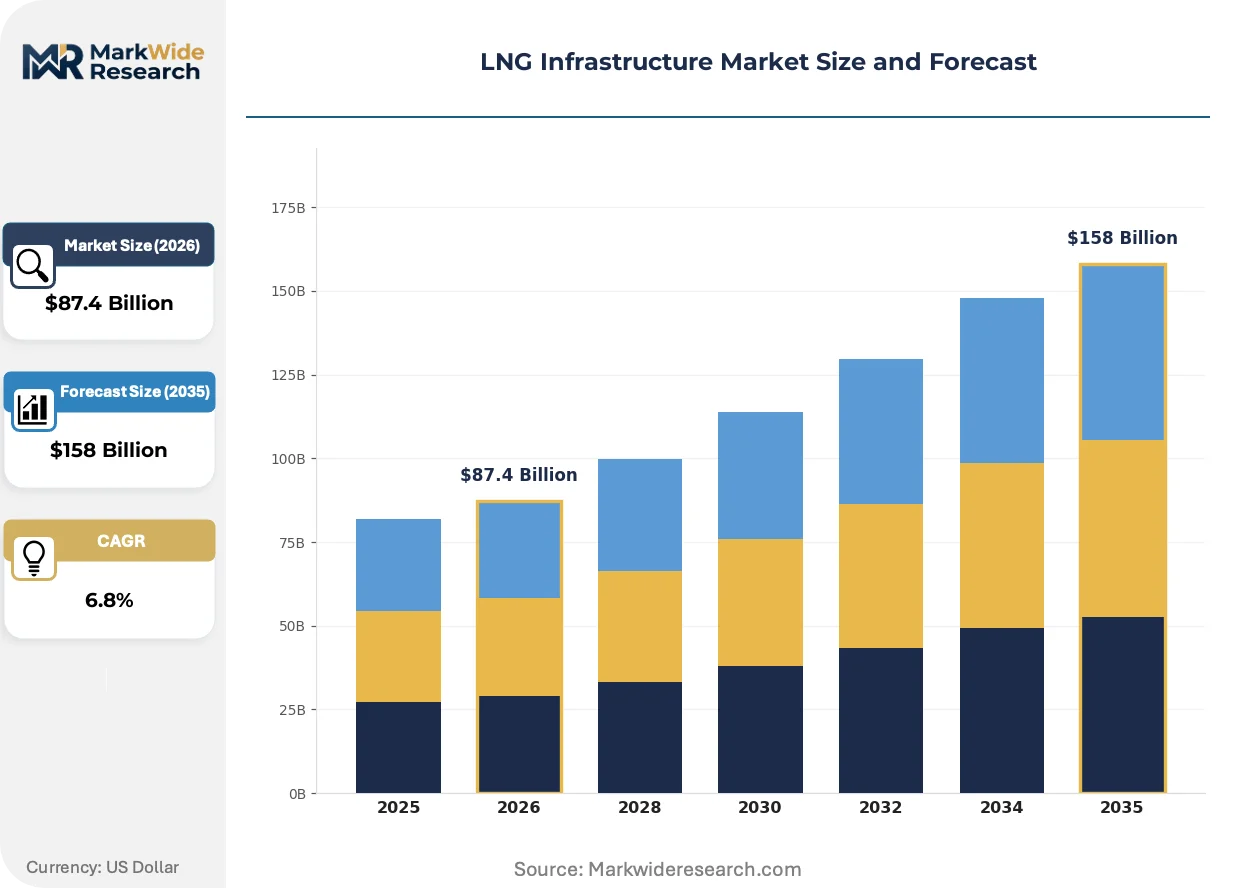
Market Dynamics
Capital commitments to liquefaction capacity are concentrating among Qatar, the United States, and Australia as these nations expand export terminal networks to serve Asian power utilities. This supply-side clustering is reshaping contracting structures and forcing buyers to secure long-term offtake earlier in project development cycles.
Growth Catalysts
- EU F-Gas Regulation:Tightening methane leakage standards are accelerating technology shifts toward lower-carbon liquefaction processes across European-connected assets.
- Power generation utilities:Baseload electricity providers are expanding long-term offtake agreements to secure supply certainty amid pipeline delivery constraints.
- Floating LNG:Offshore liquefaction technology unlocks stranded reserves without coastal land acquisition, opening new supply basins in remote maritime territories.
Market Restraints
- Specialized cryogenic steel alloys:Input cost volatility for nickel and molybdenum-intensive materials constrains fabrication scheduling and project economics.
- Qatari supply dominance:Concentration of megaproject execution capacity with select EPC consortia creates bottleneck risk for simultaneous global expansion waves.
- Carbon capture integration complexity:Technical limitations in scaling post-combustion capture for existing liquefaction trains delay emissions reduction timelines.
Strategic Opportunities
- Vietnam and Bangladesh:Underpenetrated demand centers with rising gas-fired power capacity targets offer first-mover terminal development positions.
- Small-scale LNG:Emerging bunkering and industrial feedstock applications create distributed demand nodes beyond traditional utility offtake.
- Japan METI quality specifications:Regulatory tailwind for integrated shipping-to-regasification asset control as buyers prioritize delivery reliability.
Industry Challenges
- Cryogenic welding certification:Scarcity of qualified technicians for minus 162 degrees Celsius system fabrication extends construction timelines.
- Multi-train integration:Complexity of synchronizing modular liquefaction units with shared utilities and storage creates commissioning risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LNG Infrastructure Market |
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Regasification Terminals, Liquefaction Terminals, Storage Tanks, Distribution Networks End User: Power Generation, Industrial, Residential, Transportation Technology: Cryogenic Technology, Floating LNG, Land-Based LNG, Recompression Technology Service Type: Consultation Services, Engineering Services, Maintenance Services, Operational Services |
| Companies Covered | Cheniere Energy, Bechtel Corporation, Sempra Energy, ExxonMobil, Chevron Corporation, Shell plc, Gazprom, Novatek, JGC Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LNG Infrastructure Market Strategic Shifts
Digital instrumentation and modular construction methods are compressing project timelines while tightening emissions accountability across the LNG value chain. These shifts are altering how infrastructure returns get captured and how operators maintain asset integrity over multi-decade operating lives.
Modular liquefaction trains using standardized skid-mounted components are expanding into remote and environmentally constrained development sites. Arctic operators and offshore project sponsors are adopting these systems to reduce on-site construction labor and accelerate production ramp. This approach is expanding into markets where conventional stick-built terminals face permitting delays or seasonal construction windows.
The EU F-Gas Regulation and REACH framework are imposing binding methane leakage rate ceilings and fluorinated gas equipment restrictions on European-connected LNG assets. Industrial consequence includes mandatory retrofit timelines for existing regasification terminals and revised procurement specifications for new liquefaction capacity. Mediterranean and North Sea import facilities are responding by integrating continuous emissions monitoring and switching to lower-global-warming-potential refrigerant blends.
Asian power utilities are consolidating procurement authority into centralized fuel management offices, displacing fragmented subsidiary-level contracting. This concentration is compressing supplier negotiation cycles and favoring integrated service providers offering shipping-to-delivery bundles. The shift is most visible in Japan and South Korea, where METI and KOGAS frameworks encourage long-term partnership structures over spot market participation.
LNG Infrastructure Market Segmentation
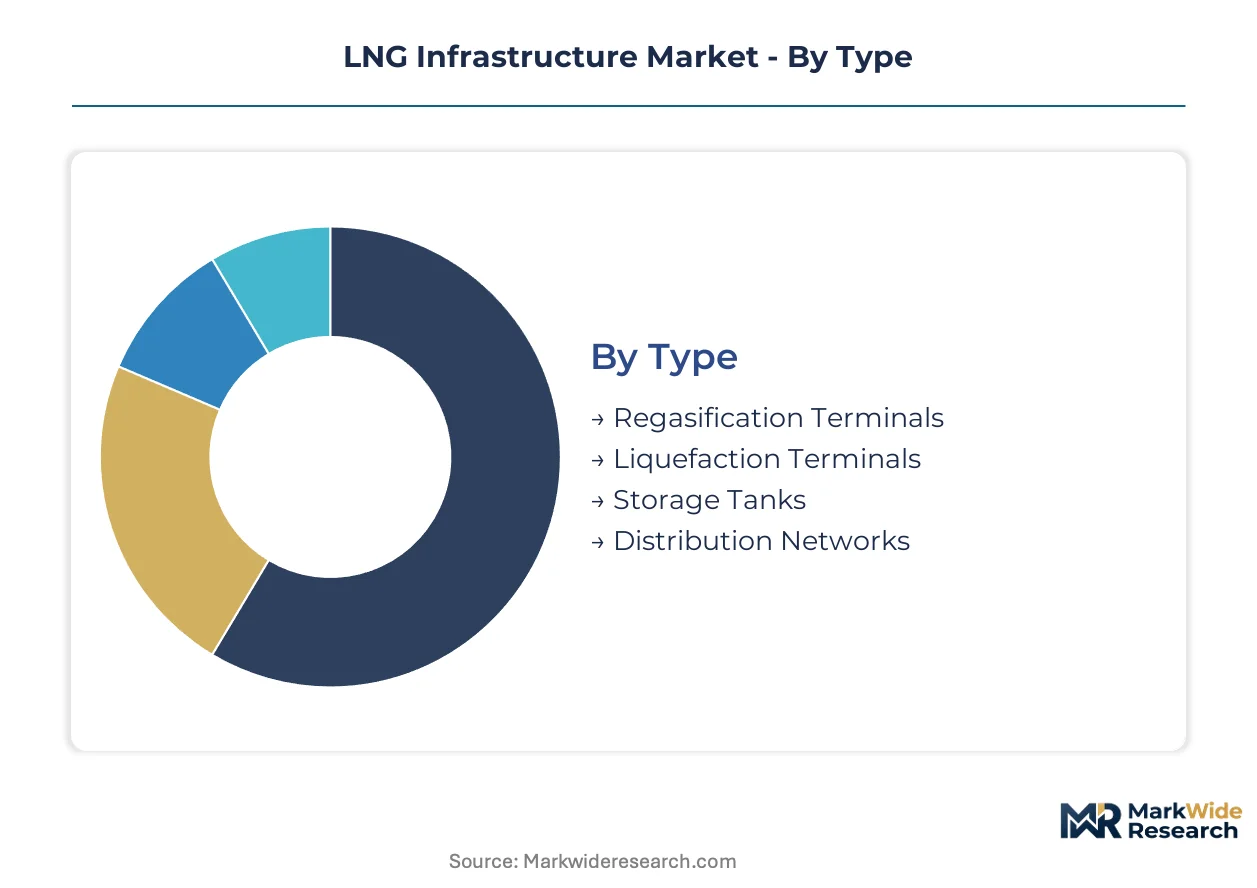
LNG infrastructure segmentation reveals how capital deployment, technology risk, and buyer procurement authority distribute across the value chain. Distinct operating requirements and regulatory exposure shape investment returns in each category.
Type:
Buyer differentiation in this category hinges on volume throughput requirements and terminal location constraints.
- Liquefaction Terminals:These facilities cool natural gas to minus 162 degrees Celsius using multi-train compression and refrigeration systems. Qatar, the United States, and Australia concentrate export capacity expansion as Asian utilities lock in long-term offtake. Front-loaded engineering intensity and four-to-six-year construction timelines command dominant capital deployment.
- Floating LNG:Offshore liquefaction vessels eliminate coastal land acquisition and enable stranded reserve development in remote maritime territories. Shell's Prelude facility off Australia and Petronas' PFLNG Dua off Malaysia demonstrate commercial viability for subsea field tiebacks.
- Regasification Terminals:Import facilities warm cryogenic LNG back to gaseous state for pipeline injection or local distribution.
- Storage Tanks:Full-containment and membrane tank systems buffer supply-demand mismatches.
- Distribution Networks:Pipeline and trucking infrastructure moves regasified product to end-use points.
Volume sits with liquefaction terminals; growth tilts toward floating LNG.
End User:
Procurement scale and contract duration separate buyers in this dimension.
- Power Generation:Baseload electricity utilities negotiate fifteen-to-twenty-year offtake agreements to secure supply certainty. Japan's JERA and South Korea's KOGAS centralize fuel procurement authority, displacing fragmented subsidiary-level contracting.
- Industrial:Petrochemical, fertilizer, and metals producers consume gas as process feedstock and thermal energy.
- Transportation:Marine bunkering and heavy-duty trucking fleets create distributed demand nodes beyond traditional utility offtake.
- Residential:City gas distribution networks serve heating and cooking loads in urban centers.
Contract value concentrates with power generation; expansion accelerates in transportation.
Technology:
Emissions exposure and modular deployment flexibility distinguish technology choices.
- Cryogenic Technology:Minus 162 degrees Celsius handling systems using nickel and molybdenum-intensive alloys face EU F-Gas Regulation methane leakage ceilings. Mediterranean and North Sea import facilities integrate continuous emissions monitoring to comply.
- Floating LNG:Offshore liquefaction and regasification vessels unlock reserves without permanent coastal footprint. Arctic operators adopt modular skid-mounted components to reduce on-site construction labor.
- Land-Based LNG:Conventional stick-built terminals face permitting delays and seasonal construction windows.
- Recompression Technology:Boil-off gas recovery systems improve vessel and terminal efficiency.
Installed base favors cryogenic systems; capacity additions favor floating LNG.
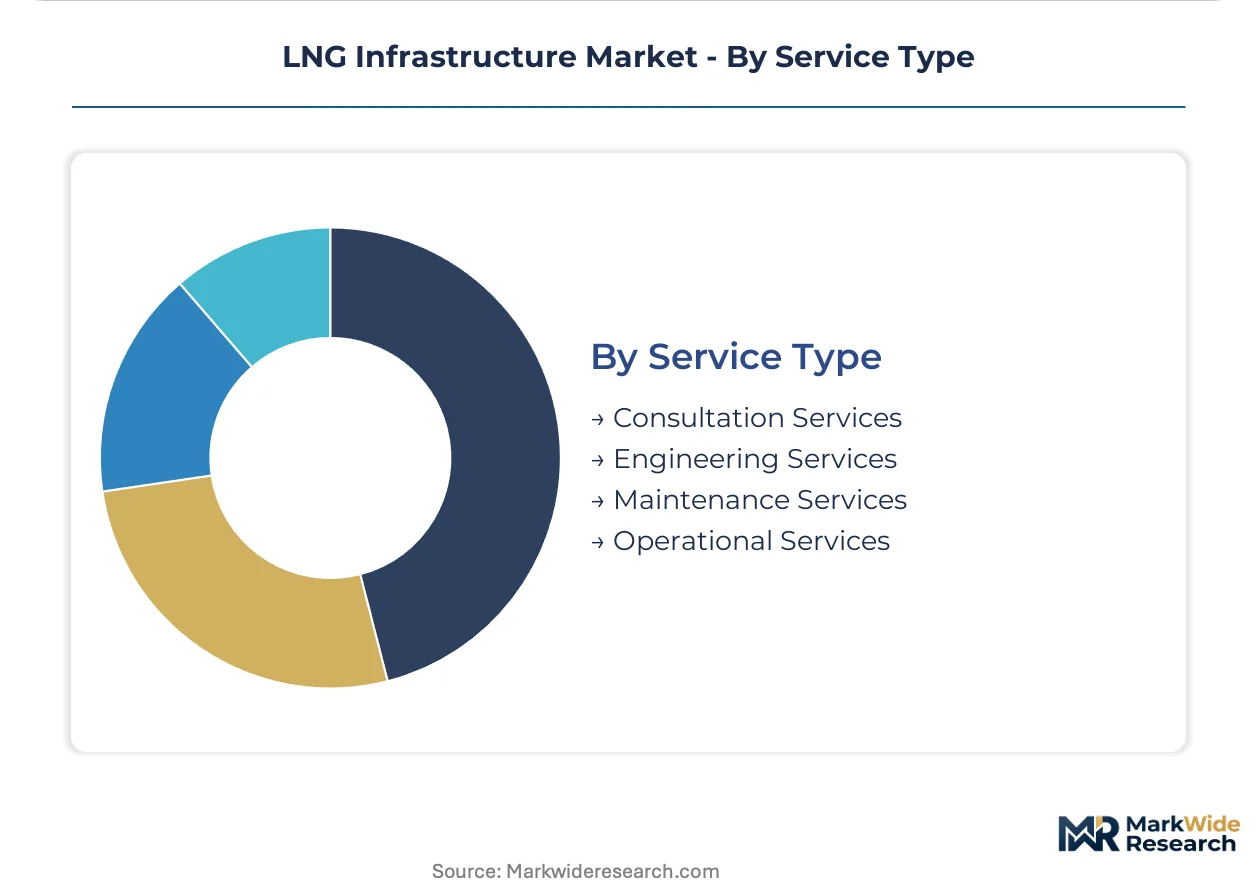
Service Type:
Project lifecycle stage and technical specialization define service procurement patterns.
- Engineering Services:Front-end design and EPC execution concentrate with Bechtel Corporation and Technip Energies for Gulf Coast and Middle East megaprojects. Cheniere Energy's tolling model locks in revenue visibility through long-term service contracts.
- Maintenance Services:Cryogenic welding certification scarcity extends turnaround timelines for minus 162 degrees Celsius system repairs.
- Operational Services:Terminal commissioning and throughput optimization integrate digital monitoring.
- Consultation Services:Regulatory compliance and market entry advisory support project development.
Revenue stability sits with maintenance services; margin expansion tilts toward engineering services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The production-consumption divide defines regional LNG infrastructure deployment. Qatar, the United States, and Australia concentrate liquefaction capacity expansion while Asian economies absorb import terminal investments.
United States
Gulf Coast utilities and independent developers advance brownfield terminal expansions to serve Asian utility offtake. FERC governs siting and environmental review for export terminals, compressing approval timelines for projects with existing coastal footprints. Cheniere Energy's Sabine Pass complex anchors Louisiana's liquefaction cluster with tolling contracts securing revenue visibility.
Qatar
North Field expansion megaprojects concentrate execution capacity with select EPC consortia serving Japanese and South Korean buyers. The country's national petroleum regulator oversees integrated project development spanning offshore production to liquefaction. Ras Laffan Industrial City hosts the world's largest LNG production complex with parallel train construction.
Australia
Shell's Prelude floating LNG facility demonstrates commercial viability for subsea field tiebacks in remote maritime territories. The country's environmental protection framework imposes binding emissions monitoring on coastal liquefaction assets. Western Australia's offshore basins concentrate floating production investments without permanent coastal footprint.
Japan
JERA and KOGAS-style centralized procurement offices displace fragmented subsidiary-level contracting for baseload power utilities. METI sets import quality specifications that shape liquefaction train design standards across supplier countries. Tokyo Bay and Osaka Bay import terminals integrate continuous emissions monitoring to comply with tightening methane leakage ceilings.
Germany
Industrial gas consumers accelerate regasification terminal development to replace pipeline supply disruptions. The EU F-Gas Regulation and REACH framework constrain allowable methane leakage rates for European-connected assets. Wilhelmshaven and Brunsbüttel anchor North Sea import infrastructure with modular floating storage and regasification units.
LNG Infrastructure Market Competitive Environment
Capital-heavy liquefaction terminal operators compete with asset-light tolling service providers for margin capture across project lifecycles. The vendor base concentrates among integrated energy majors, specialized EPC contractors, and independent terminal developers with distinct funding structures. Two archetypes dominate: integrated oil and gas companies controlling shipping-to-regasification value chains, and independent developers monetizing capacity through long-term tolling agreements. Competitive moves center on securing offtake partnerships ahead of construction commitments and capturing EPC execution capacity during simultaneous global expansion waves.
Within the integrated major tier, Shell plc and ExxonMobil occupy positions spanning liquefaction, shipping, and regasification asset control across multiple continents. Cheniere Energy exemplifies the independent developer archetype through tolling-based revenue models that lock in cash flow visibility regardless of commodity price swings. Bechtel Corporation anchors global EPC execution capacity with project backlogs concentrated in Gulf Coast and Middle East megaprojects.
| Leading Market Players |
|---|
| Cheniere Energy |
| Bechtel Corporation |
| Sempra Energy |
| ExxonMobil |
| Chevron Corporation |
| Shell plc |
| Gazprom |
| Novatek |
| JGC Holdings Corporation |
| Others |
Value Chain & Pricing Dynamics
The EU F-Gas Regulation and REACH framework are tightening methane leakage ceilings and fluorinated gas equipment restrictions, gating qualified supply to certified EPC consortia while reserving premium-tier pricing access for operators with integrated emissions monitoring and lower-carbon liquefaction technology.
Pricing Analysis
Margin tightening in long-term tolling contracts reflects input cost volatility for nickel and molybdenum-intensive cryogenic alloys. Pricing stratifies across integrated majors, independent terminal developers, and specialized service providers based on volume commitment scale and shipping-to-regasification bundling. Cost-down pressure on modular floating LNG builds accelerates because fabrication yards face qualified welder scarcity. Asian power utilities demonstrate lowest price sensitivity through fifteen-to-twenty-year offtake agreements, while industrial feedstock buyers and small-scale bunkering operators exhibit highest sensitivity to unit cost fluctuations.
Supply Chain Analysis
Qualified cryogenic welding technician scarcity in South Korea, Japan, and Germany constrains fabrication scheduling for minus 162 degrees Celsius system construction. Supply draws from nickel and molybdenum mining corridors, specialized alloy foundries, and modular skid-mounted component manufacturers. Single-source vulnerability concentrates in Qatari EPC execution capacity for simultaneous global megaproject waves. Distribution runs through marine shipping networks, floating storage and regasification units, and pipeline injection terminals to reach end-use points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The LNG infrastructure market is becoming a vertical-integration race as players pursue captive control over shipping-to-regasification value chains to capture margin across project lifecycles rather than surrendering it to fragmented service providers.
For Market Incumbents: Anticipate floating LNG technology disruption by securing exclusive fabrication yard partnerships in South Korea and Japan before capacity constraints harden. Deepen backward integration into specialized cryogenic alloy supply through long-term offtake agreements with nickel and molybdenum producers. Prioritize EU F-Gas Regulation compliance certification to defend premium pricing tiers against emerging lower-carbon competitors. For New Entrants and Emerging Players: Small-scale LNG bunkering operators in Vietnam and Bangladesh represent the most penetrable buyer archetype, as these underpenetrated demand centers lack established supplier relationships and prioritize flexible delivery terms over volume scale. Target modular floating storage and regasification unit deployment to bypass coastal land acquisition barriers. Lead with integrated digital emissions monitoring as a differentiated service bundle. For Investors and Strategic Acquirers: Japanese and South Korean utility centralization of procurement authority into JERA and KOGAS-style fuel management offices is the leading indicator that long-term partnership structures are displacing spot market participation. Favor acquisition targets with tolling-based revenue models and existing FERC or EU regulatory approvals. Material acceleration in carbon capture integration announcements for existing liquefaction trains signals inflection toward lower-carbon asset premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Tolling Agreement Expansion | Cheniere Energy's Sabine Pass complex demonstrates revenue visibility locking regardless of commodity price swings. |
| Floating LNG Capacity Buildout | Shell's Prelude facility off Australia validates commercial viability for subsea field tiebacks without coastal footprint. |
| EU F-Gas Compliance Certification | Mediterranean and North Sea import facilities integrate continuous emissions monitoring to maintain market access. |
| Cryogenic Welder Training Pipeline Investment | Fabrication yards in South Korea and Japan secure execution capacity for simultaneous global expansion waves. |
| Integrated Shipping-to-Regasification Asset Control | Asian power utilities consolidate procurement authority, favoring bundled service providers over fragmented contracting. |
Study Parameters
SEC filings, FERC project development databases, and IEA country energy statistics formed the secondary backbone, supplemented by customs and trade data tracking cryogenic equipment flows. Primary interviews with EPC project directors, utility fuel procurement officers, and terminal commissioning engineers validated demand assumptions and construction timeline estimates. Bottom-up project pipeline aggregation and top-down country-level demand forecasting were triangulated to produce volume and value estimates.
Historical trendline analysis of liquefaction capacity additions, regasification terminal commissioning rates, and floating LNG vessel deployments informed baseline growth patterns across the projection horizon. Segmentation modeling incorporated facility type, end-use sector, technology choice, and service procurement pattern dimensions. CAGRs were derived from supply-demand balance analysis and buyer contracting behavior shifts, with specific inputs from EU F-Gas Regulation compliance timelines and Asian utility centralization trends.
Revisions become necessary when Qatari megaproject execution delays, cryogenic alloy price spikes, or accelerated EU methane leakage enforcement materialize beyond baseline assumptions. Forecasts reflect documented assumptions about regulatory compliance timelines and construction labor availability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Wireless Power Transmission Market
Transmission and Distribution
Middle East Pipeline Maintenance Market
Transmission and Distribution
Submarine Electricity Transmission Systems Market
Transmission and Distribution
Natural Gas Storage Technologies Market
Transmission and Distribution
Vapor Recovery Units Market
Transmission and Distribution
Flexible Alternating Current Transmission Systems Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
Asia Pacific LNG Infrastructure Market
Transmission and Distribution
Power Transmission Component Market
Transmission and Distribution
Middle East Gas Pipeline Infrastructure Market
Transmission and Distribution
Distribution Lines and Poles Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Substation Monitoring System Market
Transmission and Distribution
Asia-Pacific High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Global Virtual Pipeline Systems Market
Transmission and Distribution
High Voltage Transmission Substation Market