
 Series Compensation System Sales Market | 2026-2036
Series Compensation System Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Series Compensation System Sales Market Insights
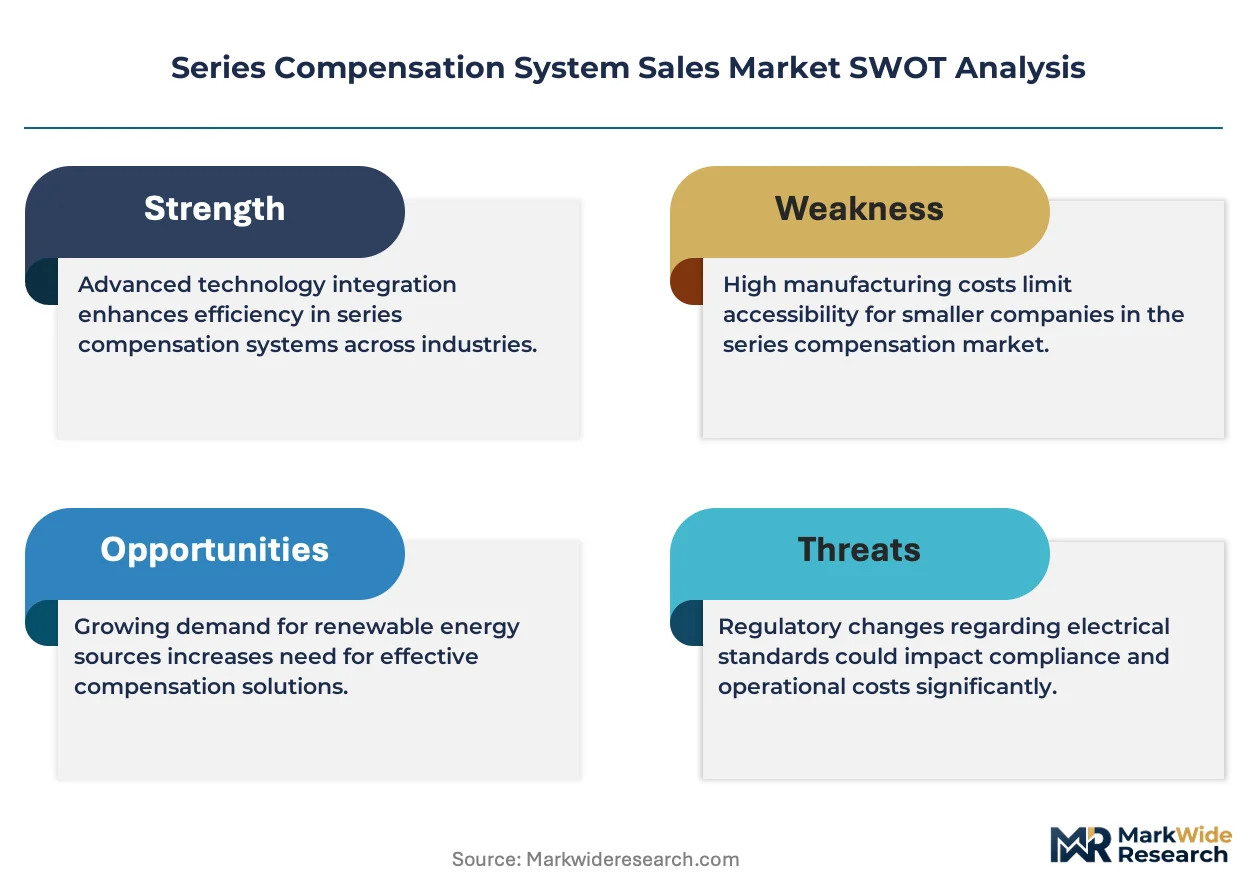
Utility buyer consolidation is repositioning procurement toward fewer, larger platform contracts with lifecycle service obligations. ABB leverages its installed base in HVDC corridors to bundle series compensation with converter stations. Siemens sustains competitive pressure through regional manufacturing footprints that shorten delivery timelines for large capacitor banks.
A series compensation system injects controlled capacitive reactance into transmission lines to improve stability, increase power transfer capacity, and reduce line losses, typically employing metal-oxide varistors and triggered spark gaps for overvoltage protection. Fixed compensation dominates mature grid interconnections where load profiles remain predictable, while variable compensation captures expanding share in renewable-heavy networks requiring dynamic impedance adjustment. Cloud-based deployment is gaining traction among regional utilities seeking remote diagnostics without dedicated IT infrastructure.
FERC Order 2023 and NERC CIP standards shape equipment qualification timelines and cybersecurity requirements for North American installations. China's GB/T standards and grid code revisions under the National Energy Administration impose localized testing protocols that filter market access. Stakeholders must weigh certification pathway costs against the revenue durability of multi-decade utility service contracts.
Market Dynamics
Utility procurement consolidation is compressing vendor counts and extending contract lifecycles toward integrated platform obligations with embedded cybersecurity and remote monitoring clauses.
Growth Catalysts
- IEEE 1547 interconnection standards:Grid modernization mandates in North America are accelerating replacement cycles for aging series compensation hardware. Utilities face compliance deadlines that compress procurement timelines.
- Metal-oxide varistor technology:Advanced overvoltage protection materials are extending equipment lifespans and reducing maintenance intervals. Grid operators prioritize these upgrades in high-reliability corridors.
- Renewable-heavy networks:Wind and solar integration in Germany and China is driving demand for variable compensation systems that adjust impedance dynamically. Transmission operators require flexible response to intermittent generation patterns.
Market Restraints
- Capacitor-grade polypropylene supply:Specialized dielectric film production concentrates among a handful of European and Japanese suppliers. Price volatility in this input cascades through capacitor bank manufacturing costs.
- Localized testing protocols:China's GB/T standards under the National Energy Administration impose country-specific certification pathways. Foreign vendors face extended qualification timelines and duplicate engineering expenses.
- Thyristor-controlled series compensation:TCSC systems compete with static synchronous series compensators in certain high-bandwidth applications. Substitution pressure intensifies where rapid reactive power modulation is prioritized over cost efficiency.
Strategic Opportunities
- Cloud-based deployment models:Regional utilities without dedicated IT infrastructure are adopting remote diagnostic platforms. Vendors can unbundle hardware from software subscriptions to capture recurring revenue streams.
- FERC Order 2023 implementation:Interconnection queue reforms in the United States are accelerating transmission buildout timelines. Equipment suppliers can align certification roadmaps with expedited project schedules.
- Hybrid compensation architectures:Convergence of fixed and variable compensation technologies enables modular system design. This flexibility appeals to grid operators managing phased renewable integration across multiple voltage levels.
Industry Challenges
- Power electronics engineering talent:Specialized expertise in high-voltage semiconductor design and electromagnetic transient analysis remains scarce. Vendors compete for limited pools capable of integrating varistor protection with digital control systems.
- NERC CIP cybersecurity certification:North American utilities require extensive documentation of supply chain security and software integrity. Compliance timelines frequently extend beyond original project schedules, straining vendor-customer relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Series Compensation System Sales Market |
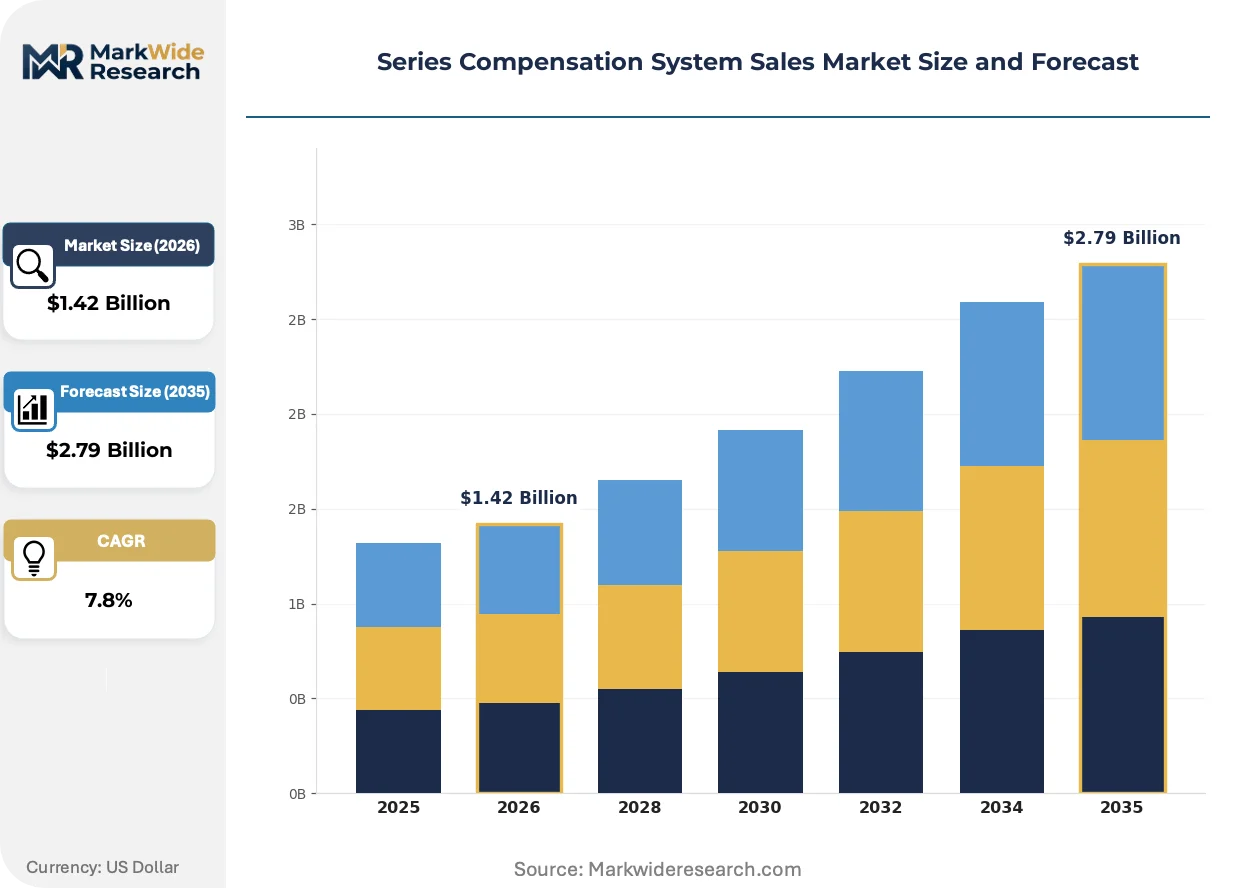
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.79 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Compensation, Variable Compensation, Benefits, Performance Management End User: Corporations, Educational Institutions, Nonprofits, Government Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Mobile Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | ABB, Siemens, General Electric, Mitsubishi Electric, Alstom, Hitachi Energy, Hyosung Corporation, NR Electric, Toshiba, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Series Compensation System Sales Market Trends and Innovations
Digital control architectures and modular platform designs are displacing conventional fixed-capacitor installations. Vendors are repositioning around lifecycle service revenue rather than equipment margins alone.
Thyristor-switched capacitor banks with integrated metal-oxide varistor protection are consolidating market share in transmission corridors requiring rapid impedance adjustment. European grid operators in Germany and Nordic markets are deploying these systems at accelerating rates to manage wind power variability. The technology is consolidating vendor differentiation around software-defined control algorithms rather than hardware specifications alone.
China's GB/T standards revisions under the National Energy Administration are tightening electromagnetic compatibility testing for imported series compensation equipment. Domestic manufacturers gain timeline advantages as foreign suppliers navigate extended qualification protocols. State Grid Corporation procurement specifications now prioritize equipment with pre-certified local testing histories, reshaping competitive access patterns.
Regional utilities are unbundling after-sales service contracts from initial equipment purchases, creating standalone recurring revenue streams for diagnostics and predictive maintenance. This behavioral shift compresses upfront capital outlays while extending vendor-customer relationships across twenty-year asset lifecycles. The pattern is most visible among municipal utilities in the United States and cooperative networks in Germany seeking operational expenditure flexibility.
Series Compensation System Sales Market Segmentation
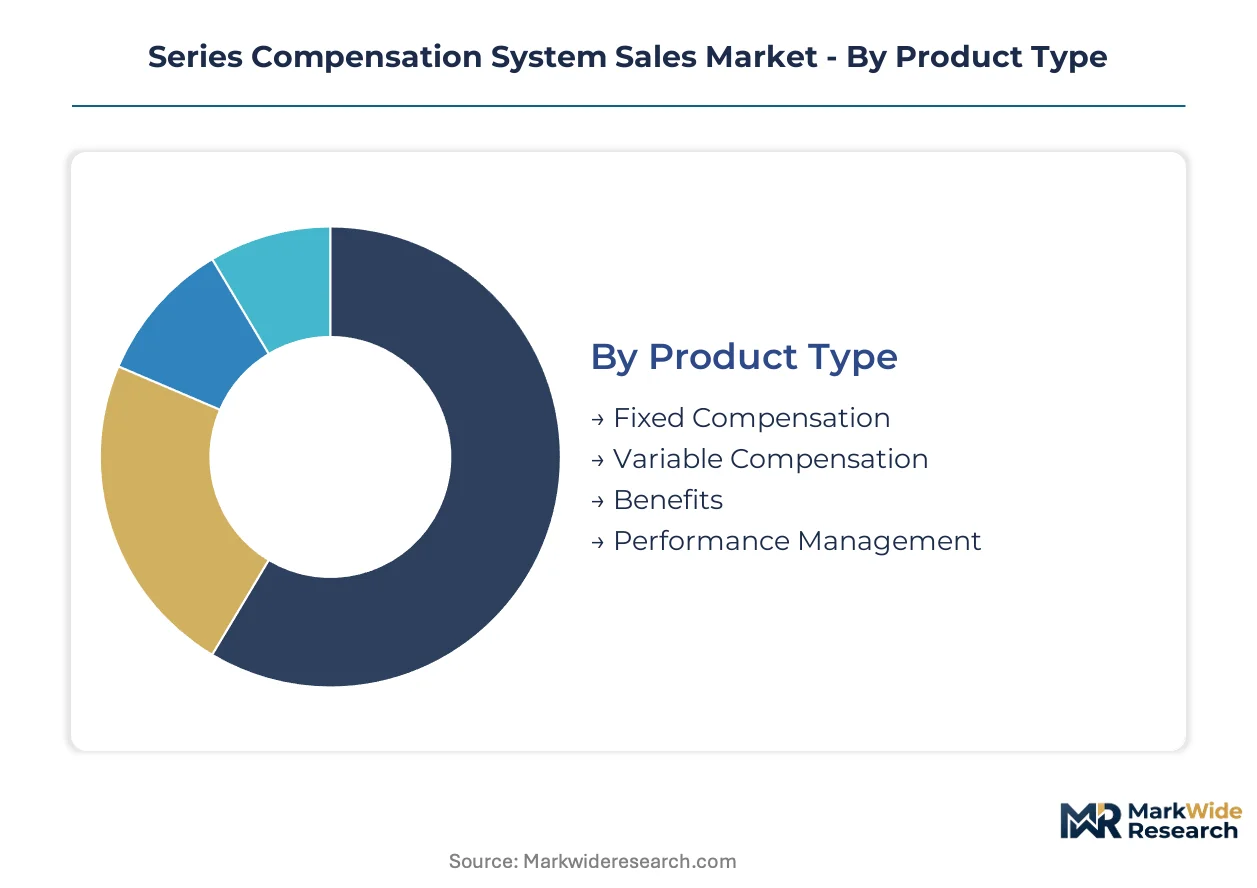
Series compensation system procurement patterns diverge sharply across buyer sophistication, infrastructure legacy, and grid modernization timelines. Understanding these fault lines enables vendors to align product architectures with specific customer capability profiles and regulatory exposure.
Product Type:
Grid operators select compensation modes based on generation predictability and corridor voltage stability requirements.
- Fixed Compensation:Capacitor banks with fixed reactance values provide baseline impedance correction for transmission lines with stable load profiles. State Grid Corporation in China deploys these extensively across coal-heavy interior corridors where dispatch patterns remain predictable.
- Variable Compensation:Thyristor-switched and mechanically switched systems enable dynamic impedance adjustment responding to real-time grid conditions. German transmission operators prioritize these for wind-rich northern corridors where generation fluctuates hourly.
- Benefits:Ancillary compensation services including voltage support contracts and reactive power market participation. Grid operators monetize these through FERC Order 2023 interconnection frameworks.
- Performance Management:Software platforms monitoring compensation effectiveness and predicting maintenance intervals. Regional utilities adopt these to extend asset lifecycles without dedicated engineering staff.
Fixed compensation leads volumes today; variable compensation is gaining share fastest.
End User:
Procurement scale and contract structure vary dramatically by institutional ownership model and regulatory oversight intensity.
- Corporations:Large industrial consumers with captive transmission infrastructure, including mining and petrochemical complexes. These buyers prioritize uptime guarantees and negotiate long-term service riders.
- Educational Institutions:University microgrids and research facilities operating campus-scale distribution networks. Procurement emphasizes demonstration value for grid modernization curricula.
- Nonprofits:Rural electric cooperatives and municipal utilities serving dispersed populations. These entities favor cloud-based monitoring to minimize IT overhead.
- Government Agencies:Federal transmission authorities and state-owned grid operators. Contracts embed cybersecurity certification mandates and domestic content requirements.
Government agencies dominate contract value; rural cooperatives show steepest expansion trajectory.
Deployment:
Infrastructure constraints and IT maturity determine how control systems integrate with existing utility architectures.
- On-Premise:Dedicated hardware installations within utility control centers. Mature grid operators in Germany retain these for air-gapped security compliance.
- Cloud-Based:Remote diagnostic platforms hosted by vendor infrastructure. Municipal utilities across the United States adopt these to convert capital expenditure to operational expenditure.
- Hybrid:Critical control functions remain on-premise while analytics migrate to cloud. This architecture satisfies NERC CIP segmentation requirements.
- Mobile:Field technician applications for asset inspection and emergency response. These extend workforce effectiveness across geographically dispersed transmission corridors.
On-premise retains majority installed base; cloud-based deployment climbs the fastest.
Service Type:
Revenue durability depends on how vendors unbundle lifecycle value from initial equipment transactions.
- Consulting:Grid planning studies identifying optimal compensation placement and sizing. These engagements establish vendor relationships ahead of capital procurement cycles.
- Implementation:Turnkey installation including civil works, protection integration, and commissioning. Chinese GB/T standards mandate local contractor partnerships for foreign vendors.
- Maintenance:Scheduled inspection and component replacement programs. Metal-oxide varistor degradation monitoring extends these contracts to fifteen-year terms.
- Support:Technical assistance and spare parts logistics. Regional utilities contract these separately to ensure 24-hour response commitments.
Implementation captures largest revenue share; maintenance contracts expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's transmission operators deploy variable compensation at higher density than China's State Grid, where fixed capacitor banks still dominate coal corridor infrastructure. This divergence reflects renewable integration timelines and legacy grid architecture across the two largest national markets.
United States
FERC Order 2023 interconnection queue reforms accelerate transmission buildout timelines across the Southwest Power Pool and ERCOT territories. NERC CIP cybersecurity standards impose extended equipment qualification protocols that filter vendor access. Texas utilities in the Houston-Gulf Coast corridor prioritize rapid-response compensation systems to manage wind generation volatility from the Panhandle.
China
State Grid Corporation procurement concentrates in interior provinces where coal-heavy dispatch patterns favor fixed compensation installations. GB/T standards revisions under the National Energy Administration mandate localized electromagnetic compatibility testing that extends foreign vendor qualification timelines. Manufacturers in the Yangtze River Delta region gain procurement advantages through pre-certified domestic testing histories.
Germany
TenneT and 50Hertz transmission operators deploy thyristor-switched systems across northern wind corridors where hourly generation fluctuation demands dynamic impedance adjustment. EU Green Deal implementation tightens grid stability requirements for renewable integration. Industrial clusters around Hamburg and Bremen anchor manufacturing capacity for capacitor-grade components serving Nordic export markets.
India
Central Electricity Authority mandates drive capacitor bank installations across Maharashtra and Gujarat to stabilize renewable evacuation from western solar zones. State-level renewable purchase obligations compress procurement timelines for transmission utilities. Manufacturing activity concentrates in Pune and Ahmedabad industrial belts where domestic fabricators serve regional grid modernization programs.
Japan
METI grid code revisions prioritize earthquake-resilient compensation architecture for Pacific coastal transmission corridors. Regional utilities in the Tohoku and Kanto areas retrofit aging fixed installations with hybrid control systems. Yokohama-based engineering consultancies specialize in seismic qualification protocols that filter equipment sourcing for domestic projects.
Series Compensation System Sales Market Competitive Landscape
European producers anchor the integrated platform tier; East Asian specialists hold position in component-scale manufacturing and regional project execution. Market structure consolidates around five to seven full-system vendors capable of lifecycle service obligations, with a fragmented base of regional integrators serving single-country procurement. Two strategic archetypes dominate: vertically integrated conglomerates bundling compensation with HVDC and converter station portfolios, and focused capacitor bank specialists leveraging regional manufacturing footprints. Competitive intensity centers on certification timeline acceleration and cloud-based diagnostic service unbundling.
Within the integrated platform tier, ABB and Siemens exemplify the full-lifecycle vendor archetype, each leveraging installed base relationships to embed compensation systems within broader transmission infrastructure contracts. Hitachi Energy occupies a position bridging Japanese domestic market access with international project reach. These three conglomerates represent the competitive standard against which regional specialists benchmark service depth and delivery reliability.
| Leading Market Players |
|---|
| ABB |
| Siemens |
| General Electric |
| Mitsubishi Electric |
| Alstom |
| Hitachi Energy |
| Hyosung Corporation |
| NR Electric |
| Toshiba |
| Others |
Pricing and Supply Chain Analysis
Capacitor-grade polypropylene film moves from European and Japanese chemical processors through tiered pricing structures that reward volume commitments from State Grid Corporation and TenneT. This dielectric input anchors cost positions across fixed and variable compensation systems, with procurement scale determining access to qualified supplier allocations.
Pricing Analysis
Capacity additions in China and Germany are reshaping price floors for thyristor-switched capacitor banks as domestic fabricators expand metallized film coating lines. Three-tier pricing structure across premium, standard, and economy levels separates NERC CIP-certified systems from GB/T-compliant domestic offerings and basic fixed installations without remote monitoring. Price differentiation hinges on cybersecurity certification grade and bundled lifecycle service terms. Cost compression in standard-tier equipment is intensifying because municipal utilities in the United States negotiate unbundled hardware procurement. Rural electric cooperatives exhibit highest price sensitivity; federal transmission authorities prioritize certification compliance over unit economics.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale buyer demand from State Grid Corporation and TenneT, bypassing distribution intermediaries for projects exceeding 500 MVAr capacity. Manufacturing concentrates in Germany, China, and Japan for capacitor-grade polypropylene, thyristor modules, and metal-oxide varistor discs respectively. Raw material dependencies draw from biaxially oriented polypropylene resin, high-purity zinc oxide ceramic powders, and silicon-controlled rectifier wafers. Single-source vulnerability in Japanese varistor substrate production creates exposure to seismic disruption and export licensing delays. Distribution runs through regional EPC contractors for implementation and commissioning phases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Series Compensation System Sales Market compounds steadily as transmission infrastructure ages across North America, Europe, and Asia-Pacific renewable integration corridors. Grid modernization mandates provide durable demand visibility without cyclical volatility.
For Market Incumbents: Anticipate substitution pressure from static synchronous series compensators in high-bandwidth applications by deepening software-defined control capabilities and predictive maintenance platforms. Prioritize certification timeline acceleration for China's GB/T electromagnetic compatibility revisions to defend access against domestic manufacturers with pre-qualified testing histories. Vertical integration into capacitor-grade polypropylene sourcing through partnerships with Yangtze River Delta metallized film coaters secures input cost positions. For New Entrants and Emerging Players: Cloud-based remote diagnostic platforms offer technology-first wedge into municipal utilities and rural electric cooperatives seeking operational expenditure flexibility without dedicated IT infrastructure. Target underpenetrated segments in India's western solar evacuation corridors where Central Electricity Authority mandates compress procurement timelines for regional transmission utilities. Lead with subscription-based performance management software to establish relationships ahead of capital equipment cycles. For Investors and Strategic Acquirers: Roll-up economics work for regional capacitor bank specialists with pre-certified domestic testing histories because China's State Grid procurement specifications increasingly prioritize equipment with localized qualification timelines. Five-to-ten-year viability rests on recurring maintenance revenue durability rather than equipment margin capture alone. Monitor FERC Order 2023 interconnection queue processing velocity as inflection indicator for North American transmission buildout acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Based Diagnostic Platform Launch | Captures recurring revenue from U.S. municipal utilities converting capital expenditure to operational expenditure models. |
| GB/T Electromagnetic Compatibility Certification | Accelerates foreign vendor access to State Grid Corporation procurement cycles against domestic manufacturer timeline advantages. |
| Thyristor Module Backward Integration | Reduces exposure to silicon-controlled rectifier supply concentration in Japan and South Korea. |
| Hybrid Compensation Architecture Development | Enables modular system design appealing to grid operators managing phased renewable integration. |
| Lifecycle Service Contract Unbundling | Extends vendor-customer relationships across twenty-year asset lifecycles for predictive maintenance revenue. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with utility planning officers, transmission system operators, EPC contractors, and capacitor bank procurement leads with secondary validation. Bottom-up triangulation draws from FERC interconnection filings, EIA transmission project databases, State Grid Corporation procurement announcements, and EU Green Deal implementation tracking. Top-down cross-checks reference IEA grid investment reports and national regulatory filings from the National Energy Administration and Bundesnetzagentur.
Rate-of-change decomposition separates volume growth from price movements across fixed compensation, variable compensation, and ancillary services segments throughout the forecast period. Segmentation dimensions modeled include product type, deployment architecture, service unbundling level, and regional regulatory framework cluster. CAGRs derive from utility capital expenditure pipeline analysis and renewable integration timeline correlation. Industry-specific forecast inputs incorporate IEEE 1547 replacement cycle schedules and GB/T standards revision implementation trajectories.
The model holds under stable grid modernization investment continuity; deviation in interconnection queue reform velocity or capacitor-grade polypropylene supply disruption would shift equipment procurement timelines. Forecasts reflect documented assumptions regarding regulatory compliance deadline adherence and renewable capacity addition schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Transmission and Distribution
Asia Pacific Load Break Switches Market
Transmission and Distribution
South and Central America High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
United States LNG Infrastructure Market
Transmission and Distribution
Oil Pipeline Infrastructure Market
Transmission and Distribution
Transmission Housing Demand Market
Transmission and Distribution
Energy and Infrastructure Inertial Systems Market
Transmission and Distribution
Electricity Transmission Infrastructure Market
Transmission and Distribution
Pipeline Monitoring System Market
Transmission and Distribution
Gas Insulated Transmission Lines Market
Transmission and Distribution
Substation Grounding System Market
Transmission and Distribution
Mobile Substation Market
Transmission and Distribution
US HVDC Transmission System Market
Transmission and Distribution
High Voltage Distribution Substation Market
Transmission and Distribution
Bulk Terminals Market
Transmission and Distribution
United States High-Voltage Direct Current (HVDC) Transmission Systems Market
Transmission and Distribution
Pipeline Services Market