
 Vietnam Semiconductor Materials Market | 2026-2036
Vietnam Semiconductor Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Semiconductor Materials Market Intelligence
Vietnam is reshaping Southeast Asian semiconductor supply chains through aggressive fab and advanced packaging capacity additions. Samsung Electronics anchors backend operations in Thai Nguyen and Bac Ninh provinces, leveraging in-house material sourcing protocols to secure wafer and photoresist volumes. Intel Corporation sustains its Assembly and Test facility in Ho Chi Minh City, where the company specializes in high-pin-count processor packaging for datacenter and client computing segments. SK Hynix dominates memory-oriented material demand through its expanding NAND flash module assembly presence near the northern border zone.
Vietnam semiconductor materials encompass high-purity silicon wafers, photoresists, packaging substrates, and conductive adhesives engineered to meet sub-10 nanometer node tolerances and thermal cycling reliability standards. These materials enable photolithography, chemical vapor deposition, and electroplating processes that fabricate integrated circuits for consumer electronics, automotive electronics, and telecom equipment applications. Photoresists command premium margin pools as foundries and OEMs transition to extreme ultraviolet lithography-compatible chemistries. Packaging materials represent the fastest-growing product category, driven by heterogeneous integration trends in automotive electronics and 5G base station chipsets where thermal interface materials and substrate cores face acute supply tightness.
Vietnam's Ministry of Industry and Trade coordinates with the country's national standards body to align semiconductor material import protocols with IEC purity benchmarks and RoHS substance restrictions, shaping customs clearance timelines and supplier qualification pathways. The Ministry of Planning and Investment administers investment licensing incentives that require foreign fabs to localize packaging material procurement, directly redirecting demand toward domestic adhesive and substrate distributors. Stakeholders must monitor how forthcoming revisions to chemical handling decrees affect photoresist storage infrastructure requirements and whether foundry customers will mandate second-source qualification for critical deposition precursors.
Market Dynamics
Advanced packaging material localization mandates from Vietnam's Ministry of Planning and Investment are forcing foundry operators to restructure supplier qualification timelines and redirect procurement toward domestic adhesive and substrate distributors.
Growth Catalysts
- EUV Photoresist Adoption:Logic foundries in Bac Ninh Province are qualifying extreme ultraviolet-compatible chemistries for sub-10 nanometer node production, creating pull-through demand for high-purity deposition precursors.
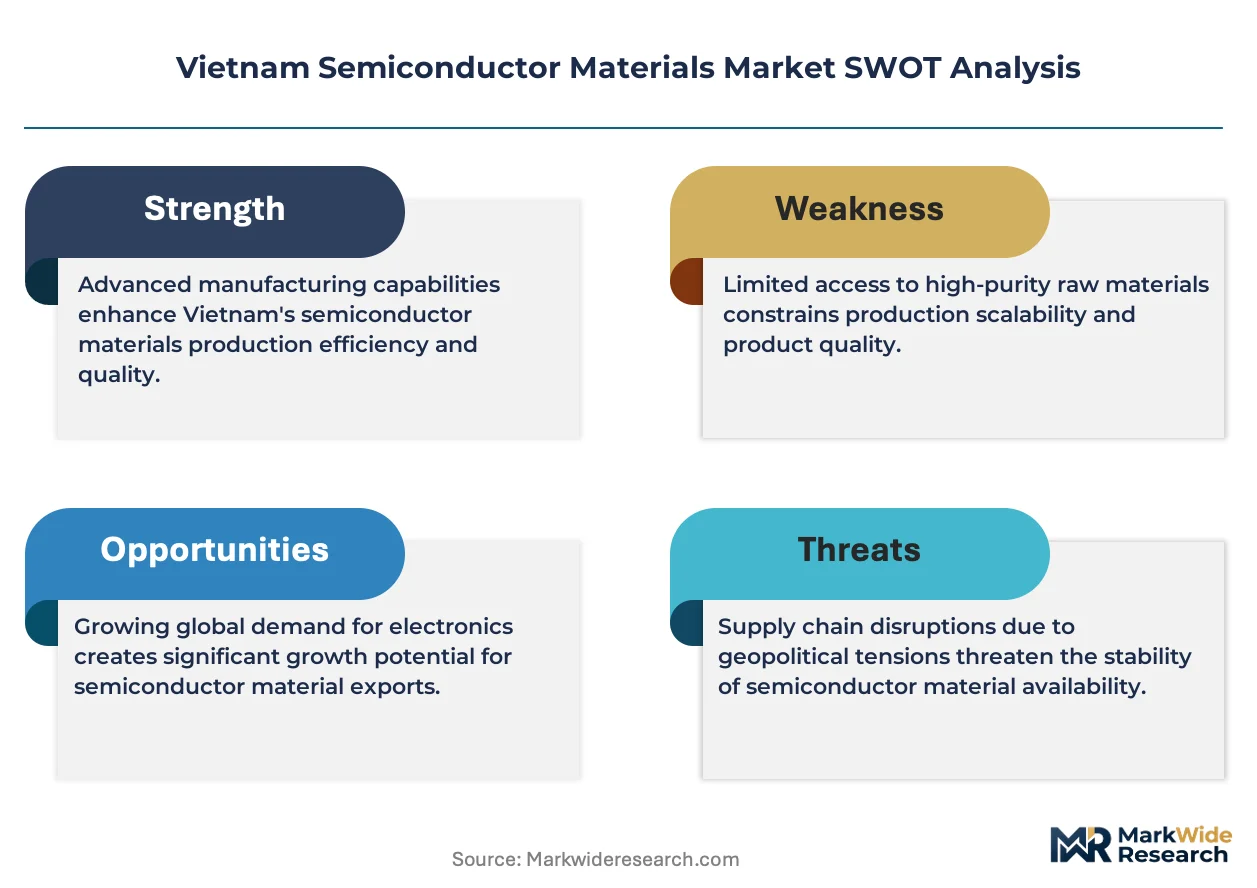
- Automotive Electronics Integration:Thermal interface materials face acute supply tightness as heterogeneous packaging designs proliferate in electric vehicle powertrain controllers and advanced driver-assistance systems.
- RoHS Alignment:Vietnam's national standards body has synchronized semiconductor material import protocols with EU substance restrictions, accelerating customs clearance for qualified photoresist and packaging substrate shipments.
Market Restraints
- High-Purity Silicon Feedstock Concentration:Vietnam lacks domestic polysilicon purification capacity, forcing foundries to rely on concentrated East Asian wafer suppliers subject to export licensing volatility.
- Photoresist Storage Infrastructure Gaps:Chemical handling decrees mandate specialized cold-chain facilities that most domestic distributors have not yet commissioned, extending lead times for temperature-sensitive lithography materials.
- Second-Source Qualification Burden:Critical deposition precursor specifications are locked under single-source agreements with Japanese and South Korean specialty chemical firms, limiting supply flexibility during demand spikes.
Strategic Opportunities
- Thai Nguyen Province Expansion:Greenfield advanced packaging facilities planned for this northern industrial corridor offer first-mover positioning for substrate core and conductive adhesive suppliers establishing local blending operations.
- 5G Base Station Chipset Demand:Telecom equipment manufacturers are specifying low-loss packaging substrates with enhanced thermal cycling reliability, opening premium material tiers for qualified domestic distributors.
- Vocational Training Partnerships:South Korean and Taiwanese workforce development programs are building technical certification pipelines that reduce onboarding friction for specialized material handling technicians.
Industry Challenges
- Specialized Technician Scarcity:Photolithography process engineering and chemical vapor deposition equipment maintenance functions face acute talent gaps despite Ministry of Planning and Investment training initiatives.
- Dual-Source Qualification Timelines:Foundry customers are mandating redundant supplier validation for critical precursors, compressing procurement cycles and straining domestic distributor technical service capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Semiconductor Materials Market |
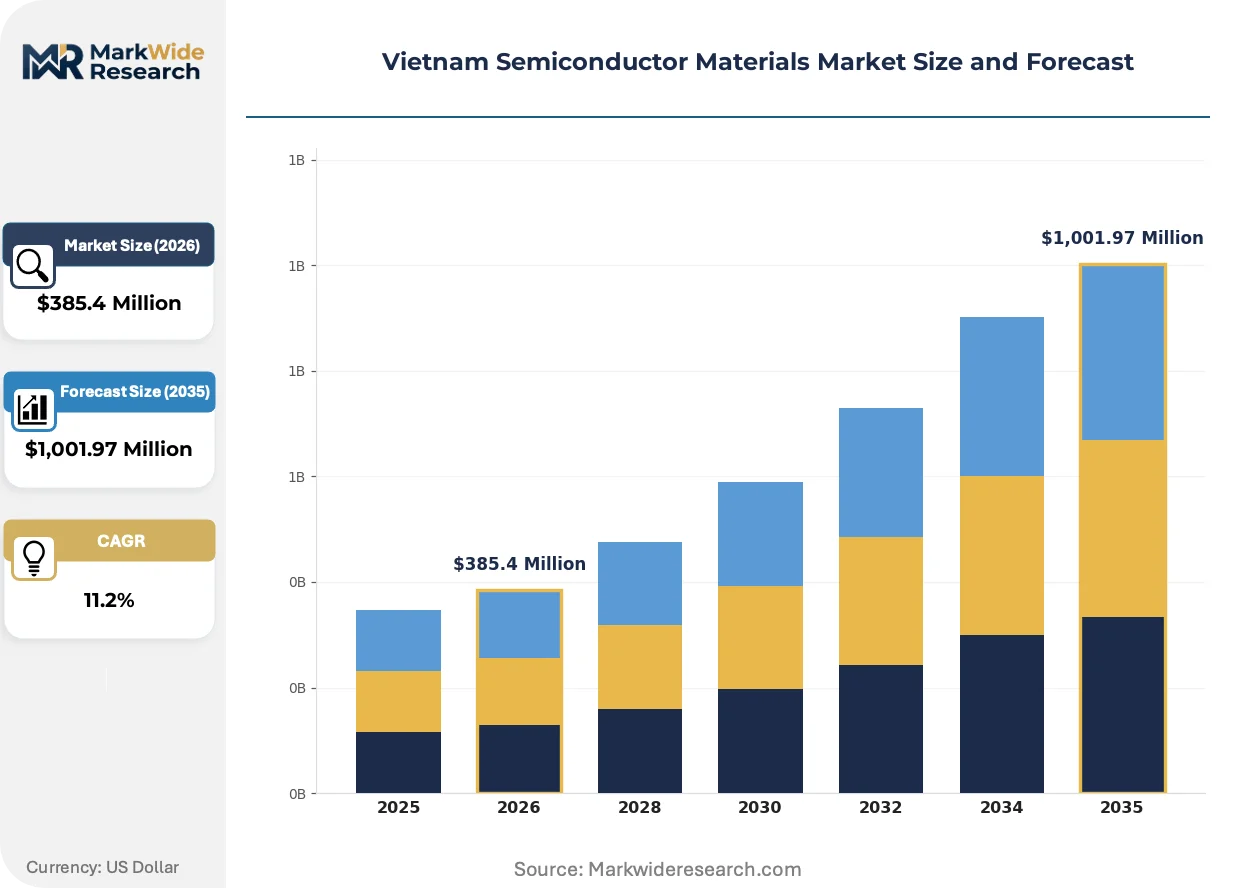
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,001.97 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicon Wafers, Photoresists, Packaging Materials, Conductive Adhesives Application: Consumer Electronics, Automotive Electronics, Telecom Equipment, Industrial Automation Technology: Photolithography, Chemical Vapor Deposition, Electroplating, Ion Implantation End User: OEMs, Fabless Companies, Foundries, Component Manufacturers |
| Companies Covered | SK Hynix, Texas Instruments, Samsung Electronics, MediaTek, Qualcomm, Intel Corporation, Micron Technology, Broadcom, Amkor Technology, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Semiconductor Materials Market Strategic Shifts & Innovations
Material purity benchmarks and process automation are converging to reshape how Vietnamese foundries specify, source, and handle semiconductor-grade chemicals and substrates across the northern industrial corridor.
Extreme ultraviolet lithography photoresists are enabling sub-7 nanometer patterning resolution for logic chip production. Samsung Electronics and Intel Corporation assembly facilities are accelerating qualification of these chemistries for high-pin-count processor packaging. This transition is digitizing supplier quality documentation and traceability systems across the procurement chain.
Vietnam's Ministry of Industry and Trade is enforcing IEC purity benchmarks alongside RoHS substance restrictions for all semiconductor material imports. This regulatory alignment is extending customs clearance timelines for non-compliant shipments while compressing qualification windows for domestic distributors seeking foundry approval. Photoresist and deposition precursor categories face the most intensive documentation scrutiny.
Direct procurement relationships between foundry operators and specialty chemical blenders are displacing traditional distributor intermediaries in high-value material categories. Domestic adhesive and substrate suppliers are responding by building in-house technical service teams capable of supporting joint process development with Bac Ninh and Ho Chi Minh City packaging facilities. This channel restructuring is most visible in thermal interface material and substrate core segments where specification complexity demands direct engineering collaboration.
Vietnam Semiconductor Materials Market Segmentation
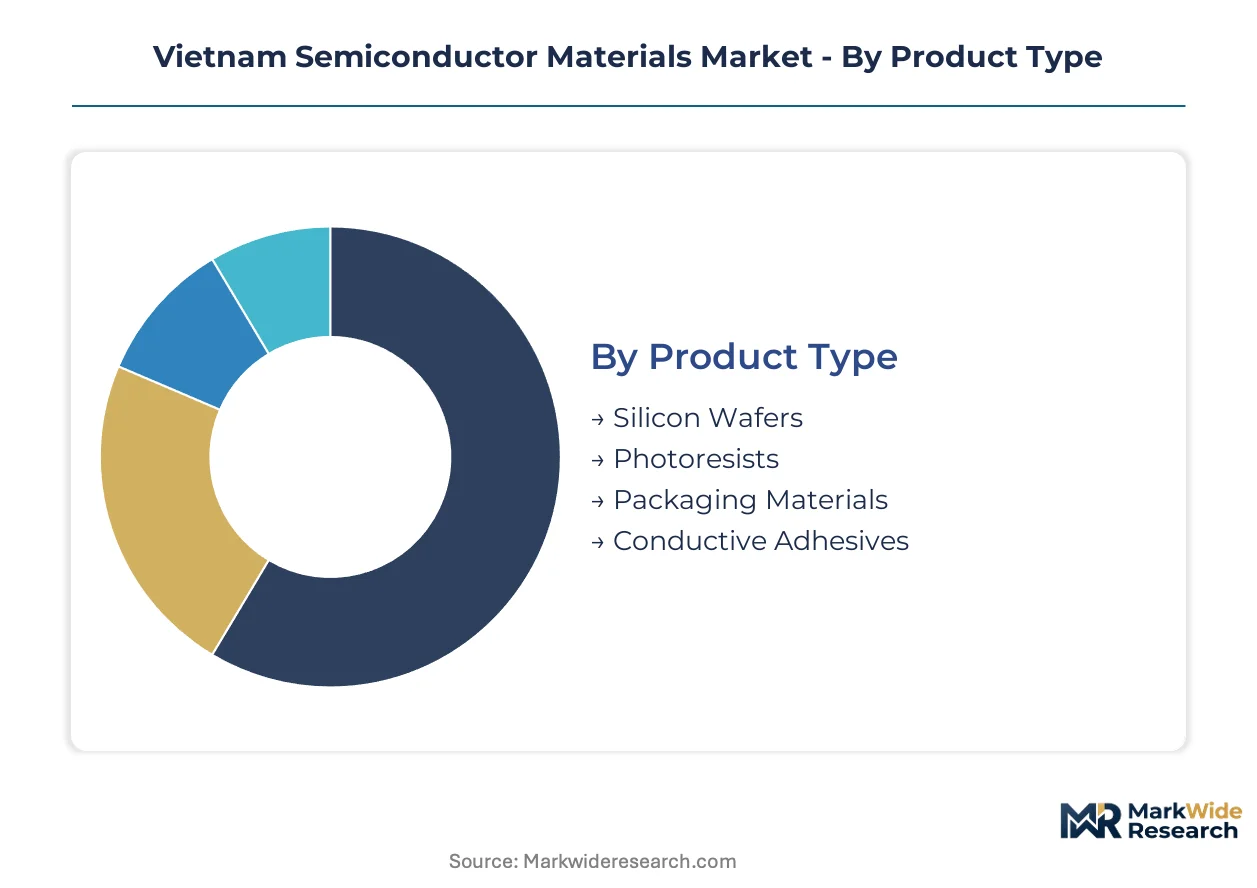
Vietnam's semiconductor materials demand fragments across four distinct dimensions. Product specifications diverge sharply between front-end wafer processing and back-end packaging operations. Application requirements from automotive powertrain controllers to 5G base station chipsets impose incompatible thermal cycling and purity standards.
Product Type:
Use cases span from raw silicon crystal growth through final device encapsulation, with each tier commanding different technical service intensity and margin profiles.
- Photoresists:These light-sensitive polymers enable sub-10 nanometer patterning resolution for logic chip production. Demand concentrates in Bac Ninh Province foundries qualifying EUV-compatible chemistries, constrained by specialized cold-chain storage infrastructure gaps that extend lead times for temperature-sensitive shipments.
- Packaging Materials:Substrate cores and thermal interface materials support heterogeneous integration in high-pin-count processors. Ho Chi Minh City assembly facilities are driving consumption for datacenter and client computing segments where thermal cycling reliability standards are tightening fastest.
- Silicon Wafers:High-purity monocrystalline substrates form the foundational layer for integrated circuit fabrication. Vietnam lacks domestic polysilicon purification capacity, forcing reliance on concentrated East Asian suppliers subject to export licensing volatility.
- Conductive Adhesives:Silver-filled epoxies and sintering pastes provide electrical interconnects in flip-chip and wire-bond packages. Domestic distributors are building local blending operations to satisfy Ministry of Planning and Investment localization mandates.
The dominant share belongs to Packaging Materials, while Photoresists is closing the gap fastest.
Application:
End-use specifications create divergent purity benchmarks and volume profiles across Vietnam's northern industrial corridor.
- Automotive Electronics:Electric vehicle powertrain controllers and advanced driver-assistance systems demand thermal interface materials with enhanced reliability under thermal shock cycling. SK Hynix and Samsung Electronics packaging facilities near the northern border zone are qualifying materials for automotive-grade NAND flash modules.
- Telecom Equipment:5G base station chipsets require low-loss packaging substrates with controlled dielectric constants. Intel Corporation's Ho Chi Minh City facility specializes in high-pin-count processors for network infrastructure where signal integrity specifications are most stringent.
- Consumer Electronics:Smartphone and tablet processors drive volume demand for standard-grade photoresists and conductive adhesives. Bac Ninh foundries serving Samsung Electronics in-house consumption anchor this segment's procurement patterns.
- Industrial Automation:Motor controllers and sensor interfaces specify mid-tier packaging materials with extended temperature range performance. This application shows slower qualification timelines due to fragmented end-customer specifications.
Automotive Electronics commands premium pricing tiers, while Telecom Equipment is expanding most quickly.
Technology:
Process chemistry requirements determine material purity thresholds and supplier qualification complexity.
- Photolithography:EUV and deep-UV exposure systems demand sub-part-per-billion metallic impurity levels in photoresists and antireflective coatings. Ministry of Industry and Trade enforcement of IEC purity benchmarks is accelerating documentation scrutiny for these chemistries.
- Chemical Vapor Deposition:Precursor gases and liquid sources for dielectric and metal film deposition require hermetic packaging and trace moisture control. Foundries are mandating redundant supplier validation for critical precursors, compressing procurement cycles.
- Electroplating:Copper sulfate and additive packages for through-silicon via and redistribution layer metallization. Ho Chi Minh City advanced packaging facilities are expanding electroplating capacity for heterogeneous integration designs.
- Ion Implantation:Dopant source materials for well and threshold voltage engineering in logic device fabrication. This technology shows lower material intensity per wafer pass than deposition or lithography processes.
Photolithography retains the largest material spend share, though Chemical Vapor Deposition precursors are gaining share fastest.
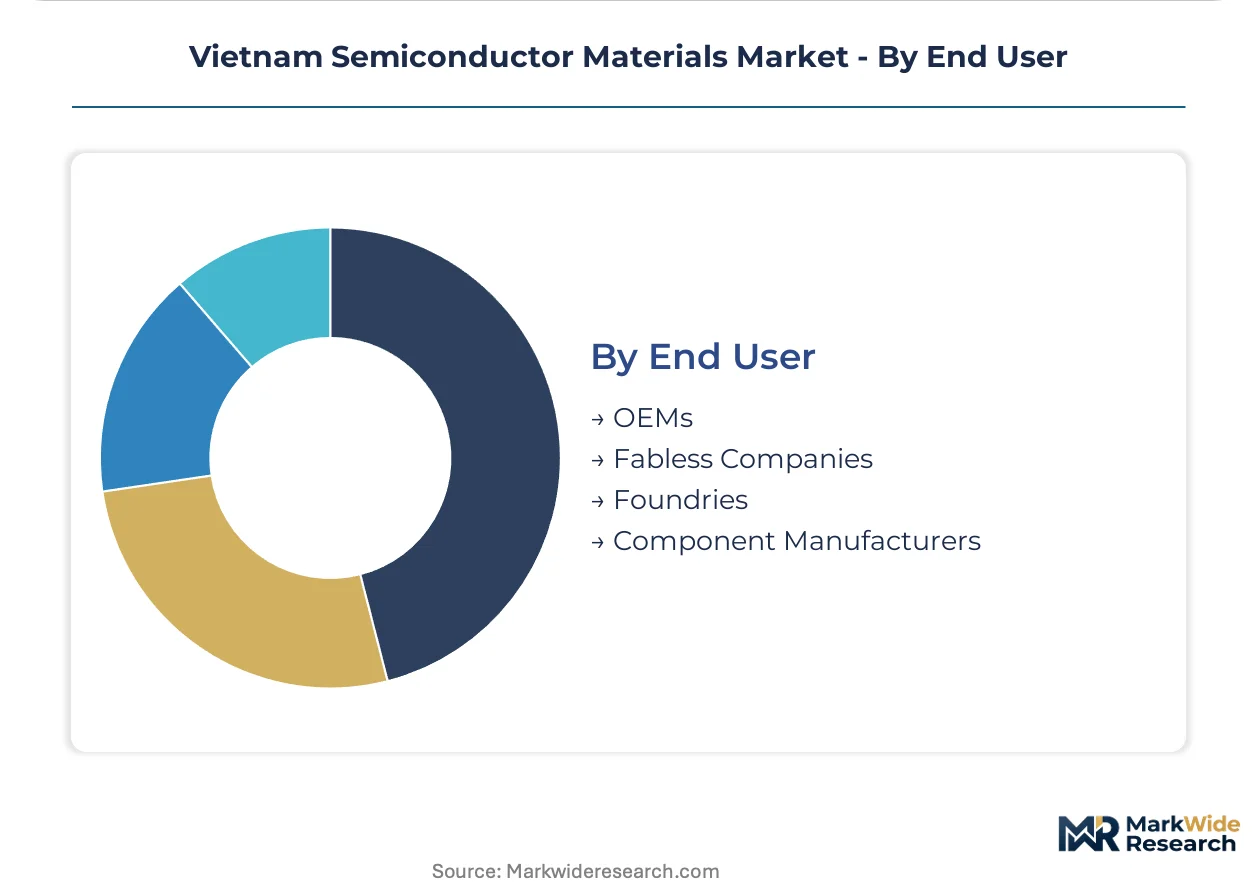
End User:
Procurement authority and technical specification control vary sharply across the value chain.
- Foundries:Samsung Electronics and Intel Corporation facilities in Bac Ninh and Ho Chi Minh City exercise direct procurement authority for high-value photoresists and deposition precursors. These operators are displacing traditional distributor intermediaries through direct relationships with specialty chemical blenders.
- OEMs:Original equipment manufacturers with captive semiconductor operations specify packaging materials for in-house module assembly. Their procurement patterns favor qualified domestic distributors with localized inventory positions.
- Fabless Companies:Design houses without fabrication assets rely on foundry-specified material sets, limiting direct procurement influence. These end users concentrate technical resources on design-for-manufacturing optimization rather than material selection.
- Component Manufacturers:Discrete and passive device producers specify standard-grade conductive adhesives and substrate materials with less stringent purity requirements than integrated circuit packaging.
Foundries dominate procurement volume, while OEMs are deepening direct material sourcing fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
East Asian suppliers dominate polysilicon purification and photoresist manufacturing, forcing Vietnamese foundries to navigate export licensing volatility while building domestic packaging material capabilities.
Bac Ninh Province
Samsung Electronics and Intel Corporation operate advanced packaging and testing facilities driving photoresist and substrate demand. Vietnam's Ministry of Planning and Investment administers investment licensing incentives requiring foreign fabs to localize procurement. The northern industrial corridor anchors logic and memory chip production with concentrated foundry operations.
Thai Nguyen Province
Greenfield advanced packaging facilities are expanding substrate core and conductive adhesive consumption for heterogeneous integration designs. The Ministry of Industry and Trade coordinates IEC purity benchmark alignment for material import protocols. This northern zone is attracting first-mover suppliers establishing local blending operations.
Ho Chi Minh City
Intel Corporation's Assembly and Test facility specializes in high-pin-count processor packaging for datacenter segments. Chemical handling decrees mandate specialized cold-chain facilities for photoresist storage that extend lead times. The southern metro serves as Vietnam's primary hub for telecom equipment chipset packaging.
South Korea
SK Hynix dominates memory-oriented material demand through expanding NAND flash module assembly near Vietnam's northern border. South Korean firms partner with Vietnam's Ministry of Planning and Investment on vocational training programs for semiconductor technicians. These cross-border workforce pipelines reduce onboarding friction for specialized material handling roles.
Vietnam Semiconductor Materials Market Key Industry Players
Integrated device manufacturers and pure-play foundries split the market between captive material sourcing and outsourced procurement channels. Samsung Electronics and Intel Corporation exercise direct procurement authority for high-value chemistries, displacing traditional distributor intermediaries. Two strategic archetypes dominate: vertically integrated conglomerates with in-house material protocols, and specialized packaging houses relying on qualified domestic distributors. Competitive moves concentrate on localizing supply chains and building technical service capabilities for joint process development.
Among Korea-based memory specialists, SK Hynix exemplifies the captive-demand archetype through its expanding Vietnam packaging presence. Samsung Electronics anchors the integrated conglomerate tier with direct procurement relationships spanning photoresists and deposition precursors. Intel Corporation represents the multinational foundry model with specialized high-pin-count packaging operations in Ho Chi Minh City.
| Leading Market Players |
|---|
| SK Hynix |
| Texas Instruments |
| Samsung Electronics |
| MediaTek |
| Qualcomm |
| Intel Corporation |
| Micron Technology |
| Broadcom |
| Amkor Technology |
| Others |
Cost & Logistics Intelligence
East Asian polysilicon purification concentration anchors margin capture at the wafer tier, while Vietnamese foundries compete for packaging material premiums through localization mandates from the Ministry of Planning and Investment.
Pricing Analysis
RoHS alignment dictates the pricing tier structure across photoresist and packaging substrate categories, with IEC purity benchmarks separating qualified from non-qualified shipments. Three-tier pricing structure across premium EUV-compatible, standard deep-UV, and economy-grade i-line photoresists reflects certification level and thermal cycling reliability grades. Cost compression in standard-grade conductive adhesives is intensifying because domestic distributors are building local blending operations to satisfy localization requirements. Fabless companies show highest price sensitivity due to limited procurement influence, while foundries with direct specialty chemical relationships capture volume discounts.
Supply Chain Analysis
High-purity silicon feedstock draws from concentrated South Korean, Japanese, and Taiwanese polysilicon suppliers subject to export licensing volatility. Photoresist chemistries and deposition precursors feed from Japanese and South Korean specialty chemical blenders operating under single-source agreements. Single-source vulnerability constrains supply flexibility for critical precursors during demand spikes. Distribution runs through foundry-direct procurement channels displacing traditional intermediaries, with domestic adhesive and substrate distributors capturing residual packaging material flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's semiconductor materials market represents a high-growth disruption as EUV photoresist adoption and advanced packaging localization mandates from the Ministry of Planning and Investment reshape procurement authority.
For Market Incumbents: Build technical service moats through in-house process engineering teams capable of joint development with Bac Ninh and Ho Chi Minh City packaging facilities. Incumbents should secure backward integration into substrate core manufacturing to defend against emerging domestic blenders, while locking foundry customers through multi-year qualification partnerships that exceed Ministry of Planning and Investment localization timelines. For New Entrants and Emerging Players: Build out Thai Nguyen Province greenfield packaging facilities as the most penetrable geography, where first-mover suppliers establishing local blending operations capture substrate core and conductive adhesive demand before incumbent distributor networks consolidate. New entrants should target automotive electronics qualification pipelines for electric vehicle powertrain controllers, leveraging South Korean vocational training partnerships to reduce specialized technician onboarding friction. For Investors and Strategic Acquirers: Secondary-cycle assets sit with domestic adhesive distributors possessing Ministry of Industry and Trade import protocol compliance infrastructure and foundry-approved cold-chain facilities. Long-term viability hinges on exposure to heterogeneous integration trends in 5G base station and automotive chipset packaging. Investors should monitor SK Hynix and Samsung Electronics capacity expansion announcements as inflection indicators for memory-oriented material demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Local Blending Operation Establishment | Domestic substrate core production satisfies Ministry of Planning and Investment procurement mandates for foreign fabs. |
| EUV Photoresist Qualification Partnership | Joint process development with Samsung Electronics Bac Ninh secures premium chemistry tier access. |
| Cold-Chain Infrastructure Investment | Specialized storage facilities reduce lead times for temperature-sensitive lithography materials under chemical handling decrees. |
| Vocational Training Program Sponsorship | South Korean and Taiwanese certification pipelines address acute photolithography technician scarcity. |
| Second-Source Precursor Validation | Redundant supplier qualification compresses procurement cycles for critical deposition materials. |
Research Approach
A standing panel of foundry procurement directors, specialty chemical technical service leads, domestic distributor operations managers, and Ministry of Industry and Trade standards officers provided ongoing calibration. Primary interviews combined with secondary validation against customs import records, IEC certification databases, Ministry of Planning and Investment licensing disclosures, and foundry capex announcements. Bottom-up demand modeling across photoresist, packaging substrate, silicon wafer, and conductive adhesive categories triangulated against top-down foundry capacity expansion data.
Scenario-bracketing around EUV adoption velocity and automotive electronics penetration shaped volume projections across the analysis window. Segmentation dimensions modeled include product purity grade, application thermal cycling specification, process technology node, and end-user procurement authority structure. CAGRs derived from foundry consumption intensity ratios and packaging material localization mandate compliance trajectories. Forecast inputs incorporated SK Hynix NAND module assembly expansion and Intel Corporation high-pin-count packaging capacity additions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated conglomerates or state-backed domestic chemical blenders would shift outcomes. Supply disruption from East Asian export licensing volatility or accelerated chemical handling decree enforcement represent specific revision risks. Cross-checking against Ministry of Industry and Trade import volume statistics and foundry customer qualification timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Silicon Germanium Material Market
Semiconductor Material
Semiconductor PI Film Market
Semiconductor Material
Glass Substrate in Semiconductor Market
Semiconductor Material
Asia-Pacific Silicone Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
Europium Market
Semiconductor Material
India Liquid Silicon Rubber Market
Semiconductor Material
Global Scintillator Market
Semiconductor Material
Polymethylhydrosiloxane Market
Semiconductor Material
Global Silicone Market
Semiconductor Material
Acetylene Black Market
Semiconductor Material
Glass Wafer Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Monocrystalline Silicone Market