
 Semiconductor PI Film Market | 2026-2036
Semiconductor PI Film Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor PI Film Market Insights
Modular film kit configurations is recalibrating procurement patterns for advanced packaging houses. Ube Industries leverages captive polyimide monomer synthesis to control supply continuity for logic-device customers. Kaneka Corporation anchors its position through roll-to-roll processing scale at facilities serving memory module producers. DuPont differentiates via thermal stability specifications that meet flip-chip ball grid array requirements.
Semiconductor PI film denotes aromatic polyimide layers engineered for thermal endurance exceeding 300 degrees Celsius, low dielectric constants near 3.4, and dimensional stability across etch-and-rinse cycles. These films serve as interlayer dielectrics, buffer coatings, and flexible carrier substrates during wafer-level processing. Ultra-thin films below 10 micrometers capture expanding margin pools as chiplet architectures multiply redistribution layer counts. Flexible substrates lead volume consumption across display driver IC packaging, while composite films gain share in heterogeneous integration stacks where copper-polyimide adhesion strength determines yield.
Japan's METI enforces JIS standards for film thickness tolerance and outgassing limits that gate supplier qualification at domestic IDMs. The EU REACH framework restricts certain dianhydride monomers, compelling reformulation of standard polyimide precursors for European-bound components. China's GB standards and SAMR certification protocols add parallel compliance tracks for equipment sold into domestic fabs. Buyers must weigh single-source qualification risk against the cost of dual-approving Asian and European material streams as packaging complexity escalates.
Market Dynamics
Chiplet architectures are multiplying redistribution layer counts, forcing packaging houses to requalify ultra-thin PI films below 10 micrometers at unprecedented speed while managing dual-source approval costs across Asian and European material streams.
Growth Catalysts
- Heterogeneous integration stacks:Copper-polyimide adhesion strength requirements in advanced packaging are pulling film specifications toward composite structures with engineered surface chemistries.
- REACH and RoHS compliance tightening:European purity mandates for polyimide precursor chemistries are accelerating reformulation investments by suppliers serving EU-bound component flows.
- South Korea's Pyeongtaek-Yongin corridor:Samsung and SK Hynix captive film qualification programs are concentrating demand for flexible substrates with thermal endurance exceeding 300 degrees Celsius.
Market Restraints
- Dianhydride monomer supply concentration:Captive synthesis capabilities at Japanese chemical conglomerates create single-source dependency risks for logic-device customers outside East Asia.
- Dual certification cost burden:Parallel GB standards and SAMR protocols in China add compliance overhead for equipment sold into domestic fabs, compressing margin pools on standard-grade films.
- Dimensional stability limits:Etch-and-rinse cycle tolerances in ultra-thin films below 10 micrometers constrain yield rates at advanced packaging houses scaling chiplet production.
Strategic Opportunities
- Modular film kit configurations:Procurement patterns at OSATs are opening white space for suppliers offering pre-qualified layer stacks with matched thermal expansion coefficients.
- Flip-chip ball grid array thermal specifications:DuPont's established performance benchmarks create template opportunities for second-tier producers targeting automotive module packaging.
- JIS standard alignment:METI-enforced thickness tolerance and outgassing limits in Japan are creating qualification gateways for films meeting combined JIS-REACH-RoHS criteria.
Industry Challenges
- Roll-to-roll processing scale requirements:Memory module producers demand continuous web widths that exceed legacy batch-coating equipment capabilities, forcing capital-intensive facility upgrades.
- Interlayer dielectric qualification timelines:IDM captive programs require 18-24 month validation cycles for new film chemistries, locking suppliers into pre-existing formulation commitments.
- Low dielectric constant specification drift:Target values near 3.4 are tightening toward 3.2 for next-generation logic devices, requiring precursor chemistry innovations without sacrificing thermal endurance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor PI Film Market |
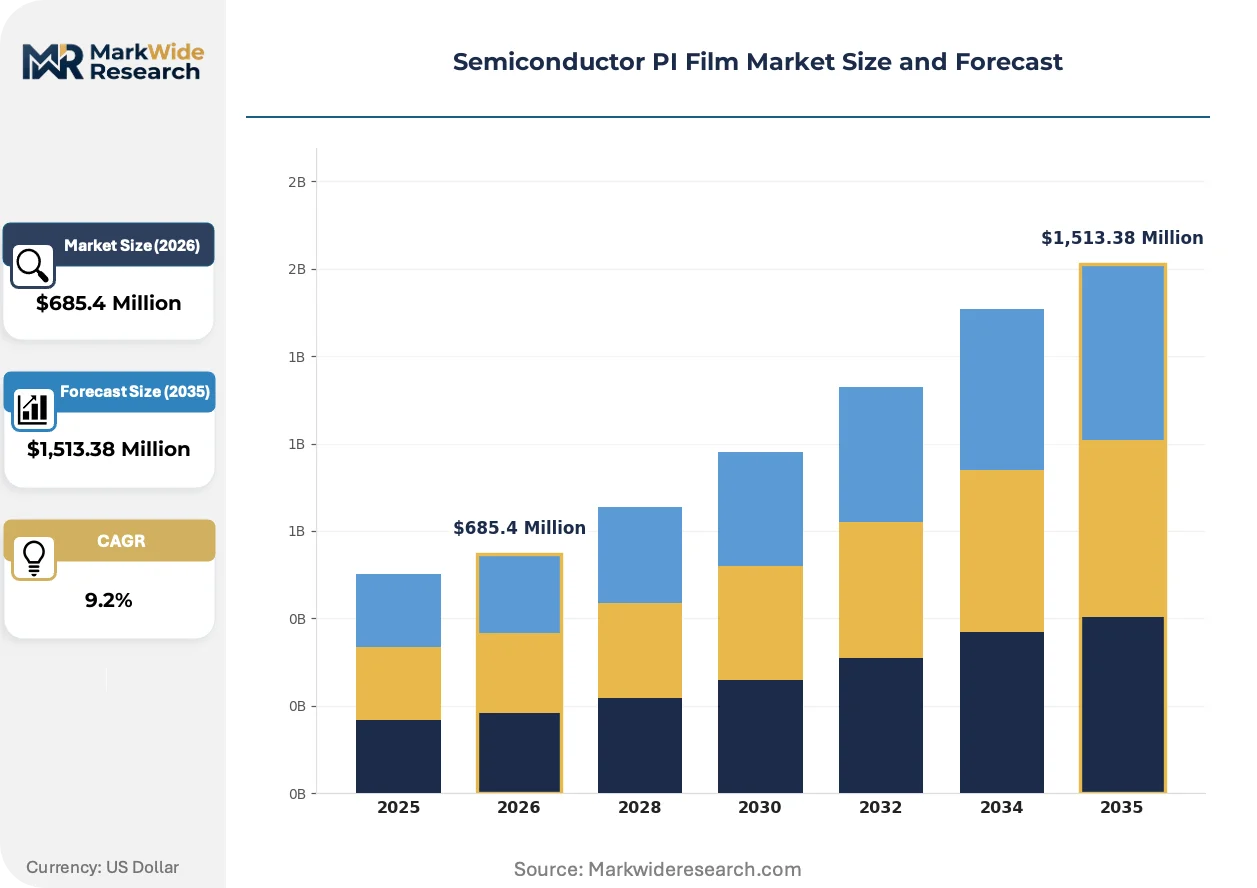
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,513.38 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Substrates, Multi-layer Films, Ultra-thin Films, Composite Films End User: Consumer Electronics, Telecommunications, Automotive Electronics, Aerospace Technology: Screen Printing, Roll-to-Roll Processing, Laser Patterning, Laminating Application: Display Panels, Sensors, Circuit Boards, Encapsulation |
| Companies Covered | Ube Industries, Rayitek, DuPont, Zhuzhou Times New Material Technology, Guilin Electrical Equipment Scientific Research Institute, Kaneka Corporation, Taimide Tech, Shenzhen Danbond Technology, PI Advanced Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor PI Film Market Trends and Innovations
Wafer-level processing workflows are compressing substrate thickness tolerances while regulatory fragmentation across Japan, Europe, and China forces parallel qualification tracks. Buyers now prioritize films with pre-certified multi-jurisdiction compliance.
Ultra-thin polyimide films below 10 micrometers are rewriting competitive positioning in redistribution layer applications. Advanced packaging houses at Samsung and SK Hynix are adopting these structures for chiplet architectures at accelerated qualification pace. This thickness reduction is rewriting margin pool distribution toward suppliers with captive monomer synthesis and precision coating scale.
EU REACH framework restrictions on specific dianhydride monomers are forcing polyimide precursor reformulations for components bound for European markets. ECHA substance evaluations are extending compliance timelines by 8-12 months for non-EU suppliers. Memory module producers serving EU automotive customers are responding by dual-approving Asian and European-qualified material streams.
Flexible substrate procurement is consolidating around specification bundles rather than discrete film grades. OSATs are displacing spot-buying with multi-year kit agreements covering buffer coatings, interlayer dielectrics, and carrier substrates. This pattern is most visible in South Korea's Pyeongtaek-Yongin corridor where Samsung's captive programs anchor volume commitments.
Semiconductor PI Film Market Segmentation
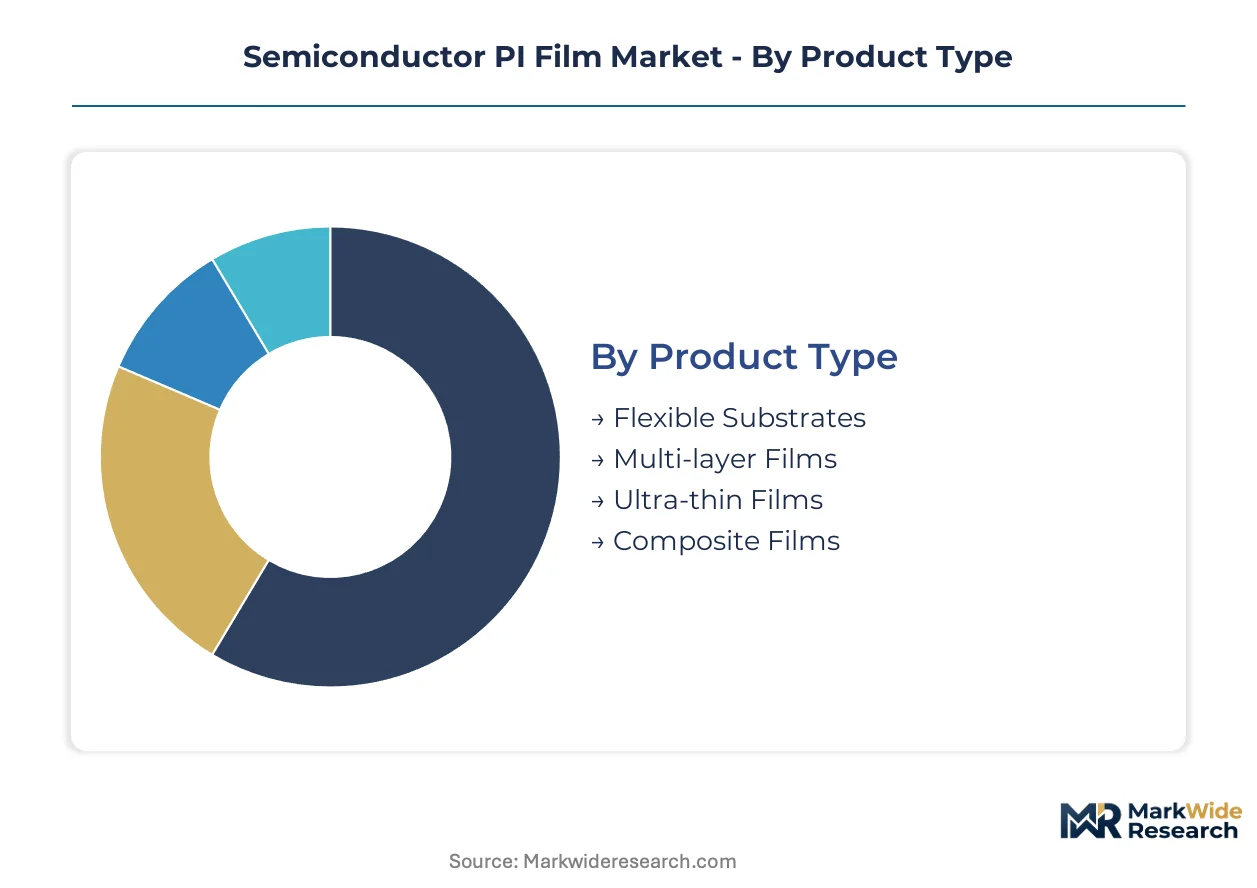
Semiconductor PI film procurement hinges on thermal specification matching against specific packaging workflows. Buyers segment demand by substrate flexibility requirements, end-use reliability standards, and processing technology compatibility rather than commodity-grade selection.
Product Type:
Cost tier determines supplier qualification pathways, with premium specifications commanding captive synthesis capabilities.
- Flexible Substrates:Aromatic polyimide layers engineered for thermal endurance exceeding 300 degrees Celsius serve as carrier substrates during wafer-level processing. Samsung and SK Hynix captive programs in South Korea's Pyeongtaek-Yongin corridor anchor volume demand for display driver IC packaging applications.
- Ultra-thin Films:Sub-10 micrometer structures capture expanding margin pools as chiplet architectures multiply redistribution layer counts. Advanced packaging houses requalify these films at unprecedented speed while managing dimensional stability constraints across etch-and-rinse cycles.
- Multi-layer Films:Stacked configurations with matched thermal expansion coefficients address heterogeneous integration requirements.
- Composite Films:Engineered surface chemistries optimize copper-polyimide adhesion strength for yield-critical applications.
Flexible substrates lead on scale; ultra-thin films lead on momentum.
End User:
Application reliability standards separate automotive-grade qualification from consumer-tier procurement.
- Consumer Electronics:Display driver IC packaging drives standardized film specifications with compressed lead times. Module producers prioritize roll-to-roll processing compatibility over custom thermal profiles.
- Automotive Electronics:Flip-chip ball grid array requirements impose stringent thermal stability benchmarks. DuPont's established specifications create template opportunities for suppliers targeting EU-bound automotive component flows.
- Telecommunications:Base station and infrastructure modules demand consistent dielectric performance across temperature cycling.
- Aerospace:Outgassing limits and thickness tolerance requirements align with JIS standards enforced by Japan's METI.
Consumer electronics leads on scale; automotive electronics leads on specification tightening.
Technology:
Volume throughput requirements favor continuous processing methods over batch-coating alternatives.
- Roll-to-Roll Processing:Continuous web widths exceeding legacy batch-coating capabilities anchor Kaneka Corporation's positioning at memory module production facilities. Capital-intensive facility upgrades constrain second-tier supplier entry.
- Laser Patterning:Precision ablation enables redistribution layer feature definition at chiplet-scale geometries. Packaging houses adopt this technology for ultra-thin film processing where mechanical patterning risks substrate damage.
- Screen Printing:Cost-efficient deposition for thick-film buffer coating applications with relaxed dimensional tolerances.
- Laminating:Multi-layer stack assembly for composite film construction in heterogeneous integration workflows.
Roll-to-roll processing leads on scale; laser patterning leads on technology advancement.
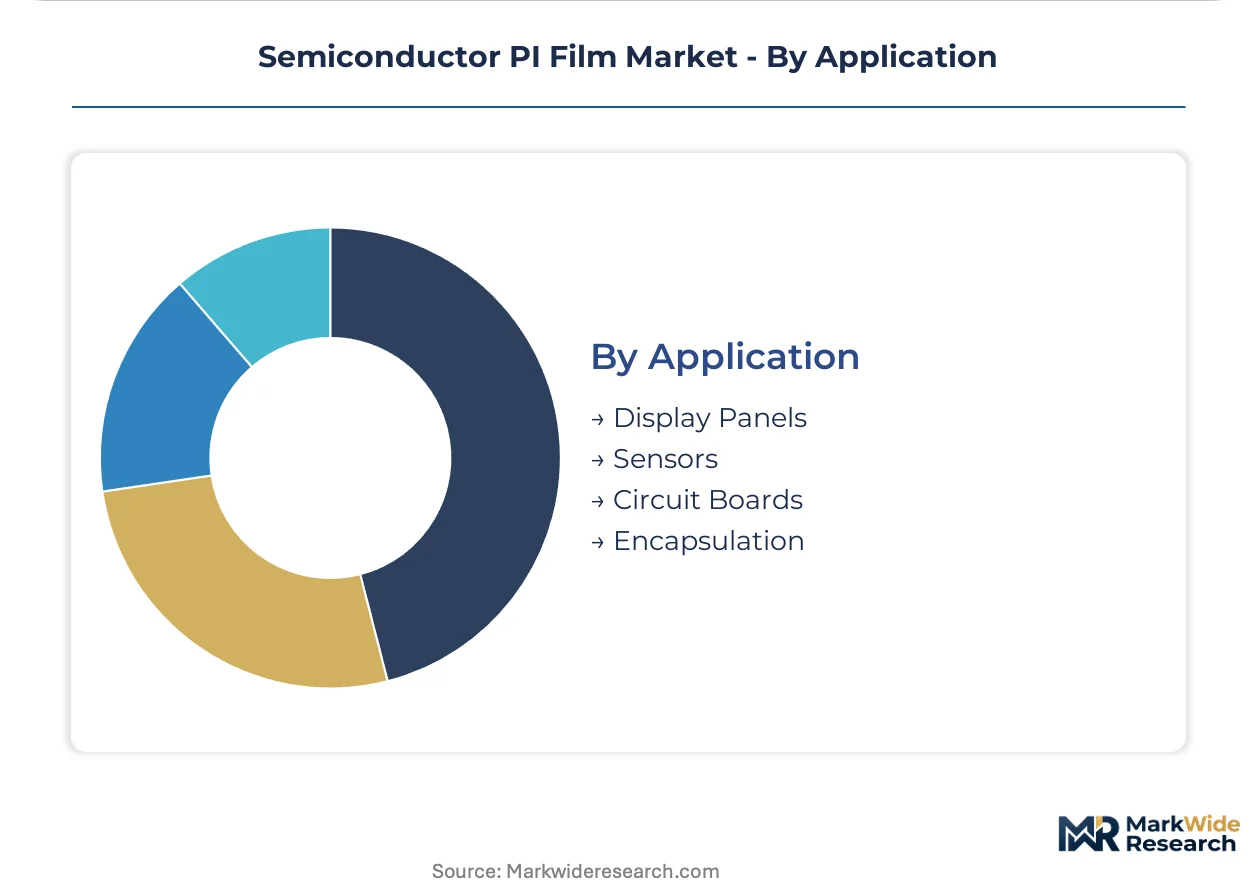
Application:
Redistribution layer complexity drives specification divergence between display-centric and logic-device requirements.
- Circuit Boards:Interlayer dielectric functions demand low dielectric constants near 3.4 with roadmap compression toward 3.2 for next-generation logic devices. IDM captive programs lock suppliers into 18-24 month validation cycles for new chemistries.
- Encapsulation:Buffer coating applications protect active devices from mechanical stress and environmental exposure. REACH and RoHS compliance tightening in Europe accelerates reformulation investments for polyimide precursor chemistries.
- Display Panels:Driver IC substrate requirements concentrate procurement around flexible film formats.
- Sensors:Miniaturized form factors drive ultra-thin film adoption with tight thickness tolerance specifications.
Circuit boards lead on scale; encapsulation leads on regulatory-driven specification change.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan pioneered polyimide chemistry for electronics in the 1960s, establishing the foundational synthesis routes that now dominate wafer-level processing workflows. South Korea and Taiwan subsequently scaled captive film production for memory and logic device packaging. Today procurement concentrates in three East Asian manufacturing corridors where thermal specification requirements exceed 300 degrees Celsius.
South Korea
Samsung and SK Hynix drive qualification programs for flexible substrates serving display driver IC packaging. The country's national semiconductor regulator enforces material purity standards aligned with EU REACH frameworks. The Pyeongtaek-Yongin corridor anchors volume demand as both IDMs expand captive film testing for chiplet redistribution layers.
Japan
METI enforces JIS standards for thickness tolerance and outgassing limits that gate supplier qualification at domestic IDMs. Japan's national chemical safety agency coordinates with ECHA on dianhydride monomer evaluations. The Chubu region around Nagoya hosts precision coating facilities serving automotive module producers with flip-chip ball grid array specifications.
China
Domestic fabs accelerate dual-source approval programs to reduce dependency on imported precursor chemistries. GB standards and SAMR certification protocols add parallel compliance tracks for equipment sold into Shanghai and Beijing facilities. The Yangtze River Delta concentrates advanced packaging houses scaling ultra-thin film adoption below 10 micrometers.
United States
IDMs in Arizona and Texas prioritize thermal stability specifications for heterogeneous integration stacks. The EPA monitors outgassing emissions from polyimide precursor manufacturing under Clean Air Act provisions. California's semiconductor design clusters pull film procurement toward low dielectric constant specifications approaching 3.2 for next-generation logic devices.
Germany
Automotive electronics suppliers demand REACH-compliant reformulations for EU-bound component flows. The KBA coordinates with ECHA on substance restrictions affecting dianhydride monomer imports. Bavaria's industrial corridor hosts packaging houses dual-approving Asian and European-qualified material streams for memory modules serving continental OEMs.
Semiconductor PI Film Market Competitive Landscape
Premium-margin players sit above commodity-margin players across thermal specification and captive synthesis capabilities. The vendor base organizes into three tiers: Japanese chemical conglomerates with backward integration into monomer production, Korean and Taiwanese roll-to-roll specialists, and Chinese regional fabricators serving domestic qualification programs. Strategic moves center on capacity expansion for sub-10 micrometer films and geographic diversification of precursor supply.
Among Japanese chemical conglomerates, Ube Industries and Kaneka Corporation occupy positions reflecting captive polyimide monomer synthesis capabilities. DuPont exemplifies the specification-driven archetype through thermal stability benchmarks. These three anchors represent distinct competitive vectors: upstream chemical control, continuous processing scale, and application-specific performance validation.
| Leading Market Players |
|---|
| Ube Industries |
| Rayitek |
| DuPont |
| Zhuzhou Times New Material Technology |
| Guilin Electrical Equipment Scientific Research Institute |
| Kaneka Corporation |
| Taimide Tech |
| Shenzhen Danbond Technology |
| PI Advanced Materials |
| Others |
Pricing and Supply Chain Analysis
Roll-to-roll processing scale requirements are simultaneously compressing unit economics at legacy batch-coating facilities and concentrating procurement leverage among Japanese and Korean suppliers with continuous web capabilities. This production-method transition feeds directly into pricing power asymmetries between captive synthesis operators and second-tier fabricators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates JIS-REACH-RoHS certified films from regional-grade alternatives and commodity spot purchases. Price differentiation rests on thermal specification grade and volume commitment scale, with automotive module producers least sensitive and display driver IC packagers most responsive to per-unit fluctuations. Cost compression in standard-grade films is intensifying because Chinese domestic fabs accelerate dual-source approval programs. Premium-tier suppliers with captive monomer synthesis maintain pricing leverage against margin erosion.
Supply Chain Analysis
Regional distribution centers in Nagoya, Pyeongtaek, and Shanghai anchor hub-and-spoke patterns serving East Asian packaging corridors. Supply concentration centers on Japan, South Korea, and China, with dianhydride monomer, polyimide precursor, and precision coating equipment as critical input dependencies. Single-source vulnerability risks concentrate at Japanese chemical conglomerates controlling captive synthesis routes. Distribution runs through IDM captive programs and OSAT kit agreements rather than spot-market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Ultra-thin film adoption below 10 micrometers opens margin expansion as chiplet architectures multiply layer counts and qualification premiums concentrate among synthesis-integrated suppliers.
For Market Incumbents: Hedge against European reformulation costs by pre-qualifying REACH-compliant precursor streams before ECHA evaluation timelines extend. Lock Pyeongtaek-Yongin corridor volume through multi-year kit agreements covering buffer coatings and interlayer dielectrics. Backward integration into dianhydride monomer production defends margin position against Asian chemical conglomerate supply leverage. For New Entrants and Emerging Players: Laser patterning compatibility for sub-10 micrometer redistribution layers offers a technology-first wedge into advanced packaging houses requalifying at accelerated pace. Target automotive electronics module producers in Germany's Bavarian corridor seeking second-tier alternatives to DuPont thermal specifications. Lead with pre-certified multi-jurisdiction compliance bundles rather than discrete film grades. For Investors and Strategic Acquirers: Valuations sit cheapest among Chinese regional fabricators with SAMR certification progress but incomplete GB standard alignment. Five-to-ten year viability hinges on capturing share in domestic fab dual-source programs before captive synthesis investments mature. Watch ECHA substance evaluation timelines as inflection indicators for European-bound component flow restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Synthesis | Ube Industries' captive polyimide precursor production secures supply continuity for logic-device customers. |
| Multi-Jurisdiction Certification Pre-Qualification | Films meeting combined JIS-REACH-RoHS criteria gate supplier access to Samsung and SK Hynix programs. |
| Roll-to-Roll Capacity Expansion | Kaneka Corporation's continuous web scale anchors positioning at memory module production facilities. |
| Laser Patterning Technology Adoption | Precision ablation enables chiplet-scale redistribution layer feature definition without substrate damage risk. |
| Modular Film Kit Agreement Structuring | OSAT procurement displacement of spot-buying locks multi-year volume commitments across layer stacks. |
Research Methodology
Bottom-up packaging workflow modeling reconciled against top-down precursor chemistry production tracking forms the analytical core of this study. Primary interviews with IDM materials qualification managers, OSAT procurement directors, polyimide precursor R&D leads, and semiconductor equipment sales engineers combined with secondary validation from customs trade data, METI JIS standard filings, ECHA substance evaluation registers, and SEC 10-K chemical segment disclosures. Triangulation between end-use demand signals and supply-side capacity announcements grounds forecast integrity.
Input-output matrices map wafer-level packaging layer counts through redistribution layer complexity tiers, thermal specification grades, and regional regulatory compliance clusters across the analysis window. Segmentation dimensions include substrate flexibility requirements, end-use reliability standards, processing technology compatibility, and application-specific dielectric performance. CAGRs derive from shipment volume trajectories reconciled against capital expenditure announcements and IDM captive program timelines. Forecast inputs incorporate chiplet architecture adoption curves and REACH reformulation investment cycles.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ECHA dianhydride monomer restriction decisions and Chinese domestic fab import substitution acceleration. Outputs reflect documented assumptions around qualification timeline stability and precursor chemistry innovation rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Semiconductor Silicon Material Market
Semiconductor Material
Global Silicon Carbide (SIC) Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Semiconductor Materials Market
Semiconductor Material
Electroceramics Market
Semiconductor Material
Titanium Diboride Market
Semiconductor Material
5G Substrate Materials Market
Semiconductor Material
Silicon Metal Market
Semiconductor Material
Synthetic Single Crystal Diamond Market
Semiconductor Material
Quartz Crucible Market
Semiconductor Material
United States Sapphire Glass Market
Semiconductor Material
Asia Pacific Graphene Market
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Electronic Circuit Board Level Underfill Material Market
Semiconductor Material
Niobium Hydride Market