
 Electronic Circuit Board Level Underfill Material Market | 2026-2036
Electronic Circuit Board Level Underfill Material Market Size, Share, and Industry Trends Forecast 2026-2036
Electronic Circuit Board Level Underfill Material Market Analysis
Specialty chemical distribution is fragmenting as regional distributors compete with direct manufacturer portals for board-level material procurement. Henkel sustains technology leadership through its broad epoxy underfill portfolio and captive R&D labs in Germany and the United States. Namics Corporation anchors Asian supply chains with Japan-centered manufacturing and JIS-standard formulations for high-reliability applications.
Electronic circuit board level underfill material denotes a liquid encapsulant, typically an epoxy resin with silica filler loading between fifty and eighty percent by weight, dispensed beneath flip-chip die to mitigate thermal-mechanical stress from coefficient of thermal expansion mismatches between silicon and organic substrates. The material cures to a rigid solid that redistributes solder joint strain and extends fatigue life under temperature cycling. Epoxy formulations dominate current volume owing to established adhesion profiles and compatibility with standard reflow profiles, while silicone underfills capture premium segments demanding broader operational temperature ranges for automotive modules. Mobile devices represent the largest application consumption pool, though medical devices command superior margins due to biocompatibility testing and lot traceability requirements.
EPA regulations in the United States restrict volatile organic compound emissions from solvent-based formulations, compelling suppliers to validate water-borne or one hundred percent solid systems. ECHA REACH registration requirements govern substance import thresholds into Europe, directly affecting Asian formulators without EU-based blending capacity. ISO 10993 biocompatibility standards shape medical device qualification pathways and extend product development timelines. Stakeholders must monitor evolving halogen-free mandates across multiple jurisdictions and assess whether captive compounding or toll manufacturing better serves regional compliance obligations.
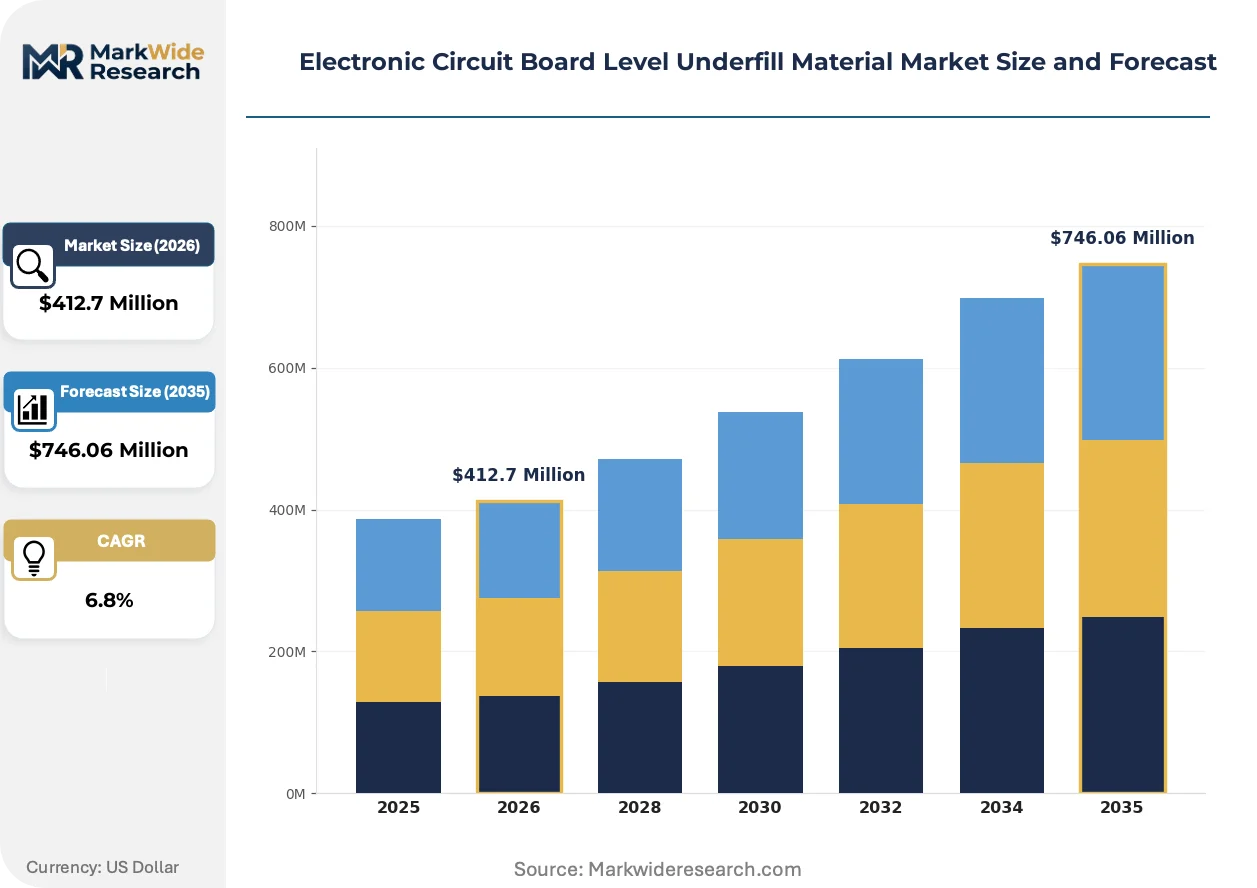
Market Dynamics
Flip-chip package miniaturization is compressing solder joint spacing below 40 microns, forcing underfill formulators to engineer ultra-low viscosity epoxies that penetrate narrower gaps without void formation.
Growth Catalysts
- RoHS and REACH compliance mandates:European electronics assemblers now specify halogen-free underfill systems, expanding addressable demand for epoxy formulators with ECHA-registered substances.
- Automotive module thermal cycling:ADAS controllers and power inverters require silicone underfills rated to 175°C continuous operation, creating premium application tiers beyond mobile devices.
- Shenzhen-Dongguan cluster concentration:Contract manufacturers in these Pearl River Delta cities procure underfill in 10,000-liter bulk totes, driving volume economics for qualified suppliers.
Market Restraints
- Silica filler cost volatility:Fused silica prices fluctuate with semiconductor-grade quartz mining output, squeezing margin on 70-80% loaded formulations.
- Japan-centered specialty resin supply:Hydrogenated bisphenol-A epoxies for low-alpha particle underfills source predominantly from Kansai-region chemical complexes, creating geographic concentration risk.
- Thermal expansion coefficient floor:Epoxy-silica composites cannot practically drop below 25 ppm/°C, limiting fatigue life extension for large-die flip-chip packages exceeding 15mm edge length.
Strategic Opportunities
- India EMS expansion:Foxconn and Dixon Electronics underfill demand in Tamil Nadu and Karnataka is outpacing qualified local blending capacity.
- Water-borne formulation validation:EPA VOC restrictions are accelerating supplier qualification of aqueous epoxy dispersions for US-based assembly operations.
- Medical device biocompatibility tier:ISO 10993-5 and -10 tested underfills command 3-4x standard pricing for implantable diagnostic modules.
Industry Challenges
- Dispense process engineering talent scarcity:Jetting equipment programming for 50-micron dot volumes requires specialized technicians concentrated in Taiwan and South Korea.
- Dual-cure formulation IP complexity:UV-thermal sequential cure patents held by adhesive multinationals complicate independent development of snap-cure underfills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electronic Circuit Board Level Underfill Material Market |
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $746.06 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Silicone, Polyurethane, Others End User: Consumer Electronics, Automotive, Aerospace, Industrial Application: Mobile Devices, Computers, Wearables, Medical Devices Distribution Channel: Online, Direct Sales, Distributors, Retail |
| Companies Covered | Henkel, Namics Corporation, AI Technology, H.B. Fuller, Protavic America, Showa Denko Materials, Zymet, MacDermid Alpha, Epoxy Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electronic Circuit Board Level Underfill Material Market Emerging Trajectories
Material science advances and regulatory tightening are converging to reshape underfill specification criteria, with performance validation now extending beyond standard thermal cycling to encompass chemical compliance and circularity metrics.
Capillary underfill is collapsing the processing window for high-density interconnect assemblies. This liquid epoxy technology wicks beneath 25-micron gap flip-chip die through passive flow rather than pressure-assisted dispense. Smartphone original design manufacturers in China are adopting it for flagship system-in-package modules. The elimination of post-dispense flow time is collapsing total underfill process steps from five to three, compressing capital equipment requirements for new assembly lines.
REACH SVHC candidate list expansion is accelerating substitution of bisphenol-A derived epoxy monomers. ECHA added several diglycidyl ether derivatives to the January 2024 update, triggering reformulation programs across European electronics supply chains. Medical device and automotive module assemblers are responding fastest, specifying alternative cycloaliphatic epoxy backbones in new procurement tenders to preempt authorization requirements.
Direct manufacturer technical service portals are displacing traditional specialty chemical distribution for qualified buyers. Large contract manufacturers in Taiwan and Mexico now access formulation databases, cure profile calculators, and regulatory documentation through supplier-hosted platforms rather than distributor field representatives. This channel compression is most visible in high-volume mobile device assembly, where procurement teams self-serve technical specifications for qualified underfill grades without intermediary validation steps.
Electronic Circuit Board Level Underfill Material Market Segmentation
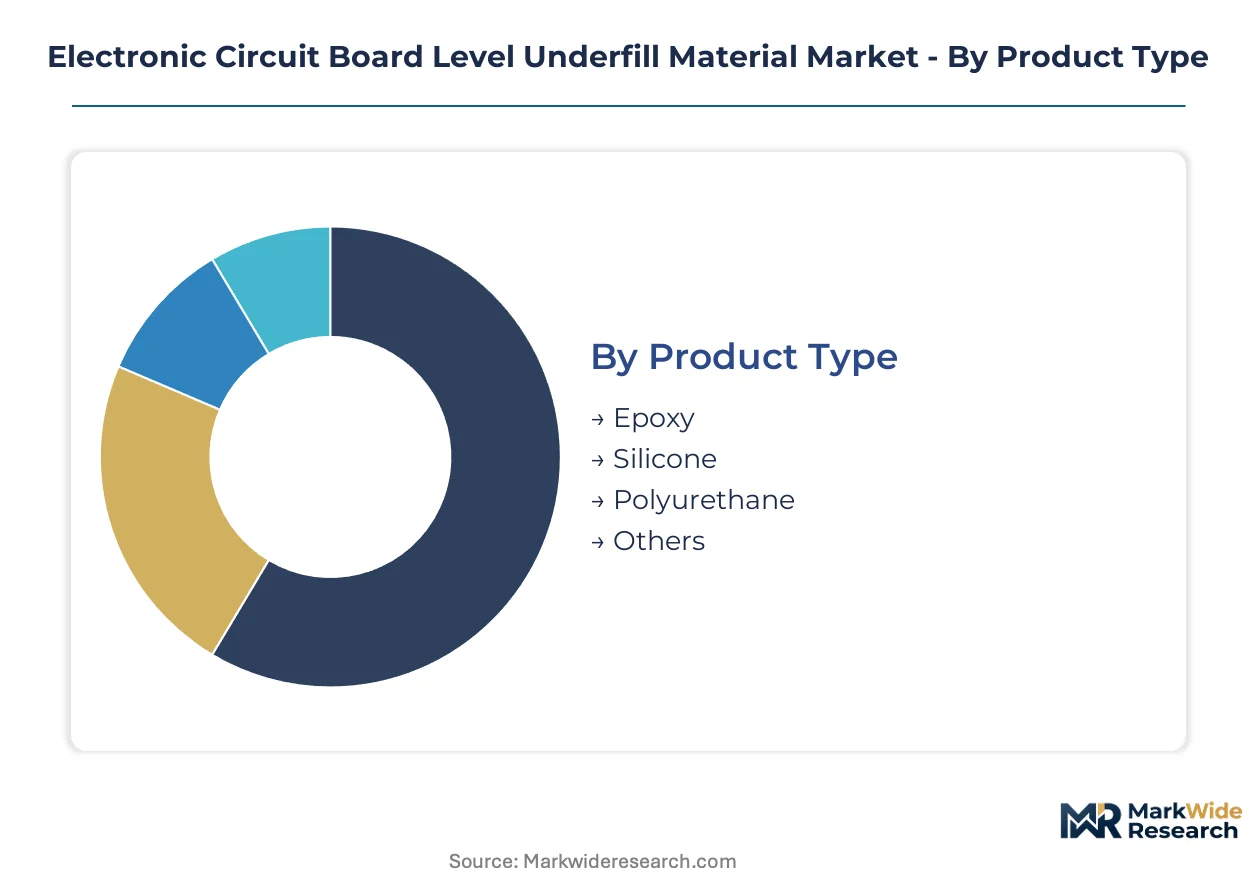
Underfill material specifications diverge sharply across end-use applications, with thermal cycling requirements and regulatory compliance tiers creating distinct procurement behaviors. Segmentation reveals where formulation complexity commands premium pricing versus where volume procurement drives standardization.
Product Type:
After-sales technical service intensity escalates with formulation complexity, as epoxy systems require standard cure profile support while silicone and polyurethane grades demand application engineering for thermal management optimization.
- Epoxy:Silica-filled thermoset systems with 50-80% filler loading by weight dominate mobile device assembly through established adhesion to organic substrates and compatibility with standard reflow profiles. Shenzhen and Dongguan contract manufacturers procure this grade in 10,000-liter bulk totes, compressing per-unit costs through volume aggregation.
- Silicone:Flexible elastomeric formulations rated to 175°C continuous operation capture automotive ADAS controller and power inverter applications where thermal expansion accommodation exceeds epoxy capability. Premium positioning reflects hydrogenated resin feedstock costs and specialized cure validation protocols.
- Polyurethane:Moisture-cure systems serve select industrial module applications requiring ambient temperature processing without reflow oven exposure.
- Others:Emerging acrylate and cyanate ester chemistries address niche hermetic sealing requirements in aerospace-qualified assemblies.
By volume, Epoxy leads. By growth pace, Silicone is ahead.
End User:
Cost tier stratification separates qualification-intensive segments from price-sensitive procurement pools, with medical and aerospace applications absorbing 3-4x standard pricing for biocompatibility and traceability documentation.
- Consumer Electronics:Smartphone and tablet manufacturers drive the largest absolute consumption through flip-chip and system-in-package module assembly. REACH and RoHS compliance mandates in Europe are accelerating halogen-free epoxy adoption across this segment.
- Automotive:ADAS controllers, battery management systems, and power inverters require underfills validated to AEC-Q100 thermal cycling standards. Silicone formulations are displacing epoxies in under-hood applications where 150°C ambient exposure is routine.
- Aerospace:Satellite and avionics modules specify low-outgassing formulations with lot-level resin pedigree documentation, extending procurement cycles and insulating suppliers from price competition.
- Industrial:Factory automation controllers and power supply modules prioritize cost efficiency over thermal extremes, accepting standard epoxy grades with abbreviated qualification pathways.
Consumer Electronics absorbs the highest tonnage. Automotive is expanding most quickly.
Application:
Customer type concentration shapes technical support models, with mobile device original design manufacturers self-serving through supplier portals while medical device assemblers require field application engineering for ISO 10993 qualification support.
- Mobile Devices:System-in-package and flip-chip smartphone modules are adopting capillary underfill technologies that collapse process steps from five to three. Foxconn and Dixon Electronics procurement in India is outpacing qualified local blending capacity.
- Computers:Server and laptop motherboard assembly consumes mid-viscosity epoxies for ball grid array reinforcement, with procurement concentrated in Taiwan and Mexico contract manufacturing hubs.
- Wearables:Miniaturized fitness trackers and hearing aids drive demand for ultra-low viscosity formulations penetrating sub-40 micron gaps.
- Medical Devices:Implantable diagnostic modules command the steepest pricing tier, with ISO 10993-5 and -10 cytotoxicity testing extending development timelines and creating supplier stickiness.
Mobile Devices represents the largest revenue pool. Medical Devices shows the steepest margin expansion.
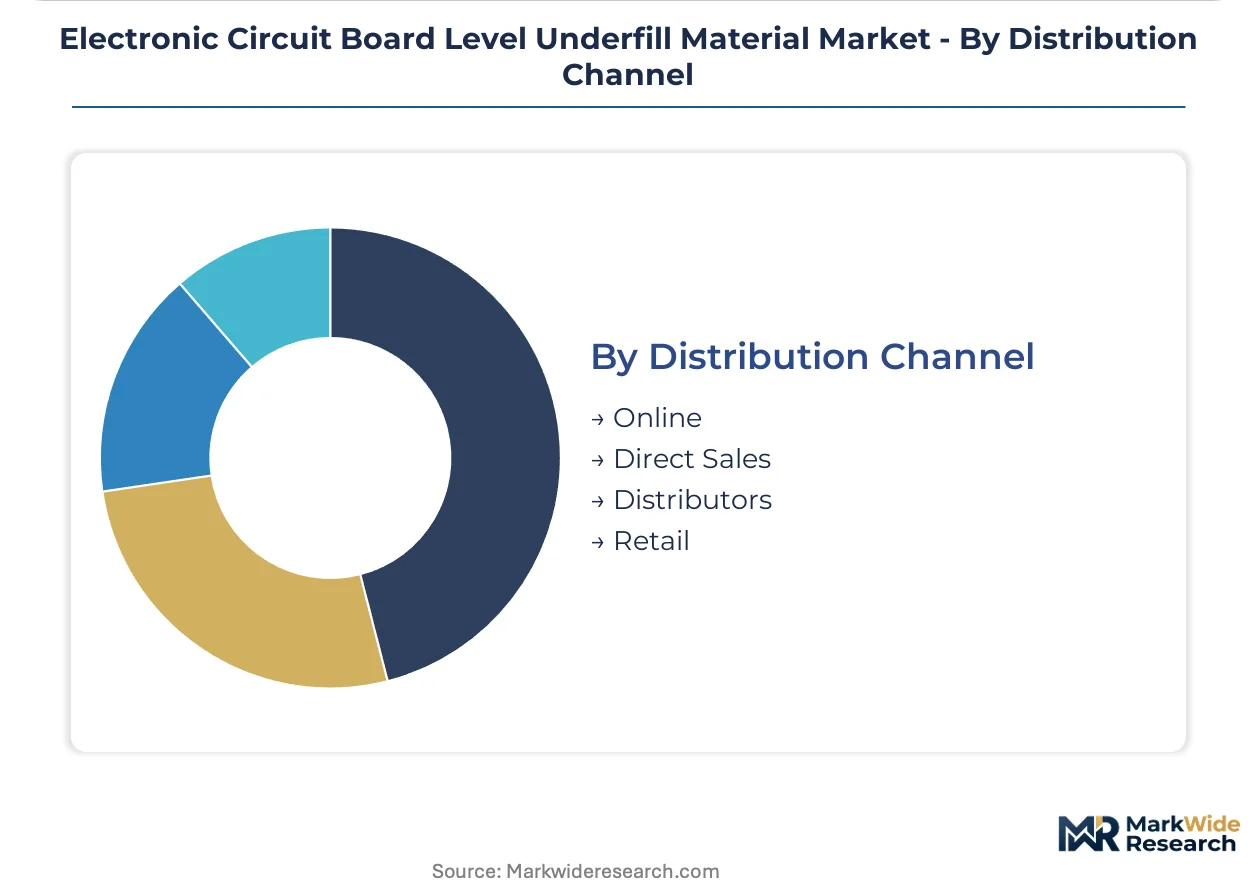
Distribution Channel:
Supply concentration in Japan-centered specialty resin production is compressing channel options for hydrogenated bisphenol-A epoxies, while standard grades fragment across multiple procurement pathways.
- Direct Sales:Large contract manufacturers in Taiwan and Mexico access formulation databases and regulatory documentation through supplier-hosted technical service portals, displacing traditional field representative relationships.
- Distributors:Regional specialty chemical distributors retain relevance for mid-volume assemblers requiring local inventory and mixed-product procurement efficiency.
- Online:Qualified buyers in high-volume mobile device assembly self-serve technical specifications through manufacturer e-commerce platforms for approved underfill grades.
- Retail:Limited to small-lot maintenance and repair operations outside mainstream electronics manufacturing supply chains.
Direct Sales captures the highest value per transaction. Online is gaining share fastest among qualified procurement teams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA REACH compliance anchors European procurement standards, while Shenzhen-Dongguan procurement clusters drive volume economics in Asia. EPA VOC restrictions and emerging India EMS expansion create divergent qualification pathways across manufacturing geographies.
China
Shenzhen and Dongguan contract manufacturers procure underfill in 10,000-liter bulk totes for mobile device assembly. MIIT dual carbon goals pressure formulators toward lower-emission epoxy systems. The Pearl River Delta electronics cluster dominates flip-chip module production for smartphone original design manufacturers.
United States
EPA volatile organic compound regulations restrict solvent-based formulations, compelling water-borne system validation. FDA ISO 10993 biocompatibility standards govern medical device underfill qualification. Texas and Arizona semiconductor packaging facilities are expanding epoxy underfill consumption for advanced computing modules.
Germany
Automotive ADAS controller manufacturers specify silicone underfills rated to 175°C continuous operation. ECHA REACH SVHC candidate list expansion triggers bisphenol-A epoxy substitution programs. Bavaria-centered captive R&D labs develop halogen-free formulations for European electronics assemblers.
Japan
Hydrogenated bisphenol-A epoxy feedstocks for low-alpha particle underfills concentrate in Kansai-region chemical complexes. METI JIS standards shape high-reliability formulation specifications. Tokyo and Osaka electronics clusters demand lot-level resin pedigree documentation for satellite module applications.
India
Foxconn and Dixon Electronics underfill demand in Tamil Nadu and Karnataka outpaces qualified local blending capacity. BIS standards compliance creates entry barriers for imported formulations. The Sriperumbudur electronics manufacturing cluster is expanding system-in-package module assembly for mobile device export markets.
Electronic Circuit Board Level Underfill Material Market Vendor Landscape
Integrated material formulators and specialty adhesive specialists split the market across technology tiers. Three to five multinational chemical conglomerates anchor premium segments through captive R&D infrastructure, while regional compounders compete on bulk epoxy pricing for high-volume mobile device procurement. Competitive moves concentrate on halogen-free formulation validation and direct technical service portal deployment to displace distributor relationships.
Among Germany-based chemical conglomerates, Henkel occupies a position exemplifying broad epoxy underfill portfolio coverage. Namics Corporation represents Japan-centered manufacturing archetypes with JIS-standard formulation specialization. H.B. Fuller anchors North American adhesive supplier positioning across industrial electronics segments.
| Leading Market Players |
|---|
| Henkel |
| Namics Corporation |
| AI Technology |
| H.B. Fuller |
| Protavic America |
| Showa Denko Materials |
| Zymet |
| MacDermid Alpha |
| Epoxy Technology |
| Others |
Supply Flow & Price Mechanics
Hydrogenated bisphenol-A epoxy feedstock concentration in Japan's Kansai region funnels margin capture toward specialty resin suppliers while downstream formulators absorb silica filler cost volatility. Medical device assemblers paying 3-4x standard pricing for ISO 10993-qualified grades demonstrate where certification barriers erect the steepest margin pools.
Pricing Analysis
Geographic price spreads of 15-25% separate European REACH-compliant halogen-free formulations from standard epoxy grades procured in Shenzhen-Dongguan bulk totes. Three-tier pricing structure across medical certification, automotive thermal rating, and consumer electronics standard levels reflects divergence in testing burden and after-sales technical intensity. Cost compression in high-volume mobile device tiers intensifies as Foxconn and Dixon Electronics aggregate 10,000-liter procurement volumes. Contract manufacturers in Taiwan and Mexico exhibit lowest price sensitivity through direct technical portal relationships, while Indian EMS operations face premium pricing until qualified local blending capacity scales.
Supply Chain Analysis
Export control regimes on semiconductor-grade fused silica constrain flows from designated mining jurisdictions, compressing availability for 70-80% loaded formulations. Supply concentrates in Japan for hydrogenated specialty epoxies, China for silica filler processing, and Germany for halogen-free catalyst systems. Raw material dependencies rest on semiconductor-grade quartz mining, hydrogenated bisphenol-A resin synthesis, and amine hardener petrochemical feedstocks. Single-source vulnerability pervades low-alpha particle underfill grades tethered to Kansai-region chemical complexes. Distribution runs through direct manufacturer technical portals for qualified high-volume buyers, with regional specialty distributors serving mid-tier assemblers requiring local inventory buffers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle recovery as smartphone original design manufacturers restock system-in-package module inventories following 2023-2024 demand contraction. Flip-chip miniaturization below 40-micron gaps sustains formulation refresh cycles regardless of macroeconomic headwinds.
For Market Incumbents: Entrench technology leadership through captive R&D lab expansion in Bavaria and Arizona to preempt REACH SVHC substitution windows. Defensive patent thicketing around UV-thermal sequential cure formulations blocks emerging competitor access to snap-cure segments. Accelerate direct technical portal deployment to displace distributor relationships in Taiwan and Mexico contract manufacturing hubs.
For New Entrants and Emerging Players: Tamil Nadu and Karnataka EMS corridors represent the most penetrable entry point where Foxconn and Dixon Electronics procurement outpaces qualified local blending capacity. Water-borne epoxy validation for EPA VOC compliance offers a regulatory-forced substitution angle in US-based assembly operations. Pursue toll manufacturing partnerships with established resin compounders rather than greenfield capacity investment.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty adhesive portfolios holding JIS-standard formulation capabilities but lacking REACH-registered European substance dossiers. Long-term viability hinges on halogen-free epoxy transition completion and medical device biocompatibility tier penetration. Watch ECHA SVHC candidate list expansion velocity as the inflection signal forcing accelerated bisphenol-A substitution programs.
| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Registered Substance Dossier Expansion | ECHA compliance unlocks European electronics assembler procurement tenders for halogen-free grades. |
| Direct Technical Portal Deployment | Taiwan and Mexico contract manufacturers self-serve specifications, compressing distributor margin capture. |
| India Local Blending Capacity Buildout | Tamil Nadu and Karnataka EMS demand outpaces qualified supply, creating first-mover positioning. |
| Water-Borne Formulation Validation | EPA VOC restrictions accelerate supplier qualification for US-based mobile device assembly operations. |
| ISO 10993 Biocompatibility Tier Investment | Medical device underfills command 3-4x standard pricing through cytotoxicity testing barriers. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with formulation chemists, EMS procurement directors, and semiconductor packaging engineers; and secondary validation through SEC 10-K filings, customs trade data, and ECHA REACH registration databases. Bottom-up triangulation aggregated individual product-grade consumption estimates across epoxy, silicone, and polyurethane chemistries. Top-down verification cross-checked against aggregate electronics assembly output from Shenzhen-Dongguan, Taiwan, and Mexico manufacturing clusters.
Forecast inputs considered flip-chip package miniaturization trajectories, REACH SVHC candidate list expansion schedules, and India EMS capacity buildout timelines across the projection horizon. Segmentation modeling spanned chemistry type, thermal rating tier, end-use application, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to volume-weighted average pricing by segment. Industry-specific inputs included silica filler loading ratios, reflow profile compatibility windows, and biocompatibility testing duration assumptions.
Practitioners should monitor ECHA authorization list updates, India BIS standards implementation, and EPA VOC rulemaking for early signals of forecast revision triggers. Material shifts in hydrogenated bisphenol-A resin supply availability or REACH SVHC regulatory thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Methyl Phenyl Silicone Resin Market
Semiconductor Material
Hafnium Market
Semiconductor Material
DCB and AMB Substrate Market
Semiconductor Material
Semiconductor Glass Wafer Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Rhenium Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Organic Silicon Coating Market
Semiconductor Material
LED Materials Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Silicon Dioxide Market
Semiconductor Material
Sputtering Target Market
Semiconductor Material
Solar Silicon Ingots Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Transparent Conductive Films Market
Semiconductor Material
Polycrystalline Silicon Market