
 Acetylene Black Market | 2026-2036
Acetylene Black Market Size, Share, and Industry Trends Forecast 2026-2036
Acetylene Black Market Analytics
ISO 9001 certification is bifurcating the competitive landscape into qualified suppliers and marginal participants. Denka Company Limited leverages its Japanese manufacturing base to sustain premium positioning in conductive grades. Birla Carbon anchors volume supply through integrated carbon black operations spanning multiple continents. Orion Engineered Carbons S.A. differentiates via specialized acetylene black formulations for battery cathode applications.
Acetylene black is a high-purity carbon black produced through acetylene gas thermal decomposition, characterized by extremely fine particle size below 35 nanometers and exceptional electrical conductivity exceeding 100 S/cm. Manufacturers deploy it primarily as a conductive additive in lithium-ion battery electrodes and high-performance rubber compounds. Conductive acetylene black commands the largest volume share as battery manufacturers standardize on this grade for cathode formulations. Specialty acetylene black captures expanding margin pools where aerospace and medical electronics buyers require ultra-low metal contamination. Battery manufacturing applications outpace rubber production growth as electric drivetrain demand reshapes material procurement priorities.
REACH registration requirements in Europe and China's GB/T standards for battery materials govern product composition thresholds and market access conditions. The EPA oversees particulate emissions from acetylene decomposition facilities in the United States, raising capital requirements for new production capacity. Battery makers and carbon black producers must monitor evolving purity specifications from cell manufacturers and national regulators to secure long-term supply agreements.
Market Dynamics
Electric vehicle battery cathode specifications are tightening purity thresholds faster than incumbent acetylene black production lines can recalibrate, forcing capacity decisions before demand curves fully materialize.
Growth Catalysts
- GB/T 30835-2014 battery material standards:China's purity mandates for lithium-ion cathode additives are disqualifying lower-grade conductive carbons from cell manufacturer qualification lists.
- Silicon-anode blending:Battery engineers are incorporating higher silicon loadings in graphite anodes, requiring elevated conductive additive ratios to maintain electrode integrity.
- Daesan and Ulsan manufacturing corridors:South Korean cathode production clusters are concentrating procurement volumes among qualified acetylene black suppliers with ISO 9001 certification.
Market Restraints
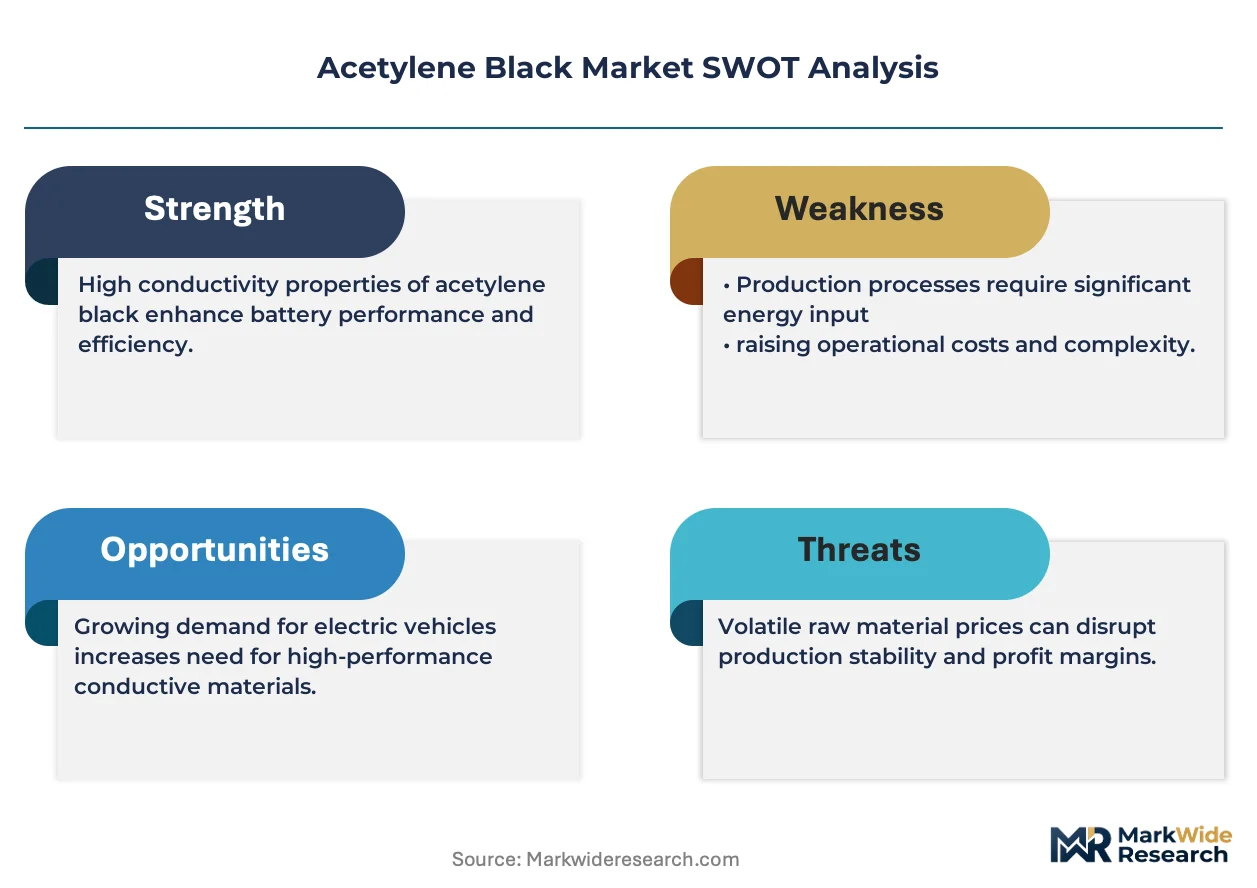
- Acetylene feedstock volatility:Calcium carbide production economics swing with electricity pricing in Chinese manufacturing provinces, transmitting cost instability through the supply chain.
- Single-source decomposition technology:Thermal cracking reactor designs remain concentrated among engineering licensors, limiting new entrant process validation pathways.
- Super-P carbon black substitution:Battery makers are qualifying lower-cost furnace black alternatives for mid-tier energy storage applications where conductivity margins permit.
Strategic Opportunities
- US Inflation Reduction Act domestic content credits:Cell manufacturers are reshoring cathode production to capture tax incentives, creating qualification windows for North American acetylene black capacity.
- Solid-state battery electrolyte interfaces:Next-generation cell architectures require specialized conductive additives compatible with sulfide and oxide solid electrolytes.
- Direct-to-cathode-plant distribution:Bypassing regional distributors through dedicated bulk silo installations at battery cell facilities is compressing logistics costs and qualification timelines.
Industry Challenges
- ISO 9001:2015 transition audits:Certification bodies are extending review cycles for carbon black facilities, delaying supplier approval for time-sensitive cathode line ramp schedules.
- Legacy furnace black integration:Rubber compounders seeking conductive grade upgrades face formulation revalidation costs that stall specification changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acetylene Black Market |
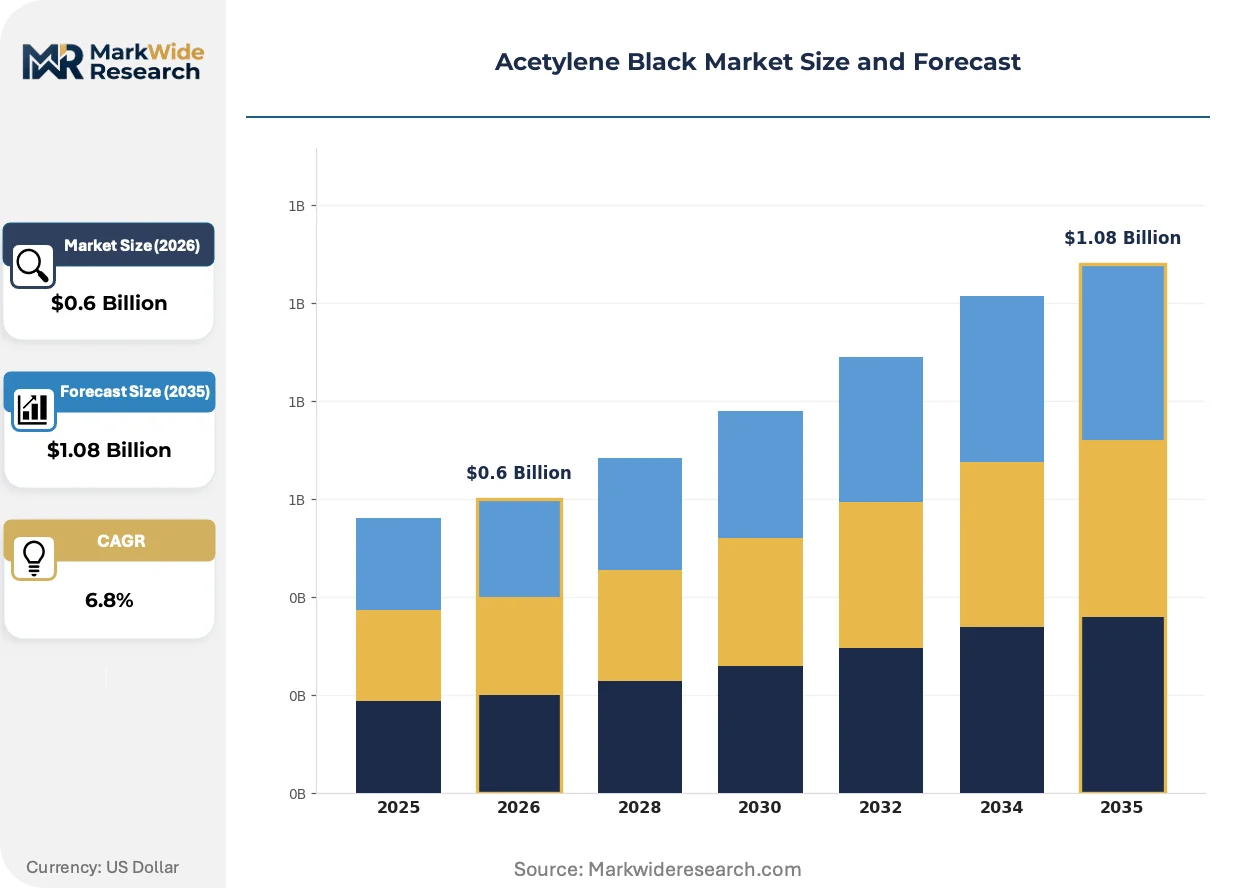
| Market Size in 2026 | $0.6 Billion |
| Market Size in 2035 | $1.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated Acetylene Black, Conductive Acetylene Black, Specialty Acetylene Black, Uncoated Acetylene Black Application: Battery Manufacturing, Rubber Production, Coatings, Plastics End User: Automotive, Electronics, Consumer Goods, Aerospace Distribution Channel: Online Retail, Wholesalers, Direct Sales, Distributors |
| Companies Covered | Birla Carbon, Jinhua Chemical Co. Ltd., Denka Company Limited, Phillips Carbon Black Limited, Mitsubishi Chemical Corporation, Orion Engineered Carbons S.A., Hexing Chemical Industry Co. Ltd., Tokai Carbon Co. Ltd., Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acetylene Black Market Evolving Landscape
Battery cathode chemistry evolution is fragmenting the conductive additive specification landscape, with performance thresholds diverging between automotive power cells and grid storage applications.
Ultra-high purity acetylene black with metal contamination below 10 ppm is displacing standard conductive grades in nickel-rich NMC cathode formulations. Korean cathode manufacturers are mandating this specification for 800-volt automotive platforms. The displacement is compressing margins for producers lacking hydrometallurgical purification capabilities.
REACH SVHC candidate list expansion is forcing European battery material importers to document carbon black impurity profiles at the nanoparticle level. ECHA notification requirements are extending lead times for non-EU suppliers by 8-14 weeks. German automotive OEMs are responding by pre-qualifying suppliers with completed SCIP database registrations.
Long-term offtake contracting is replacing spot market purchasing for cathode-grade material. Tier-one battery cell manufacturers are locking five-year supply agreements with fixed volume tiers and indexed pricing adjustments. This behavioral shift is most pronounced in Japanese procurement offices, where keiretsu relationship norms favor supply security over price optimization.
Acetylene Black Market Segmentation
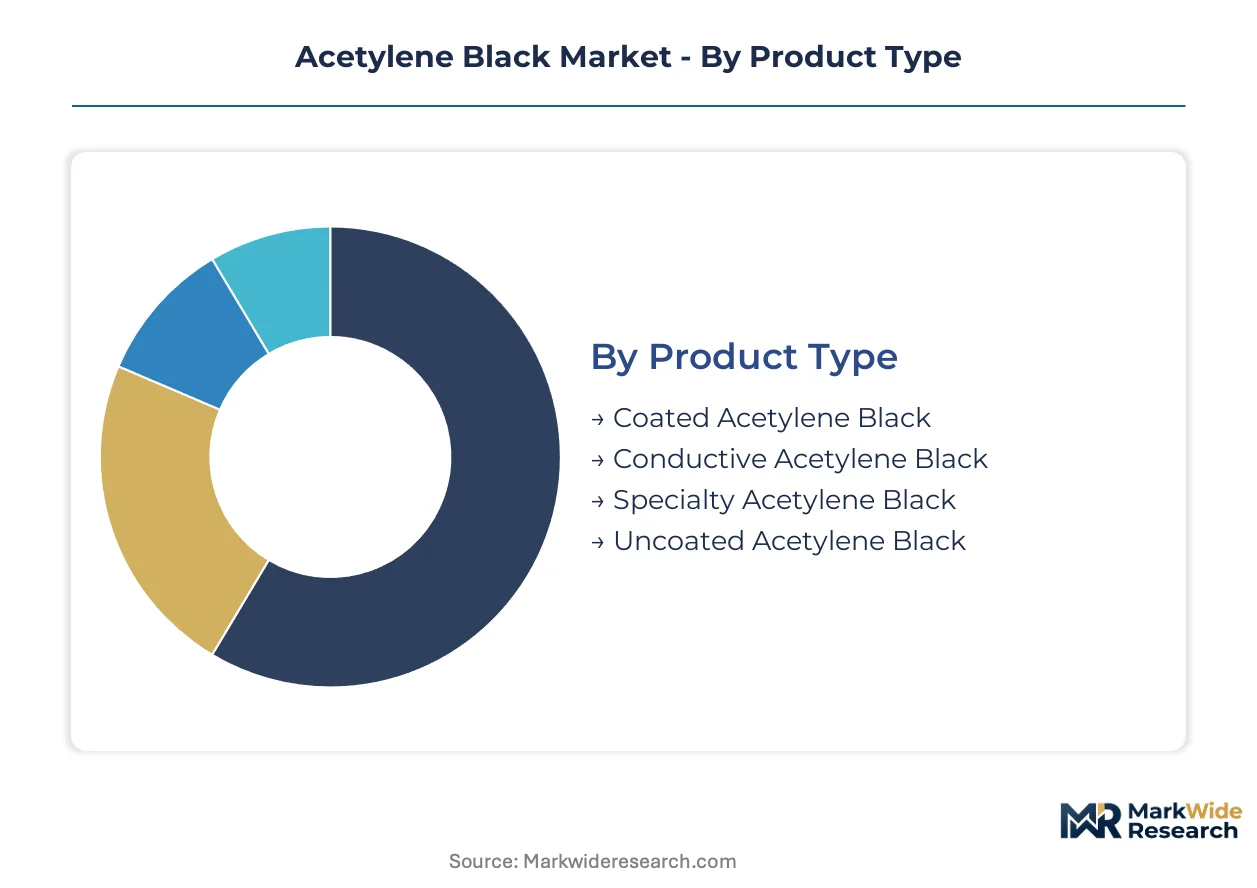
Acetylene black procurement channels diverge sharply by purity grade and end-use criticality. Battery cathode manufacturers demand direct technical partnerships, while rubber compounders rely on established distribution networks for commodity conductive grades.
Product Type:
Channel-mix patterns separate commodity grades flowing through distributors from specialty grades requiring direct manufacturer engagement.
- Conductive Acetylene Black:Standard conductive additive with electrical conductivity exceeding 100 S/cm and particle size below 35 nanometers. Demand concentrates at lithium-ion battery cathode plants in South Korea's Ulsan corridor and China's Ningde manufacturing cluster, driven by GB/T 30835-2014 purity mandates disqualifying lower-grade alternatives.
- Specialty Acetylene Black:Ultra-low metal contamination grade with impurities below 10 ppm, produced via hydrometallurgical purification. Korean cathode manufacturers mandate this specification for 800-volt automotive platforms, compressing margins for producers lacking advanced purification capabilities.
- Coated Acetylene Black:Surface-modified variant for enhanced dispersion in polymer matrices.
- Uncoated Acetylene Black:Base conductive grade for cost-sensitive rubber applications.
By volume, Conductive Acetylene Black leads. By growth pace, Specialty Acetylene Black is climbing the fastest.
Application:
Cost-tier stratification separates premium cathode-grade material from commodity rubber and coatings consumption.
- Battery Manufacturing:Primary application as conductive additive in lithium-ion cathodes and silicon-blended anodes. Procurement concentrates among qualified suppliers with ISO 9001 certification serving South Korean and Japanese cell manufacturers, with five-year offtake contracts replacing spot purchasing.
- Rubber Production:High-performance conductive filler for antistatic and electromagnetic shielding compounds. Legacy furnace black integration challenges stall specification upgrades as compounders face formulation revalidation costs.
- Coatings:Conductive pigment for electrostatic discharge protection.
- Plastics:Additive for conductive polymer compounds in electronics housings.
Battery Manufacturing commands premium pricing tiers. Rubber Production maintains the broadest geographic footprint.
End User:
Customer-type differentiation separates automotive procurement offices with long-term contracting norms from electronics buyers with flexible sourcing.
- Automotive:Electric vehicle battery cell manufacturers driving cathode-grade demand. Japanese procurement offices favor keiretsu-style supply security through multi-year agreements, while European OEMs pre-qualify suppliers with completed SCIP database registrations under REACH requirements.
- Electronics:Consumer battery and semiconductor packaging applications requiring consistent conductivity performance.
- Consumer Goods:General industrial rubber and plastic applications.
- Aerospace:Ultra-high reliability specifications for avionics and satellite systems.
Automotive end users dominate value capture. Electronics represents the most fragmented procurement landscape.
Distribution Channel:
Supply concentration determines channel efficiency, with direct sales compressing logistics costs at high-volume cathode plants.
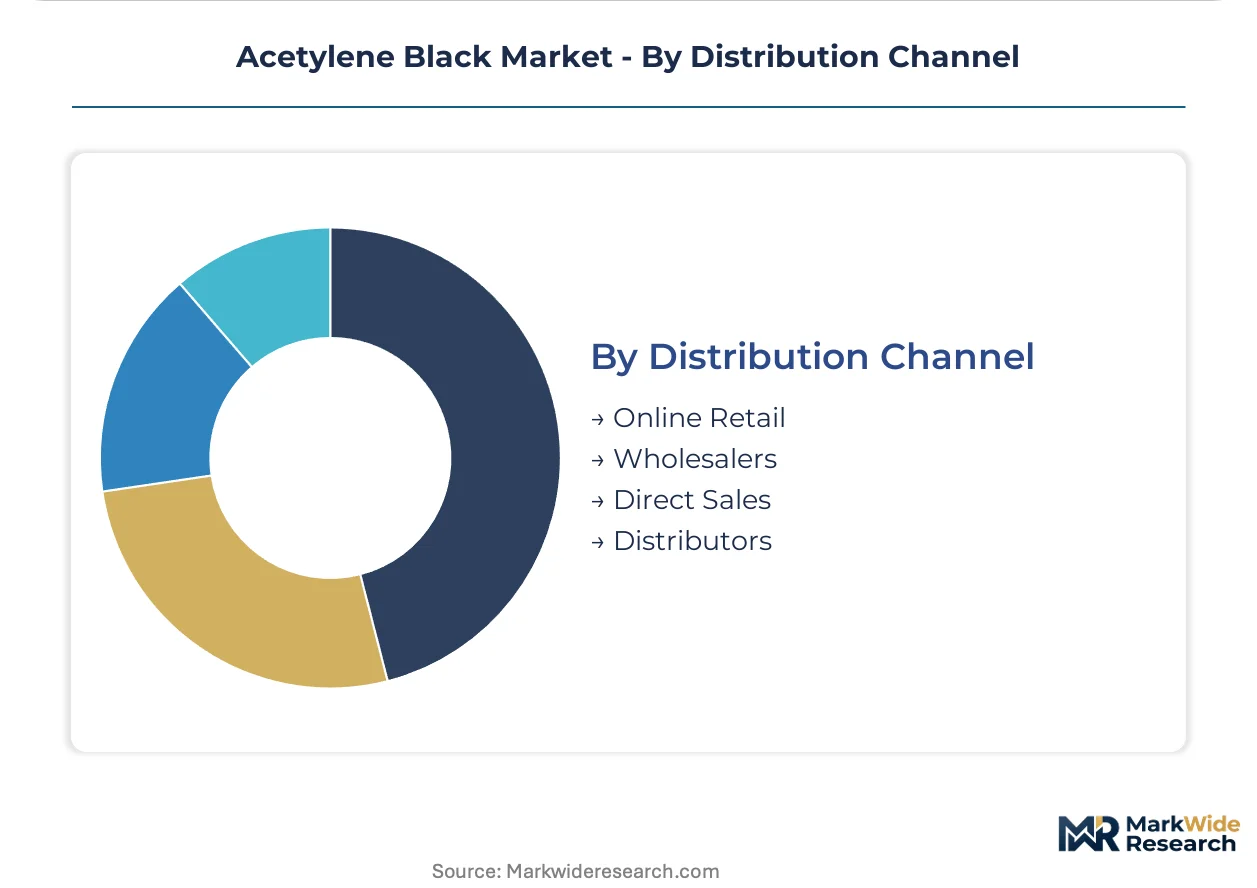
- Direct Sales:Dedicated bulk silo installations at battery cell facilities bypassing regional distributors. US Inflation Reduction Act domestic content credits are accelerating North American direct sales qualification windows as cell manufacturers reshore cathode production.
- Distributors:Regional intermediaries serving rubber compounders and smaller electronics manufacturers with lower volume requirements.
- Wholesalers:Bulk handlers for commodity-grade material in mature industrial markets.
- Online Retail:Small-quantity channel for R&D sampling and specialty formulations.
Direct Sales captures the steepest expansion trajectory. Distributors retain the deepest penetration in legacy industrial segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port anchors Asia-Pacific acetylene black logistics, handling calcium carbide feedstock imports and finished carbon black exports for battery supply chains. This maritime infrastructure underwrites China's dominance in conductive carbon manufacturing.
China
Calcium carbide production clusters in Inner Mongolia and Ningxia supply acetylene feedstock for thermal decomposition plants. GB/T 30835-2014 standards mandate cathode-grade purity thresholds that disqualify lower-tier producers. The Ningde manufacturing cluster in Fujian Province concentrates procurement volumes for CATL and BYD cell facilities.
South Korea
POSCO Chemical and LG Chem cathode plants drive specialty acetylene black demand for 800-volt automotive platforms. Korean Ministry of Trade, Industry and Energy (MOTIE) battery material localization programs incentivize domestic qualification of conductive additives. The Ulsan-Daesan industrial corridor hosts dedicated bulk silo installations bypassing regional distributors.
Japan
Keiretsu procurement norms favor multi-year offtake agreements with fixed volume tiers over spot market purchasing. METI's battery supply chain security initiatives accelerate domestic stockpiling of high-purity conductive carbons. The Kansai region around Osaka maintains legacy rubber compounder demand alongside emerging solid-state battery R&D programs.
United States
IRA domestic content credits reshore cathode production to capture tax incentives, creating qualification windows for North American acetylene black capacity. EPA particulate emissions standards raise capital requirements for new thermal cracking facilities. The Southeast manufacturing belt attracts cell facility investments from Korean and Japanese producers seeking tariff-advantaged supply.
Germany
ECHA REACH SVHC candidate list expansion forces importers to document nanoparticle-level impurity profiles, extending lead times for non-EU suppliers. German automotive OEMs pre-qualify suppliers with completed SCIP database registrations. The North Rhine-Westphalia chemical corridor integrates carbon black processing with cathode precursor manufacturing.
Acetylene Black Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers, with ISO 9001:2015 qualification bifurcating the vendor base into approved suppliers and marginal participants. The market structure concentrates around integrated carbon black producers with captive acetylene decomposition capacity and independent specialists focused on battery-grade purification. Three archetypes dominate: diversified chemical conglomerates with backward integration into feedstock production, pure-play conductive carbon specialists with hydrometallurgical capabilities, and regional calcium carbide producers with downstream thermal cracking assets. Competitive moves center on five-year offtake contracting with tier-one cell manufacturers and direct-to-plant bulk silo installations compressing logistics costs.
Within the integrated conglomerate tier, Birla Carbon and Mitsubishi Chemical Corporation occupy positions spanning multiple continents with carbon black operations feeding battery and rubber applications. Denka Company Limited exemplifies the premium specialist archetype through its Japanese manufacturing base. Orion Engineered Carbons S.A. represents the formulation-focused competitor developing specialized grades for cathode applications.
| Leading Market Players |
|---|
| Birla Carbon |
| Jinhua Chemical Co. Ltd. |
| Denka Company Limited |
| Phillips Carbon Black Limited |
| Mitsubishi Chemical Corporation |
| Orion Engineered Carbons S.A. |
| Hexing Chemical Industry Co. Ltd. |
| Tokai Carbon Co. Ltd. |
| Cabot Corporation |
| Others |
Value Network & Pricing Analysis
Five-year offtake contracting with fixed volume tiers and indexed pricing adjustments locks in supply access for battery cell manufacturers while compressing margin visibility for acetylene black producers facing feedstock volatility. This contract structure concentrates pricing power among qualified suppliers with ISO 9001 certification serving Korean and Japanese cathode plants, while marginal participants absorb spot market exposure.
Pricing Analysis
Certification level creates the primary spread between premium specialty grades and commodity conductive material. Three-tier pricing structure across premium, standard, and economy levels separates ultra-low metal contamination grades for 800-volt automotive platforms from standard conductive additives and uncoated rubber grades. Cost compression in mid-tier conductive material is intensifying as Super-P carbon black substitution gains traction in grid storage applications. Rubber compounders exhibit the highest price sensitivity due to formulation revalidation barriers, while automotive battery makers prioritize supply security over unit economics.
Supply Chain Analysis
Strategic stockpiling preferences dominate Japanese procurement offices under METI supply chain security initiatives, while Korean and Chinese buyers favor just-in-time bulk silo installations at cathode plants. Manufacturing concentrates in China, South Korea, and Japan, with calcium carbide feedstock drawn from Inner Mongolia and Ningxia provinces. Acetylene feedstock volatility and single-source thermal cracking reactor designs create structural vulnerability. Distribution runs through direct sales channels at high-volume battery facilities, bypassing regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through REACH SVHC documentation and GB/T 30835-2014 qualification creates durable barriers against unqualified entrants.
For Market Incumbents: Compound certification advantages by accelerating ISO 9001:2015 transition audits ahead of competitor recertification delays. Deepen hydrometallurgical purification capabilities to capture expanding specialty grade margins as Korean cathode manufacturers tighten 800-volt platform specifications. Capacity addition in North America secures IRA domestic content credit qualification windows before reshoring investments mature. For New Entrants and Emerging Players: Direct-to-cathode-plant distribution infrastructure represents the most penetrable service-layer gap where incumbents under-serve mid-tier cell manufacturers with flexible volume requirements. Target solid-state battery electrolyte interface applications where specialized conductive additive formulations remain undefined. Pursue joint development agreements with silicon-anode developers requiring elevated conductive ratios as the primary go-to-market angle. For Investors and Strategic Acquirers: Pure-play conductive carbon specialists with captive hydrometallurgical capabilities represent the most attractive acquisition target archetype for strategic buyers seeking battery material exposure. Long-term viability hinges on five-year offtake contract backlogs with tier-one cell manufacturers rather than spot market positioning. Watch for GB standards tightening purity thresholds as the inflection indicator forcing consolidation among marginal producers.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | North American thermal cracking facilities capture IRA domestic content credit qualification windows. |
| Backward Integration | Captive calcium carbide production insulates against electricity pricing volatility in Chinese provinces. |
| Long-term Supply Agreement | Five-year offtake contracts with Korean cathode plants lock in volume tiers amid GB/T 30835-2014 tightening. |
| Green Manufacturing Transition | EPA particulate emissions compliance raises capital barriers against unqualified new entrants. |
| Joint Venture | Solid-state battery R&D partnerships with sulfide electrolyte developers secure next-generation qualification. |
Research Methodology
Initial hypotheses were tested against primary input from cathode plant procurement managers, carbon black technical directors, calcium carbide facility operators, and battery cell supply chain strategists, then refined through secondary validation. Sources included customs trade data for acetylene black movements, SEC filings from listed carbon black producers, GB/T standard documentation from SAMR, and ECHA REACH registration databases. Bottom-up volume estimates from individual cathode production lines were triangulated against top-down market sizing from carbon black trade associations.
Variance decomposition across product grade, end-use application, geographic production hub, and certification tier informed the analytical framework over the projection horizon. CAGRs were derived from segment-level growth trajectories weighted by cathode capacity expansion schedules and silicon-anode blending adoption curves. Forecast inputs incorporated electricity pricing scenarios for Chinese calcium carbide production and EV battery cell manufacturing capacity announcements from Korean and Japanese OEMs.
Forecasts assume regulatory continuity in REACH SVHC candidate list expansion and GB/T 30835-2014 enforcement; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as acetylene feedstock volatility and super-P carbon black substitution thresholds evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Solar-Grade Polysilicon Market
Semiconductor Material
Graphene Oxide (GO) Market
Semiconductor Material
Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Cadmium Telluride Market
Semiconductor Material
Platter Substrate Materials Market
Semiconductor Material
Tungsten Market
Semiconductor Material
Europe Silicone Market
Semiconductor Material
Quartz Market
Semiconductor Material
Polysilicon for Solar Semiconductor Market
Semiconductor Material
Electronic Thermal Management Materials Market
Semiconductor Material
Yttrium Market
Semiconductor Material
Asia-Pacific Semiconductor Materials Market
Semiconductor Material
Electronic Film Market
Semiconductor Material
Asia Pacific Polyvinylidene Fluoride (PVDF) Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Niobium Hydride Market