
 Global Scintillator Market | 2026-2036
Global Scintillator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Scintillator Market Foresight
Japan is narrowing its historical dependence on imported rare-earth feedstocks through domestic recycling partnerships and strategic stockpiling. Hamamatsu Photonics K.K. leverages vertical integration across crystal growth, photodetector pairing, and module assembly to command premium positioning in medical imaging chains. Saint-Gobain S.A. anchors North American supply security through its ceramic scintillator foundry network, while Kromek Group plc specializes in cadmium-zinc-telluride alternatives for portable nuclear security devices.
A scintillator is a material that luminesces when struck by ionizing radiation, with inorganic crystals such as sodium iodide doped with thallium achieving light yields exceeding 38,000 photons per MeV and decay constants near 230 nanoseconds, enabling precise energy resolution in gamma spectroscopy and medical tomography. Organic plastic scintillators dominate high-energy physics installations at CERN and Fermilab due to cost scalability across multi-tonne detector volumes, whereas ceramic scintillators capture expanding margin pools in CT scanner arrays where radiation hardness and mechanical stability override raw light output. Silicon photomultiplier readouts are displacing legacy photomultiplier tubes in magnetic-field environments, reshaping technology selection across the installed base.
The U.S. FDA's 21 CFR Part 1020 performance standards for diagnostic x-ray systems directly shape scintillator material specifications for CT compliance, while the EU MDR tightens traceability requirements on radiation-emitting medical devices entering European clinical settings. Japan's METI enforces JIS standards on scintillator purity grades for domestic nuclear safeguards instrumentation. Stakeholders must weigh silicon photomultiplier transition timelines against remaining photomultiplier tube service revenues when allocating R&D budgets across detector platforms.
Market Dynamics
Silicon photomultiplier readouts are compressing technology selection cycles across the installed base, forcing simultaneous decisions on crystal chemistry, photodetector pairing, and module architecture that previously unfolded sequentially.
Growth Catalysts
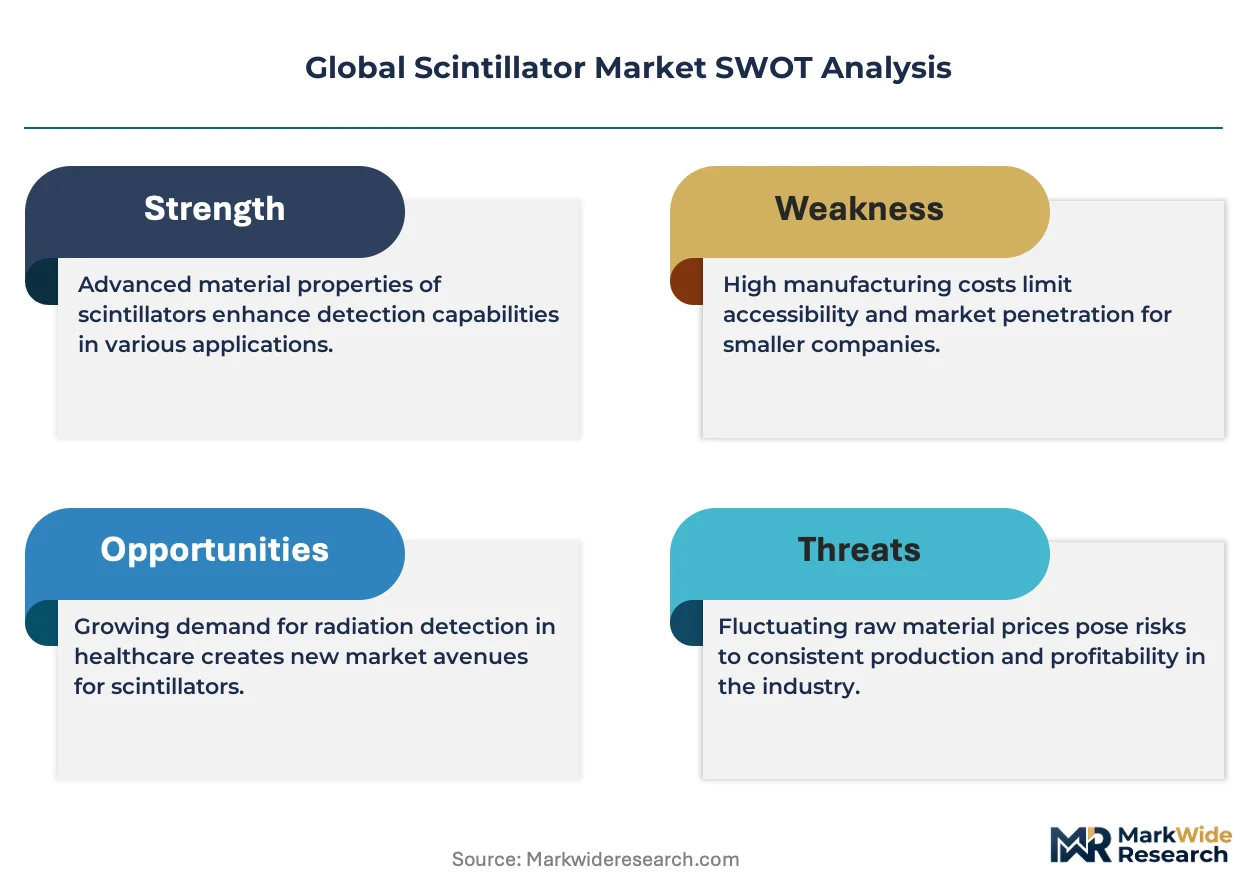
- FDA dose optimization mandates:The U.S. FDA's renewed emphasis on radiation dose reduction in diagnostic equipment accelerates material upgrades toward higher light-yield crystals in PET-CT and SPECT installations.
- Japan's photodetector cluster:Dense concentration of photodetector-integrated scintillator production around Hamamatsu creates spillover demand for precision-grown crystals serving medical imaging chains.
- CERN-scale physics installations:Multi-tonne detector volumes at high-energy physics facilities sustain organic plastic scintillator demand through cost scalability across unprecedented scale.
Market Restraints
- Rare-earth feedstock volatility:Dependence on imported cerium and lutetium concentrates exposes crystal growers to supply interruptions and price swings beyond hedging capacity.
- Photomultiplier tube service lock-in:Legacy PMT infrastructure in existing nuclear medicine departments delays silicon photomultiplier transitions despite magnetic-field compatibility advantages.
- Cadmium-zinc-telluride substitution:Direct-conversion semiconductor alternatives capture portable nuclear security applications where room-temperature operation outweighs scintillator light-output advantages.
Strategic Opportunities
- Domestic recycling partnerships:Japan's strategic stockpiling and rare-earth recovery from end-of-life medical equipment reduces import dependence while securing feedstock for high-purity crystal growth.
- EU MDR traceability requirements:Tightened documentation mandates on radiation-emitting medical devices create premium positioning for suppliers with certified supply-chain visibility.
- SiPM-CT convergence:Silicon photomultiplier integration with CT scanner arrays opens magnetic-field-compatible detector architectures previously inaccessible to PMT-based systems.
Industry Challenges
- Crystal growth technician scarcity:Mastery of Bridgman and Czochralski methods for large-diameter sodium iodide and lutetium oxyorthosilicate requires years of apprenticeship that outpaces training pipeline output.
- Dual certification timelines:Simultaneous pursuit of FDA 21 CFR Part 1020 compliance and EU MDR conformity assessment stretches regulatory affairs bandwidth across divergent documentation standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Scintillator Market |
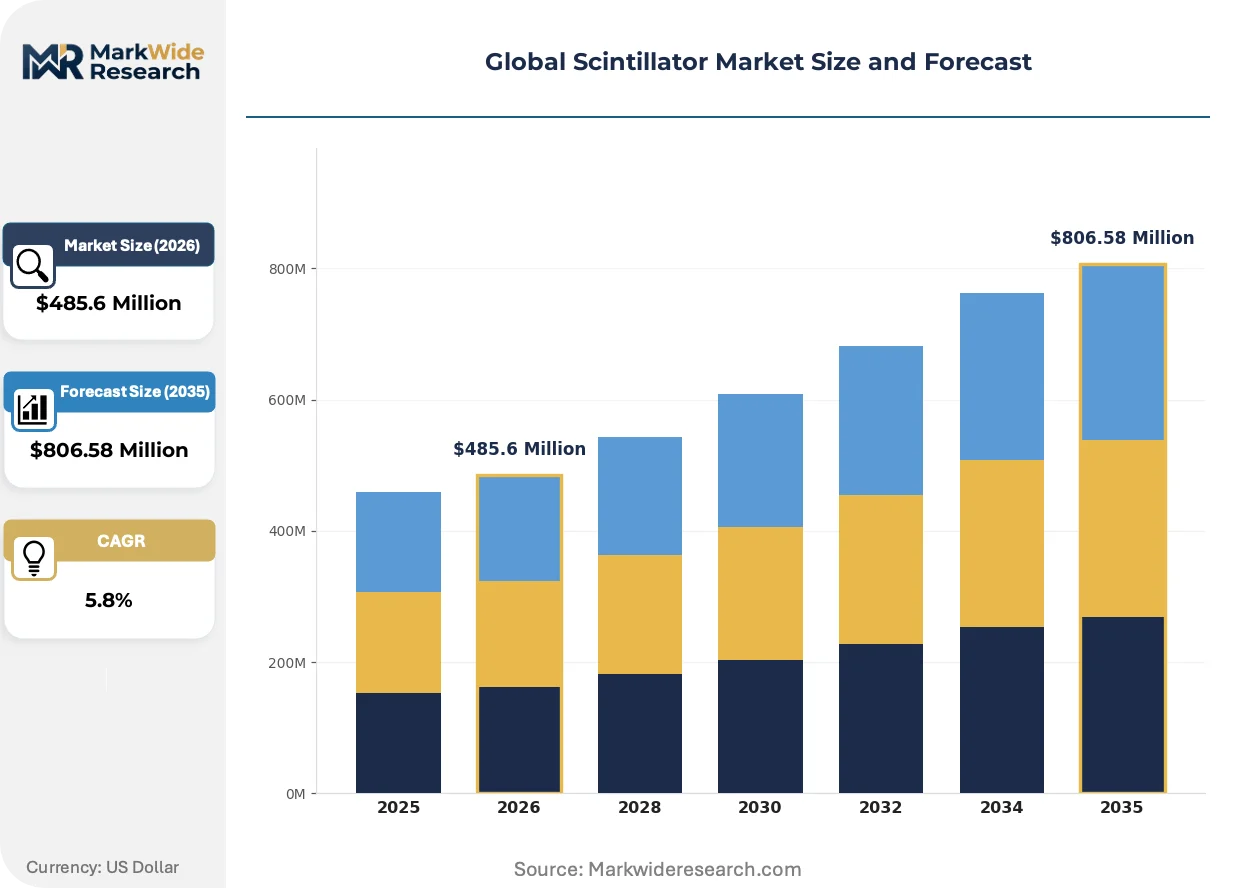
| Market Size in 2026 | $485.6 Million |
| Market Size in 2035 | $806.58 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inorganic Crystals, Organic Plastic, Liquid Scintillators, Scintillating Fibers, Ceramic Scintillators Application: Medical Imaging, Nuclear Security, Industrial Radiography, Oil Exploration, High Energy Physics End User: Hospitals, Nuclear Laboratories, Oil & Gas Companies, Research Institutes, Security Agencies Technology: Photomultiplier Tubes, Silicon Photomultipliers, Avalanche Photodiodes, Charge-Coupled Devices, Complementary Metal-Oxide Semiconductor Sensors |
| Companies Covered | Hamamatsu Photonics K.K., Saint-Gobain S.A., Mirion Technologies Inc., Proterial, Ltd., Radiation Monitoring Devices Inc., Ludlum Measurements Inc., Kromek Group plc, Rexon Components, Inc., Scintacor Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Scintillator Market Shifts & Advancements
Detector readout electronics are digitizing at the pixel level, collapsing the traditional separation between scintillation crystal and signal processing into unified digital detector modules.
Silicon photomultiplier arrays with single-photon resolution are digitizing gamma-ray detection in magnetic-field environments where photomultiplier tubes fail. Cardiac PET installations in hybrid MRI-PET suites adopt SiPM-based detectors at accelerating pace. This digitization is compressing the addressable market for legacy PMT refurbishment services while expanding specification scope for radiation-hardened ASIC design.
The EU Medical Device Regulation tightens post-market surveillance and traceability requirements on scintillator-equipped imaging systems entering European clinical settings. Manufacturers must now maintain device history records spanning crystal growth batch through final module assembly. High-end CT scanner arrays face the steepest compliance burden, driving consolidation toward vertically integrated suppliers with captive crystal foundries.
Hospital procurement departments are consolidating scintillator sourcing through long-term crystal supply agreements tied to detector module refresh cycles. Group purchasing organizations in the United States negotiate multi-year sodium iodide and ceramic scintillator contracts that displace spot-market purchasing. This concentration is most visible in integrated delivery networks replacing independent imaging center procurement autonomy with centralized supply chain governance.
Global Scintillator Market Segmentation
Scintillator procurement patterns diverge sharply across detector physics, regulatory environments, and integration complexity. Crystal chemistry and readout electronics selections cascade through certification requirements, maintenance protocols, and total cost of ownership calculations that reshape vendor relationships across the forecast window.
Product Type:
Each material class serves distinct radiation detection regimes where light yield, decay time, and mechanical durability trade off against unit economics and manufacturing scalability.
- Inorganic Crystals:Sodium iodide doped with thallium and lutetium oxyorthosilicate achieve light yields exceeding 38,000 photons per MeV with decay constants near 230 nanoseconds. PET-CT installations in the United States and Japan concentrate procurement of these materials as FDA dose optimization mandates accelerate detector upgrades.
- Organic Plastic:Polyvinyltoluene-based formulations dominate CERN and Fermilab installations where cost scalability across multi-tonne detector volumes overrides energy resolution requirements. Radiation hardness limitations constrain penetration into medical imaging chains despite favorable pricing.
- Liquid Scintillators:Organic fluor dissolved in aromatic solvents enables large-volume neutrino detection at SNOLAB and Jinping facilities.
- Scintillating Fibers:Polystyrene cores with fluorescent dopants track particle trajectories in calorimeter assemblies.
- Ceramic Scintillators:Rare-earth garnet structures serve CT scanner arrays where mechanical stability and radiation hardness command premium positioning.
The dominant share belongs to inorganic crystals, while ceramic scintillators are closing the gap fastest.
Application:
End-use concentration varies with regulatory stringency, capital intensity, and replacement cycle timing across clinical, security, and research domains.
- Medical Imaging:PET-CT and SPECT modalities absorb the majority of high-purity crystal output. Hybrid MRI-PET suites in German university hospitals and Japanese diagnostic centers drive silicon photomultiplier integration at accelerating pace.
- Nuclear Security:Portal monitors and handheld identifiers at U.S. Customs and Border Protection installations sustain demand for ruggedized sodium iodide assemblies. Cadmium-zinc-telluride alternatives capture portable applications where room-temperature operation outweighs scintillator light-output advantages.
- Industrial Radiography:Pipeline inspection and weld verification deploy plastic scintillator arrays for cost-sensitive field deployment.
- Oil Exploration:Downhole logging tools measure formation density through cerium-doped lanthanum bromide crystals.
- High Energy Physics:Multi-tonne plastic installations at CERN sustain dedicated foundry capacity.
Medical imaging commands the largest revenue pool, though nuclear security applications are expanding most quickly.
End User:
Procurement governance structures diverge between centralized health systems, fragmented research consortia, and security agencies with classified specifications.
- Hospitals:Integrated delivery networks in the United States negotiate multi-year crystal supply agreements that displace spot-market purchasing. Group purchasing organizations consolidate sodium iodide and ceramic scintillator sourcing through detector module refresh cycles.
- Nuclear Laboratories:Brookhaven National Laboratory and RIKEN operate dedicated crystal characterization facilities that bypass commercial vendor qualification.
- Oil & Gas Companies:Schlumberger and Halliburton maintain captive scintillator inventories for logging-while-drilling tool maintenance.
- Research Institutes:CERN procurement frameworks standardize plastic scintillator specifications across member-state contributions.
- Security Agencies:U.S. Department of Homeland Security and Japan's Nuclear Regulation Authority operate classified supply chains with domestic content requirements.
Hospitals account for the dominant procurement volume, while security agencies are gaining share fastest.
Technology:
Readout electronics selection cascades through magnetic field compatibility, pixel density requirements, and legacy infrastructure replacement economics.
- Photomultiplier Tubes:Legacy infrastructure in existing nuclear medicine departments delays replacement despite silicon photomultiplier advantages. Hamamatsu Photonics and Photonis maintain refurbishment service revenues across installed base.
- Silicon Photomultipliers:Single-photon resolution in magnetic-field environments enables hybrid MRI-PET detector architectures previously inaccessible. Cardiac PET installations at Massachusetts General Hospital and University of Tokyo Hospital adopt SiPM arrays at accelerating pace.
- Avalanche Photodiodes:Lower gain variants serve cost-constrained PET modules where magnetic field immunity is not required.
- Charge-Coupled Devices:Scintillator-coupled CCDs persist in X-ray diffraction systems at structural biology facilities.
- Complementary Metal-Oxide Semiconductor Sensors:Direct deposition integration enables pixel-level digitization in next-generation CT flat panels.
Photomultiplier tubes retain the dominant installed base, while silicon photomultipliers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystal growth capacity clusters in three national manufacturing corridors where photodetector integration, regulatory certification, and end-use demand converge. Japan, the United States, and Germany anchor supply-side concentration through distinct specialization patterns.
United States
FDA dose optimization mandates under 21 CFR Part 1020 accelerate PET-CT detector upgrades across hospital networks. The Department of Homeland Security sustains classified procurement for portal monitors and handheld identifiers at border installations. Massachusetts General Hospital and University of Texas MD Anderson anchor cardiac PET adoption clusters driving silicon photomultiplier integration.
Japan
METI enforces JIS purity standards on nuclear safeguards instrumentation while Hamamatsu Photonics anchors photodetector-integrated production. Domestic recycling partnerships with end-of-life medical equipment reduce rare-earth import dependence. The Shizuoka-Hamamatsu corridor concentrates crystal characterization facilities serving hybrid MRI-PET suites at University of Tokyo Hospital.
Germany
EU MDR traceability requirements tighten post-market surveillance on scintillator-equipped imaging systems entering clinical settings. German university hospitals in Munich and Heidelberg drive hybrid MRI-PET detector architecture adoption. Bavaria-based characterization facilities bypass commercial vendor qualification for CERN-scale physics procurement frameworks.
China
NMPA medical device registration reforms accelerate domestic CT scanner array certification timelines. State-backed rare-earth processing consolidation secures cerium and lutetium concentrate supply for crystal growth operations. Yangtze River Delta manufacturing clusters scale ceramic scintillator output for export-oriented medical imaging chains.
United Kingdom
UK Research and Innovation funding sustains neutrino detection installations at SNOLAB-scale facilities requiring liquid scintillator volumes. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit device standards with EU MDR documentation requirements. Oxford-Cambridge research corridor procurement frameworks standardize specifications across member-state physics contributions.
Global Scintillator Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in crystal growth and photodetector pairing. The vendor base stratifies across three tiers: vertically integrated medical imaging chains, captive foundry operations serving security agencies, and independent crystal houses supplying research consortia. Two strategic archetypes dominate: photodetector-integrated module assemblers and rare-earth supply-secured crystal growers. Competitive moves concentrate on backward integration into feedstock recovery and detector module refresh cycle contracting.
Within the photodetector-integrated tier, Hamamatsu Photonics K.K. exemplifies vertical control across crystal growth, photodetector pairing, and module assembly. Saint-Gobain S.A. occupies a position among ceramic scintillator foundry operators anchoring North American supply security. Kromek Group plc represents the cadmium-zinc-telluride alternative specialists capturing portable nuclear security applications.
| Leading Market Players |
|---|
| Hamamatsu Photonics K.K. |
| Saint-Gobain S.A. |
| Mirion Technologies Inc. |
| Proterial, Ltd. |
| Radiation Monitoring Devices Inc. |
| Ludlum Measurements Inc. |
| Kromek Group plc |
| Rexon Components, Inc. |
| Scintacor Ltd. |
| Others |
Supply & Pricing Matrix
The Shanghai-Hamburg rail corridor's freight cost volatility cascades through scintillator crystal pricing, amplifying margin compression for European detector module assemblers while Japanese producers leverage domestic photodetector integration to maintain premium positioning against spot-market buyers.
Pricing Analysis
FDA 21 CFR Part 1020 dictates the pricing tier structure across medical imaging chains, separating FDA-validated crystal batches from unvalidated commercial grades. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with premium tiers bundling silicon photomultiplier compatibility testing. Cost compression in standard-grade sodium iodide intensifies because Chinese ceramic scintillator exports capture mid-tier CT scanner contracts. Hospital procurement through group purchasing organizations demonstrates lowest price sensitivity, while independent imaging centers negotiate aggressively on spot crystal purchases.
Supply Chain Analysis
Rare-earth concentrate supply draws from Chinese separation facilities, Australian mining operations, and Japanese recycling partnerships. Cerium and lutetium feedstocks rest on single-source vulnerability at the concentrate refining stage, with spot price swings transmitted directly to crystal growth foundries. Distribution runs through vertically integrated photodetector assemblers in Japan, captive security agency channels in the United States, and research consortium procurement frameworks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment around FDA and EU MDR certification timelines constructs formidable defensive moats, as switching costs for hospital imaging chains extend 7-10 years across detector module refresh cycles.
For Market Incumbents: Entrench through backward integration into rare-earth recycling partnerships and captive silicon photomultiplier foundry capacity. Cadmium-zinc-telluride substitution in portable nuclear security applications threatens sodium iodide volume; counter by locking hospital networks into multi-year crystal supply agreements tied to detector refresh cycles.
For New Entrants and Emerging Players: Pursue ceramic scintillator white space in mid-tier CT scanner arrays where Saint-Gobain's North American dominance leaves price-sensitive openings. Hybrid MRI-PET suites in German university hospitals represent the most penetrable segment; enter through SiPM-integrated module partnerships with regional imaging equipment distributors.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate materials divisions holding non-core scintillator crystal assets with captive rare-earth supply contracts. Five-to-ten-year viability hinges on photodetector integration capabilities; monitor silicon photomultiplier adoption inflection at cardiac PET installations as the decisive signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Recycling | Japan's METI-backed partnerships reduce import dependence while securing feedstock for high-purity crystal growth. |
| SiPM-Compatible Detector Module Launch | Massachusetts General Hospital and University of Tokyo Hospital cardiac PET suites accelerate magnetic-field-compatible adoption. |
| EU MDR Certification Pathway Investment | German university hospitals demand device history records spanning crystal growth batch through final assembly. |
| Long-Term Crystal Supply Agreement | U.S. integrated delivery networks displace spot-market purchasing through GPO-negotiated multi-year sodium iodide contracts. |
| Joint Venture with Photodetector Specialist | Hamamatsu Photonics' vertical integration model demonstrates premium positioning through crystal-to-module control. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across crystal growth technicians, hospital biomedical engineers, GPO contracts managers, and nuclear security procurement officers. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, NMPA registration records, and customs trade data on rare-earth concentrate flows. Bottom-up crystal production estimates triangulated against top-down medical imaging equipment shipment data.
Calibration against historical CAGRs from adjacent radiation detection markets anchored growth rate bounds across the projection horizon. Segmentation modeling captured product type, application, end user, and readout technology dimensions, with silicon photomultiplier transition timelines and rare-earth price elasticity as critical forecast inputs. Growth trajectories derived from equipment replacement cycle analysis and regulatory compliance deadline clustering.
Sensitivities concentrate around rare-earth export restriction timing and silicon photomultiplier cost curve inflection points. Cross-checking against CERN procurement framework specifications and hospital capital expenditure surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Material
Dysprosium Titanate Market
Semiconductor Material
Thermoelectric Materials Market
Semiconductor Material
Semiconductor Film Market
Semiconductor Material
Zinc Oxide Market
Semiconductor Material
Semiconductor Silicon Wafer Market
Semiconductor Material
Tellurium Market
Semiconductor Material
Battery Silver Paste Market
Semiconductor Material
Global Silicon Alloys Market
Semiconductor Material
Big Size Synthetic Diamond Market
Semiconductor Material
Global Semiconductor Epoxy Mold Compound Market
Semiconductor Material
Germanium Market
Semiconductor Material
Silicon Tetrachloride Market
Semiconductor Material
Niobium Hydride Market
Semiconductor Material
Quartz Market
Semiconductor Material
Polysilicon Market
Semiconductor Material
Silicon Nitride Market